





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 24, 2026 | NCFA Market Activity | Payments And Money Movement, Capital Markets And Market Infrastructure, SME Finance And Business Banking
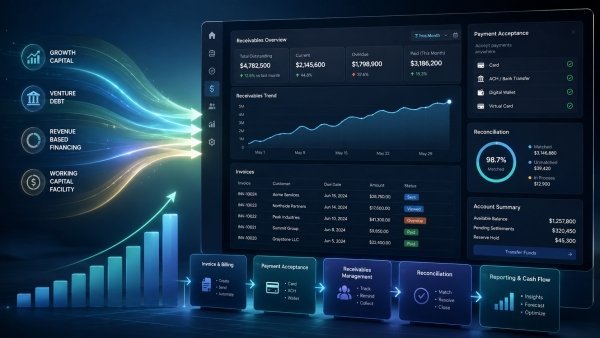
On August 24, 2026, Toronto based Flow Capital announced a US$6 million investment in Aliaswire (see quarterly filing), a Burlington, Massachusetts payments technology company serving vertical SaaS platforms, financial institutions and enterprises. The investment was made August 17 and will provide working capital for growth while refinancing existing debt.
Aliaswire provides billing, receivables and payments technology through DirectBiller for enterprises and financial institutions and DirectEmbed for vertical SaaS platforms. The company says its technology serves more than 7,000 customers and has processed more than one billion transactions and US$100 billion in payment volume.
Its embedded receivables platform lets software companies add billing, invoicing, payment acceptance, account management and reconciliation inside their own products without building the full payments operation themselves.
The financing terms have not been disclosed. Flow's core business is growth venture debt, but the public documents do not identify the Aliaswire instrument, pricing, maturity, security or any equity component. The US$6 million should therefore be treated as an investment unless further terms are released.
Aliaswire is large enough to have more financing choices than an early startup. Equity brings capital without scheduled principal repayments but gives up ownership. Bank debt can be cheaper when a company qualifies. Venture debt can extend runway with less dilution, while other private credit can offer more flexible terms when a financing need falls outside normal bank lending.
Venture debt is one form of private credit. Flow focuses on revenue generating growth companies and typically provides senior secured financing, sometimes with a small warrant component.
This deal sends Canadian growth capital into a U.S. fintech. Canadian institutions already hold roughly C$500 billion in private credit exposure, much of it outside Canada, while non-bank loans account for only about 15% of external funding for Canadian non-financial businesses. Foreign investment is not the problem. The question is whether Canadian fintechs at the same stage can access comparable growth capital at home?
Capital Choice
| Financing | Where It Can Fit | Founder Advantage | Main Tradeoff |
|---|---|---|---|
| Bank debt | Established cash flow, credit history or collateral | Often lower cost when available | High growth companies may not qualify |
| Venture debt | Growth company with traction and a defined next milestone | Can extend runway with limited ownership dilution | Interest and repayment obligations, often with warrants |
| Private credit | Financing needs that do not fit normal bank lending | Terms can be tailored to the company and use of capital | Can cost more and give lenders stronger protections |
| Equity | High growth where cash needs to remain inside the business | No scheduled principal repayment | Founders and existing investors give up ownership |
How Companies Have Used Flow Capital Financing
Flow's portfolio shows how growth debt can serve different jobs. Toronto retirement fintech Common Wealth used a C$15 million senior secured note before raising a C$12 million Series A in March 2026. The debt helped fund product development, customer growth and operating scale before the equity round.
Vancouver based JUDI.AI used several Flow tranches to finance U.S. expansion, including senior sales hiring and new American credit union customers. UK insurtech Wrisk used a C$4.25 million senior secured note to fund growth toward profitability. Revenue rose 142% in the following year, its UK operation later became profitable and the company subsequently raised a £12 million Series B.
UK marketplace lending platform CrowdProperty received a C$5.25 million senior note for marketplace lending growth and technology improvements. Aliaswire adds another use case by combining new working capital with refinancing.
Debt isn't replacing equity in these examples. Common Wealth used it before an equity raise, JUDI.AI used it to enter a new market, Wrisk used it to reach profitability and CrowdProperty used it to expand an established platform. The financing changed with what each company needed to accomplish next.
Aliaswire is raising capital as payments become a bigger part of the vertical SaaS business model. Stripe reported that median payments adoption across its software platforms rose from 27% in 2024 to 40% in 2025, while leading platforms reached 80% or more. Its vertical SaaS payments data also found 11% lower annual churn among platforms offering embedded financial products and 49% faster revenue growth among platforms offering several financial products compared with software only peers.
J.P. Morgan's work on embedded payments points to transaction revenue, stronger customer relationships and proprietary payments data. As AI makes software features easier to reproduce, owning more of the financial workflow can make a platform harder to replace.
Aliaswire is targeting that opportunity through embedded receivables rather than payment acceptance alone. DirectEmbed combines payments with billing, invoicing, self service, account management and payment operations. Aliaswire is also adding AI for receivables automation, including cash flow prediction, DSO optimization, risk analysis and agentic payment workflows.
Aliaswire's embedded receivables model also connects with the Financial Innovation Map, where payments, receivables, SME finance and embedded software are tracked as connected opportunity areas.
If more vertical SaaS companies bring billing, receivables and payments inside their products, Aliaswire can grow with a market it has served for more than two decades while DirectEmbed gives it a newer route into software platforms. Its existing payment volume, customer base and financial institution relationships give it experience that newer embedded finance providers still need to build.
The opportunity is also attracting much larger payment companies and newer infrastructure providers. AI can make software features easier to copy, while deeper control over billing and payments increases fraud, compliance and reliability demands. Aliaswire has to do more than make payments easy to add. It needs to help software companies get customers using them, earn more from them and manage receivables better than competing platforms can.
Aliaswire has already processed more than US$100 billion in payments. Can US$6 million of flexible capital help it turn embedded receivables and AI into a bigger position inside vertical SaaS while larger payment platforms compete for the same customers?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply