





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


On August 21, 2026, Canada's founder drain returned to the national debate with a harder number attached to it. The Dominion List, a curated catalogue rather than a census, now tracks 517 U.S.-based companies with a Canadian-linked founder. Together they have raised roughly US$414 billion. About 88% of the founder links include education at a Canadian university, and 56% of the companies are headquartered in San Francisco.
The pace in the list also accelerated during the AI boom. Jesse Rodgers' Barn Ventures analysis counts 60 newly founded U.S. companies with Canadian-linked founders in 2023, 93 in 2024 and 87 in 2025, compared with roughly 20 to 30 a year from 2016 through 2022. The dataset is curated and recent companies may be easier to capture, so it should not be treated as a population estimate. The direction is still difficult to ignore.
Canada clearly produces ambitious builders. The strategic question is whether enough of them can find the capital, customers, infrastructure, investors and operating density needed to build more of the resulting value here. That makes founder retention part of a wider participation problem, not a standalone brain-drain story.
Canadian universities are producing founders at global scale
The Dominion List links 88% of its founder records to Canadian universities. Waterloo alone accounts for 216 founders across 180 U.S.-based companies in the current dataset, while Toronto, McGill, UBC and Queen's are also major feeders.
The value capture concentrates somewhere else
The 517 companies in the list have raised about US$414 billion. Fifty-six are valued at US$1 billion or more, 19 are public and 59 have been acquired. San Francisco alone hosts 287 of them.
Canada's problem is not producing ambitious people. It is converting more of that talent into companies, jobs, ownership and follow-on investment that compound inside the Canadian economy.
U.S. founder programs start earlier and remove more friction
Barn Ventures maps programs that reach students before graduation, then layer in early capital, founder communities, recruiting, immigration support and dense investor networks. The argument is that the U.S. offer is a system rather than one accelerator or one cheque.
Canada's response cannot be one more accelerator
Keeping more founders does not mean preventing mobility or copying Silicon Valley. It means giving more builders credible reasons to start, finance, hire and scale from Canada before the strongest networks and ownership structures form elsewhere.
Capital matters, but so do density, access, customers, infrastructure and the speed of getting from talent to a company with traction. Founder retention makes the wider participation thesis concrete because Canada can create the input and still lose much of the compounding.
The Forum looks across the financing lifecycle
NCFA's review of the SEC Small Business Forum shows why the process is useful for Canada. The 2026 Forum program again moved from early-stage financing to growth capital and smaller public markets.
The same frictions keep returning in new forms
Finders, investor eligibility, offering limits, fund structures, secondary liquidity and small-public-company economics remain active issues because one reform can solve one bottleneck while exposing another.
The transferable lesson is not a U.S. securities rule. It is the habit of bringing market participants back into the process and testing whether a framework is producing the market it was intended to create.
Canada already has detailed market evidence
CVCA tracks venture and private equity, while NACO tracks angel investing. Regulators and departments publish market studies, consultations and program data. Canada does not lack information about every part of the financing system.
Canada is also actively intervening
The federal government is preparing another C$1 billion venture and growth capital program. The Competition Bureau is studying SME financing. Payments, data access and retail private markets are also being redesigned.
Canada already has consultations, programs and market data. The harder test is whether each reform produces enough real participation to change who can compete, invest and scale.
Institutional venture capital is getting a larger engine
The Venture and Growth Capital Catalyst Initiative is designed to attract more private and institutional capital into Canadian venture funds, strengthen fund managers and support high-growth companies from pre-seed through growth.
SME financing is being tested against a broader business population
NCFA's SME financing competition review examines lender entry, expansion, switching friction and the market position of alternative finance providers. The Competition Bureau market study is the primary verification source.
Growth VCCI can deepen capital for companies that fit venture mandates. It does not automatically finance every viable manufacturer, service company or local employer whose growth profile, asset base or financing need sits outside institutional venture economics.
Financial data is moving toward regulated access
NCFA's Canada Open Banking Rules intelligence tracks accreditation, liability, data scope, security and technical standards as consumer-driven banking moves toward operation. Finance Canada's proposed regulations provide the primary policy source.
Core payment infrastructure is opening to a wider membership base
PSPs and more credit unions can join Payments Canada, while the Real-Time Rail rules and access are moving toward the planned Q4 2026 launch. Payments Canada remains the primary launch and system source. Wider eligibility gives PSPs and credit unions a clearer route into core payment infrastructure.
Formal access changes who is allowed to participate. Competition changes only when entrants can absorb compliance, technology, integration and operating costs and still build products customers want.
Fintechs can gain more control over the customer experience
More direct access to data, payments and settlement can reduce dependence on incumbent-controlled infrastructure and give challengers more control over pricing, product design and service delivery.
Smaller financial institutions can compete through shared capabilities
Credit unions and regional firms may not need to build every payments, AI, compliance, data or digital-asset capability internally if specialized providers can deliver those functions at workable scale.
The payoff is not a longer list of fintech entrants. It is more providers controlling enough of their infrastructure and economics to put sustained pressure on incumbents.
Managed access gives households professional selection
Ontario's long-term asset fund work could give retail investors diversified exposure to venture capital, private equity, private debt, infrastructure and other long-duration assets through professionally managed funds. The OSC LaunchPad notice verifies the project and its retail-access objective.
Direct access gives households the company decision
Equity crowdfunding lets an investor choose an individual company. It can connect businesses with customers, employees and supporters, but it also concentrates risk and usually offers little liquidity.
Managed access can broaden exposure to private-market returns. Direct access can broaden the number of people deciding which companies receive their money. Both can widen participation, but they create different markets.
Canada is building the managed channel for wider retail use
Managed structures can bring diversification, diligence, portfolio construction and product-level controls around valuation and liquidity. They can also preserve professional gatekeeping over where retail capital is deployed.
Canada's direct channel remains comparatively constrained
NI 45-110 allows a Canadian issuer to raise up to C$1.5 million in 12 months. Ordinary investors are generally limited to C$2,500 per offering, or C$10,000 when a registered dealer determines suitability.
If more company value is created while businesses remain private, wider retail access affects more than issuer financing. It influences which households can accept productive risk and participate earlier in private-market returns.
Canadian direct demand can reach the existing ceiling
Blossom, Edison Motors and Gander have used community capital alongside accredited, offering memorandum or other financing. Their raises show direct retail capital can complement professional capital rather than replace it.
International peers provide more room for direct participation
Australia permits eligible issuers to raise A$5 million in 12 months and caps retail investment at A$10,000 per company annually. U.S. Regulation Crowdfunding allows eligible issuers to raise up to US$5 million.
Canada's smaller market does not prove regulation caused weak activity. Issuer quality, investor demand, distribution, awareness, liquidity and platform execution also matter. It does show why market-opening rules should eventually be judged by whether enough issuers, investors and intermediaries can participate economically.
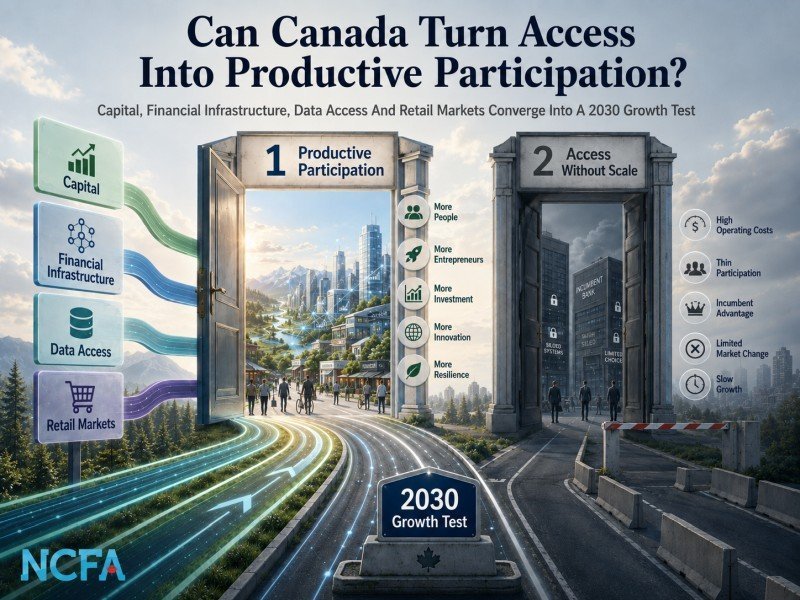
One future produces more viable participants
New payment participants build useful services. Open-banking firms turn permissioned data into products customers adopt. Smaller institutions buy modern capabilities instead of rebuilding them. More businesses find financing that fits their stage and economics.
The other future opens rules without changing market power very much
Accreditation, integration, compliance, distribution and technology remain expensive enough that the largest institutions and professional managers capture most new activity. Formal access widens while competitive intensity changes only at the margin.
The evidence will be practical. Entrants that survive. Products customers use. Capital reaching different kinds of companies. Investors using managed and direct routes. Smaller institutions offering capabilities once reserved for much larger competitors.
Better participation can improve the inputs to productivity
More financing choices, faster settlement, stronger data access and better financial tools can give businesses more capacity to invest, automate, hire, commercialize and serve customers.
Stronger companies can create the next round of participation
Businesses that build revenue, productivity and international reach create more investable opportunities. When more founders build and exit from Canada, employees, angel investors and repeat entrepreneurs can recycle capital, experience and networks into the next generation.
More viable participants can increase competition. Better competition can improve products, distribution and capital allocation. Better tools and financing can support more investment. Stronger companies can create more opportunities for households and institutions to participate again.
The U.S. process expects the friction to change
Market participants return because new rules, market conditions and business models keep changing the problem. A recommendation can be implemented and still leave a new bottleneck elsewhere.
Canada will need the same feedback discipline across more than capital
As payments, data, private markets and financing become more open, policymakers will need to know who entered, who could not, which businesses became sustainable and where access failed to generate enough economic activity.
Canada has spent years opening doors. The next phase is finding out which openings create viable markets. That means judging regulation and public programs by the participation, competition and productive activity they generate while preserving the protections that made wider access possible.
Participation is not a complete explanation for Canada's productivity problem. Management capability, commercialization, industrial structure, R&D, domestic demand, risk appetite and global scale all matter. The value of the thesis is that Canada is now opening enough capital, data, payments and investor channels at the same time to test whether participation becomes a measurable growth mechanism.
Talking Point
Canada already produces globally competitive talent and holds deep pools of capital, technology and institutional capacity. The opportunity between now and 2030 is to connect more of those assets before founders, ownership and future value compound somewhere else. If today's reforms create viable participation rather than permission alone, Canada could end the decade with more competitors, more investable companies and more ways for households and institutions to share in productive growth.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply