

Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


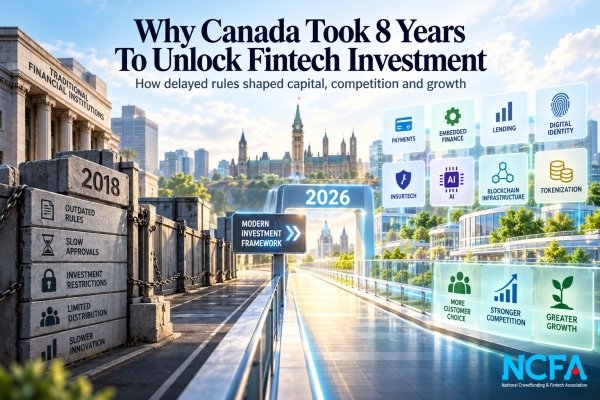
On October 17, 2026, Finance Canada published proposed fintech investment and technology regulations for powers Parliament approved in June 2018 and never brought into force. The package reaches more than 400 federally regulated financial institutions.
Finance now says the older rules can “prevent or complicate” fintech investment, limit capital flowing into innovative sectors and impede productivity growth. Eight years after Parliament acted, the operating rules are still only proposed.
The delay wasn’t one long consultation. Finance’s own record shows six concrete problems. Officials had to draw the regulatory perimeter between finance and technology, preserve the barrier against unrelated commerce, set revenue and regulatory capital limits, stop the rules from squeezing smaller institutions, and cut reporting requirements industry said were too heavy. Then Parliament had to repair defects in the 2018 statute in 2024. Six problems turned one reform into eight years of rulemaking.
This wasn’t a ban on fintech investment. Banks and insurers could still buy businesses that fit the existing rules. The trouble started when a fintech mixed finance with commercial software or expanded after an institution had invested. Banks had already warned that some domestic technology approvals took three to four months. The 2026 proposal would finally give qualifying mixed businesses a new route when at least 60% of their activity is financial, subject to separate limits on the investor.
Finance opened the review in 2016. It held 32 meetings and received 63 written submissions, then received 300 submissions in 2017, with 25 focused on fintech. Finance later acknowledged that incumbent institutions and industry associations were better represented than independent fintechs and venture investors.
Bankers came with a practical complaint. The Canadian Bankers Association’s 2017 submission said some domestic technology approvals could take three to four months and covered only the activities named in the application. That’s a poor fit for a fintech that can add a product, market or subsidiary in the time it takes a large institution to finish an approval process.
Founders weren’t building tidy regulatory categories. Payments were moving into merchant software, identity tools could serve banks and law offices, and data companies were becoming financial infrastructure while selling into other industries. The old rules drew cleaner lines than the market did.
Investors wanted a wider lane too. Finance said collaboration could pair fintech speed with the balance sheets and customer relationships of established institutions. Portag3 Ventures, then backing Canadian companies including Wealthsimple, Borrowell and KOHO, supported broader investment flexibility and argued that bank financing and collaboration were important to the fintech ecosystem. Capital and distribution were already part of the policy problem.
Under the Bank Act route described by the CBA, a substantial investment generally had to stay inside permitted activities. If even one ancillary activity or a downstream subsidiary moved outside that list, the bank could face another approval, a different investment classification or divestment. The CBA called the restriction a “significant impediment” with the potential to restrict Canadian innovation.
Insurers ran into the same boundary from another direction. The life insurance industry’s 2017 submission said an insurer could use identity or anti money laundering technology inside finance but couldn’t freely sell the same capability to law offices, real estate firms, other businesses or government. Useful technology could have a broader market, while the ownership and commercialization rules stayed narrow.
A growing fintech can create a problem for the shareholder that helped fund it. Add inventory software, merchant analytics or a commercial subsidiary because customers want them, and the business may no longer fit the permission that supported the original bank investment. The CBA warned that this could discourage fintechs from working with banks.
Insurers faced a similar commercial choice. A tool built for regulated finance might have customers far beyond finance, yet the legal route could narrow who could own the business or where the product could be sold. That can influence which investor a founder takes, how the company is structured and which markets it enters next.
Parliament responded on June 21, 2018. The 2018 Budget Implementation Act broadened permitted technology activities, removed prior ministerial approval for the expanded nonfinancial activities, widened referral powers and created a new investment category for companies whose businesses were mostly financial services. The law clearly moved toward more flexibility.
But Parliament didn’t define how much of a company had to be financial to qualify as a majority financial services entity. It also left the revenue, capital, reporting and transaction conditions to regulation. Without those operating rules, institutions couldn’t use the new powers and stayed under the older framework.
Parliament gave banks and insurers broader ownership powers in June 2018. Finance still had to define the majority test, exposure limits and safeguards before anyone could use them. The authority existed. The investment route didn’t.
That left financial institutions making real investment decisions under the old framework while fintech business models kept widening. A company could fit the rules when a bank first invested and create a new legal problem later simply by adding a commercial activity customers wanted.
After Royal Assent, Finance worked with the CBA, the Canadian Life and Health Insurance Association and OSFI. The first problem was the regulatory perimeter. Finance called separating new technology activities from core financial services a “serious technical challenge”, especially when the same staff, assets and systems served both. Officials also had to preserve existing investment prohibitions and keep visibility into the new business.
Then came the operating limits. In 2019, officials worked through revenue caps, regulatory capital exposure, annual reports and transaction conditions. A 2020 technical review exposed two more problems. Uniform rules could box out smaller institutions, while the proposed reporting package could impose a significant burden. Finance later revised both.
The delay didn’t come from one unresolved issue. It came from six. Finance had to separate finance from technology, preserve limits on unrelated commerce, set revenue and capital exposure caps, give smaller institutions enough room to compete, and reduce reporting requirements industry said were too burdensome. Those were the five regulatory design problems documented through the consultation record.
The sixth problem sat in the law itself. Bill C-59 received Royal Assent in June 2024 and made technical corrections to the 2018 law. It fixed discrepancies between the English and French provisions and clarified that the expanded technology powers were limited to information technology. By then, Finance had already consulted in 2019, reviewed a draft in 2020, consulted again in 2021 and returned with another draft in 2024.
Every revision created another round of legal or regulatory work. Caps changed. Reporting changed. Parliament repaired the statute six years after passage. The first public regulations still didn’t reach Canada Gazette Part I until October 2026, even though stakeholders were asking by 2024 for the powers to come into force “as soon as feasible.”
National Bank took control of Flinks in 2021. Its disclosed transaction included C$73 million for voting preferred shares followed by another C$30 million investment. The bank’s interest rose to 85.9%.
RBC bought WayPay in 2019 to expand automated business payments and account reconciliation. Canada Life acquired ClaimSecure in 2021, adding 1.25 million plan members and technology handling more than C$1.2 billion in annual claims payments. Canada Life and ClaimSecure later launched a combined benefits product.
Those deals matter because they rule out the easy story. Canada didn’t ban institutional fintech investment, and banks and insurers kept buying businesses that fit the existing framework. The squeeze showed up at the edges, where finance blended with commercial activity or a company later expanded beyond the legal fit that supported the original investment.
By October 2026, Flinks had moved beyond financial data connectivity into banking development, payment integrations, account switching and managed services. That’s exactly the kind of expansion a strategic shareholder may want to keep backing. Under the older framework, a different commercial move could force the shareholder to stop and ask whether it could legally stay invested.
The CBA warned that the legal fit could affect a deal before anyone applied for approval. If a fintech needed capital quickly, a bank bid carrying a regulatory condition could lose to cleaner, faster money. A later business change could also force the bank back into approval or divestment. A lost opportunity can disappear before Ottawa ever sees a file.
Finance expects more activity once the new route is usable. Over the past decade, roughly one institution per year sought the relevant ministerial approvals. Finance now assumes large banks will average two qualifying investments annually and large insurers one. The figures aren’t directly comparable, but Finance itself expects more activity because the process should be faster, less costly and more certain.
Government data can count approvals. It can’t count the bank bid that was never made, the expansion pushed into another company or the investor a founder never approached because the legal fit was poor. It can’t count technology an insurer decided not to sell outside finance either. Those decisions rarely leave a public record.
The economic toll starts before an approval file exists. A bank offer with conditions can lose to faster capital. A founder can split a product, delay a commercial move or avoid an investor whose ownership may become a future constraint. None of those choices needs a rejection letter to change the company’s path.
The October proposal finally puts a number on majority. A target can qualify when at least 60% of its business consists of qualifying financial activity, measured using whichever produces the highest result among revenue, operating expenses or assets. That gives younger or differently structured companies more than one way to clear the test.
The investor has separate limits. Institutions with more than C$12 billion in equity would face a 10% nonfinancial revenue ceiling and a 10% regulatory capital exposure limit. Small and medium institutions with C$12 billion or less in equity would get 15% revenue headroom while keeping the same 10% capital limit.
Take a payments company that also sells merchant software. Under the older activity based route, one impermissible commercial activity could knock the company out of that investment permission. Under the proposal, a business with 70% qualifying financial activity and 30% other commercial activity could potentially qualify. The 70 and 30 split is illustrative, but the business consequence is straightforward. The founder may no longer have to strip out every useful commercial feature just to keep a bank investor eligible.
The percentages don’t describe the same limit. The historical 5% exemption covered certain bank technology investments without approval and required the investee to stay within prescribed activities. The new 60% test applies to the target company’s business mix. The 10% and 15% limits apply to the investing institution’s aggregate nonfinancial business. There isn’t a simple old cap and new cap comparison.
More eligible bank and insurer investors can improve financing choices, distribution and negotiating leverage for an independent fintech. A strategic buyer can get a product in front of customers much faster. It can also end up owning technology several competing institutions rely on. More capital and more competition aren’t automatically the same outcome.
Finance is trying to keep sight of that risk. Certain large acquirers would have to report material supply arrangements between a target and the acquirer’s competitors. Smaller and medium institutions get more revenue headroom and no new reports, because identical limits would leave them with much less room to compete.
A wider buyer pool can help founders raise money, get distribution and negotiate exits. It can also put an important supplier or emerging challenger inside a major incumbent. That’s where the reform shifts from a capital question to a competition question.
The Competition Bureau’s fintech study supported removing unnecessary barriers to entry and collaboration while keeping scrutiny where incumbent relationships could weaken competition. Finance’s new supply reporting reflects the same concern. The useful outcome isn’t simply more acquisitions. It’s more capital reaching strong companies without draining independent competitive pressure from the market.
Finance estimates the proposed rules will add C$267,518 in annualized administrative and compliance costs, or about C$1.88 million in present value over 10 years. Those figures cover the new reporting burden. They don’t count the savings from removing some ministerial approvals, and they certainly don’t capture eight years of slower, narrower business choices under the old framework.
The regulations are proposed, not in force. Canada Gazette Part I opened a 30 day consultation on October 17, 2026, with comments due November 16. The government still has to finalize the regulations and use a separate Order in Council to activate the dormant 2018 amendments.
The last round now turns on execution. The 60% definition has to work for current fintech business models, smaller institutions need enough room to compete, and Finance needs visibility into new risks without rebuilding the reporting burden industry spent years pushing back on. Get those choices wrong and the reform can still underdeliver even after eight years.
Canada has already spent eight years designing conditions around powers Parliament approved in 2018. The next step is simpler to describe and harder to deliver. Put the rules into force, give good businesses a workable path to institutional capital, and keep enough independent competition in the market that customers actually benefit.
Canada’s eight year delay carried a real economic toll. Banks faced approval processes that could take three to four months. Mixed fintechs could lose access to some bank or insurer investors as they expanded. Insurers had less room to sell useful technology outside financial services. Finance now says the old framework can prevent or complicate investment, limit capital and impede productivity. We can’t put a credible dollar figure on every deal, product or expansion that went another way, but the commercial cost isn’t abstract. It lands in who funds a company, what it builds next and how quickly it gets to market.
Canada has good reasons to keep banks and insurers out of unrelated commerce. Those guardrails protect stability and stop financial institutions from controlling too much of the wider economy. But a safeguard carries a cost when rules written for older business models keep constraining newer ones after Parliament has already approved change. The Competition Bureau’s fintech progress review has warned that regulatory barriers can weaken competition too. Capital won’t wait eight years for rulemaking to catch up.
Founders didn’t stop building while Ottawa worked through the rules. Banks and insurers still found ways to invest where the old framework allowed it, as Flinks, WayPay and ClaimSecure show. The 2026 proposal can widen those paths without turning strategic investment into another route to incumbent control. Eight years are gone. The better outcome now is a market where good Canadian fintechs have more ways to finance growth, commercialize useful technology and challenge the status quo.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |

August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
Leave a Reply