





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Stablecoin Research | Sep 23, 2025
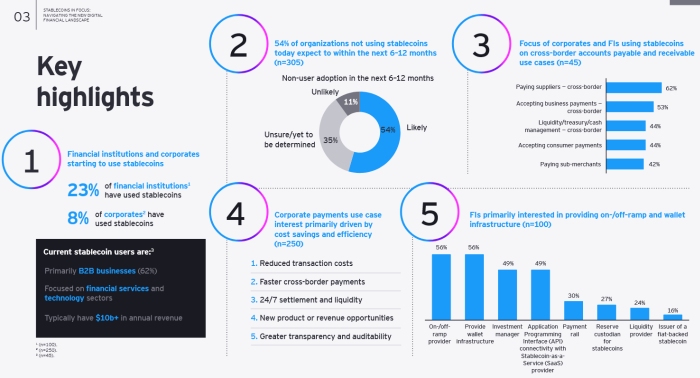
Image: Stablecoin Survey Research Highlights (EY Parthenon Sep 2025)
On September 15, 2025, EY-Parthenon released its latest stablecoin survey results, "Stablecoins: Adoption, Optimism, and Regulatory Clarity" (download 31 page PDF), covering 350 executives from corporates and financial institutions across the US, EMEA and other regions. Research takeaways confirm adoption is picking up speed, supposed by regulatory clarity by the GENIUS Act, recently signed into law.
Why is this happening? Approval of the U.S. GENIUS Act is a regulatory catalyst. Further, pilots are proving real value and corporate treasurers are under pressure to improve efficiency. The thinking is that organizations delaying adoption risk losing ground to competitors who are moving forward and benefiting from the lower cost and faster transactions of stablecoin technologies.
Why is everyone saving money by using stablecoins? The reason is straightforward. Traditional cross border payments involve multiple intermediaries, each adding fees and time. Stablecoins bypass these frictions and settles instantly, so the cost savings are structural (not incremental). For fintech providers, there's a growing opportunity to provide integration and risk management tools to help corporates adopt/use stablecoins and measure their effectiveness.
The reality is that we live and function in a global economy where delays can disrupt supply chains, so it's not surprising that corporates will adopt stablecoins for faster and more streamlined and predictable settlement solutions. This means that stablecoin adoption will likely strong and swift among B2B supplier and trade finance flows before expanding more widely into consumer payments.
In Canada, regulatory inaction is catching up with market momentum. On September 19, 2025, regulators like OSFI have warned the Prime Minister Mark Carney that Canada should accelerate federal stablecoin rules to avoid falling behind global peers. The Bank of Canada has echoed this call, saying stablecoins should be as safe and stable as the balance in your bank account. OSFI is already drafting a new framework to regulate stablecoin issuers, while domestic momentum is building as Tetra Digital Group secured $10M from Canadian banks and fintechs to launch a CAD stablecoin in 2026. Observers including investor John Ruffolo warn in his Looming Stablecoin Storm substack that without clear domestic rules, Canada risks ceding innovation, competitiveness and monetary sovereignty to jurisdictions that move faster.
Canadian corporates and fintechs need to plan not just for current global trends, but for a new local regulatory stablecoin framework. Firms are advised to engage with policymakers to create the right environment, build compliance ready infrastructure now and position for interoperability with USD pegged tokens and domestic stablecoin initiatives.Waiting could result in higher compliance costs, restricted access, and eventually a decline in market share.
Bottom line is banks understand that clients will demand stablecoin services and that failure to provide them risks their disintermediation. There's an intensifying race between traditional institutions and fintech challengers to capture stablecoin transaction flows.
Hybrid build and partner strategy. Corporates are demanding trust and compliance, while financial institutions know they cannot deliver the full stack alone. This means that partnerships between fintechs, banks and technology providers will determine how quickly stablecoin adoption scales.
Stablecoins are moving from pilot projects into enterprise strategy. Corporates see real cost savings and competitive advantage, while financial institutions are preparing to build services at scale to meet client demand. Regulation is beginning to catch up, led by the GENIUS Act in the US, but the global landscape is unbalanced while Canada’s fintech ecosystem is calling on the federal government to create and regulate a stablecoin framework to remain aligned and competitive.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply