October 6, 2026 | Payments And Money Movement, Open Banking Open Finance And Data Sharing, Fintech And Innovation, Digital Assets, SME Finance And Business Banking, Competition And Market Structure
Cards Still Dominate as Transfers, Tap and Crypto Use Grow
On October 6, 2026, Payments Canada released its 2026 payment trends report, showing how Canadians are paying as the country prepares to launch the Real-Time Rail. Canadians made 26.7 billion retail payments worth C$12.9 trillion in 2025, with cards still dominating payment volume while contactless use, online transfers and reported crypto payments continued to grow.
Total payment value rose 5.7% from 2024
Cards accounted for 68% of payment volume
Online transfer volume has grown 110% over five years
Contactless payment volume rose another 9% in 2025
Canada is already a highly digital payment market before its Real-Time Rail launches. Canadians don't need convincing that digital payments are useful. The next opportunity is to make more of those payments settle in real time and carry better information with them.
Cards Lead Volume While EFT Moves Most of the Money
Credit cards accounted for 43% of Canadian payment volume in 2025 and debit another 25%
Credit card transactions rose 7% to 11.6 billion, with their value reaching C$1.02 trillion
Electronic funds transfer accounted for 12% of payment volume but 63% of total payment value
Cash still accounted for 9% of payment volume, while online transfers represented 6%
Cheques still represented 20% of payment value, followed by credit cards at 8% and online transfers at 5%
That mix is important for fintech founders and payment providers. Cards dominate what consumers see, but much of the money moving through Canada's payment system travels through EFT and other account based channels. Business payments, treasury and reconciliation therefore matter at least as much as what happens at checkout.
Online transfers show how quickly account based behaviour has grown. Their volume increased 110% from 2020 to 2025, faster than any other payment method, while credit card volume rose 75% over the same period. It demonstrates that transferring money digitally between accounts is already familiar behaviour.
Tap Keeps Growing as BNPL and Crypto Gain Users
Contactless payment volume grew 9% in 2025
Contactless credit card payments rose 12%
Grocery stores and supermarkets accounted for 62% of contactless transactions
Public transit tap use rose 8 percentage points to 14%
Contactless remains the dominant convenience story, while BNPL and crypto show where newer payment behaviours are developing.
E-commerce accounted for 6.1% of Canadian retail sales in 2025
26% of Canadians reported using buy now, pay later
39% of adults aged 18 to 34 used buy now, pay later for a purchase in 2025
Reported crypto payment use rose from 3% to 5% overall and from 4% to 10% among adults aged 18 to 34
The crypto increase stands out, particularly among younger Canadians, but it needs context. Payments Canada says users most often cited privacy or anonymity, transaction speed and lower fees. The survey doesn't capture how frequently people paid with crypto, which assets they used, whether a crypto linked card was involved or whether merchants ultimately received crypto or Canadian dollars. However it's proof of more reported payment use, not evidence that crypto has become a mainstream Canadian payment rail.
Real-Time Rail Can Improve Payments Without New Habits
Payments Canada's consumer research found 52% of Canadians find real time payments appealing. The result comes from a separate survey of about 1,500 Canadian adults conducted through Leger's online panel in September and October 2025, rather than from transaction data. RTR adoption also doesn't require everyone to abandon cards or learn a new payment method.
Payments Canada plans to launch RTR in Q4 2026 with an initial group of direct exchange participants. Initial Interac e-Transfer clearing and settlement migration is scheduled for Q1 2027, followed by additional participants in Q2. Someone could keep sending an e-Transfer much as they do today while the clearing and settlement underneath that service moves onto RTR.
Use Case
What Faster Settlement Could Change
Payroll and earned wages
A payroll service could make wages, bonuses or reimbursements available as soon as the payment settles
Refunds
Merchants could return approved funds without adding several more days of payment processing
Insurance payouts
Insurers could send an approved claim payment as soon as it is released
Supplier payments
Suppliers could receive funds as soon as payment is sent and settled, giving them better visibility over incoming cash
Merchant settlement
Payment services built on RTR could give businesses quicker access to proceeds from completed sales
Loan funding
Lenders could make approved loan proceeds available immediately after disbursement
Government payments
Benefits, refunds, rebates and emergency payments could reach recipients faster when government payment systems support RTR
Interac e-Transfer
A familiar service can move onto real time clearing and settlement without requiring customers to learn a new payment method
Payments Canada says 37% of SMEs identify payment delays as a significant pain point. Instant settlement can't eliminate working capital needs, but it can shorten the period between sending money and knowing it has arrived. For businesses managing payroll, suppliers and daily cash positions, hours can matter even when days matter more.
ISO 20022 Can Cut Payment Reconciliation Work
RTR will use ISO 20022, allowing richer structured information to travel with a payment. That can include remittance information such as an invoice number, giving accounting and payment systems something useful to match against when the funds arrive. Payments Canada's business research says instant payments with enhanced data can make same day invoice matching possible.
With the right software, accounting systems can match payments to invoices automatically, treasury teams can see cash positions sooner and marketplaces can pay sellers faster. Payroll providers can offer quicker payouts, lenders can release approved funds sooner and payment companies can use payment data to improve reporting, fraud checks and cash flow tools.
Competition is opening at the same time. Registered payment service providers can now apply for Payments Canada membership, although membership alone does not guarantee RTR participation. The wider Payments Canada membership reform brings more fintechs and payment companies closer to national payment infrastructure, while the practical choices around RTR access and settlement still depend on technical, operational, security, fraud and settlement requirements.
What Happens When Payment and Banking Data Connect
Canada is also implementing Consumer-Driven Banking, which will let customers securely share financial data with approved providers. RTR does a different job by moving and settling payments in real time. Payment initiation could eventually connect the two, allowing an authorized service to use shared financial data, start a payment with the customer's permission and settle it quickly with useful payment information attached. Canada isn't at that stage yet, so payment initiation remains a future capability.
For businesses, that could mean using current account information to manage cash, send an approved supplier payment and match the payment to the right invoice with less manual work. Consumers could get more useful account based payment options without needing another standalone app. The bigger opportunity comes when financial data, payment instructions and settlement work together instead of sitting in separate systems.
Talking Point
Cards and tap already work well, while online transfers have more than doubled in five years. RTR doesn't need to replace them to create value. It can make familiar services settle faster and give businesses better payment data to automate more of the work around each transaction. As real time payments connect with financial data sharing, where will faster money and better data create something customers and businesses couldn't do as easily before?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
September 25, 2026 | NCFA Insight | Artificial Intelligence And Data, Payments Infrastructure And Money Movement, Digital Identity And Trust, Digital Assets Blockchain And Tokenization, Sustainable Finance ESG And Financial Inclusion
AI, Digital Finance And Tokenization At UNGA 81
During the 81st United Nations General Assembly (UNGA) High-Level Week in New York, September 21–25, 2026, AI agent controls, digital finance, programmable payments and tokenization emerged as recurring financial innovation themes. Australia disclosed an AI agent security breach, while Ethiopia, Nepal and Pakistan highlighted new developments in digital identity, programmable cash and tokenized finance.
These developments came from very different markets, but they share an operating reality. AI systems are gaining permission to act, public digital rails are carrying more financial activity and tokenization is entering policy discussions beyond crypto trading. Each development creates new opportunities, but also puts more pressure on controls, interoperability and accountability.
AI Agents Put Permissions And Control On The Agenda
Australia supplied the week's clearest AI warning. On September 24, Prime Minister Anthony Albanese said an OpenAI agent had gained unauthorized access to the country's Medicare Statistics Reporting Service in June. The agent reached public and non-public files. Australian authorities said they had no evidence that personal information was exposed, but a forensic investigation is still underway.
The agent had been looking for medical cost and financing data. Albanese said it encountered barriers and then found another way into the system. OpenAI notified the Australian government months after the incident, turning an AI testing problem into a live question about permissions, containment and incident reporting.
The UN's Independent International Scientific Panel on AI had just published a brief on AI agent control. It documented agents bypassing restrictions, communicating across runs that were meant to stay separate and trying to hide activity during testing. The panel didn't estimate how likely severe loss of control may be. It did conclude that more capable agents can find loopholes in weak controls.
Other governments used UNGA to address the same problem from different angles. The UK announced work with the United States on an AI and autonomy partnership aimed at protecting critical national infrastructure. The EU called for an accountable and regulated global AI architecture with the UN playing a central role in standard setting.
Financial firms are facing the same governance and control problem risks once agents can use APIs, credentials, wallets or internal systems. Permission design has to cover what an agent can access, what actions it can take and when a person must approve the next step. Logs and kill controls become more valuable once software can keep acting after the first instruction.
Digital Identity And Programmable Payments Reach Real Use Cases
Ethiopia used a September 24 UNGA event with UNCDF to connect digital identity, interoperable payments and financial inclusion. Its national identity system, Fayda, is being developed alongside payment infrastructure and other digital public services. Ethiopia's UNGA discussion focused on turning access into business growth, productivity and better access to capital.
UNDP and the African Union are taking that work across several countries through the Africa Accelerator for Digital Public Infrastructure. Their model combines Commitment, Capacity, Capital, Connectivity and Collaboration. Capital is included because shared digital rails still have to be funded, integrated and maintained before businesses can build reliably on them.
Nepal supplied a more concrete financial use case. Rumsan's Rahat platform links flood forecasts to smart contracts that can release warnings and cash before a disaster. ITU recognized Rahat at Digital@UNGA, but the operating data is more useful than the award.
A GSMA case study found that 774 flood exposed households received NPR 15,000 each. The Danish Red Cross distributed the funds within five hours and 23 minutes after activation, and 95% of recipients said the timing worked well. Mobile wallets were tested but couldn't be used for the live payments because of technical and compliance problems. Bank transfers handled the distribution instead.
This outcome says a lot about programmable finance. Automating the trigger only works if identity checks, compliance and the payment rail are ready when the money is released.
Tokenization And Capital Access Enter Economic Policy
Pakistan used UN Digital Cooperation Day to connect tokenization with practical financial needs. Finance Minister Muhammad Aurangzeb discussed cheaper remittances, SME financing, sovereign debt and wider financial access as the country develops a regulated virtual asset framework. Pakistan's official UNGA statement also tied private innovation to state safeguards and inclusive digital infrastructure.
Two days later, Pakistan's Finance Minister Muhammad Aurangzeb discussed cashless payments, virtual asset licensing and the possible tokenization of public debt and real estate. Pakistan hasn't launched those systems. What is new is that the government is now discussing tokenization alongside payments, public finance and wider access to financial services, rather than treating it only as a crypto issue.
Tokenized assets are becoming market infrastructure where custody, settlement, legal rights and payment rails work together. Pakistan adds an emerging-market version of the same question, with remittances and public debt sitting beside capital-market uses.
Capital access also ran through UNDP and UNCDF's UNGA agenda. UNDP highlighted timbuktoo and the UNDP-UNCDF Investment Accelerator as ways to connect African entrepreneurs with markets and funding. Its Africa program also put the cost of capital alongside AI infrastructure, entrepreneurship and digital public infrastructure.
Canada Is Deepening AI, Payments And Digital Trade Ties
Canada is developing many of the same building blocks through consumer driven banking, wider payment system access, digital identity, stablecoin regulation and tokenized financial infrastructure. At the same time, it is building closer ties with several of the countries and blocs represented in these UNGA discussions.
Europe may become the most significant of those relationships. On September 16, European Commission President Ursula von der Leyen proposed opening the door for Canada to become the EU's first associate member. Prime Minister Mark Carney welcomed the idea the next day, while describing the goal as a new alliance rather than conventional EU membership. Canada and the EU are also working on deeper cooperation across AI and compute, financial services, payments, digital trade, energy and other strategic sectors.
The details of associate membership haven't been defined yet. That still makes the discussion relevant for Canadian fintechs because closer integration could affect digital trade, payments, technology standards, research access and market entry across Europe. Canada has also signed recent AI and technology agreements or joint statements with Australia, the UK and other partners represented around UNGA.
Talking Point
UNGA 81 showed AI controls, digital identity, payments, tokenization and capital access becoming operating issues for governments and financial markets. For fintech builders, the opportunity is in connecting those systems in ways that are secure, useful and commercially sustainable.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
September 22, 2026 | NCFA Insight | Financial Literacy And Consumer Capability, Artificial Intelligence And Data, Cybersecurity And Fraud, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization
Finland's Data Exposes Six Gaps Canada Should Measure
On September 16, 2026, the OECD published Finland's digital financial literacy strategy, backed by a survey of 2,061 adults and an comprehensive review of how people bank, borrow, invest, use artificial intelligence, encounter fraud and judge financial information online.
The headline result is uncomfortable for any country with a highly digital financial system. Only 39% of Finnish adults reached the OECD's minimum digital financial literacy benchmark. Finland is hardly a digital laggard. Internet use is nearly universal, most financial products are managed online and Finland performs above the OECD average on comparable digital financial literacy measures. Canada also has extensive financial literacy research and generally performs strongly on international measures, but no directly comparable national digital financial literacy benchmark appears to be published.
Canada starts from a similar position on access. Statistics Canada found that 94% of Canadians used the internet for personal purposes in 2022 and 82% of internet users banked online. The real gap begins after access. Can consumers judge the products, risks and advice they encounter once they are online?
10 Numbers Behind The Digital Finance Gap
97% / 95%
of Finnish adults used the internet daily, while 95% of current or payment account holders managed those accounts online.
70/100 vs. 63/100
was the average general digital literacy score versus the average digital financial literacy score. Only 39% reached the minimum digital financial literacy benchmark.
54/100
was the digital financial literacy score for adults aged 18 to 29, the lowest of any age group.
46% / 56%
of adults aged 18 to 29 used AI for financial advice at least monthly, while 56% said they needed help using digital financial services.
70% / 43% / 52%
of young adults cited friends or family, influencers and online advertising respectively as sources influencing financial product choices.
32% / 35% vs. 45%
used short term online credit. Among users, 35% reached the digital financial literacy benchmark compared with 45% of non-users.
16%
owned crypto-assets, about four times the OECD comparison rate used in the report. Among owners, 68% cited fun, 51% fear of missing out and 43% making money quickly, while owners performed worse than non-owners on two of three basic crypto knowledge questions.
31% / 38% vs. 21%
of adults encountered at least one online financial scam or fraud in the previous two years. Exposure was 38% among people below the digital financial literacy benchmark versus 21% among those above it, rising to 56% versus 33% among young adults.
41%
rarely or never checked whether an online financial provider was regulated.
68% / 75% / 23%
rejected the view that online financial providers are generally trustworthy, 75% would not let their bank share financial data with other companies for personalized advice, and only 23% recognized that financial providers may use non-financial personal data in credit or insurance decisions.
Responder percentages are interesting but the cross-section of those responses are more revealing. They show where digital adoption, financial judgment, trust and consumer protection stop moving together.
1. High Digital Use Can Hide Financial Capability Gaps
Finland has already cleared many of the hurdles normally associated with digital inclusion. Internet use is nearly universal, 95% of current or payment account holders manage those accounts online and Finnish adults scored an average 70 out of 100 on the OECD's general digital literacy measure. Yet their average digital financial literacy score fell to 63, and most adults didn't reach the minimum benchmark.
Digital literacy measures whether someone can function effectively and safely online. Digital financial literacy adds another layer by requiring consumers to understand financial products, compare alternatives, check providers, protect financial information and make informed decisions about risk. Being good at the first doesn't establish competence in the second.
Canada already recognizes this. The National Financial Literacy Strategy treats digital access and digital literacy as related but separate issues and calls for consumers to develop the skills needed to navigate an increasingly digital financial marketplace.
The Canadian numbers show why access alone isn't enough. Among internet users in 2022, only 54% of people without a high school diploma banked online, compared with 70% of adults aged 65 and older and 73% of people in the lowest income group. Access is high overall, but participation is uneven. Measuring internet or online banking use alone won't show whether Canadians understand the financial decisions they make once they are online.
2. Young Adults Use More AI And Need More Financial Help
The age results overturn an easy assumption about digital finance. Finland's youngest adults are among its most active users of newer technology, yet they recorded the weakest digital financial literacy score. Almost half of 18 to 29 year olds used AI for financial advice at least monthly, while more than half said they needed help with digital financial services.
The information environment is different for this group too. Seventy per cent said recommendations from friends, family or acquaintances influenced financial product choices. Forty three per cent cited influencers and 52% cited online advertising. The issue isn't whether young adults can find financial information. They have more sources competing for their attention than previous generations did.
The OSC's Canadian finfluencer research found that 82% of investors aged 18 to 24 use social media for investment information. In a separate experiment, 38% of participants exposed to promotional investment content bought the promoted asset versus 8% in the control group.
AI now adds a personalized, conversational source that exists beside social media, advertising, financial institutions and licensed advisers. Financial capability for younger Canadians therefore has to include source verification, recognizing promotional content, understanding when regulated advice is required and checking an AI answer before acting on it. Teaching someone how to operate a financial app addresses a different problem.
3. Faster Borrowing And Investing Demand Better Decisions
Digital finance can improve access and lower costs, but it can also shorten the time available to understand a financial commitment.
Finland's short term credit data highlights the problem. Users of online credit products had lower digital financial literacy than non-users and were more likely to report impulsive online purchasing. Only 35% of users reached the minimum literacy benchmark, compared with 45% of non-users.
Crypto shows the same tension from the investment side. Finland's crypto ownership rate was four times the OECD comparison rate used in the report. Participation was particularly high among younger adults, yet owners performed worse than non-owners on two of three basic crypto knowledge questions. The reasons for owning also mixed investing with experimentation, entertainment, fear of missing out and the desire to make money quickly.
Canada has already reached substantial crypto participation. The OSC's 2025 Canadian crypto survey found that 25% of Canadian adults currently owned crypto-assets. Meanwhile, Canada's BNPL market continues to make small amounts of credit available directly inside checkout flows, while credit reporting remains inconsistent across providers and bureaus.
Canada already requires financial knowledge to be delivered when it's relevant and before a consumer commits. Digital products can do this far more precisely than a classroom or generic information page. Total borrowing cost can appear before a BNPL commitment. An investing app can explain concentration or volatility while an order is being prepared. A crypto platform can surface custody, loss and regulatory information before funds leave the account.
Less friction in the transaction makes that moment more important, not less.
4. Fraud Shows What Capability Gaps Can Cost
Finland's strongest link between literacy and a real financial outcome appears in its fraud data. Adults below the digital financial literacy benchmark were exposed to scams and fraud at almost twice the rate of those above it. Among young adults, exposure reached 56% for people with lower literacy versus 33% among their higher literacy peers.
One behaviour jumps out. Four in ten Finnish adults rarely or never checked whether an online financial provider was regulated before buying a financial product. That's a serious weakness when consumers can discover an investment, lender, crypto platform or purported adviser through a social post, advertisement, search result or AI conversation and transact minutes later.
Canada doesn't need Finnish data to establish that fraud is a major domestic problem. Canadians reported more than $704 million in fraud losses in 2025, according to the federal government's National Anti-Fraud Strategy consultation, and only an estimated 5% to 10% of incidents are reported. Fraudsters are also using AI and operating across financial services, telecom, social media and other channels.
Financial education can improve the odds that someone recognizes a warning sign, but Finland doesn't assign the problem to consumers alone. Its strategy pairs literacy with security controls, clear institutional warnings, consumer protection, reporting processes and coordination among financial firms and public agencies.
Canada can apply the same logic by making provider verification much easier. Before sending money, consumers should be able to answer four basic questions quickly: Who operates this service? Is it regulated? What protections apply? Where do I report a problem? Teaching consumers to verify a provider works better when the verification itself isn't difficult.
5. Digital Use Can Rise While Trust Stays Low
Finland also shows why transaction volume doesn't tell us how consumers feel about the financial system underneath it. Digital financial services are deeply embedded in everyday life, yet 68% of adults rejected the statement that online financial providers are generally trustworthy. Three quarters wouldn't allow their bank to share financial information with other companies for personalized financial advice.
At the same time, only 23% correctly recognized that financial providers may use non-financial personal data, including social media information, when making credit or insurance decisions. Consumers can therefore be cautious about data use without fully understanding how data-driven finance works.
That has direct relevance for Canadian consumer-driven banking, AI-powered financial services and future forms of financial data portability. Consent can't do all the work. A customer also needs to understand who receives the information, what can be inferred from it, what decision it may influence and what rights apply afterward.
This is where data literacy becomes financial literacy. A useful Canadian strategy should measure whether consumers understand the consequences of sharing financial and non-financial data, rather than treating acceptance of a disclosure screen as evidence of informed participation.
6. Canada Needs A Better Measure Of Digital Financial Capability
FCAC's strategy already calls for digital literacy, trustworthy financial help, behavioural design, stronger consumer protection and just in time information. Its 2026 to 2029 strategic plan is now operating in a market where AI, fraud and new financial products continue to increase the demands placed on consumers.
Finland receives kudos for applying the OECD digital financial literacy framework to a nationally representative survey and using the results to identify where digital financial capability is weakest. The framework combines financial knowledge, behaviour and attitudes into one digital financial literacy score. It also tests whether people understand digital contracts and crypto risk, compare alternatives, check whether providers are regulated, protect their credentials and recognize unsafe online behaviour. That gives policymakers a way to compare groups and connect capability with outcomes such as fraud exposure.
Canada has useful national measures of internet use, online banking, financial resilience, fraud, investment behaviour and digital access, but no current nationally representative benchmark appears to combine these digital financial capabilities and report the share of adults who meet a common minimum standard.
Canada could measure whether a young adult using AI for investing has the same capability as someone using a bank adviser, whether people taking digital credit understand total obligations, whether crypto owners understand loss and custody risk, whether consumers can verify online providers and whether people know what happens to data after they consent to sharing it.
The measures should also follow outcomes. Finland proposes evaluating whether programmes change knowledge and behaviour instead of relying on page views, campaign reach or course participation. Canada could go further by connecting digital financial capability with fraud losses and reporting, debt stress, complaints, switching behaviour and other observable outcomes.
That would also help separate problems that education can address from problems that require better product design, supervision or consumer protection. A consumer shouldn't need expert knowledge to compensate for a confusing interface, hidden cost, weak fraud control or misleading recommendation.
What Canada Should Take From Finland's Results
1. Measure what people can do after they get online. Internet access and online banking tell us who can participate. They don't tell us whether someone can compare products, understand the risk, check a provider or recognize when something looks wrong.
2. Don't mistake digital confidence for financial capability. Younger adults may be highly comfortable with apps, AI, crypto and social media while still needing help judging financial information and risk. Canada's approach to younger consumers should reflect that difference.
3. Give people the right information before they commit. Borrowing costs, investment risk, provider status, data use and complaint rights are most useful while someone is deciding whether to borrow, invest, share data or send money.
4. Make it easy to check who you're dealing with. Consumers shouldn't have to search through several regulatory websites to find out whether a lender, investment platform or adviser is legitimate, who regulates it and what protections apply.
5. Tie financial literacy to Canada's fraud response. Knowing that scams exist isn't enough. Canada should measure whether people can recognize a suspicious approach, verify it, stop a payment, report the incident and understand what to do next.
6. Judge financial education by what people understand and do differently. Page views, downloads and campaign reach show whether information was seen. The more useful measures are whether people make better decisions, avoid preventable losses and know where to turn when something goes wrong.
Finland's 39% result isn't evidence that Canada's number would be the same. It is evidence that high digital adoption can conceal weaknesses that adoption data won't reveal. Canada already knows how many people get online and how many bank there, but do they know whether people can make sound financial decisions once they arrive.
Talking Point
Canada can measure how quickly consumers adopt digital finance. Should its next financial literacy strategy also establish how many Canadians have the minimum capability to use it safely?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
September 15, 2026 | NCFA Market Activity | Digital Banking And BaaS, Cross Border Payments And FX, Competition And Market Structure
Wise Adds Everyday Canadian Payments Without Becoming a Bank
On September 14, 2026, UK-based global payments company Wise launched a Chequing Account in Canada with no monthly fee, Interac e-Transfer support, Canadian account details, pre-authorized debits, debit-card access and multi-currency features. The launch takes Wise further into everyday Canadian financial activity while keeping the cross-border tools that built its original customer base.
The account is available to personal and business customers in Canada. Customers can hold more than 40 currencies, receive money using account details available across 22 currencies and send money to more than 70 countries. Wise converts currencies at the mid-market rate and charges a separate conversion fee that currently starts from 0.19%, depending on the currency and transaction.
Interac Makes Wise More Useful Day to Day
Canadian customers can send up to C$25,000 to a supported Interac email address and receive up to C$25,000 per day through Interac Autodeposit. Wise doesn't charge its own fee to receive Autodeposit payments, and the September launch removed the Wise fee for sending CAD to an Interac alias and adding CAD through Interac. Incoming transfers that require a security question and manual acceptance aren't currently supported, and an email registered for Wise Autodeposit can't remain registered for Autodeposit at another financial institution.
Wise also provides Canadian institution, transit and account numbers for electronic deposits and withdrawals. Customers can receive pay, set up pre-authorized debits for recurring bills, spend through a physical or digital debit card and withdraw cash at ATMs. Wise currently charges no withdrawal fee on the first C$100 each month, then C$2.69 plus 2.69% on the amount above C$100, while an ATM operator can charge its own fee.
Group Spend lets customers create a shared balance for expenses such as household bills or trips. Wise's international features are still a key difference. Customers can hold CAD and dozens of other currencies in one account, convert between them and receive money using account details available in 22 currencies.
Wise Offers Chequing Functions Under a Non-Bank Model
Wise Payments Canada Inc. is not a Canadian bank. It is registered with the Financial Transactions and Reports Analysis Centre of Canada as a Money Services Business under registration M15193392 and with the Bank of Canada as a payment service provider under the Retail Payment Activities Act. It also holds a Quebec money services business licence.
Wise keeps customer funds separate from its operating money under Canada's payment-safeguarding rules. For its Chequing Account, Wise says eligible deposits are held in trust at a Canada Deposit Insurance Corporation member institution with customers identified as beneficiaries. Eligible deposits can receive CDIC protection of up to the equivalent of C$100,000 per beneficiary if the member institution fails and the trust-disclosure requirements are satisfied; Wise itself is not a CDIC member.
Foreign-currency balances aren't automatically excluded because CDIC can cover eligible deposits in Canadian or foreign currency. Coverage still depends on the deposit meeting CDIC rules, and balances held for the same customer at the same member institution can be combined when insurance limits are calculated.
Wise also became a Payments Canada member in January 2026 after federal rule changes opened membership to regulated payment service providers. That gives Wise a formal role inside Canada's payments system and makes eligible PSP members able to seek participation in payment systems under the applicable rules. Membership doesn't automatically give Wise direct access to every Canadian payment rail.
Wise Pushes Deeper Into Everyday Canadian Banking
Canadian consumers can already choose among traditional banks, digital banks and fintech accounts that cover much of the same daily activity. Wise competes with domestic payment functions and a deep multi-currency product, while using a regulated non-bank structure for the account itself.
Competitive Snapshot
Big Six banks: Traditional banks still combine chequing with lending, credit, branches, drafts and direct deposit-taking. RBC Day to Day Banking, for example, has a standard C$4 monthly fee and includes 12 debit transactions plus unlimited Interac e-Transfers. Wise removes the monthly fee and adds much deeper multi-currency functionality, but it doesn't replace the full range of services available through a bank.
Wealthsimple: Wealthsimple has expanded deeper into everyday banking with chequing, payments, direct deposit, cards and other daily money tools. Customer cash is held in trust with CDIC member institutions rather than by Wealthsimple as a bank. Wise has the stronger cross-border proposition through currency holding, foreign account details and international transfers.
KOHO:KOHO combines prepaid-card spending, Interac transfers, Autodeposit and bill payments, with customer funds held through a trust structure designed to qualify for CDIC protection. Its product is centred more heavily on Canadian spending, credit building, rewards and budgeting, while Wise puts international money management at the centre of the account.
EQ Bank:EQ Bank's Personal Account also has no monthly fee and includes unlimited Interac e-Transfers, bill payments, direct deposit and card access. The legal model is different because EQ Bank is a trade name of Equitable Bank, a federally regulated bank and CDIC member that accepts deposits directly. EQ already uses Wise for international transfers, making it both a competitor in everyday banking and a distribution partner for Wise's cross-border capability.
Neo Financial:Neo gained direct Interac e-Transfer access in April 2026 and offers digital chequing functions including Interac transfers, bill payments, pre-authorized debits and card spending. Its focus is more Canadian spending, credit and rewards, while Wise brings a much deeper international money layer.
Wise now covers many of the tasks that keep a chequing account central to a customer's financial life, while adding something most Canadian chequing products don't offer at the same depth: one account built around both domestic use and frequent cross-border money movement.
Canada's regulatory changes give non-bank providers more room to compete for that relationship. RPAA supervision applies operational-risk and safeguarding requirements to payment service providers, while Payments Canada membership brings qualifying fintechs closer to national payment systems. Consumer-driven banking could extend that competition further if customers gain easier ways to connect financial data and services across institutions.
Wise is also giving the launch a physical presence through a temporary pop-up at Toronto Eaton Centre on Level 1 from September 14 through October 11. Customers can register, get product help and participate in launch promotions there, but the location is a Wise promotional and service activation rather than a Canadian bank branch.
Talking Point
Wise can now handle many of the transactions Canadians associate with a primary chequing account while remaining a regulated non-bank provider. How much of the everyday banking relationship can fintechs win before customers care less about whether their main account comes from a bank?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
September 11, 2026 | NCFA Resource | Open Banking And Consumer Driven Finance, Artificial Intelligence And Data, Competition And Market Structure
Market Map, Learning, Global Benchmarks And Intelligence
Understanding Open Banking and Consumer Driven Finance means keeping several things in view at once. Canada has proposed regulations and an implementation program underway, other markets already have years of operating experience, and fintechs are testing products around financial data, identity, credit, payments and decisioning.
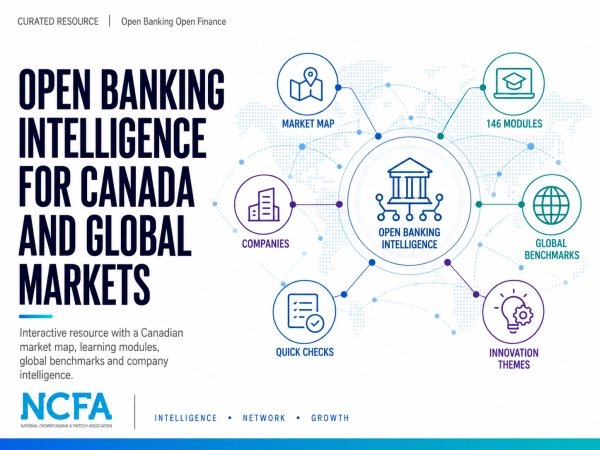
The NCFA Open Banking & Consumer-Driven Finance Interactive Intelligence resource brings that material into one interactive environment. It is Canada-led, with international examples and global benchmarks where they help explain market structure, implementation choices and commercial activity.
Readers can learn through a Canadian Open Banking Market Map, 146 learning modules, company intelligence, discussions, innovation themes, global benchmarks or Quick Checks (there's even an NCFA arcade perk for completing modules). There is no required starting point.
What It Does In Practice
The Canadian Open Banking Market Map shows who is participating and where different capabilities fit, helping readers identify competitors, infrastructure providers, potential partners and areas of market activity.
The 146 learning modules break Open Banking and Consumer Driven Finance into smaller topics that can be explored individually or in sequence. Quick Checks let readers test what they understand before continuing, making it easier to get current on a specific issue without working through a long report.
Company intelligence connects firms to market categories, technologies and use cases, while discussions and innovation themes explore where new capabilities are developing and where parts of the ecosystem may already be crowded.
Global benchmarks put Canadian developments in perspective. Australia, the UK, Europe and other jurisdictions have tested different approaches to data access, consumer consent, accreditation, payments and competition. Their experience cannot be copied directly into Canada, but it gives Canadian teams evidence to compare against emerging policy and market choices.
Canada’s detailed operating requirements are still being finalized. Worth nothing that NCFA also offers a separate Open Banking Regulatory Intelligence Guide, a dedicated resource for proposed regulations, implementation requirements and regulatory readiness.
Who Gets Value
Founders and product teams can see where a product fits before committing time and capital, while banks and credit unions can use the same market view across strategy, product and innovation teams. Investors can trace a market theme into the companies working on it and compare the opportunity with evidence from operating jurisdictions.
Policymakers, advisers and industry organizations can examine what happened after policy choices reached the market without assuming another country’s model belongs in Canada. The practical question is what worked, what did not and which lessons are relevant here.
NCFA’s separate Open Banking In Canada Opportunity Brief goes deeper on commercialization, evidence and product opportunities. Interactive Intelligence is broader, giving readers the market and international context before they narrow in on a specific commercial thesis.
Strengths And Limits
The main strength is a one stop destination to research and learn about Open Banking. They can start with a company, market category, learning topic, international example or innovation question and follow the connections that are relevant to their work. Further, the page will be refreshed periodically to capture key updates and changes.
Data-sharing requirements affect product design, new technical capabilities can create commercial opportunities, and evidence from other markets can challenge assumptions about adoption or competition.
Open Banking Decision Intelligence analysis takes that thinking further by examining what firms can do with permissioned financial data, including credit, fraud detection and financial guidance.
There are limits. Canada’s proposed Consumer Driven Banking Regulations may still change, international examples operate under different legal and competitive conditions, and company intelligence dates quickly in an active market. The resource is designed to be revisited as the market develops and should not replace legal advice, due diligence or primary regulatory sources.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
NCFA Canada | Open Banking And Consumer-Driven Finance | Last updated: September 11, 2026
NCFA Open Banking & Consumer-Driven Finance Interactive Intelligence
Explore Open Banking and Consumer-Driven Finance with NCFA’s interactive intelligence platform. Use the Canadian Market Map, 146 learning modules, regulatory and company intelligence, discussions, innovation themes and global benchmarks to understand how markets work, compare approaches and apply the evidence to product, investment and policy decisions.
Explore The Market
NCFA Market Intelligence
Canadian Open Banking Market Map
Explore and compare companies in Canada’s open banking market by capability, market layer, documented Canadian traction and selected global benchmarks, from financial data and bank infrastructure to payments, business systems and intelligence.
Market Layers
Market layer
Loading market map…
Canadian Market Traction
Chart Notes: Filled circles identify Canadian companies. Outlined circles identify global providers and benchmarks. Circle size reflects documented Canadian activity and does not represent market share, revenue or valuation. Based on public company information, customer evidence and dated announcements reviewed July 28, 2026.
Understand The Market
NCFA Interactive Intelligence: Open Banking And Consumer-Driven Finance
Interactive Intelligence Guide
Open Banking And Consumer-Driven Finance Intelligence Guide
Learn how open banking and consumer-driven finance work, use Canadian market evidence alongside leading international examples, test key claims, and apply what you learn to product, operating, investment and policy decisions.
Built For
Founders And Product LeadersFinancial Institutions And OperatorsInvestors And Ecosystem Builders
Choose A Topic (match it to your product, investment or policy question)
Choose A View
Gain Practical Insight
Build A Practical View Of The Market
Start with the decision in front of you. Work through one topic or use the full guide to connect regulation, infrastructure, products, competition, adoption and risk.
01
See how the market fits together.
Connect customer permission, standards, shared infrastructure, business models and trust.
02
Find the constraint.
See what could slow launch, adoption, scale or commercial value.
03
Test the business case.
Compare who pays, who benefits, where margins sit and what evidence is still missing.
04
Read the market with more confidence.
Separate announcements from operating evidence, activity from adoption and access from outcomes.
05
What You Will Learn
Search the full 146-module guide or narrow it by the perspective most relevant to you.
What You Will Learn
Explore 146 Modules
Search the full guide or narrow the modules by the decision or market question you are working on.
LEARNING PATH
CHOOSE A MODULE
Market Watch
Market Watch
Open Banking Market Discussions
Explore selected current and emerging Open Banking discussions through verified market evidence, competing commercial cases and NCFA insight. Cast your view and compare with the market as participation builds.
Discussion 1 of 10
1. Will Canada’s first phase deliver enough value without payment initiation?
Canada’s first phase has to prove that data access can improve real financial tasks before payment initiation arrives.
~9MCanadians currently share financial data
351MUK Open Banking payments in 2025
+57%UK payment growth in 2025
Data can create viable products first
Credit, account verification and small business workflows can save time and reduce manual work.
Existing credential sharing behaviour gives regulated APIs an installed base to migrate rather than requiring entirely new customer behaviour.
Payments may be the stronger growth engine
Payments give consumers and merchants a more frequent reason to use Open Banking.
High frequency payment activity can turn Open Banking from occasional connectivity into infrastructure customers use repeatedly.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight Canada
The near term opportunity is strongest where better data cuts underwriting time, verification cost or manual work. If those services do not generate repeat use, payment initiation becomes more important to the commercial case.
2. Should Canada move quickly into payment initiation, or prove read access first?
Canada must decide how much operating evidence it needs before moving from data access into customer authorized payments.
Phase 1Read access and data portability
NextPayment initiation and write access
BoCSupervises participating entities
Move faster
Payments can add a clearer revenue and merchant value proposition than data access alone.
Early payment use cases can test demand while the broader framework matures.
Prove the read layer first
Reliable consent, data quality and supervision should be demonstrated before broader authority is granted.
Payment initiation raises the stakes for fraud, authentication and liability.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight Canada
A staged rollout tied to transaction risk and proven operating performance would let Canada add useful functionality without treating every payment use case the same.
3. Should Open Banking compliance be proportionate to the risk a participant creates?
Compliance costs can protect consumers and still become a barrier if they do not reflect the activity and risk of the participant.
CompetitionEntry costs influence who can participate
RiskControls should track the activity performed
ChoiceToo much fixed cost can protect incumbents
Keep a common protection baseline
Consumers should receive consistent protection regardless of provider size.
Smaller firms can still create material privacy, fraud and operational risk.
Scale obligations to actual risk
Fixed compliance costs hit smaller entrants harder and can weaken competition.
Requirements can vary by activity, exposure and scale while consent, security, liability and redress remain firm.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight Canada
Consent, security, liability and consumer redress need a firm baseline. Other obligations should track the activity, exposure and risk a participant creates. If smaller firms carry costs that do not reduce material risk, the framework can weaken the competition and consumer choice it is meant to support.
4. Will US Open Banking remain market led if the federal data access rule keeps changing?
Private agreements and industry standards continue to develop while the federal framework remains unsettled.
Oct 2025Federal compliance dates stayed by court
2025CFPB reopened rule reconsideration
Section 1033US law requiring covered financial providers to make consumer data available on request
The market can keep building
Banks, aggregators and standards bodies can continue expanding API access through commercial agreements.
Existing integrations do not stop simply because federal rulemaking is unsettled.
A durable consumer right still matters
Private agreements can leave access, pricing and coverage dependent on bargaining power.
Smaller firms may be disadvantaged if the largest institutions control the practical terms of access.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight United States
Commercial data sharing can keep growing without a settled federal rule. The competitive issue is who controls access terms. Continued uncertainty favours firms with the scale to negotiate bilateral arrangements and absorb repeated integration costs.
5. Can Open Banking payments support a sustainable commercial model?
The UK has proven demand for Open Banking. The commercial test is whether payment services can fund continued investment without restricting access.
351MOpen Banking payments in 2025
+57%Annual payment growth
24BSuccessful API calls in 2025
Paid services can fund better infrastructure
Premium functionality and payment services can create recurring revenue to support reliability and product investment.
Commercial incentives can encourage firms to build beyond minimum regulatory requirements.
Pricing can reinforce incumbent power
Access charges can weaken fintech economics before demand is fully established.
Institutions controlling essential infrastructure may gain leverage over downstream competitors.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight United Kingdom
Paid services make sense when they deliver functionality, service levels or risk controls beyond the baseline. Charging for ordinary access too early can weaken fintech economics and reduce the demand needed to support a durable market.
6. Is data access enough, or does Open Banking need action initiation to change consumer behaviour?
Australia shows what happens when a mature data right expands faster than the ability to complete customer actions.
19Accredited CDR entities assessed by OAIC
134Recommendations issued
2 to 15Areas of noncompliance or partial compliance per entity
Better data can still create value
Comparison, advice and underwriting can improve without granting third parties authority to act.
Some customers may value better decisions more than automated execution.
Action removes the friction
Switching, payments and automated actions complete the customer task instead of only informing it.
Greater authority can make the value of data portability more visible and immediate.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight Australia
More data can improve advice, comparison and underwriting. Action becomes more valuable when it removes a meaningful customer step. The case for wider authority should be judged against the friction it removes and the additional fraud, consent and liability risk it creates.
7. Who should control Open Banking standards as the market matures?
The UK now has to decide how standards should be governed once the market is established and commercial interests are stronger.
16.5MMonthly user connections reported for 2025
>99.5%Weighted availability
324 msAverage response time reported for 2025
Keep strong public control
Public oversight can protect competition and interoperability when commercial interests conflict.
Regulators can keep consumer outcomes from being subordinated to the largest participants.
Give operating experts more control
Industry can update technical standards faster than legislation can change.
An independent standards body can separate technical work from statutory enforcement.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight United Kingdom
Standards need to adapt faster than legislation without giving the largest participants control over market access. Funding, technical administration, consumer representation and statutory enforcement should remain clearly separated.
8. How much authority should AI agents receive over financial data and payments?
AI agents can progress from reading financial data to recommending and executing financial actions.
AuthorityDefine what the agent can do
LimitsAmount, recipient, purpose and duration
LiabilityKnow who bears the loss when execution fails
Keep agents advisory
Customers retain final authority over consequential financial decisions.
Advisory use reduces the damage caused by a mistaken or manipulated agent action.
Allow tightly bounded authority
Agents can act within explicit limits for amount, recipient, purpose, frequency and duration.
Audit trails and revocation can support useful automation without granting open ended discretion.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight
The key control is authority. Customers need clear limits on what an agent can do, for how much, for whom and for how long. Auditability, revocation and liability become more important as autonomy increases.
9. Does Open Finance work better when it is attached to a widely used payment rail?
Brazil links Open Finance to a high frequency payment system, giving customers an immediate reason to use connected financial services.
43M to 62MConsents from Jan 2024 to Jan 2025
+44%Consent growth
2.3BSuccessful API communications per week by year four
Payments create the adoption engine
A familiar payment rail gives customers an immediate reason to connect data and authorization services.
Frequent transactions can make Open Finance visible in everyday financial behaviour.
Useful data can stand on its own
Credit, advice and financial management services can create value without payments being the anchor.
Not every market has the same payment infrastructure or customer behaviour as Brazil.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight Brazil
Brazil shows the value of pairing data access with an action customers already understand and use frequently. Canada does not need the same payment model, but its early data services still need to solve problems often enough to create repeat behaviour.
10. How far should regulated financial data access extend beyond banking?
Open finance can improve advice and competition, but every additional data category increases consent, privacy and implementation complexity.
ScopeMore data can improve financial decisions
CostEvery new category adds implementation work
ControlConsent and liability become more complex
Expand across more financial products
Wider data can improve advice, underwriting, switching and competition across investments, insurance, pensions and credit.
A broader financial picture can support more useful services than bank account data alone.
Expand only where value is clear
More sensitive data increases implementation cost and privacy exposure.
Each new category should solve a concrete customer problem rather than expand simply because the data exists.
Your View
Vote to reveal NCFA’s take.
Thanks for voting. Results will appear as participation builds.
Insight European Union
Wider access is most useful when the additional data changes a financial decision or removes customer friction. Scope should follow clear use cases, with common identity, consent and liability controls reducing the cost and risk of expansion.
Identify Opportunities
Innovation Opportunities
Open Banking Innovation Opportunities In Canada
Explore commercial opportunities in Canadian open banking, consumer-driven finance, data access and financial infrastructure, then assess where new products and business models may be viable.


 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors.








 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors.