




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


October 29, 2026 | NCFA Story Intelligence | Capital Markets Infrastructure And Funding, Artificial Intelligence And Data, Competition And Market Structure
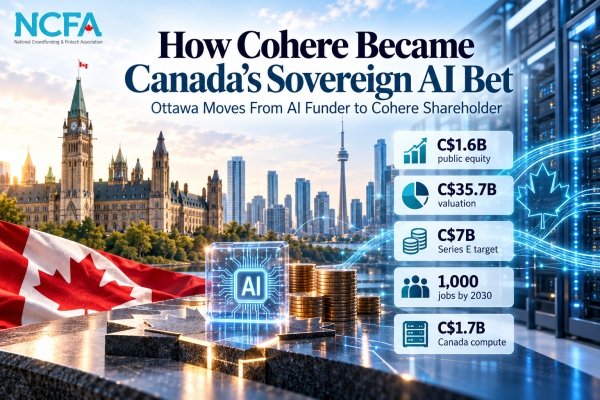
On October 29, 2026, the Ottawa announced plans to invest up to C$1.6 billion in Toronto based Cohere as part of a Series E financing targeting as much as C$7 billion, putting public money directly into a Toronto company that is trying to build a Canadian and European alternative to the dominant US AI platforms. The deal would make Ottawa more than a supporter of Canadian AI. It would make the federal government a shareholder in one of the country’s most valuable private technology companies, at a time when Canada is pushing for greater digital sovereignty and Cohere is expanding deeper into Europe and global enterprise markets.
The government says the investment will be made in stages. Cohere must keep its Canadian incorporation and headquarters, create at least 1,000 new Canadian technical jobs by 2030, and commit at least C$1.7 billion to additional computing infrastructure in Canada. Cohere is entering the deal from a much stronger position than it occupied two years ago. Its Series E is targeting up to C$7 billion at a stated C$35.7 billion valuation. Schwarz Group leads the round. NVIDIA, Bell Ventures, Inovia Capital, Prosperity7 Ventures and other investors are participating. Cohere says its annual recurring revenue grew 165% year over year in the third quarter of 2026 and its customer base expanded twentyfold to about 300 customers.1
Ottawa calls this a sovereignty investment. Prime Minister Mark Carney says Canada needs the ability to build, adopt and govern AI on its own terms, while taking equity lets Canadians share in Cohere’s success if the company keeps climbing.
The sovereignty case and the investment case aren’t the same thing. Canada can value domestic AI capacity even if Cohere never becomes a great financial investment. It can also make money if Cohere becomes a much larger global company. Ottawa is now trying to do both.
What follows is a story of a Canadian AI company finding a different lane, moving closer to government, crossing the Atlantic for scale, and returning to a cap table where Canada itself now wants a seat.
By early 2024, Reuters reports Cohere’s annualized revenue has climbed from about US$13 million to roughly US$35 million by the end of March. The company is growing, but the numbers also show how far it sits from the largest US AI platforms.2
Cohere leans into control instead of reach. Its pitch increasingly centres on private deployment, data security, cloud choice and enterprise customization. The company can compete without needing to win the consumer chatbot popularity contest.
The customer list gets heavier. Cohere names RBC, TD Bank, Bell, Fujitsu, PwC and other large organizations among customers. Private deployment gives the company a route into sectors where security, residency and compliance can block consumer oriented tools.
The scale gap hasn’t disappeared. Anthropic reported US$16.29 billion of revenue in the first half of 2026 in its IPO filing, while OpenAI and other US platforms remain far larger in consumer reach and capital commitments.5 Cohere is trying to win a different buying decision.
The C$240 million support is not the same as today’s equity. Federal records describe the earlier deal as a contribution tied to compute expansion. Ottawa gets economic and strategic benefits if the project succeeds, but it does not participate in Cohere’s valuation the way a shareholder does.
Cohere keeps raising privately. In August 2025 it raises US$500 million at a US$6.8 billion valuation. Cohere Raises $500M at $6.8B for Enterprise Agentic AI shows a company still relying on venture, pension and strategic investors while government support sits outside the cap table.
Europe offers customers, public sector relationships and a policy environment that already prizes data control and local infrastructure. Cohere gains another route to market without having to imitate the consumer led strategies of the largest US firms.
Europe also brings competition. France’s Mistral is raising billions around a European AI champion of its own. US platforms are selling aggressively into the same enterprise accounts. Sovereignty creates demand, but it doesn’t hand Cohere the market.
Something could go very right. If Cohere turns its enterprise and sovereign AI position into a much larger global business, Canada participates in the appreciation instead of collecting only jobs, tax revenue and infrastructure benefits. A future valuation above C$35.7 billion would make equity look very different from another contribution.
The same structure exposes taxpayers to the downside. A private valuation can reset. New rounds can dilute shareholders. Compute spending can consume capital quickly. Cohere may deliver strategic benefits to Canada while still producing a weak investment return. Sovereignty doesn’t erase price.
Canada’s new Canada Launches $1.75B Venture and Growth Capital Plan mostly uses public money to attract private investors through funds and managers. Cohere is a far more concentrated position in one company.
The price is already much higher than it was last year. Cohere raised at a US$6.8 billion valuation in August 2025. The new round points to C$35.7 billion after a year of product growth, acquisitions, European expansion and the Aleph Alpha combination. Ottawa is buying after the story has already moved.
Cohere gives Ottawa a rare chance to test two ideas at once.
The first is strategic. Canada wants more control over the AI systems that governments, banks and other critical organizations may eventually depend on. Cohere’s architecture, Canadian roots and Europe strategy fit that ambition better than handing every sensitive workload to a foreign hyperscaler or consumer AI company.
The second is financial. Instead of paying only for infrastructure, research or jobs, Ottawa wants equity. If Cohere becomes one of the few globally important enterprise AI companies outside the United States and China, taxpayers own part of the upside.
The company has earned a stronger hand than it had two years ago. Revenue has grown, the customer list has widened, North has moved into production environments, European expansion is real, and Schwarz Group has put capital and infrastructure behind the transatlantic strategy.
There is still plenty the public can’t see. Cohere doesn’t disclose net profit or cash burn. Ottawa hasn’t published the ownership percentage or shareholder protections. Nobody outside the deal can yet judge whether C$35.7 billion is an attractive entry price for taxpayers.
Canada may be right about the strategic asset and still have to prove it bought the asset well.
The investment becomes more interesting if Cohere keeps compounding from here. It becomes more difficult if the company needs repeated public support, the valuation falls, or strategic goals start masking weak investment performance.
Cohere has spent seven years trying to prove a Canadian AI company can scale without becoming another US platform. Ottawa has now put C$1.6 billion behind the next chapter.
If Canada wants to become an owner of national champions, Cohere will help show whether it can act like one.
The government has announced an equity commitment of up to C$1.6 billion, but it hasn’t disclosed the ownership percentage, share class, voting rights, board rights, liquidation preference, dilution protections or exit terms. Those details are needed before the investment economics can be judged properly.
Cohere reports rapid ARR and customer growth, and Reuters has reported strong margins around its private deployment strategy. The company does not publicly disclose net income, cash burn or complete financial statements, so profitability cannot be confirmed from public information.
Ottawa says the equity will be invested in stages with regular reporting on jobs and Canadian investment. The public announcement does not disclose the consequences for missed milestones or whether later stages can be withheld.
Ottawa has not said the Cohere structure will become a standard program. The Canada Strong Fund does point in the same direction by making commercial equity ownership a larger part of federal economic policy. Cohere may become an early test of how those strategic and financial objectives work together.
Budget 2025 Accelerates Fintech, AI, and Capital Growth
How federal AI infrastructure and growth capital policy started converging before direct Cohere equity arrived.
Canada Adds Competitiveness to Federal Regulation
A wider look at Ottawa’s push to put competitiveness more directly into federal economic and regulatory decisions.
National Security Is Now Part of Financial Supervision
Why sovereignty, infrastructure control and national security are moving deeper into financial and technology policy.
Why AI Investment Is Missing What Workers Actually Want
A reminder that capital and technical capability still have to translate into adoption, useful work and measurable outcomes.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
October 28, 2026 | NCFA Market Activity | Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Competition And Market Structure
Wealthsimple's C$13.8 Billion Valuation Backs Expansion Into Banking, Credit and Business Finance
On October 27, 2026, Toronto fintech Wealthsimple announced a C$425 million financing agreement at a C$13.8 billion post money valuation. Singapore sovereign wealth fund GIC is leading the round, with Power Corporation, IGM Financial, ICONIQ, CPP Investments and Inovia participating. Wealthsimple will receive C$300 million in new capital, while up to C$125 million will be used to purchase existing shares from eligible employees.
The valuation is 38% above the C$10 billion reached in Wealthsimple's October 2025 financing. Since then, Wealthsimple has expanded further beyond investing into chequing, spending, credit and business finance. With more than four million customers, Wealthsimple already has a large base of Canadians using its platform. Building that kind of reach is much harder than launching another financial product.
Wealthsimple reported C$169.2 billion in assets under administration as of September 30, 2026, up from C$100 billion at its October 2025 financing. That's an increase of C$69.2 billion, or 69%, in less than a year. The increase includes both market appreciation and new money entering the platform, so it can't be treated as a direct measure of market share gained from competitors.
Separate transfer data provides clearer evidence of competitive movement. Wealthsimple recorded the highest number of account transfers in the company's history during Q1 2026. It has also told Finance Canada that customers are moving investment accounts from other financial institutions and that record transfer activity shows Canadians are actively shopping for value. Wealthsimple doesn't disclose which institutions are losing those assets, so the public data can't show how much is coming specifically from Canada's major banks. But the direction of travel is clear. Some investment assets are moving from incumbent financial institutions onto Wealthsimple's platform.
For Wealthsimple, every account transferred onto the platform can become more than an investment relationship. A customer who already holds investments there can add chequing, credit or business services without Wealthsimple having to win that person from scratch. The larger the asset and customer base becomes, the more products Wealthsimple can build around relationships it already owns.
The new financing gives Wealthsimple C$300 million of fresh capital to keep building that model. The separate secondary component gives eligible employees a chance to sell up to C$125 million of existing shares while Wealthsimple remains private.
Existing shareholders are also putting in more money. IGM Financial is investing another C$96 million and expects to retain a 25.1% interest after closing. Power Financial is contributing C$68 million, bringing the Power group's combined participation to C$164 million. GIC, which helped lead Wealthsimple's C$750 million financing last year, is leading this round.
GIC managing director Vinay Yarlagadda pointed to Wealthsimple's customer focus and pace of product development as qualities the investor sees in exceptional companies globally. That view now comes with another large commitment of capital from GIC and several major Canadian institutional investors.
The size of the round also stands out in Canada's fintech market. KPMG's Canadian fintech funding data showed US$996.7 million invested across 47 deals in the first half of 2026, compared with about US$1.7 billion across 82 deals a year earlier. Wealthsimple's financing comes later in the year, but it reinforces a clear shift toward larger pools of capital concentrating around companies that have already reached meaningful scale.
The strongest sign that Wealthsimple is becoming more than an investment platform came in the second quarter of 2026. New chequing account openings surpassed investment account openings for the first time, while the company reported approximately C$17 billion in quarterly net inflows.
Chequing changes how often a customer can interact with Wealthsimple. Investing may involve periodic contributions and trades. A chequing account can be at the centre of payroll deposits, bills, transfers and daily spending. Once that activity moves onto the platform, Wealthsimple has more opportunities to connect investing, saving and credit around the same customer.
The company says it launched more than 50 products over the past year. Its May 2026 product expansion added business chequing, portfolio credit and family services. Wealthsimple has also expanded into options, futures, selected IPO access and cash deposits through more than 5,300 Canada Post locations.
Wealthsimple already serves more than 30,000 businesses. Business chequing gives it a base from which it could add more payments, cash management and credit services over time. The firm isn't a chartered Canadian bank. Its chequing services use financial institution partners, while Wealthsimple owns the digital relationship and provides the surrounding products. That structure lets it broaden its financial offering without building a traditional branch network.
Canada's incumbents are responding. BMO introduced zero commission trading through InvestorLine in September 2026, joining other Canadian providers that had already eliminated standard stock and ETF commissions. Low cost trading helped fintech companies attract investors. As that feature spreads, competition moves toward which provider can offer customers the most useful combination of investing, cash, credit and service.
KOHO is taking another route and is working towards becoming a bank. It has more than 2.5 million customers and is pursuing a Canadian bank licence as it expands its consumer financial offering.
Wealthsimple is expanding through its existing regulated businesses and financial institution partnerships. Both are trying to capture more of the customer relationship that has historically belonged to Canada's large banks, but they're using different structures to get there.
Two global fintech companies offer useful comparisons because they've already pushed further into the same convergence of investing, banking, payments and credit.
Revolut reported 68.3 million retail customers and 767,000 business customers at the end of 2025. Annual revenue reached US$6 billion, with 11 product lines each generating more than about US$135 million. Revolut Business accounted for 16% of total income. Revolut started in foreign exchange and payments and has since expanded across banking, investing, lending and business services. Its scale is far larger and its regulatory structure differs from Wealthsimple's, but the commercial lesson is relevant. One customer relationship can support several meaningful revenue streams when the products connect naturally.
Robinhood provides a closer comparison to Wealthsimple's investing roots. It reported 28.7 million funded customers and US$396 billion in platform assets in the third quarter of 2026. Quarterly revenue reached US$1.4 billion and Robinhood Gold subscriptions climbed to 5.2 million. The company said 14 business lines had reached at least US$100 million in annualized revenue. Robinhood has moved from trading into retirement products, subscriptions, cash management, credit cards and banking services. Wealthsimple is following the same broad logic in Canada, using its investment customer base to introduce services people may use more frequently.
The three companies have different market sizes, banking arrangements and product offerings. What they share is a strategy of earning more from customer relationships by connecting several financial services. Revolut shows the potential scale of everyday banking and business finance. Robinhood shows how an investing platform can expand into credit, cash and subscription products. Wealthsimple is bringing parts of both models into the Canadian market.
The Canadian market has its own dynamics. A small number of large banks already have deep relationships across deposits, mortgages, credit cards, investments and business finance. Wealthsimple's four million customers and C$169.2 billion in client assets give it enough scale to compete for more of those relationships one product at a time.
CEO and cofounder Michael Katchen summed up the strategy in the financing announcement, saying Wealthsimple plans to keep building until "every Canadian can live their entire financial life on Wealthsimple." The numbers behind this round show that investors are funding that broader financial services strategy, not simply another expansion of its trading business.
Wealthsimple's next phase seems to be how much of a customer's financial life it can pull away from incumbent institutions. Record account transfers show that movement has already started.
If chequing, credit and business services accelerate it, Canada's banks won't just be competing with Wealthsimple for new customers. They'll increasingly be competing to keep the assets and financial activity of customers they already have.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 28, 2026 | NCFA Story Intelligence | Regulation And Policy, Digital Assets Blockchain And Tokenization, Competition And Market Structure, Capital Markets Infrastructure And Funding
Binance thought it was leaving Canada in 2023. The regulatory fight stayed behind.
Binance never entered Canada the way a bank or securities dealer would. It didn’t open a Canadian branch, build a local exchange or wait for a Canadian licence. Changpeng Zhao was a Canadian entrepreneur who had studied computer science at McGill, but Binance launched in Shanghai in July 2017 and grew into the world’s largest crypto exchange by trading volume within about six months. The product was global from the start. Borders came later.
By 2021, Canadian regulators were catching up with what that model meant on the ground. Ontario pushed Binance out. Binance hired former regulators, incorporated in Alberta and tried to build its way back in. Then Canada tightened the rules again. On May 2, 2023, Binance told securities regulators it planned to withdraw nationally.
Eight days later, the OSC opened an investigation. The next day came a sweeping demand for company records. On May 12, Binance told the public it was leaving Canada.
The exit and the investigation crossed in real time. Binance was trying to close one Canadian chapter while the regulator was opening another.
Three years later, that unfinished business has reached the Supreme Court of Canada. Ontario’s Court of Appeal has already ruled that part of the OSC summons went too far. The OSC wants that ruling overturned. Nine interveners now include civil liberties groups, securities regulators and four governments.
What follows is a story of a borderless crypto company meeting national regulators, leaving some markets, adapting in others, and discovering that a market exit doesn’t make the regulatory past disappear.
Ontario treats access as local activity. The OSC’s position is that platforms offering securities or derivatives to Ontario users can’t avoid provincial rules simply because the company or servers sit somewhere else. For internet based finance, the customer’s location can pull a global platform into a local regulatory system.
Binance starts planning a return. By early 2022, Binance is doing something that would have looked unlikely months earlier. It hires former Canadian regulators, incorporates in Alberta and starts building toward full registration. Binance hires ex-regulators and incorporates in Alberta to charter compliance course in Canada catches the pivot. A few months later, Alberta-based Binance Canada expects to return to Ontario by 2024 shows how far the strategy has moved. The company isn’t talking about abandoning Canada. It is talking about coming back to Ontario through the front door.
The OSC gets enforceable controls. The undertaking turns account restrictions, product wind downs and monitoring into commitments the regulator can supervise. Binance is no longer only deciding what Ontario access should look like on its own.
Binance still sees a Canadian future. The company pursues registration outside Ontario and talks publicly about returning. That makes the national exit in 2023 more than a market withdrawal. It ends an attempted compliance strategy.
Binance blames the rule set, not Canada itself. The company says it delayed the decision while looking for another route and hopes to return someday. Canada is a relatively small market for Binance, but the evidence doesn’t establish that size alone drove the exit. The company’s own explanation focused on the rule set and the product limits that came with it.
Other platforms make a different calculation. Some exchanges also leave, while others pursue Canadian registration and accept narrower product menus. Every platform has to decide whether the local opportunity justifies the controls, product limits and ongoing supervision required to stay.
Regulators need records to reconstruct the past. Cross border platforms can spread staff, systems and legal entities across several countries. Without compulsory powers, investigators may struggle to establish who made a decision, which controls existed and what customers were told.
Broad demands carry real operating costs. A request covering years of email, chat, files and other communications can trigger preservation, data collection, legal review, privilege screening and cross border privacy work. A global exchange can spend heavily on that process. A smaller fintech may feel the same demand much more sharply.
The ruling protects relevance, not secrecy. The Court accepts that regulators have strong production powers and that privacy expectations for regulated business records can be low. It still requires a reasonable basis to believe compelled records may matter to the investigation.
The OSC sees a wider enforcement problem. The regulator argues that the Court of Appeal’s approach could make investigations slower and more difficult, particularly before investigators know exactly where useful evidence sits. Binance answers that regulators have had relevance limits for decades and can draft demands around the conduct they are actually investigating.
Investor protection still needs effective investigations. Regulators can’t police complex markets without access to records. Cross border digital businesses make that harder because relevant evidence may sit across entities, employees and systems that don’t line up neatly with one province.
Constitutional limits still matter inside regulated markets. Laura Paglia of the Canadian Forum for Financial Markets told Advisor.ca that securities regulators need broad powers, but argued that demands should remain proportionate and consider compliance costs. CFFiM was denied intervener status, so its view is industry commentary rather than a submission the Supreme Court will hear.14
Binance has already tried several endings in Canada.
First it left Ontario. Then it hired regulators and built an Alberta operation that was supposed to bring it back. Then it accepted an Ontario undertaking. Then it decided the national rules were no longer worth the trade and left Canada altogether.
The legal history kept going.
FINTRAC imposed a penalty tied to the years Binance operated here. Investors pursued a separate class action. Ontario courts rejected Binance’s attempt to force those investors into costly Hong Kong arbitration, a dispute later followed by Ontario Court Orders Binance To Pay Investor Legal Costs. The OSC kept investigating. The company that left Canada in 2023 is still litigating here in 2026.
Binance changed too. Zhao stepped down. A board arrived. Local licences and compliance teams became part of the growth strategy. Japan went from warning Binance to hosting a locally registered Binance business. Abu Dhabi became a regulated global base.
The Supreme Court case is now much bigger than Binance.
The Court is being asked to decide where constitutional limits sit when a regulator with legitimate investigative powers demands a very large volume of company records. A ruling that gives regulators wider latitude could make it easier to investigate complex businesses whose people, systems and data span multiple entities and countries. A ruling that requires a tighter connection between requested records and suspected conduct could force regulators to narrow summonses earlier and give companies stronger grounds to challenge sweeping demands.
Either way, the decision could shape how securities regulators design investigations, how regulated firms preserve and produce records, and how much compliance cost companies may face when regulators come looking for evidence. Depending on how broadly the Court reasons, its impact could also reach beyond capital markets into other regulated sectors that rely on statutory production powers.
That helps explain why governments, another securities regulator and civil liberties organizations have joined a dispute that began with one crypto exchange. The precedent could influence the balance between effective supervision and protection against regulatory overreach across Canadian business.
Binance spent years learning that global reach doesn’t erase national borders. Canada’s highest court is now deciding where one of those borders sits for regulators themselves.
Once a regulator has authority to investigate, how much of a company can it force open?
Binance left Canada. The company moved on. The answer could matter to regulated businesses long after this case is over.
INVESTOR GUIDE
7 Questions to Ask Before Choosing a Crypto Exchange in Canada
A current guide to registration, custody, transfers, funding, fees and operational risks Canadian investors should check before sending money to a crypto platform.
FINTECH INTELLIGENCE
Are Regulators Opening Markets While Raising Costs?
Market access can improve while evidence, records and supervision requirements get tougher, changing the economics for both incumbents and smaller entrants.
REGULATORY INSIGHT
Canada Proposes Stablecoin Market Entry Rules
Canada’s new stablecoin proposal shows how market access can depend on local custody, supervision and operating requirements, even when the underlying product is global.
REGULATION AND POLICY
National Security Is Now Part of Financial Supervision
Financial supervision is expanding beyond traditional capital and conduct questions into sanctions, cyber threats, ownership and state linked risk.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 27, 2026 | NCFA Market Activity | Competition And Market Structure, Artificial Intelligence And Data, SME Finance And Business Banking
Canadian Fintech Expands Bank Pricing, Customer Offers and Compliance
On October 26, 2026, Toronto banking technology company Zafin signed a definitive agreement to acquire Naehas, a California software provider that helps banks manage customer offers, disclosures and marketing compliance. The purchase would expand Zafin's existing banking product and pricing business, giving it more technology to sell to major financial institutions. The transaction is expected to close in the fourth quarter of 2026, subject to regulatory approvals and customary conditions.
A Zafin spokesperson told BetaKit the company agreed to pay a nine figure sum in US dollars, using cash and equity with partial financing from a credit line. Naehas brings approximately 250 employees and US$30 million to US$50 million in annual revenue, according to the spokesperson. Zafin is making a substantial investment to expand its US banking business, adding established customers and software capabilities rather than building everything internally.
Zafin helps banks manage financial products, interest rates, account fees, billing and customer pricing without replacing their entire core banking systems. Naehas handles the next area of the business. Its software helps banks prepare customer offers, manage disclosures, secure approvals and deliver communications that meet regulatory requirements.
Consider a bank launching a new savings account promotion. Zafin's technology can manage the interest rate, account terms and customer eligibility. Naehas can help prepare the offer, approve the disclosures and deliver the correct information to customers. Banks often handle these activities across separate departments and systems. Connecting them could shorten the time between deciding on a product and bringing it to market.
Rab Govil, Naehas founder and CEO explained the business opportunity in the acquisition announcement.
"The cost and time required to execute an offer determine how many growth opportunities an institution can pursue."
Naehas has built its business around reducing that work. Banks need to compete on pricing and respond quickly when customer needs change, but they can't ignore disclosure requirements or approval controls. For Zafin, acquiring an established provider is also a way to expand into related banking operations with existing software and customer relationships.
The acquisition could allow Zafin to sell more services to banks already using its technology. Instead of competing only for product and pricing software budgets, Zafin could pursue spending on customer offers, marketing operations and compliance. Selling additional products to established customers may also be less costly than winning new banks, where purchasing decisions and technology implementations can take considerable time.
Bank customers could benefit from closer coordination between pricing and sales. A business client using deposits, loans and payment services may qualify for better terms based on the overall relationship. Zafin can support that pricing, while Naehas can help deliver the offer and associated documents. Better coordination could help banks win more business from existing customers while reducing the work needed to launch each offer.
For Zafin, the economics depend on how much additional software banks buy and how well the companies combine their operations. A broader product range could strengthen customer relationships and make Zafin harder to replace. Banks may also prefer to work with fewer suppliers, although they'll expect competitive pricing and dependable integration with their existing systems. If the products remain difficult to connect, some of the acquisition's value could be lost.
Zafin is also investing in artificial intelligence. Its AIOS platform is designed to coordinate AI agents and oversee their work, while Zafin IO connects banking systems. Integrating Naehas could eventually extend AI automation into customer offers, disclosures and approval processes.
Nordic Capital's investment in Zafin dates to 2024, when the private equity firm acquired a majority stake to support international growth. Nordic Capital reports that Zafin generated €110 million in revenue in 2025. The planned Naehas acquisition would add an established US banking software business, giving Zafin more products to sell and additional institutional customers to serve.
According to figures provided by Zafin to the media, the combined business is expected to serve 16 of the 20 largest US banks. Zafin is also targeting US$200 million in annualized recurring revenue by the end of 2026. The acquisition gives Zafin more opportunities to sell software to major banking groups, where an existing customer relationship can be valuable in winning additional contracts.
Banks are investing in new technology to compete, but they're taking different approaches. Tangerine's launch of business banking on Starling's core technology shows one approach, building new products on a modern banking platform. Zafin takes another, helping institutions improve pricing and product management around existing core systems. Adding Naehas could give banks more ways to update customer offers without replacing their underlying banking infrastructure.
For Canada's fintech industry, Zafin shows how a domestic enterprise software company can expand internationally through acquisitions and established banking relationships. Can Zafin turn Naehas's customer relationships and technology into enough additional business to justify the purchase and compete for larger banking software contracts?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 26, 2026 | NCFA Market Activity | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization, SME Finance And Business Banking
On October 26, 2026, Atlanta based trade finance company PrimeRevenue announced plans to tokenize trade finance assets on Solana, bringing its Electronic Time Drafts (ETDs) to blockchain capital markets. These instruments represent corporate buyers' obligations to pay suppliers on agreed future dates and can be financed to provide suppliers with earlier cash. PrimeRevenue aims to expand beyond its established bank funding network by connecting these obligations with additional institutional and eligible blockchain investors.
PrimeRevenue reports 50,000 companies using its platform, more than 100 funding partners and over US$300 billion in annual payment transactions. That established network gives the company a strong starting point for bringing corporate payment obligations to new investors. Rather than building a financing market from scratch, PrimeRevenue can extend its existing relationships, financial instruments and distribution capabilities into blockchain capital markets.
When a corporate buyer owes a supplier money, the supplier may have to wait 30, 60 or 90 days for payment. PrimeRevenue's Electronic Time Draft allows the buyer's payment obligation to be transferred to a financing bank at a discount. The supplier receives cash early, while the bank collects the full amount from the buyer when payment comes due. Financing terms reflect factors including the buyer's credit rating and the remaining payment period.
For example, a supplier owed US$100,000 in 90 days could exchange the draft for an earlier discounted payment. A smaller supplier working with a financially stronger corporate customer may secure more attractive financing than borrowing against its own credit. The buyer retains the agreed payment date, the supplier receives working capital and the bank earns a return for providing the funding and assuming the buyer's payment risk.
ETDs aren't ordinary digital invoices. PrimeRevenue's patented process creates and signs a time draft electronically, supports its transfer to the financing bank and arranges collection at maturity. The company says the structure also removes certain lien search and release requirements that can complicate conventional receivables financing.
Over time, tokenized ETDs could support a continuously replenishing working capital market. Corporate buyers generate new payment obligations, suppliers receive early financing, and investors recover capital as drafts mature. That money could finance the next round of transactions, potentially giving suppliers more flexible access to funding without relying on a single lender. Each draft would still carry its own credit risk, but the financing network could operate more like a revolving pool of capital.
In 2018, PrimeRevenue reported US$1.78 billion in ETD financing, helping nearly 1,000 suppliers across 13 countries get paid early. The program involved 14 banks and more than 100 corporate buyer programs, showing that ETDs were already being used internationally well before the Solana initiative.
PrimeRevenue currently connects corporate payment obligations with established funding institutions. Tokenization could allow other eligible investors to finance or acquire interests in those obligations, depending on how the legal structure is implemented. Solana would provide a shared record of issuance, transfers and settlements, while PrimeRevenue continues supplying the corporate relationships and transaction activity.
PJ Bain PrimeRevenue CEO described the intended expansion in the company's announcement:
"It creates new pathways to unlock working capital and liquidity for our customers and funding partners."
A bank might gain another way to distribute its exposure instead of holding every draft until maturity. New investors could gain access to corporate credit with defined payment dates. Suppliers could benefit if competition among funding providers improves pricing or financing availability. None of these benefits is established until investors commit capital and completed transactions demonstrate the economics.
PrimeRevenue still needs to clarify what investors would actually own, how they would receive payments and what happens if a corporate buyer fails to pay. Holding a token on Solana doesn't automatically give an investor the legal right to collect the underlying debt. Investors would also need to consider whether they could sell their holdings before payment is due.
The bigger opportunity is bringing more investors into trade finance, not simply processing transactions faster. PrimeRevenue already connects corporate buyers, suppliers and banks. Tokenization could open that network to additional investors, giving suppliers access to more funding options and potentially better rates.
Unlike Fission's tokenized fund liquidity model, which helps investors access cash from existing fund holdings, PrimeRevenue is bringing corporate payment obligations to new funding markets. Both use tokenization to connect financial assets with capital, but they serve different financing needs.
Canadian businesses face similar working capital pressures. Payments Canada's 2026 research found that 37% of surveyed small and medium businesses consider payment delays a significant problem. Recent Canadian SME financing initiatives are expanding access to smaller loans and more flexible supplier payments. Tokenized ETDs could offer another option, especially for suppliers selling to large, creditworthy corporate customers.
Canadian banks, commercial lenders and financing platforms could eventually use similar models to connect corporate payment obligations with a wider pool of investors. This could give suppliers more financing choices while opening new opportunities for lenders and financial technology providers.
PrimeRevenue describes the Solana initiative as its first step toward decentralized finance (DeFi), connecting traditional trade finance with new blockchain funding markets.
PrimeRevenue already has the corporate customers, financing network and bank relationships to bring trade finance assets to new investors. Solana could help attract more capital and give suppliers better financing options. Can PrimeRevenue turn tokenized trade finance into a larger, more competitive funding market that delivers real value to businesses?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 17, 2026 | Last Updated: Oct 30, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Competition And Market Structure, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Identity And Trust, Embedded Finance, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, Sustainable Finance ESG And Financial Inclusion, Digital Banking And BaaS, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading, Open Banking Open Finance And Data Sharing

] Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-March 13, 2026, March 14-March 20, 2026, March 21-March 27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-June 12, 2026, June 13-June 19, 2026, June 20-June 26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-July 24, 2026, July 25-July 31, 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026, September 5-September 11, 2026, September 12-September 18, 2026, September 19-September 25, 2026, September 26-October 2, 2026, October 3-October 9, 2026, October 10-October 16, 2026).
Sezzle is trying to move from distributing credit through banking partners toward owning a federally supervised banking platform. If approved, that would give it more control over deposits, credit products, funding and customer economics. The next signals are OCC and FDIC decisions, capital requirements and how much of Sezzle's current partner model eventually moves inside the bank.
Mortgage technology only earns its place when it improves underwriting, servicing and broker economics. NORTHGUARD has acquired an operating base rather than starting with software alone. Founders and capital partners should watch how quickly it expands beyond Quebec, how it funds mortgages and whether faster decisions translate into stronger loan performance.
Ramp is seeking direct control over regulated investment and custody capabilities rather than relying entirely on external providers. Following its recent funding and expansion, the charter application adds another route for the company to broaden its financial services business. The key tests are OCC approval, which capabilities Ramp brings in-house, and how the new entity would work alongside existing bank partners.
SoFi is testing whether customers will keep digital dollar balances at a bank until they need to transact. The split between an insured deposit and a transferable stablecoin is commercially important because the legal protections change at conversion. Banks and fintechs should compare yield, redemption terms and access rather than treating both tokens as the same product.
Banks are starting to offer controlled data access where customers already work with AI, rather than forcing every question back into a banking app. Finom’s read-only design keeps the risk boundary relatively clear. The test is whether business owners use it routinely and whether future payment permissions can be added without sacrificing that control.
A bank can now test whether AI cuts investigation costs without losing control of the decision trail. Starling’s approach also raises the bar for vendors that sit outside the banking core. But speed isn’t enough. Compliance teams still need to know when a decision should be challenged, who owns an error and whether the economics hold across higher risk cases.
AI risk is moving from broad supervisory concern into bank level remediation work. The practical question is no longer whether banks recognize the threat. It's whether they can show the ECB who owns the risk, what systems need investment and how quickly controls can change as models become more capable. NCFA first tracked the supervisory direction in ESRB Warns Frontier AI Models Could Strain Cyber Resilience. The October action plans turn that warning into an execution deadline.
The FCA has made current obligations easier to test against real deployment patterns without creating a separate AI rulebook. Firms can compare their controls with concrete supervisory examples before weak ownership, monitoring or vendor dependence becomes an operating problem. NCFA has been tracking the same AI governance and compliance costs as financial institutions move from experiments into live workflows.
This expands the market infrastructure available for event driven securities products before the products themselves reach investors. The commercial test is whether Cboe and Robinhood can turn the new clearing authority into meaningful trading volume while keeping the risk, margin and settlement controls expected of regulated securities markets.
Private credit is becoming too large for market data firms to treat as a side business. LSEG is paying for proprietary information, workflow and distribution in a market it estimates at US$3.5 trillion. Investors should watch whether the deal improves pricing and risk visibility in less liquid credit or simply concentrates more valuable data inside one platform. The commercial upside depends on cross selling without weakening the specialist product customers already pay for.
Fund managers have a new capital application window, but founders still need to meet the investment criteria of the funds receiving public commitments. The capital won’t necessarily reach businesses outside the venture model. The immediate tests are which managers apply, how they attract pension and private capital, and whether founders beyond established funding hubs gain access.
This separates collateral custody from the funding used on a derivatives platform. Traders can keep crypto exposure while obtaining dollar margin, but the convenience comes with another lender, security interest and liquidation process. Custodians and brokers should watch collateral valuation, loan terms and who can act when markets gap outside banking hours.
French managers seeking US advisory access have a clearer supervisory cooperation arrangement behind their applications. The practical question is how registration processing, compliance preparation and ongoing examination responsibilities operate under the memorandum. Asset managers expanding internationally should distinguish the renewed application pathway from permission to begin serving clients without SEC registration.
Malaysia has moved tokenized fixed income into core market infrastructure rather than leaving it in a pilot. That matters because issuance, ownership records and settlement now sit inside infrastructure controlled by the central bank. NCFA previously tracked the earlier groundwork in Bank Negara Malaysia Onboards Ringgit Stablecoin And Tokenized Deposit Pilots. The next test is issuance volume and whether banks, governments and corporate borrowers start using the new rails regularly.
Mobile wallet providers and fintechs could gain more control over how contactless services reach iPhone users. Fees, available technical methods and contractual access are the practical questions. Firms considering wallet or account-based payment products should examine the consultation now, rather than planning around terms that have not yet been finalized.
Western Union already has customer distribution and cash access. The harder work is fitting a stablecoin rail into local payout rules, liquidity and customer support. Noah gains an important infrastructure role, but both firms still need to show where customers can actually use the service and whether fees fall without making redemption harder.
Cross border card programs become expensive when every new country needs another bank relationship and operating stack. Newline is using Fifth Third's balance sheet and Visa's network to give fintechs one route into more than 40 markets. The opportunity is meaningful for software platforms serving global employers and businesses. The real test is whether local authorization and issuing reduce fees and failed transactions enough to justify the added compliance work.
Fiserv is selling fewer integrations as a cross border growth advantage. Large merchants can add local payment methods without rebuilding settlement, reporting and operational controls market by market. The commercial test is whether that consolidation lowers total payment costs and speeds expansion enough to outweigh the value of using specialized providers in individual countries.
Cross-border digital money won’t scale if every bank has to negotiate a different settlement and compliance arrangement in every market. BLOOM puts three central banks at the table with the providers building those connections. Operators should follow the actual commercial agreements, supported assets and settlement rules, not just the growing participant list.
Stablecoin payments are being fitted into existing institutional fraud and compliance operations rather than treated as a separate risk channel. Banks and payment providers will need to test whether the combined intelligence improves decisions across conversion, transfer and payout stages, and how responsibility is divided between partners when a suspicious transaction is held or rejected.
Agent-driven commerce needs a way to recognize authorized software without giving fraudsters a free pass. Identity signals that enter the merchant’s existing risk engine offer one practical approach. The next test is whether checkout performance holds across more merchants, higher transaction volumes and contested payments, where evidence of the human mandate matters as much as recognizing the agent.
Loan participation payments are still full of reconciliation work after the money arrives. Moving the payment and loan records together attacks that operating cost directly. Banks should care less about the token label than whether the process shortens settlement, reduces exceptions and keeps every participant on the same loan balance. Repeat volume across more institutions would turn this from a useful transaction into infrastructure.
Institutional settlement now has another bank deposit option on a public blockchain where tokenized assets already trade. Treasury and digital asset teams can compare the legal claim, eligible counterparties, network access and liquidity against stablecoin-based settlement. The commercial test is whether institutions use the additional network for regular transactions, not simply as another technical connection.
Revolut now has another regulated entity it can use to expand crypto services without relying on one licensing base for every market. The value will come from where the Gibraltar permission actually opens distribution, custody and staking at scale. Investors should watch which markets are added, how quickly customers migrate to the new entity and whether regulatory expansion improves revenue without adding disproportionate compliance cost.
Switzerland already had deep crypto infrastructure, but retail fund approval changes distribution. Wealth platforms and advisers can now offer Bitcoin through a supervised investment product instead of pushing every customer toward direct ownership. The advantage is easier custody and familiar fund controls. The risk doesn't disappear, and competing providers will still have to win on fees, liquidity and investor trust.
Failed cross border payments are expensive because the bank or fintech still absorbs investigation, repair and customer service costs. Connecting verification across bank accounts and wallets gives institutions a chance to catch bad recipient data before funds leave. The value will show up in lower exception rates and fewer fraud losses. Adoption will depend on how much coverage Liink participants can use without adding another slow step to the payment flow.
Payment providers can’t afford a different wallet authentication arrangement for every country or partner. A common set of rules could lower integration costs and clarify liability. The industry now has time to shape those rules, but firms shouldn’t treat a published development plan as a completed authentication standard.
Financial identity checks are extending beyond onboarding into agent interactions, remote approvals and sensitive communications. Firms considering these tools need to test exactly which facts a proof establishes, what data must be retained and who accepts liability if a verified participant still gives fraudulent instructions. Design-partner use is an early distribution step, not proof of broad institutional adoption.
AI assistants are moving from advice into execution inside everyday business software. Stripe gives Claude access to payment and commerce tools while keeping the owner at the approval point. For founders, that can cut routine admin without handing an agent open ended spending authority. The commercial question is whether customers trust the controls enough to move real purchasing and finance work into the interface.
Stablecoin adoption is moving into a bank's existing retail distribution rather than asking customers to adopt a new crypto wallet. That cuts a major onboarding barrier. The numbers to watch now are wallet activation, payment frequency and merchant usage. If customers use RedCoin for ordinary transactions, regulated stablecoins start competing as payment products rather than mainly trading and settlement tools.
Payment margins can depend on who controls the local acquiring relationship. Nuvei can now bring more of that work inside its own network instead of paying intermediaries. Merchants should compare actual approval rates and processing costs after implementation. For Canadian payment firms, the licence shows how regulated local access can strengthen international distribution.
Agents that buy software services need spending limits that survive across multiple suppliers. Mastercard is testing a way to approve a budget once without granting open access to company funds. The commercial question is whether developers and merchants adopt one shared payment method instead of creating another patchwork of wallets, credits and billing accounts.
Euronet wants a larger share of the merchant relationship than payment processing alone. Connecting checkout, reconciliation and business software can improve retention and open new service revenue. Merchants will judge the platform on integration costs and daily usefulness. Competing payment providers should watch whether the Greece rollout turns Euronet’s distribution into a durable advantage.
Business payment automation is crossing a practical barrier: recognized agents can finish authorized transactions inside supplier portals without a person manually completing every step. Finance teams will need to define mandate limits, approval evidence and exception handling before using this model more widely. Successful pilot transactions are a useful milestone, but broad interoperability and dispute processes remain to be proven.
Card networks are designing agent payment protocols, but local bank account and wallet schemes can’t simply assume those rules fit. The council gives payment providers a place to settle the hard questions around mandates, identity and refunds before agents become another checkout channel. Its value depends on usable technical specifications and adoption by real payment schemes.
More official repo capacity gives market makers another liquidity buffer as Hong Kong builds deeper offshore RMB markets. The increase itself is modest, but the control point is important. Banks competing for RMB flows now have stronger public liquidity support behind market making, while exchanges, payment firms and treasury platforms get a deeper funding base for products built around offshore RMB.
Corporate treasurers leave cash idle when fund cut off times don't match when money becomes available. This transaction shows how tokenized bank money can connect that cash directly to an investment product without rebuilding the treasury stack around a stablecoin. The opportunity is better use of working cash. The business case will depend on redemption speed, fund access and whether the model scales beyond bespoke transactions.
The important shift isn't that an AI can read a balance. It can now carry out approved treasury work inside the financial account. Founders gain leverage if routine transfers and invoice payments move out of the admin queue without weakening controls. Banks and fintechs will need equally clear permission models because the competitive question is moving from who has an AI assistant to who safely lets it touch money.
AI and tokenization are no longer sitting outside the routine examination cycle. Firms using either in regulated workflows should expect questions about governance, supervision, records, controls and investor outcomes. For infrastructure providers, the combination of Treasury clearing and tokenization also puts implementation risk closer to the examiner's desk, not just the product roadmap.
Regulatory competitiveness now has explicit federal policy requirements, but better outcomes aren't automatic. Fintechs and investors should watch whether impact assessments, burden offsets and regulatory reviews actually reduce entry costs and approval friction. The same questions around OSFI's approach to growth and competition extend across federal regulation: will the new requirements make it easier for credible entrants to launch, scale and compete?
The final rule gives stablecoin issuers a clearer operating framework, but rewards remain a competitive fault line between banks and crypto platforms. Exchanges may still have room to pay customers when the reward isn't simply interest for holding a stablecoin, yet there is no blanket approval. Issuers and partners now need structures they can defend under OCC review. For banks, the deposit competition debate isn't settled just because the rule is final.
Crypto firms need to establish which activities require authorization and which qualify for exclusions before committing to licensing and operating structures. The distinction is particularly important for stablecoin payments, decentralized protocol interfaces and technical service providers. Firms affected by uncertainty over arranging permissions should engage with the FCA during the application window rather than assume that forbearance extends the application deadline.
Canada's existing restrictions can complicate fintech investments when a business combines financial services with other commercial activities. The proposed fintech investment reforms would give banks and insurers more room to invest, acquire and build technology businesses while retaining limits on their exposure. Fintech founders could gain access to strategic capital and established distribution networks. The commercial test is whether institutions use that flexibility to expand products and partnerships, rather than simply absorb promising competitors.
Hiring senior leaders can take months when every role requires an external approval. The UK is proposing to put more of that decision back on regulated firms without removing accountability. Boards and compliance teams should compare the proposed savings with the additional burden of documenting their own assessments before changing staffing or control plans.
Retail brokers now have a dated supervisory benchmark for scam controls rather than a general warning about fraud exposure. Firms should review the full guidelines and FAQs against their customer protection, escalation and operational processes, identify changes requiring development or vendor support, and budget the work ahead of June 2027.
A global crypto brand still needs effective controls inside its locally regulated payments entity. Reliance on a parent company doesn’t transfer accountability for safeguarding customer funds. Payment firms expanding into Europe should verify daily reconciliations, board visibility and the resources available to challenge a group service provider when problems appear.
Financial crime controls built around yesterday’s payment and customer patterns can miss risks introduced by agents, crypto products and new vendors. Firms should test whether their transaction evidence, staff escalation and sanctions processes still work across those channels. The consultation offers a chance to challenge unclear expectations before the final guide is issued.
A shared classification method could give issuers and capital providers a more consistent basis for assessing transition-finance claims. But the real allocation decisions will turn on sector thresholds, supporting evidence and independent review. Investors and borrowers should not treat today’s methodology as a certification of individual projects or assume that unsettled greenwashing and disclosure risks have disappeared.
Financial data partnerships now carry clearer accountability beyond the initial customer consent. Banks and fintech aggregators need to map every downstream recipient, inspect contract rights and test whether their oversight works when data are reused. Access to the rail is valuable, but it won’t excuse weak controls at the next company in the chain.
Canada put C$1.75 billion in venture and growth capital on the table and introduced new rules to make federal regulation more competitive. Internationally, banks and fintechs advanced tokenized deposits, cross-border settlement and AI-controlled financial transactions. These are becoming practical business decisions about who controls customer access, payment infrastructure and compliance costs. The opportunity for Canadian fintechs is to compete on execution, building products customers trust, securing distribution and turning regulatory change into commercial advantage.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech news and insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |
October 23, 2026 | NCFA Insight | Capital Markets Infrastructure And Funding, Competition And Market Structure, SME Finance And Business Banking
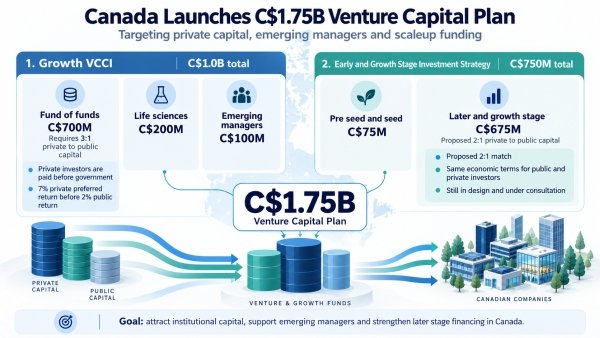
On October 22, 2026, Industry Minister Mélanie Joly launched Canada's C$1.75 billion Venture and Growth Capital Plan. It combines C$1 billion for a new Venture and Growth Capital Catalyst Initiative with C$750 million for early and growth stage investing. Ottawa expects the programs to attract at least C$3.8 billion of private investment, taking the total pool above C$5.5 billion.
Canada may be reaching an important turning point in how it supports venture capital. The plan is more targeted than another funding announcement. It uses public capital to attract institutional investors, broaden the fund manager base and strengthen later stage financing where Canadian companies often rely heavily on foreign capital.
The C$1.75 billion is federal capital, not money already invested in startups. Most of it will move through fund managers that must raise private capital before investing in venture funds or companies. The first C$700 million fund of funds competition is open now, while the largest growth stage stream is still being designed.
The plan has five funding streams.
Founders won't apply directly for most of this money. BDC will manage the federal investments, while selected fund managers raise private capital and invest through venture funds or eligible companies. The structure is meant to increase the amount of private money available across the financing cycle rather than turn C$1.75 billion into startup grants.
The C$700 million fund of funds stream is the first part with final application terms. Applications close January 21, 2027 at noon Pacific. Managers must be raising at least C$150 million, show Canadian venture investment experience and demonstrate institutional backing or a comparable track record.
The C$100 million emerging manager allocation addresses another weakness. In 2025, the five largest Canadian venture funds captured 83% of all capital raised, while emerging managers raised only C$249 million. A separate stream gives newer managers room to build track records without having to clear the C$150 million minimum used for the main fund of funds competition.
The C$675 million later and growth stage stream targets Series B and beyond, where the financing gap becomes more pronounced. Its current design covers growth equity, opportunity funds, continuation vehicles and some innovation focused buyout strategies. It isn't open for applications yet, and ISED and BDC are accepting feedback until November 23, 2026 at 5 p.m. Pacific.
The most consequential part of the plan may be how Ottawa is using public money to improve the economics for private investors. Selected fund of funds managers must raise C$3 of private capital for every C$1 of public capital. A fund receiving C$50 million from Ottawa would therefore need at least C$150 million from private investors.
The fund of funds terms give private investors priority when returns are distributed. Private investors are paid before the government. They first recover their contributed capital and receive enough additional distributions to reach a 7% internal rate of return. Federal capital is then repaid and begins earning its 2% return before remaining profits are distributed under the fund's waterfall. The 7% isn't guaranteed. Private investors still carry venture risk, but they receive better economics than the federal government when a fund performs well enough to return capital and profits.
Federal money is also put to work early. Public and private capital are generally drawn equally until the government's commitment has been used, even though federal capital represents about 25% of a fund meeting the minimum 3 to 1 private match. That can make participation more attractive to institutional investors by delaying some of their capital calls.
The program still keeps a strong Canadian investment requirement. At least 60% of fund investments must go into qualifying Canadian venture funds. Managers can invest up to 30% of a fund directly into companies, but at least 90% of those direct investments must go to Canadian based businesses.
Previous programs show that the model can attract larger pools of capital. Across VCAP and earlier VCCI programs, Ottawa reports C$1.2 billion of federal investment, C$3.7 billion raised by recipient managers and C$6.4 billion invested in Canadian companies by supported funds and other investors.
The proposed C$675 million growth stage stream takes a different approach. Its current design calls for at least C$2 of private capital for every C$1 of federal investment, but public and private investors would receive the same economic terms. That could make sense in a market where the priority is increasing the number of investors able to finance larger Canadian rounds.
The need is visible in the numbers. Canadian VC investment reached C$2.69 billion across 250 deals in the first half of 2026, but 16 financings of C$50 million or more absorbed 59% of all capital. Later stage activity fell to 18 deals, growth stage financing totalled only C$127 million across three deals and foreign investors participated in 56% of later stage rounds.
International capital is an advantage, something Canada should augment, not replace. The weakness appears when Canadian investors aren't able to lead or anchor enough of those larger rounds. More domestic growth capital can give strong companies another option when they are deciding where to raise, who joins the cap table and how much of the next stage of growth remains anchored in Canada.
Private capital is already moving into the gap. RBC recently launched a C$1.4 billion Canadian technology initiative that includes a growth fund for later stage technology companies. Public capital can widen that market by bringing more pension funds, insurers, family offices and fund managers into the same part of the financing cycle.
The emerging manager stream could broaden Canada's venture market as well. In 2025, government backed VCAP and VCCI capital represented 36% of Canadian VC fundraising. The next step is getting more pension funds, insurers, family offices and other private investors to keep investing after public capital has helped funds build a track record.
Exit markets remain a constraint. Canada recorded 18 venture backed exits worth C$716 million in the first half of 2026 and no venture backed IPOs. Funds ultimately need acquisitions, secondary sales or public markets to return money to investors and put that capital back to work.
Canada has an opportunity to use public capital differently this time. The C$1.75 billion plan can bring more institutional investors into venture, give emerging managers room to build credible track records and expand the pool of capital available when Canadian companies reach larger rounds. The turning point comes if it broadens the investor base (not just the amount of capital available), and those investors earn competitive returns and keep allocating capital after the incentives have done their job. That would move Canada closer to a venture market that compounds on its own rather than waiting for the next government program.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016