




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


October 27, 2026 | NCFA Industry Resource | SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Capital Markets Infrastructure And Funding
Growth Loans, Regional Financing and Founder Awards
On October 22, 2026, Women's Enterprise Organizations of Canada (WEOC) and the Business Development Bank of Canada (BDC) announced up to C$200,000 in growth loans for eligible women entrepreneurs. WEOC also partnered with Quebec lender Evol to connect more founders with financing and business support. Separately, the Capital Elle Business Impact Award is accepting applications until October 28, 2026, giving Canadian women entrepreneurs three opportunities worth considering.
The new Women Entrepreneur Growth Financing programme combines WEOC loans of up to C$50,000 with BDC loans of up to C$150,000. Backed by a C$12.5 million financing commitment over two years, the pilot targets eligible women owned businesses outside Quebec that need more capital to expand. BDC is contributing C$10 million toward the programme.
For businesses ready to buy equipment, invest in technology, increase production or pursue larger contracts, the additional financing could make a meaningful difference. Regional WEOC lending partners will assess applicants and provide business advice and ongoing support. The combined C$200,000 is a maximum, subject to eligibility and lending approval.
Applications haven't opened yet. Financing is expected to begin later in 2026. Interested founders can register for WEOC growth financing updates to receive application details, eligibility requirements and loan terms when available.
WEOC's new partnership with Evol connects lending services across Canada. Evol supports entrepreneurs throughout Quebec's 17 regions, while WEOC works through lending partners elsewhere in Canada. The organizations will refer founders to suitable financing and advisory services, including businesses that may not qualify for an existing programme.
Both organizations participate in the Women Entrepreneurship Loan Fund, which offers eligible businesses loans of up to C$50,000. The partnership isn't a new grant or an extension of the C$200,000 BDC pilot into Quebec. It helps entrepreneurs find lenders and support suited to their location and financing needs.
The Capital Elle Business Impact Award offers Canadian women entrepreneurs cash awards and business support across three categories covering strategic connections, growth capital and acquisitions. The organizer advertises a combined prize package worth more than C$100,000, including C$5,000 cash for each category winner, professional services, mentoring and business connections.
The award is open to women founders across industries, subject to eligibility requirements. Applicants select the category that best fits their business goals. The application process costs C$50 for nonmembers (nonrefundable), while eligible paid Elleiance members can apply without an additional fee.
Deadline is October 28, 2026, at 9 p.m. Eastern. Founders should review the official award terms and confirm eligibility.
More financing options are welcome, and founders should match the opportunity to their business. Growth loans can fund expansion, regional lenders can provide ongoing support, and awards offer cash and business connections. The best choice depends on how much money the business needs, what it qualifies for and whether it can take on debt.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
October 23, 2026 | NCFA Insight | Capital Markets Infrastructure And Funding, Competition And Market Structure, SME Finance And Business Banking
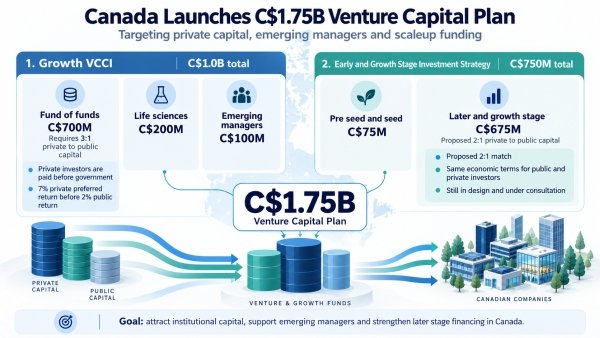
On October 22, 2026, Industry Minister Mélanie Joly launched Canada's C$1.75 billion Venture and Growth Capital Plan. It combines C$1 billion for a new Venture and Growth Capital Catalyst Initiative with C$750 million for early and growth stage investing. Ottawa expects the programs to attract at least C$3.8 billion of private investment, taking the total pool above C$5.5 billion.
Canada may be reaching an important turning point in how it supports venture capital. The plan is more targeted than another funding announcement. It uses public capital to attract institutional investors, broaden the fund manager base and strengthen later stage financing where Canadian companies often rely heavily on foreign capital.
The C$1.75 billion is federal capital, not money already invested in startups. Most of it will move through fund managers that must raise private capital before investing in venture funds or companies. The first C$700 million fund of funds competition is open now, while the largest growth stage stream is still being designed.
The plan has five funding streams.
Founders won't apply directly for most of this money. BDC will manage the federal investments, while selected fund managers raise private capital and invest through venture funds or eligible companies. The structure is meant to increase the amount of private money available across the financing cycle rather than turn C$1.75 billion into startup grants.
The C$700 million fund of funds stream is the first part with final application terms. Applications close January 21, 2027 at noon Pacific. Managers must be raising at least C$150 million, show Canadian venture investment experience and demonstrate institutional backing or a comparable track record.
The C$100 million emerging manager allocation addresses another weakness. In 2025, the five largest Canadian venture funds captured 83% of all capital raised, while emerging managers raised only C$249 million. A separate stream gives newer managers room to build track records without having to clear the C$150 million minimum used for the main fund of funds competition.
The C$675 million later and growth stage stream targets Series B and beyond, where the financing gap becomes more pronounced. Its current design covers growth equity, opportunity funds, continuation vehicles and some innovation focused buyout strategies. It isn't open for applications yet, and ISED and BDC are accepting feedback until November 23, 2026 at 5 p.m. Pacific.
The most consequential part of the plan may be how Ottawa is using public money to improve the economics for private investors. Selected fund of funds managers must raise C$3 of private capital for every C$1 of public capital. A fund receiving C$50 million from Ottawa would therefore need at least C$150 million from private investors.
The fund of funds terms give private investors priority when returns are distributed. Private investors are paid before the government. They first recover their contributed capital and receive enough additional distributions to reach a 7% internal rate of return. Federal capital is then repaid and begins earning its 2% return before remaining profits are distributed under the fund's waterfall. The 7% isn't guaranteed. Private investors still carry venture risk, but they receive better economics than the federal government when a fund performs well enough to return capital and profits.
Federal money is also put to work early. Public and private capital are generally drawn equally until the government's commitment has been used, even though federal capital represents about 25% of a fund meeting the minimum 3 to 1 private match. That can make participation more attractive to institutional investors by delaying some of their capital calls.
The program still keeps a strong Canadian investment requirement. At least 60% of fund investments must go into qualifying Canadian venture funds. Managers can invest up to 30% of a fund directly into companies, but at least 90% of those direct investments must go to Canadian based businesses.
Previous programs show that the model can attract larger pools of capital. Across VCAP and earlier VCCI programs, Ottawa reports C$1.2 billion of federal investment, C$3.7 billion raised by recipient managers and C$6.4 billion invested in Canadian companies by supported funds and other investors.
The proposed C$675 million growth stage stream takes a different approach. Its current design calls for at least C$2 of private capital for every C$1 of federal investment, but public and private investors would receive the same economic terms. That could make sense in a market where the priority is increasing the number of investors able to finance larger Canadian rounds.
The need is visible in the numbers. Canadian VC investment reached C$2.69 billion across 250 deals in the first half of 2026, but 16 financings of C$50 million or more absorbed 59% of all capital. Later stage activity fell to 18 deals, growth stage financing totalled only C$127 million across three deals and foreign investors participated in 56% of later stage rounds.
International capital is an advantage, something Canada should augment, not replace. The weakness appears when Canadian investors aren't able to lead or anchor enough of those larger rounds. More domestic growth capital can give strong companies another option when they are deciding where to raise, who joins the cap table and how much of the next stage of growth remains anchored in Canada.
Private capital is already moving into the gap. RBC recently launched a C$1.4 billion Canadian technology initiative that includes a growth fund for later stage technology companies. Public capital can widen that market by bringing more pension funds, insurers, family offices and fund managers into the same part of the financing cycle.
The emerging manager stream could broaden Canada's venture market as well. In 2025, government backed VCAP and VCCI capital represented 36% of Canadian VC fundraising. The next step is getting more pension funds, insurers, family offices and other private investors to keep investing after public capital has helped funds build a track record.
Exit markets remain a constraint. Canada recorded 18 venture backed exits worth C$716 million in the first half of 2026 and no venture backed IPOs. Funds ultimately need acquisitions, secondary sales or public markets to return money to investors and put that capital back to work.
Canada has an opportunity to use public capital differently this time. The C$1.75 billion plan can bring more institutional investors into venture, give emerging managers room to build credible track records and expand the pool of capital available when Canadian companies reach larger rounds. The turning point comes if it broadens the investor base (not just the amount of capital available), and those investors earn competitive returns and keep allocating capital after the incentives have done their job. That would move Canada closer to a venture market that compounds on its own rather than waiting for the next government program.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 23, 2026 | NCFA Community Opportunities | Women Entrepreneurs, Startup Funding, Business Awards, Canada

On October 23, 2026, Canada's Total Mom Pitch and Business Awards are accepting applications for the 2026–2027 programme, with a November 15 deadline approaching for Canadian mom entrepreneurs looking for funding, business support and national recognition.
The programme, operated by Sinclair Creative Agency under licence from Total Mom Inc., offers a competitive founder pitch with a $50,000 grand prize package alongside national business awards that don't require a live pitch.
NCFA is supporting the initiative as a community partner and encouraging eligible entrepreneurs across its network to explore the opportunities before applications close.
Canada's Total Mom Pitch offers one winning founder a prize package valued at approximately $50,000, consisting of $10,000 in cash and $40,000 in business services, mentorship and strategic support provided by participating sponsors and partners.
The competition selects 100 semi-finalists, who gain access to business education, funding resources, networking and national media opportunities. Five finalists advance to pitch live at the awards gala on February 10, 2027.
The Total Mom Business Awards offer a separate opportunity for entrepreneurs seeking recognition for their businesses and achievements. Applicants select from the available award categories, and no live pitch is required.
Entrepreneurs may apply for the Pitch, the Business Awards or both, subject to the eligibility requirements and separate application fees.
Application deadline: November 15, 2026, at 11:59 p.m. ET
Pitch grand prize: $10,000 cash plus approximately $40,000 in business services and support
Pitch application fee: $35 plus processing fees and applicable taxes
Business Awards application fee: $197 plus processing fees and applicable taxes
Live Pitch Finale: February 10, 2027
Pitch applicants must meet the programme's published eligibility requirements, including being a mom-identifying woman entrepreneur, having annual business sales below $2 million and meeting Canadian residency requirements. Quebec residents aren't eligible for the Pitch. Business Awards categories have their own eligibility criteria.
Founders should review the official programme rules before applying, including eligibility, fees and prize conditions.
Explore the opportunities and apply: Canada's Total Mom Pitch and Business Awards
Access to capital remains important for entrepreneurs, but funding isn't the only constraint on business growth. Experienced advisors, industry connections, market exposure and practical operating support can also make a difference, particularly for founders managing business and family responsibilities.
The Total Mom programme combines financial recognition with opportunities for participating entrepreneurs to build relationships, strengthen business plans and gain exposure beyond their existing networks.
As a community partner, NCFA encourages eligible founders to review the programme and consider applying. With the November 15 deadline approaching, interested entrepreneurs should check the requirements and submit their applications before the closing date.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 22, 2026
Customer acquisition is a moving target for fintech companies. A new product may need immediate visibility, while an established one may already attract visitors through search. The questions customers ask can change as the company adds features, enters new markets, or learns which audiences are most likely to convert. A search budget set at launch should be able to change along with the business.
Working with a digital marketing agency that manages both SEO and Google Ads makes those changes easier to spot and act on. The same team can see which paid searches produce qualified prospects, which website pages are gaining organic visibility, and where the next portion of the budget could have the greatest effect. Rather than treating ads and SEO as unrelated expenses, a fintech company can use them as parts of one customer acquisition plan.
Google Ads can help a company reach people searching for a relevant product today. That is useful for a launch, a new service, or a market where the company has little organic visibility. Paid campaigns can also reveal which search terms generate interest and which messages persuade visitors to take the next step.
SEO usually takes longer. A company needs pages that answer customer questions clearly, explain its products, and make its website easy to use. Those pages may gain organic visibility over time, giving prospective customers another way to discover the business. SEO still requires investment in research, content, technical work, and upkeep. Its value is that a useful page can continue attracting relevant visitors between campaign launches.
Neither channel should be expected to do every job. An ad can bring a visitor to a new product page before that page has earned an organic ranking. A well-established guide can introduce people to a problem before they are ready to request a demo. Together, the channels can reach customers at different points in their decision-making process.
A fintech company may begin with an informed guess about the words customers use. Actual search activity can challenge that guess.
Imagine a company offering expense-management software to small businesses. Its team might describe the product as an “expense automation platform,” while potential customers search for “track employee expenses” or “approve staff reimbursements.” Google Ads can help the company test these terms and see whether visitors who use them become qualified leads.
Those findings should inform the website. If a particular question repeatedly brings in the right audience, the company may need a dedicated page that answers it in detail. If visitors respond to a specific benefit in an ad, the landing page should explain that benefit just as clearly. Paid campaigns can therefore do more than generate traffic; they can help a company learn how customers describe their needs.
That learning is particularly valuable when marketing a product that takes time to understand. A prospective customer may need to compare approaches, review features, and discuss the purchase internally before making contact. Useful SEO content can support that process long after the first ad click.
As pages gain organic visibility, the role of paid search may change. Suppose the expense-management company publishes a practical guide to managing employee reimbursements. At first, it uses ads to reach people searching for that topic. Several months later, the guide and a related product page begin attracting relevant organic visitors and generating demo requests.
The company now has a decision to test. It could reduce paid spending on some of those searches and use the available budget to promote a new feature or reach a different audience. It could also keep the ads running if they continue to generate customers the organic results do not capture.
The important point is to make a measured change. A high organic ranking does not prove that an ad is unnecessary. Some people will click an ad even when the same company appears below it in search results. Others may respond to a particular ad message or arrive on a more focused landing page. Cutting spend based on rankings alone could reduce the total number of qualified leads.
A sensible test would adjust the budget gradually, then compare the combined results from paid and organic search. Did the number of qualified demos change? Did acquisition costs improve? Did the company reach customers it might otherwise have missed? Those answers should determine the next move.
Reallocating budget is more useful than simply reducing it. If organic search begins serving one established topic well, paid media can help the company pursue something new.
That might mean testing searches related to a recently released feature. It could mean reaching a new type of business, promoting a page built for a different market, or learning whether a more competitive term can produce customers at an acceptable cost. Ads provide a way to gather evidence while the company develops the content and organic presence needed for a longer-term effort.
The flow can also work in the opposite direction. If an SEO page starts attracting relevant visitors but few of them enquire, the team can test new messages and calls to action through paid campaigns. Results from those tests can guide improvements to the page.
This creates a cycle: ads provide timely feedback, SEO builds on what the company learns, and organic results help the team decide where paid spend is most useful next. The budget follows customer demand and business priorities rather than staying attached to a fixed list of keywords.
A search report can look encouraging while hiding a problem. Ads may generate clicks from people who cannot use the product. A page may rank well for a popular question but attract readers who are unlikely to become customers. For a fintech company, traffic and rankings matter most when they contribute to a worthwhile business result.
Before changing the budget, the team should agree on what a valuable conversion looks like. Depending on the product, that might be a qualified demo request, a completed application, or a new account that meets the company’s customer criteria. It should then track those outcomes across both paid and organic search.
Sales feedback adds another layer. Are the leads asking about the product the company actually offers? Do they serve the market the company can support? Are they ready to take a meaningful next step? Answers to those questions can be more useful than a lower cost per click.
Shared measurement also prevents each channel from claiming success in isolation. If the ads team reports more leads and the SEO team reports more traffic, the business still needs to know whether overall customer acquisition improved. Looking at the full picture makes budget decisions more credible.
Coordinated search marketing depends on what happens after someone clicks. A strong ad cannot compensate for a page that leaves visitors unsure what the product does. Likewise, organic visibility has limited value if the page does not help the right person decide what to do next.
The website should answer the question that brought the visitor there. A search for a specific feature should lead to a page explaining that feature, who it helps, and how it works. A broader educational search may be better served by a guide that explains the issue before introducing the product. Clear navigation can help readers move from learning to comparing and, when they are ready, to making contact.
For fintech companies, clarity is especially important. Customers may be evaluating a service that affects how they handle money or business operations. Marketing copy should explain the offer plainly and accurately. The SEO and ads teams should work from the same product information so that the promise in a search result matches the experience on the page.
A combined strategy does not require constant changes to campaigns. It requires a regular opportunity to ask whether the current allocation still makes sense.
In a monthly review, a company and its marketing team might look at the searches producing qualified customers, the pages gaining organic traction, and the areas where visibility remains weak. They can then choose a small number of changes to test: update a landing page, develop content around a proven customer question, or move part of the paid budget to a new opportunity.
NCFA Canada’s discussion of fintech startup challenges includes the cost of finding customers. That makes disciplined experimentation more valuable than maintaining two separate search plans indefinitely. Each investment should help the company understand where its next customers are coming from and how efficiently it can reach them.
SEO and Google Ads will not always rise or fall together. A new product may need more paid support; an established topic may need less. When both channels are managed against the same customer acquisition goals, a fintech company can respond to those changes deliberately—and put its budget where it has the best evidence of value.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 9, 2026

For a 5-page business website, visual layout is the easiest part of a designer's job to automate. A current AI tool can pick a colour palette and arrange a hero image above 3 service blocks in under a minute. The harder parts of the job are deciding what the site should leave out and meeting accessibility law, and those parts depend on judgment that the tools still hand back to a person.
Nielsen Norman Group reviewed AI design tools again in May 2025 and found that the most useful features were the narrow ones. Palette generators, placeholder image generators and copy rewriting saved designers time on tasks with a single obvious goal. For a small business owner, that means a model can match a colour scheme to an existing logo or cut a long services paragraph down to its essentials in seconds.
Statistics Canada's 2023 survey of business technology and internet use put AI use at 7% of businesses with 5 or more employees in 2023, up from 4% in 2021, and at only 6% of small businesses. Among the businesses that used AI, 73% used generative AI, so for most small firms an AI layout tool is still a first experiment.
General-purpose tools in that review, the ones that generate whole wireframes or prototypes from a prompt, produced generic designs with weak visual hierarchy. They repeated the same layout patterns even when the prompts varied, and they could not work from an existing design system. One tool limited prompts to 500 characters, style="font-size:20px;"too short to describe a business in any detail. The authors concluded that only a human designer can balance the design, business and user needs that a finished site has to meet.
A dental clinic's home page has to show in the first screen that the clinic accepts new patients and how to book an appointment. A generated layout tends to open with a large photo and a slogan. A designer, or an owner thinking like one, moves the answers to the top and pushes the slogan down.
Job Bank data updated in November 2025 put the median wage for web designers in Canada at $33.65 an hour, with a range from $21.48 to $57.16. At 30 to 60 hours of design and build time, a small brochure site therefore represents roughly $1,000 to $2,000 in labour at the median rate, before any agency margin. Owners who build a website with AI replace most of that labour with an afternoon of prompting and editing, plus the monthly cost of the plan.
The saving applies to a site whose content is already settled in the owner's head. It shrinks when the owner has never written down what the business offers, because the AI tool will fill the gaps with generic text that the owner then has to rewrite page by page.
Ontario has a legal accessibility standard that AI tools do not check for by default. Under the Accessibility for Ontarians with Disabilities Act, organizations with 50 or more employees in the province have had to meet the Web Content Accessibility Guidelines 2.0 at Level AA since January 1, 2021. Businesses with 20 or more Ontario employees also file regular reports on AODA compliance that cover online accessibility. Corporations that fail to comply face fines of up to $100,000 for each day the offence continues, and directors and officers can be fined up to $50,000 a day. The standard exempts only 2 criteria, live captions and pre-recorded audio descriptions, so nearly every page element on a typical business site is in scope.
Level AA covers details that a generated layout can get wrong, such as the contrast between text and background and the labels on form fields. Designers working to that standard test these items before launch. An owner using AI can run the same tests with a free accessibility checker, but has to know that the step exists.
Generated layouts look alike because the tools draw on the same patterns. When 3 competing dog groomers in one town each accept the first design an AI tool offers, they can end up with near-identical home pages, and a customer comparing them in 3 browser tabs has little to separate them except the photos.
A designer's value in that situation is a distinct visual identity, built from a logo treatment and a photography style that appear on the site and on everything else the business prints. An owner can get part of the way with AI by giving the tool brand assets and rejecting its first few drafts.
Image generators can fill every page with polished photos in minutes, and that speed creates a specific problem for a small business. Some of those photos mislead. A generated shot of 8 smiling technicians at a firm that employs 2 presents something to customers that does not exist. In Toronto, some restaurant owners have turned to AI-generated menu photos to save time and money, and CBC News reported customers calling the results slop and reading them as a sign of the restaurant's values. A designer working with a real client usually pushes for photos of the actual premises and work.
Under the 2022 amendments to the Competition Act, the maximum administrative penalty for a corporation found to have engaged in deceptive marketing is the greater of $10 million, rising to $15 million for a repeat violation, and 3 times the benefit it gained. For an individual, the ceiling starts at $750,000. A small firm is unlikely to face penalties near those ceilings, but an owner who publishes generated photos of work the business never did is taking a legal risk that no design tool will flag.
The labour market for this work is growing. The U.S. Bureau of Labor Statistics projects employment of web designers and interface designers to grow 7% from 2024 to 2034, faster than the average for all occupations, with a median annual wage of US$104,000 in May 2025. WorkBC expects 1,960 openings for web designers in British Columbia between 2025 and 2035 and lists the job as a high opportunity occupation in the province. Hiring one is a normal business purchase, and the question for a small firm is when the fee pays for itself.
A designer is worth the cost for a business with 50 or more Ontario employees, since the accessibility duty applies in full, and for a store whose revenue depends on e-commerce checkout design, where one confusing step between the cart and the payment page can lose the sale. A designer is also worth it at a brand launch, when the visual identity has to be set once and then repeated everywhere. A contractor who needs 5 pages and a phone number at the top of each one can reach a working result with AI and careful editing.
A web designer, for a small business, is the person who decides what the visitor sees first and what the site leaves out, and who checks that every visitor can use it. AI tools can produce the pages. Those decisions stay with whoever is responsible for the site, and an owner who makes them has taken on the designer's job.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 9, 2026 | Market Activity, SME Finance And Business Banking, Payments, Embedded Finance, Canada

On October 8, 2026, Calgary fintech Woveo and BDC announced a C$10 million microlending program, offering loans up to C$25,000. BDC and Woveo are helping entrepreneurs access smaller loans that conventional lenders may find costly to originate. Woveo's loans are available to qualifying businesses outside Quebec.
The same day, Peloton Technologies and Driven Financial announced a supplier payment and working capital partnership, giving Peloton's Canadian small business clients preferred access to Driven's financing products. Peloton's existing Bill Pay by Card service offers up to 55 days of payment flexibility through eligible credit card billing cycles, serving eligible clients across Canada. Peloton and Driven are connecting existing business payment customers with financing when their needs extend beyond a credit card billing cycle.
A C$15,000 business loan can require many of the same checks as a C$150,000 loan. For traditional lenders, the time spent verifying information, assessing risk and servicing a small balance can make the economics unattractive. Woveo combines AI assisted underwriting, banking transaction data, credit information and community accountability to evaluate borrowers. BDC contributes institutional capital through its Community Banking initiative, giving Woveo greater capacity to serve entrepreneurs seeking relatively small amounts.
The BDC and Woveo microloan program provides up to C$25,000 without traditional collateral. Applicants must have at least 12 months in business, C$5,000 in monthly revenue, a credit score of 600 or higher and a community accountability partner. The program excludes Quebec. These requirements mean the offering could help businesses underserved by conventional lenders, but it isn't unrestricted financing for new startups or borrowers without established revenue.
Woveo reports facilitating more than 1,200 loans with a 98% repayment rate through earlier community programs. The commercial opportunity is to make small business lending more economical while retaining sufficient oversight and borrower support. The program's longer term value will depend on loan performance, borrowing costs and whether participants can subsequently obtain larger financing from mainstream institutions.
Peloton serves businesses that need to pay suppliers before customers have settled their invoices. Its Bill Pay by Card service lets eligible customers charge supplier payments to a credit card, even when the supplier doesn't accept cards. Peloton transfers the funds electronically, and the business pays its card issuer later. The arrangement can preserve cash for up to 55 days, depending on the card billing cycle, but it isn't a separate loan from Peloton.
Peloton's published transaction fees start at 1.59% for consumer cards, 1.75% for corporate and purchasing cards, and 2.4% for business cards. Actual charges vary, and additional interest may apply when card balances aren't paid on time. An owner expecting a customer payment next week faces a different calculation from one borrowing to cover several months of expenses. Supplier discounts and card rewards may offset some transaction costs, but the business still needs to compare its total financing expense.
Driven (formerly Thinking Capital) and now part of Purpose Unlimited, provides separate business lending products for longer funding requirements. Its current Driven Financial company information reports more than C$1.6 billion in financing across over 20,000 Canadian businesses. Peloton clients receive preferred access to Driven, but lending decisions remain subject to assessment, and the companies haven't disclosed a shared underwriting system.
Payment delays can leave Canadian small businesses short of cash even when sales are healthy. Payments Canada's 2026 Canadian payments data shows that 37% of surveyed SMEs consider payment delays a significant problem. A contractor waiting for customer payments may need temporary cash to cover suppliers, while another business might require a C$20,000 loan to purchase equipment or expand operations. The amount, repayment period and reason for borrowing determine which financing product makes sense.
Canada's SME financing gaps aren't explained by approval rates alone. Smaller businesses can struggle with application costs, collateral requirements and financing products designed for larger or more established borrowers. Woveo is addressing the economics of evaluating small loans. Peloton and Driven are using a payment relationship to connect businesses with financing.
BDC and Woveo are addressing the cost of serving smaller borrowers, while Peloton and Driven are combining payment services with access to business credit. Both arrangements could improve how Canadian SMEs find suitable financing, but the commercial and borrower benefits still need to be demonstrated. Can alternative lenders make smaller financing transactions profitable while offering terms that genuinely match how Canadian businesses earn and repay money?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 5, 2026 | Legal, Regulation, FinTech, Crowdfunding, Human Capital

In the early days of a fintech or crowdfunding platform, legal work often falls to a founder, an outside firm on retainer or a part time advisor. That works for a while. Then the company grows, regulators take notice, partners ask harder questions during due diligence, and it becomes clear that legal expertise is no longer a supporting function. It is part of the product.
Hiring the right legal talent at the right time can be the difference between scaling smoothly and stalling under compliance pressure. Here is what Canadian fintech leaders should know.
Fintech companies operate in one of the most heavily regulated corners of the economy. Every new product, market or partnership can trigger obligations around money laundering, privacy, securities or payments.
Investors understand this. Strong legal and compliance leadership signals that a company can grow without costly surprises. Banks and payment partners often expect it before they will sign an agreement. And when something does go wrong, experienced counsel can limit the damage.
The Canadian regulatory landscape explains why legal hiring has become so competitive.
Many fintechs, including money services businesses and some crypto platforms, have reporting and compliance obligations to the Financial Transactions and Reports Analysis Centre of Canada. These obligations typically include appointing a compliance officer, maintaining a written compliance program and reporting certain transactions. Getting this wrong can lead to significant penalties.
Fintechs handle highly sensitive personal and financial information. In most provinces, private sector privacy is governed by the Personal Information Protection and Electronic Documents Act (PIPEDA), and the Office of the Privacy Commissioner of Canada explains how organizations must collect, use and protect that information. Some provinces also have their own private sector privacy laws.
Crowdfunding portals and investment platforms must navigate provincial securities rules, including the national start-up crowdfunding exemptions. Offering documents, investor limits and marketing all require careful legal review.
The Retail Payment Activities Act requires many payment service providers to register with the Bank of Canada and meet operational and fund safeguarding requirements, adding a new layer of compliance work for payments companies.
Not every company needs a full legal department on day one. As companies grow, these roles tend to appear in roughly this order.
A first general counsel usually handles everything from contracts and financing to regulatory strategy. The best early hires are generalists who are comfortable working at startup speed and know when to bring in outside specialists.
A dedicated compliance officer, often with anti-money laundering expertise, becomes essential once regulatory obligations grow. This person builds policies, trains staff and manages relationships with regulators.
As products become more data driven, specialized counsel can manage privacy programs, vendor agreements and cybersecurity requirements.
Growing fintechs sign agreements with banks, processors, software vendors and distribution partners. Counsel who can negotiate these efficiently keeps deals moving.
Lawyers with real fintech experience are in short supply. Fintechs compete with major banks, large law firms and global technology companies for the same people, often with smaller budgets. Candidates also need a rare combination of skills: regulatory knowledge, commercial judgment and comfort with ambiguity.
Startups can compete by offering meaningful equity, broad responsibility and the chance to shape a legal function from the ground up. But they need to find the right candidates first.
A few steps can make the process more effective:
Many companies also find it worthwhile to work with specialists. Experienced legal recruiters like The Heller Group understand the Canadian legal market and can identify candidates with the right regulatory background, including those not actively searching. That can save months on a critical hire.
In fintech and crowdfunding, legal expertise is not overhead. It is infrastructure. The companies that thrive are the ones that treat compliance as part of their product, build legal capacity ahead of regulatory pressure and hire people who can help them grow responsibly. Investing in the right legal bench early is one of the smartest moves a growing platform can make.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016