




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Oct 5, 2026 | Legal, Regulation, FinTech, Crowdfunding, Human Capital

In the early days of a fintech or crowdfunding platform, legal work often falls to a founder, an outside firm on retainer or a part time advisor. That works for a while. Then the company grows, regulators take notice, partners ask harder questions during due diligence, and it becomes clear that legal expertise is no longer a supporting function. It is part of the product.
Hiring the right legal talent at the right time can be the difference between scaling smoothly and stalling under compliance pressure. Here is what Canadian fintech leaders should know.
Fintech companies operate in one of the most heavily regulated corners of the economy. Every new product, market or partnership can trigger obligations around money laundering, privacy, securities or payments.
Investors understand this. Strong legal and compliance leadership signals that a company can grow without costly surprises. Banks and payment partners often expect it before they will sign an agreement. And when something does go wrong, experienced counsel can limit the damage.
The Canadian regulatory landscape explains why legal hiring has become so competitive.
Many fintechs, including money services businesses and some crypto platforms, have reporting and compliance obligations to the Financial Transactions and Reports Analysis Centre of Canada. These obligations typically include appointing a compliance officer, maintaining a written compliance program and reporting certain transactions. Getting this wrong can lead to significant penalties.
Fintechs handle highly sensitive personal and financial information. In most provinces, private sector privacy is governed by the Personal Information Protection and Electronic Documents Act (PIPEDA), and the Office of the Privacy Commissioner of Canada explains how organizations must collect, use and protect that information. Some provinces also have their own private sector privacy laws.
Crowdfunding portals and investment platforms must navigate provincial securities rules, including the national start-up crowdfunding exemptions. Offering documents, investor limits and marketing all require careful legal review.
The Retail Payment Activities Act requires many payment service providers to register with the Bank of Canada and meet operational and fund safeguarding requirements, adding a new layer of compliance work for payments companies.
Not every company needs a full legal department on day one. As companies grow, these roles tend to appear in roughly this order.
A first general counsel usually handles everything from contracts and financing to regulatory strategy. The best early hires are generalists who are comfortable working at startup speed and know when to bring in outside specialists.
A dedicated compliance officer, often with anti-money laundering expertise, becomes essential once regulatory obligations grow. This person builds policies, trains staff and manages relationships with regulators.
As products become more data driven, specialized counsel can manage privacy programs, vendor agreements and cybersecurity requirements.
Growing fintechs sign agreements with banks, processors, software vendors and distribution partners. Counsel who can negotiate these efficiently keeps deals moving.
Lawyers with real fintech experience are in short supply. Fintechs compete with major banks, large law firms and global technology companies for the same people, often with smaller budgets. Candidates also need a rare combination of skills: regulatory knowledge, commercial judgment and comfort with ambiguity.
Startups can compete by offering meaningful equity, broad responsibility and the chance to shape a legal function from the ground up. But they need to find the right candidates first.
A few steps can make the process more effective:
Many companies also find it worthwhile to work with specialists. Experienced legal recruiters like The Heller Group understand the Canadian legal market and can identify candidates with the right regulatory background, including those not actively searching. That can save months on a critical hire.
In fintech and crowdfunding, legal expertise is not overhead. It is infrastructure. The companies that thrive are the ones that treat compliance as part of their product, build legal capacity ahead of regulatory pressure and hire people who can help them grow responsibly. Investing in the right legal bench early is one of the smartest moves a growing platform can make.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 29, 2026 | NCFA Event Spotlight | Capital Formation And Venture Markets, Regulation And Policy, Competition And Market Structure

On October 15, 2026, the Ontario Securities Commission will host Capital Raising Opportunities and Regulatory Innovation in Ontario, a 90 minute webinar on how businesses can raise capital across Ontario's private and public markets. The session comes while the OSC is looking at where companies encounter financing gaps or regulatory obstacles as they move from startup through maturity.
The webinar runs from 10:00 to 11:30 a.m. Eastern with the OSC staff covering the Listed Issuer Financing Exemption (LIFE), the Well Known Seasoned Issuer (WKSI) regime, prospectus exemptions, streamlined reporting requirements and cross border capital raising arrangements with regulators in France and Hong Kong. A final panel focuses on how evidence from issuers, founders, dealers, investors and advisors informs OSC capital formation initiatives.
Event: Capital Raising Opportunities and Regulatory Innovation in Ontario
Host: the Ontario Securities Commission
Date: October 15, 2026
Time: 10:00–11:30 a.m. ET
Format: Webinar
Registration: Register for the OSC webinar
Agenda
The agenda covers several points where financing can become easier or more difficult as a company grows. LIFE gives eligible listed issuers a lighter route to public capital. WKSI can simplify access for larger, established issuers. Prospectus exemptions provide other routes, while streamlined reporting can affect how much time and money companies spend meeting securities requirements.
LIFE provides a useful example of why regulatory design matters. In May 2025, regulators expanded Canada's Listed Issuer Financing Exemption, raising the financing limit from C$10 million to C$25 million, or as much as C$50 million for larger issuers, subject to conditions. Hundreds of issuers subsequently raised about C$3.7 billion during the first year under the higher limits, roughly eight times the previous pace.
The CSA is now proposing to make those higher limits permanent, with comments due October 21. Higher limits don't prove that regulation caused every additional financing, but issuers clearly used the added capacity. That gives the OSC webinar a concrete example to work from when discussing which rules facilitate capital raising and which may constrain it.
The international agreements with France and Hong Kong add another angle. For companies capable of raising beyond Canada, the issue isn't only how much capital is available domestically. It is also how efficiently an Ontario issuer can reach investors and markets elsewhere without duplicating unnecessary regulatory work.
The OSC's Office of Economic Growth and Innovation is looking across the financing continuum rather than at one exemption or company stage. An early stage company may raise its first outside capital and still struggle when it needs a much larger round. A listed company may have more financing routes but face costs, disclosure requirements or eligibility rules that make some of them impractical.
Canada's recent SME financing gaps evidence shows why formal access and usable access aren't always the same thing. A funding route can exist and still fail to meet the size, cost or timing a growing company needs.
Canada's recent SME financing gaps evidence shows why formal access and usable access aren't always the same thing. A funding route can exist and still fail to meet the size, cost or timing a growing company needs.
Equity crowdfunding offers a specific example. Canada's NI 45-110 startup crowdfunding exemption remains capped at C$1.5 million over 12 months, while NCFA has advocated a C$5 million or higher issuer cap for years. Recent Canadian offerings have also pushed close to the existing C$1.5 million ceiling.
Other markets allow substantially larger raises.
The OSC hasn't included equity crowdfunding as part of the webinar, but the Canadian investment crowdfunding issuer cap illustrates the policy question well. When does a financing limit become too low for a growing company and push it toward a more expensive way to raise capital?
The 10:45 panel should be especially relevant for founders, issuers, dealers and funding platforms. The OSC says it will discuss how stakeholder feedback, market intelligence and data influence targeted initiatives. Useful questions include where the regulator sees the largest gaps between startup, private growth and public markets, which requirements materially affect access to capital, and what evidence it needs before changing a rule.
The October 15 session lands in the middle of two live regulatory discussions. The proposed LIFE amendments close for comment on October 21. A separate CSA review, open until November 13, considers public company regulation including issuer classification, financial reporting requirements, private placement hold periods and material change reporting.
Neither process means the OSC has decided that particular rules should change. They do show that regulators are comparing existing requirements with how companies actually raise capital, while the OSC is gathering evidence about financing friction at different stages of growth.
More Reading:
Ontario already gives companies several ways to raise capital. The question is where those options stop working as a company grows. Sometimes the problem is investor demand or business risk. Other times, financing limits, costs or regulatory requirements may be getting in the way. The October 15 discussion should help show where the OSC sees those problems and what evidence might support a change.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
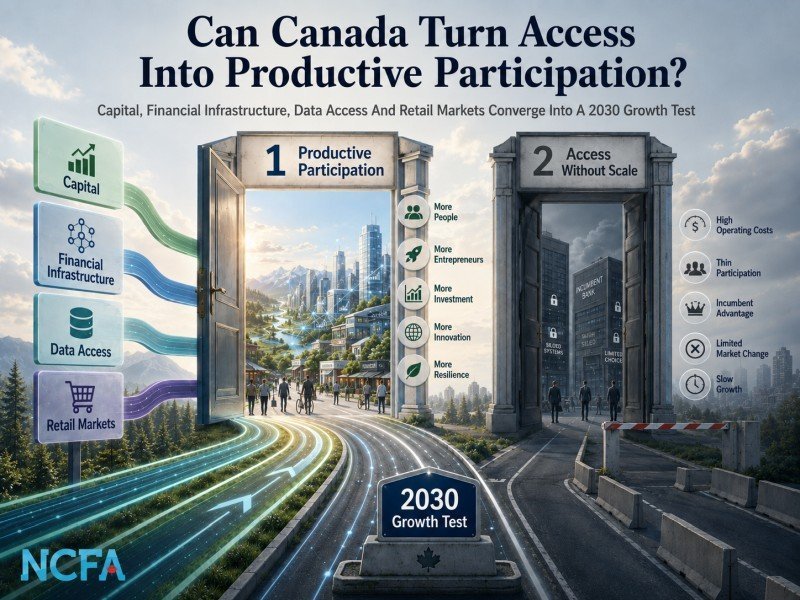
On August 21, 2026, Canada's founder drain returned to the national debate with a harder number attached to it. The Dominion List, a curated catalogue rather than a census, now tracks 517 U.S.-based companies with a Canadian-linked founder. Together they have raised roughly US$414 billion. About 88% of the founder links include education at a Canadian university, and 56% of the companies are headquartered in San Francisco.
The pace in the list also accelerated during the AI boom. Jesse Rodgers' Barn Ventures analysis counts 60 newly founded U.S. companies with Canadian-linked founders in 2023, 93 in 2024 and 87 in 2025, compared with roughly 20 to 30 a year from 2016 through 2022. The dataset is curated and recent companies may be easier to capture, so it should not be treated as a population estimate. The direction is still difficult to ignore.
Canada clearly produces ambitious builders. The strategic question is whether enough of them can find the capital, customers, infrastructure, investors and operating density needed to build more of the resulting value here. That makes founder retention part of a wider participation problem, not a standalone brain-drain story.
Canada's problem is not producing ambitious people. It is converting more of that talent into companies, jobs, ownership and follow-on investment that compound inside the Canadian economy.
Capital matters, but so do density, access, customers, infrastructure and the speed of getting from talent to a company with traction. Founder retention makes the wider participation thesis concrete because Canada can create the input and still lose much of the compounding.
The transferable lesson is not a U.S. securities rule. It is the habit of bringing market participants back into the process and testing whether a framework is producing the market it was intended to create.
Canada already has consultations, programs and market data. The harder test is whether each reform produces enough real participation to change who can compete, invest and scale.
Growth VCCI can deepen capital for companies that fit venture mandates. It does not automatically finance every viable manufacturer, service company or local employer whose growth profile, asset base or financing need sits outside institutional venture economics.
Formal access changes who is allowed to participate. Competition changes only when entrants can absorb compliance, technology, integration and operating costs and still build products customers want.
The payoff is not a longer list of fintech entrants. It is more providers controlling enough of their infrastructure and economics to put sustained pressure on incumbents.
Managed access can broaden exposure to private-market returns. Direct access can broaden the number of people deciding which companies receive their money. Both can widen participation, but they create different markets.
If more company value is created while businesses remain private, wider retail access affects more than issuer financing. It influences which households can accept productive risk and participate earlier in private-market returns.
Canada's smaller market does not prove regulation caused weak activity. Issuer quality, investor demand, distribution, awareness, liquidity and platform execution also matter. It does show why market-opening rules should eventually be judged by whether enough issuers, investors and intermediaries can participate economically.
The evidence will be practical. Entrants that survive. Products customers use. Capital reaching different kinds of companies. Investors using managed and direct routes. Smaller institutions offering capabilities once reserved for much larger competitors.
That recycling question is now moving into tax policy. The Bet on Canada campaign, launched in October 2026 by Canadian innovation, venture and professional groups, is calling for stronger incentives to reinvest gains from successful Canadian companies into the next generation of domestic businesses, including broader capital gains rollover treatment.
More viable participants can increase competition. Better competition can improve products, distribution and capital allocation. Better tools and financing can support more investment. Stronger companies can create more opportunities for households and institutions to participate again.
Canada has spent years opening doors. The next phase is finding out which openings create viable markets. That means judging regulation and public programs by the participation, competition and productive activity they generate while preserving the protections that made wider access possible.
Participation is not a complete explanation for Canada's productivity problem. Management capability, commercialization, industrial structure, R&D, domestic demand, risk appetite and global scale all matter. The value of the thesis is that Canada is now opening enough capital, data, payments and investor channels at the same time to test whether participation becomes a measurable growth mechanism.
Talking Point
Canada already produces globally competitive talent and holds deep pools of capital, technology and institutional capacity. The opportunity between now and 2030 is to connect more of those assets before founders, ownership and future value compound somewhere else. If today's reforms create viable participation rather than permission alone, Canada could end the decade with more competitors, more investable companies and more ways for households and institutions to share in productive growth.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 4, 2026 | Crowdfunding, Charitable Giving, Digital Platforms

Quick answer: Canadian crowdfunding grew in dollar terms in 2026 but shrank in participation. Online donations processed through CanadaHelps reached $529 million in 2025, up 10% year over year, while gifts under $100 fell 17%. The market is consolidating around fewer, larger donors, and the platforms best positioned for the next two years are those that reduce friction for occasional, small-ticket contributors.
For organizers, that last cluster of numbers is the actionable part. A $66 average gift means volume matters more than any single donor, which in turn means the checkout experience is the campaign. Platforms built for crowdfunding canada that let a contributor give without creating an account convert measurably better at that price point than platforms that require registration.
The Giving Report 2026 describes a market that looks healthy in aggregate and fragile underneath.
Total online giving is up. The growth rate is the best since 2021. But the composition of that growth is narrow. Donors making gifts of $1,000 to $9,999 increased 40%. Donors giving $10,000 or more doubled. Meanwhile the $10-to-$100 band, historically the foundation of Canadian charitable participation, contracted 17%.
This is not a Canadian anomaly. It mirrors a pattern visible across most mature giving markets: donor concentration rising while donor count falls. But it has specific consequences for crowdfunding, which is structurally dependent on the small-gift band that is shrinking fastest.
Three explanations are usually offered, and all three appear to be partly true.
The third point is the one platforms can actually control.
Local and regional organizations became the largest cause area on CanadaHelps.org in 2025, with $121.8 million in donations, an 11% increase, and giving to local causes has nearly tripled since 2019.
That reorientation toward the local is arguably the most important structural story in Canadian crowdfunding. It favours campaigns with a geographic identity, a named beneficiary and a verifiable connection to a community. It disadvantages diffuse, national-scope appeals.
| Segment | 2026 direction | Structural driver |
| Local and regional causes | Strong growth | Proximity, verifiability, community trust |
| Medical and emergency campaigns | Stable | Urgency, high shareability |
| Peer-to-peer and team challenges | Growth | Distributed asking, social proof |
| Creative and product projects | Flat | Competition from e-commerce pre-orders |
| Small-gift general appeals | Decline | Cost of living, friction, fatigue |
The market splits into three tiers, and organizers routinely pick the wrong one.
Tier 1: charity-only platforms. Zeffy (0% platform fee, funded by optional donor tips) and CanadaHelps (3.75% on one-time gifts, 3.5% on monthly, plus card fees) both issue CRA-compliant tax receipts. Both require registered charitable status. For a registered charity, the receipting infrastructure alone justifies the fee.
Tier 2: general-purpose crowdfunding. GoFundMe and Fundrazr accept individuals and informal groups. Reach is the differentiator; GoFundMe's brand recognition still moves campaigns beyond a personal network in a way smaller platforms cannot match.
Tier 3: money pool and group-collection platforms. This is the fastest-growing and least-analyzed tier. Tiing, a Montreal-based platform operating in Canadian dollars for Canada and US dollars for the United States, is representative: a flat $1 fee per contribution covering Stripe processing, a 4% commission taken only when the organizer requests the transfer, no transfer fee, and payout within 24 to 48 hours. Contributors do not create an account. Tiing reports 120,000 users, more than $6.5 million collected and a 4.8/5 user rating.
The tier-3 model matters for a specific structural reason: it is optimized for exactly the small-ticket, high-volume contribution pattern that the broader market is losing. A flat fee plus back-end commission is transparent in a way percentage-plus-fixed models are not, and removing account creation addresses the friction problem directly.
Fee structures verified August 2026. Confirm current pricing with each provider.
The performance data is unusually consistent across platforms and geographies.
Canadian crowdfunding remains split between two regulatory realities. Donation-based and reward-based crowdfunding operate largely outside securities regulation, governed instead by consumer protection law, payment-processor rules and platform terms. Equity crowdfunding sits under provincial securities regimes and start-up crowdfunding exemptions.
For donation-based campaigns, the practical trust levers are disclosure rather than regulation: naming the organizer, naming the beneficiary, disclosing the fee structure up front, and being explicit about whether a tax receipt will be issued. Platforms that do not issue charitable receipts should say so plainly, and organizers should repeat it in the campaign description.
Three things look likely.
Consolidation of donor value at the top will continue. Charities that have not built a major-gift and securities-donation capability will feel the squeeze regardless of how well their online campaigns perform.
Friction reduction becomes the main competitive axis for small-gift platforms. Account-free contribution, wallet payments and single-field checkouts are no longer differentiators, they are table stakes.
Local specificity keeps winning. The tripling of local giving since 2019 is not a cycle, it is a reorientation.
How big is crowdfunding in Canada in 2026? Online donations through CanadaHelps alone reached $529 million in 2025, up 10%. The total Canadian market is larger, since it includes general-purpose platforms, money pool platforms and equity crowdfunding, which are not captured in that figure.
What is the average donation to a Canadian crowdfunding campaign? $66.
Do I need to be a registered charity to crowdfund in Canada? No. Individuals, families, schools, sports clubs and informal committees can raise money through general-purpose or money pool platforms such as Tiing, GoFundMe or Fundrazr. You cannot issue charitable tax receipts without registered status.
Are crowdfunding proceeds taxable in Canada? Funds received as a genuine personal gift are generally not taxable income, but the treatment depends on the circumstances, particularly if the funds relate to a business, a service or a reward. This is general information, not tax advice; consult an accountant or the CRA.
Which platform has the lowest fees for a Canadian campaign? For registered charities, Zeffy at 0%. For everyone else, flat-fee-plus-commission models such as Tiing's ($1 per contribution plus 4% at withdrawal) are typically among the lowest total-cost options, particularly at higher average gift sizes.
What makes a Canadian crowdfunding campaign succeed? Video, week-one momentum above 30% of goal, an itemized target, weekly updates, an explicit local connection, and the fewest possible clicks between "I want to give" and "I gave".
The Canadian crowdfunding market in 2026 is not in decline, but it is changing shape. Dollars are concentrating while participation thins. The organizations and organizers that adapt will be the ones that make small gifts effortless again, and that anchor their appeal in a place, a person and a number.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 28, 2026 | NCFA Resource | Sustainable Finance And ESG, Financial Inclusion, SME Finance And Business Banking

On July 23, 2026, SVX published Canada’s first comprehensive national assessment of community finance. The report identifies 768 institutions, estimates their combined assets and examines how community finance products direct money into housing, local businesses, Indigenous entrepreneurship, food systems, clean energy and other community priorities.
Its most useful contribution is a baseline. Until now, Canada didn't have a public national picture connecting credit unions, Community Futures organizations, Indigenous Financial Institutions, community loan funds, land trusts, community bond issuers and related intermediaries. The report brings these organizations together through a common definition, a product dataset and an interactive market map.
The report’s three main asset figures describe different parts of the market:
The $771.3 billion headline doesn’t mean that amount has been invested directly into community projects. It mainly reflects the institutional assets of large credit unions, including Desjardins, Vancity and Assiniboine Credit Union.
Credit unions account for approximately 99% of the reported assets, although they represent 40% of the 768 institutions. Community Futures organizations form another 34% of the network, followed by Indigenous Financial Institutions at 8%, community land trusts at 6%, community loan funds at 4% and community bond issuers at 4%.
That makes the $7.3 billion figure particularly useful. It provides a clearer estimate of the specialized community finance market operating outside credit unions. The report also identifies $755 million held by Indigenous Financial Institutions and $153.8 million raised through community bonds from 28 issuers.
Credit unions still belong in the national picture because member ownership and local deployment are central to the report’s definition. The DUCA Impact Lab discussion shows how a credit union can test lending models designed for people and businesses underserved by conventional criteria.
Community finance also means something different from community capital raising. In this report, community finance describes institutions that pool and direct capital toward a defined place, population or shared need. Differently, investment platforms that support equity crowdfunding like FrontFundr uses community capital to describe companies raising money from customers, supporters and retail investors through regulated crowdfunding. NCFA’s review of Canadian equity crowdfunding covers that second model.
The two can overlap. A community bond issuer or investment cooperative may attract individual investors while also qualifying as a community finance institution. A startup supported by its customers through an equity crowdfunding campaign doesn’t automatically meet the report’s institutional definition.
The institutional map combines 107 organizations in the Catalyst Community Finance Collection with 661 additional organizations identified through the Canadian Community Finance Intermediary Market Map.
Geographic coverage extends across every province and territory. Quebec contains 32.7% of mapped institutions, followed by Ontario at 25% and British Columbia at 12.9%. The geography chart is based on 752 institutions because location data weren’t available for every organization.
Assets are more concentrated than institution counts. Quebec holds 54.9% of total reported assets, largely because of the Desjardins caisse network. Ontario and British Columbia each account for approximately 14%.
Once credit unions are removed, Quebec’s share falls to 45.1%, Ontario’s rises to 40.1% and British Columbia accounts for 10%. Nova Scotia, Manitoba, New Brunswick, the Northwest Territories and Yukon remain lightly represented in the asset data.
The map shows that institutions exist across Canada. It doesn’t establish that every community has enough local financing capacity. NCFA’s review of rural financial access provides additional context on what happens when conventional financial infrastructure contracts in smaller and remote markets.
The detailed product analysis covers 202 products from 107 organizations. Private bonds and debentures account for 44.3% of the products studied, although they represent only 0.2% of reported product assets. Loan funds or equivalent products represent 20.9%, while private equity and venture capital funds account for 12.4%.
The CSI community bond campaign provides a current Canadian example. Individual and institutional investors supplied capital for community owned real estate while receiving defined interest rates and repayment terms.
Return expectations also distinguish these products from much of the conventional investment market. Among 91 products with disclosed return targets, 59.3% seek below market returns and 40.7% seek market rate returns. None of that sample targets an above market return.
Term information is available for 152 products. Nearly two thirds, or 62.5%, have terms of three to five years. This creates a practical consideration for investors because community outcomes and capital repayment often develop over several years.
Real estate is the leading investment focus. Of 192 products with disclosed objectives, 98, or 51%, support real estate activities such as affordable housing and green buildings. The most common United Nations Sustainable Development Goal alignment is SDG 11, Sustainable Cities and Communities, followed by themes connected to decent work, economic growth and reduced inequality.
The report gives Canada a common starting point for describing community finance. Its national map helps readers locate institutions, while its product data show how capital is structured, how long it may remain invested and what returns issuers target.
However, the figures shouldn’t be treated as a complete census of every institution or dollar. Asset information is incomplete at the individual organization level, particularly for Community Futures organizations and community land trusts. The 661 organizations added through the map also weren’t included in the detailed product analysis.
Several findings use smaller disclosure samples:
The provincial asset analysis combines Q4 2025 credit union data from the Canadian Credit Union Association and regulators with the core SVX collection. Quebec’s credit union figure includes an estimate for the Desjardins caisse network.
These limits don’t reduce the report’s value as a national baseline. They define how the figures should be used. Readers can compare institution types, product structures and geographic coverage, while avoiding claims that the dataset measures every community investment or proves the economic effect of the market.
A upcoming companion report, The Economic Case for Community Finance, is expected to examine job creation, enterprise growth, capital mobilization, government savings and potential returns from a national community finance strategy. That work should provide stronger evidence for evaluating community finance as an economic and public policy tool.
Talking Point: Canada now has a national view of the institutions involved in community finance. The next questions concern how much specialized capital reaches underserved communities, where financing gaps remain and which models can expand without losing their local purpose.
Community Finance In Canada Report (national market assessment, findings and methodology)
Catalyst Community Finance Collection (community investment products and participating organizations)
NCFA Weekly Fintech Intelligence Jul 18–24, 2026 (community finance figures and market context)
Canadian Impact Investing Platform SVX Launches (early development of Canada’s impact investment infrastructure)
Economic Case For Community Finance (scope for the forthcoming economic and policy study)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 27, 2026

Ask most fintech watchers what crowdfunding funds and you'll hear about startups, real estate, or the odd gadget. Rarely do card games come up first — yet tabletop projects have quietly become one of the strongest categories on reward-based platforms, and the numbers back that up. For anyone tracking alternative finance in Canada, it's a category worth a second look.
Reward-based crowdfunding was built for exactly this kind of project: a creator with a finished prototype, a passionate niche audience, and a product people can pre-order rather than just invest in blindly. Card and board games fit that mould almost perfectly. Backers aren't betting on a business plan — they're paying upfront for a physical thing they'll actually get to play.
Kickstarter's own 2024 year-in-review called it the biggest year for games in the platform's fifteen-year history, with $270 million pledged across games projects and 83% of that money going specifically to tabletop titles. That's not a niche curiosity anymore — it's a real slice of the alternative finance economy, funded entirely by individual backers rather than venture capital.
Canadian creators have been active participants in this shift for years, not just recent arrivals. Research on nearly 10,000 Canadian Kickstarter campaigns found that roughly a third succeeded — a reminder that reward-based crowdfunding, while accessible, still rewards a clear pitch and a product people genuinely want.
For creators, the appeal is obvious: no equity given up, direct validation from a real audience, and often enough working capital to cover a full print run. For backers, it's a chance to shape what gets made and get a game months before retail — assuming the campaign delivers, which isn't guaranteed.
Not every campaign is worth a pledge. Look for creators with a track record, a playable prototype (not just concept art), and a realistic production timeline. Comment sections and creator updates on past projects are usually more honest than the campaign page itself.
Whether or not you're backing the next big campaign, there's no shortage of ways to enjoy the category right now. Sites built around fun card games are a good starting point if you want to try something new without waiting for a shipping date.
It can be, but it favours creators who already have a working prototype and an existing audience. All-or-nothing platforms like Kickstarter mean the project only gets funded — and the creator only gets paid — if the goal is hit.
They combine a tangible reward, a built-in enthusiast community, and relatively low production complexity compared to, say, hardware or video games, which makes them easier to pitch and deliver.
No. Reward-based crowdfunding gives backers the product itself, not equity or royalties — that distinguishes it from equity crowdfunding, which is regulated differently in Canada.
Delayed or cancelled delivery. Even well-intentioned creators can underestimate manufacturing and shipping timelines, so backing is closer to a pre-order with extra risk than a guaranteed purchase.
Building an audience before launch, running a modest and achievable funding goal, and having a genuinely playtested prototype all correlate strongly with success, based on patterns across thousands of past Canadian campaigns.
Card games aren't a footnote in the crowdfunding world — they're one of its steadiest performers, and Canadian creators have a real track record within that space. For anyone watching where alternative finance is headed next, it's a category that keeps proving there's an audience willing to fund what they genuinely want to play.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 26, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Risk Compliance And Regtech, Payments And Market Infrastructure, Regulation And Policy, Treasury Liquidity And Cash Management

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026, Jun 6-12, 2026, Jun 13-19, 2026).
Credit unions now have a clearer way to test stablecoins, tokenized deposits and digital asset accounts inside member owned financial institutions. Banks, core providers, payments firms, fintechs and regulators should watch whether these early programmes become production deployments for real time settlement, deposit tokens and broader member access to digital assets.
Stablecoin issuer regulation is becoming an AML and identity control issue, not only a reserve or redemption issue. Issuers, banks, custodians, wallets, exchanges and compliance teams should prepare for customer identification, verification, recordkeeping and risk controls as payment stablecoin frameworks mature.
Stablecoin regulation is moving from policy design into operating rules for payment infrastructure. Issuers, banks, custodians, payment firms, exchanges, and fintechs should watch how reserve design, redemption rights, safeguarding, and systemic supervision shape market access for regulated digital money.
Tokenization platforms are entering public capital markets. Asset managers, broker dealers, transfer agents, custodians, exchanges and investors should watch how public company access, regulated ATS infrastructure and cross border digital securities permissions shape the next phase of tokenized fund and real world asset distribution.
Event contract markets are facing a sharper boundary test. Exchanges, brokers, prediction market platforms, sports leagues, tribal gaming authorities and regulators should watch whether Congress narrows the line between federally regulated event contracts and state regulated gambling.
Private market trading infrastructure needs audit rules that firms can apply before transactions scale. Companies, auditors, advisers, venues and investors should watch how PISCES treatment affects independence checks, audit committee planning, transaction readiness and the operating model for periodic private share trading.
Canadian issuer disclosure is becoming more digital by default. Public companies, transfer agents, investor relations teams, legal advisers and compliance staff need to adjust delivery controls, SEDAR+ workflows, investor notices and request handling before the new access model takes effect.
Canadian equity market structure remains tied to US implementation timelines. Trading venues, brokers, market makers, and technology teams need more time to adjust routing logic, fee models, tick increments, compliance controls, and systems that support trading in interlisted securities.
Tokenization is moving closer to regulated market infrastructure. Exchanges, brokers, clearing firms, custodians, digital asset platforms, and regulators should watch how traditional market operators and crypto venues build permissioned pathways for tokenized securities, futures access, custody, execution, and compliance. Similar infrastructure questions are also emerging in event contract markets as new regulated venues, distribution channels, and contract frameworks develop.
Bank AI adoption is moving from pilots to operating metrics. Financial institutions, fintech vendors, compliance teams, investors, and regulators should watch how large banks measure AI value, scale employee access, govern automation agents, and connect AI deployment to fraud control, onboarding, productivity, risk operations, and compute infrastructure markets.
Cross border payments are becoming a regulated corridor strategy. Exporters, payment firms, banks, compliance teams and fintechs should watch how RPAA registration, money services business obligations, local payout capability and bank account connectivity affect competition in Canada India payment flows.
Digital euro policy is becoming payment infrastructure design. The next test is how offline use, privacy controls, holding limits, fees, PSP distribution, and cash protection fit into a system that has to work across public money, private payment providers, and existing rails.
Mortgage distribution is becoming a stronger fraud, licensing, and consumer protection issue. Brokers, lenders, fintech mortgage platforms, compliance teams, and investors should watch how higher penalties, clearer licensing rules, and stronger supervision reshape risk controls in mortgage services.
Financial crime detection no longer depends only on what individual institutions can see. Banks, credit unions, payment service providers, securities dealers, fintechs and other reporting entities can now strengthen risk detection by sharing designated information, creating new opportunities for collaborative fraud controls, network analysis and anti money laundering investigations.
Regulatory enforcement is becoming more incentive driven. Banks, insurers, investment firms, credit unions and compliance teams should review how early investigation strategy, breach assessment, remediation evidence and senior accountability affect enforcement outcomes.
Audit reporting is becoming more focused on useful disclosure, controls evidence and investor readability. Companies, audit committees, auditors, governance advisers and compliance teams should prepare for updated report content, Provision 29 controls statements and revised audit workflows before the December effective date.
Firms need to know where encryption is used, which vendors are exposed, which systems protect high value data, and how long migration will take. Crypto inventory, procurement language, vendor assurance, and roadmap planning should start before compliance dates become delivery pressure.
A regulated operating company is using a tokenized money market fund for its own liquidity rather than presenting it as a future client product. That moves tokenization into daily treasury operations, where continuous access, settlement speed, custody controls and balance-sheet utility can be tested against conventional cash-management infrastructure.
Approval processes are becoming more transparent and predictable for eligible applicants entering or expanding within Canada's federally regulated financial sector. Banks, fintechs, federal credit union applicants and regulated financial institutions should watch how the framework affects application timelines, market entry, organizational changes and future supervisory expectations. For background, see NCFA's earlier coverage of the Streamlined Approvals Framework proposal.
Manitoba has put AI governance and cybersecurity inside the same statutory control structure for the public sector. The next test is implementation. Regulations will determine how far the province goes on human oversight, technical standards, incident reporting and vendor procurement, and whether those requirements become a practical benchmark for other Canadian governments.
Every week brings hundreds of announcements. Only a small number signal meaningful change. This week's developments point to new opportunities across payments, digital assets, AI, capital markets and regulation that could influence where innovation accelerates, investment flows and new business models emerge next.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016