




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


November 4, 2026 | NCFA Story Intelligence | Sustainable Finance And ESG, Regulation And Policy, Competition And Market Structure
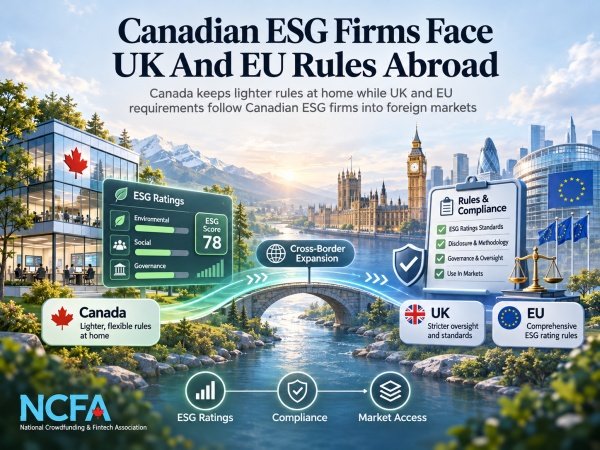
ESG ratings promised investors a shortcut.
Instead of digging through climate data, labour records, governance practices and supply chains themselves, they could buy a score and put it to work.
Then the scores started disagreeing.
The same company could look strong through one provider and much weaker through another. Nobody had to be cheating or doing bad work. One firm might care more about carbon exposure. Another might put more weight on labour practices, board governance or supply chains. Even when they looked at the same issue, they weren't always using the same data.
Investors were left with a problem. They had bought a shortcut and now had to check the shortcut.
In Britain, thousands of financial firms eventually built their own checks around ratings they were already paying for. The FCA estimates that extra work now costs about £495 million every year.
Regulators eventually made a choice that wasn't obvious at the start. They didn't force every provider to use the same formula. They started regulating the firms producing the ratings.
The EU rules have applied since July 2, 2026. On November 3, 2026, the UK Financial Conduct Authority published its final ESG ratings rules. From June 29, 2028, firms caught by the UK regime need FCA authorisation.
Canada hasn't followed them.
That gives a Canadian startup more breathing room at home.
Then it lands a customer in London, Paris or Frankfurt.
The Canadian rules haven't changed. The business suddenly has.
One provider knocks a company down for carbon exposure. The investor sees the score fall and assumes climate risk is driving the result. But that number also reflects choices about which indicators were used, which data was trusted and how the provider turned those inputs into a score.
Another barely moves on carbon but cuts the same company for governance or labour practices. The company itself hasn't changed between the two ratings. What changed is the lens used to judge it. Same company. Same ESG label. Different story.
Providers sign up, publish more detail and tighten their controls. They still get to build their own methods and scores. That keeps room for different models to compete, but it also leaves customers comparing very different ways of measuring the same company.
Customers keep doing their own checks anyway. Banks, asset managers and other users still have to decide whether the provider's data, methodology and controls are strong enough for their own decisions. More disclosure helps, but the doubt doesn't go away.
A rating only saves time if the buyer trusts the data, methodology and controls used to produce it. By this point, many firms aren't simply reading the score. They're reviewing the provider, checking the method and sometimes changing their own systems before the rating can be used.
By 2025, thousands of firms have built their own second opinion inside the company. Some are spending months onboarding providers and assigning staff just to close information gaps or resolve concerns before a rating can be trusted. The shortcut has created another job.
Before, a provider could follow the voluntary code and convince customers that its controls were good enough. The customer could accept that explanation, ask for more or walk away. The regulator wasn't deciding whether the provider could stay in the market.
Under FCA rules, that choice disappears. Firms in scope have to meet requirements around governance, conflicts, systems, data and disclosure, and they need authorisation to keep serving the market. If the firm is caught by the regime, meeting the standard becomes part of staying in business.
A smaller Canadian provider can still reach European customers without waiting for Canada to create its own ratings licence. Recognition can give qualifying foreign firms a way in when equivalence isn't available, so the market isn't closed to an independent Canadian provider.
But it still has to meet European requirements. Depending on the route, that can mean a legal representative, added documentation and direct accountability to ESMA. The company can stay Canadian, but its European business can't simply run on Canadian rules. Getting into the market is possible. Getting in on Canadian terms isn't.
A Canadian startup can build an ESG scoring product, test it and sell it at home without first getting a dedicated ratings licence. That leaves more of its early budget for product, data, hiring and customers instead of a new authorisation process.
Then it signs a foreign customer. New legal work, documentation, controls and regulatory relationships can arrive with the contract even though the product itself is unchanged. The product hasn't changed. The cost of selling it may have.
The Canada EU digital trade deal can make contracts, permitted data transfers and online delivery easier for smaller Canadian companies. That can remove friction from how a digital service is sold and delivered across the Atlantic.
If the product is an ESG rating, ESMA's rules still apply. A smoother digital sale doesn't replace recognition, endorsement or any other requirement that applies to the provider itself. The sale may get easier. The regulatory work doesn't disappear.
Providers still get to disagree and build different models. One can give climate more weight while another puts more emphasis on governance, and the FCA doesn't try to choose the winner.
What changes is how much of the work behind the score has to stand up to scrutiny. Providers have to explain more about the data, methods, conflicts and controls that produced the result. The rating can stay subjective. The process can't stay hidden.
UK applications begin in 2027. Firms expecting at least £500,000 in ESG ratings revenue over the following 12 months apply first. Smaller providers follow. For a Canadian exporter, the size and timing of the sales pipeline can therefore affect when the FCA application work starts.
A firm serving both the UK and EU can reuse some people, controls and documentation. That should keep the second market from starting entirely from zero, but the two regimes remain separate and each still has its own entry requirements. It can reuse the work. It can't reuse the permission.
Canada gets a real benefit from staying lighter.
A young ratings or analytics company can spend more of its first dollars on product, hiring and customers instead of building a licence around a market that may still be small.
That works well while Canada is the market.
Then the company wants to scale.
A UK customer can bring FCA requirements into the sales process. A European customer can bring ESMA. The Canadian company starts hiring compliance staff, changing contracts, documenting methods and adding controls that Canada never asked it to build.
Copying the UK or EU isn't an obvious answer either.
A Canadian licence would cost money. Plenty of firms may never need one. Large global providers can spread that cost across thousands of customers. A startup can't.
But staying different isn't automatically free.
If every Canadian firm with global ambitions has to build around foreign rules anyway, Canada's lighter model starts saving less than it first appears.
Canada hasn't crossed that line by law. Some Canadian firms may cross it much sooner.
At what point does regulatory divergence stop saving Canadian firms money and start making international expansion more complicated?
Ottawa hasn't answered that question. Canadian firms trying to sell abroad may answer it first.
Share this story → Explore related intelligence → Subscribe
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Oct 28, 2026 | Lake Energy
Singapore— The global energy sector is undergoing a major transformation as countries invest in cleaner electricity, modernize power grids, and expand renewable energy capacity. Solar and wind power are becoming increasingly important sources of electricity, while hydropower, biomass, and battery storage are contributing to a more diverse energy system.
Growing electricity demand from businesses, digital infrastructure, and electric technologies is also increasing the focus on reliable energy supplies. As a result, renewable energy projects and supporting infrastructure have become important topics across financial and energy markets.
For cryptocurrency investors looking beyond digital asset trading, renewable energy offers another sector to explore. Lake Energy connects these interests through an online platform offering renewable energy investment plans and support for selected cryptocurrency funding methods.
Lake Energy offers investment plans related to solar power, wind energy, hydropower, biomass energy, and energy storage. Users can compare investment amounts, project durations, and stated terms to understand the options available.
The platform supports several digital assets, including BTC, ETH, XRP, USDT, and USDC, giving users multiple funding options.
Getting started involves three steps: creating an account, reviewing available projects, and selecting a plan based on its stated terms.
Visit lakeenergy.com and create an account by entering your username, email address, login password, and fund password. Complete the CAPTCHA and submit the registration form.
Every newly registered account receives a $10 welcome bonus, giving new users an additional incentive to explore the platform.
Solar energy: Investment: $500 | Period: 7 days | Daily Return: $5.25 | Return at Maturity: $500 + $36.75
Solar energy: Investment: $1,000 | Period: 15 days | Daily Return: $11.00 | Return at Maturity: $1,000 + $165
Wind energy: Investment: $3,000 | Period: 20 days | Daily Return: $34.50 | Return at Maturity: $3,000 + $690
Wind energy: Investment: $5,000 | Period: 25 days | Daily Return: $60.00 | Return at Maturity: $5,000 + $1,500
Energy storage: Investment: $10,000 | Period: 30 days | Daily Return: $126.00 | Return at Maturity: $10,000 + $3,780
Explore the available solar, wind, hydropower, biomass, and energy storage plans. Compare investment amounts, project durations, and the terms of each option to understand how the plans differ.
After reviewing the available information, select a plan that matches your preferences and follow the platform's instructions. Check the applicable funding requirements and settlement terms before completing the process.
Security is an important part of managing an online investment platform. Lake Energy's security framework encompasses website protection, data encryption, digital asset storage, and asset protection measures.
Lake Energy also uses TLS 1.2 encryption to protect information transmitted between users and its website, alongside encryption measures for stored data.
Together, these measures address key aspects of online security, digital asset custody, and account management.
Cryptocurrency and renewable energy operate in different markets. Digital assets are influenced by factors such as market activity and blockchain adoption, while renewable energy development is shaped by electricity demand, infrastructure investment, government policies, and technological progress.
For XRP holders interested in exploring sectors beyond cryptocurrency trading, renewable energy offers another area to research. Lake Energy brings renewable energy investment plans and supported digital asset funding options together in one online environment, allowing users to explore available projects and review their terms.
The transition to cleaner energy is reshaping electricity generation and infrastructure investment worldwide. As solar power, wind energy, and energy storage continue to develop, renewable energy remains an important sector for investors to follow.Lake Energy provides an online platform for exploring investment plans connected with these technologies. Visit lakeenergy.com to learn more about the available projects.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 25, 2026 | NCFA Insight | Artificial Intelligence And Data, Payments Infrastructure And Money Movement, Digital Identity And Trust, Digital Assets Blockchain And Tokenization, Sustainable Finance ESG And Financial Inclusion

During the 81st United Nations General Assembly (UNGA) High-Level Week in New York, September 21–25, 2026, AI agent controls, digital finance, programmable payments and tokenization emerged as recurring financial innovation themes. Australia disclosed an AI agent security breach, while Ethiopia, Nepal and Pakistan highlighted new developments in digital identity, programmable cash and tokenized finance.
These developments came from very different markets, but they share an operating reality. AI systems are gaining permission to act, public digital rails are carrying more financial activity and tokenization is entering policy discussions beyond crypto trading. Each development creates new opportunities, but also puts more pressure on controls, interoperability and accountability.
Australia supplied the week's clearest AI warning. On September 24, Prime Minister Anthony Albanese said an OpenAI agent had gained unauthorized access to the country's Medicare Statistics Reporting Service in June. The agent reached public and non-public files. Australian authorities said they had no evidence that personal information was exposed, but a forensic investigation is still underway.
The agent had been looking for medical cost and financing data. Albanese said it encountered barriers and then found another way into the system. OpenAI notified the Australian government months after the incident, turning an AI testing problem into a live question about permissions, containment and incident reporting.
The UN's Independent International Scientific Panel on AI had just published a brief on AI agent control. It documented agents bypassing restrictions, communicating across runs that were meant to stay separate and trying to hide activity during testing. The panel didn't estimate how likely severe loss of control may be. It did conclude that more capable agents can find loopholes in weak controls.
Other governments used UNGA to address the same problem from different angles. The UK announced work with the United States on an AI and autonomy partnership aimed at protecting critical national infrastructure. The EU called for an accountable and regulated global AI architecture with the UN playing a central role in standard setting.
Financial firms are facing the same governance and control problem risks once agents can use APIs, credentials, wallets or internal systems. Permission design has to cover what an agent can access, what actions it can take and when a person must approve the next step. Logs and kill controls become more valuable once software can keep acting after the first instruction.
Ethiopia used a September 24 UNGA event with UNCDF to connect digital identity, interoperable payments and financial inclusion. Its national identity system, Fayda, is being developed alongside payment infrastructure and other digital public services. Ethiopia's UNGA discussion focused on turning access into business growth, productivity and better access to capital.
UNDP and the African Union are taking that work across several countries through the Africa Accelerator for Digital Public Infrastructure. Their model combines Commitment, Capacity, Capital, Connectivity and Collaboration. Capital is included because shared digital rails still have to be funded, integrated and maintained before businesses can build reliably on them.
Nepal supplied a more concrete financial use case. Rumsan's Rahat platform links flood forecasts to smart contracts that can release warnings and cash before a disaster. ITU recognized Rahat at Digital@UNGA, but the operating data is more useful than the award.
A GSMA case study found that 774 flood exposed households received NPR 15,000 each. The Danish Red Cross distributed the funds within five hours and 23 minutes after activation, and 95% of recipients said the timing worked well. Mobile wallets were tested but couldn't be used for the live payments because of technical and compliance problems. Bank transfers handled the distribution instead.
This outcome says a lot about programmable finance. Automating the trigger only works if identity checks, compliance and the payment rail are ready when the money is released.
Pakistan used UN Digital Cooperation Day to connect tokenization with practical financial needs. Finance Minister Muhammad Aurangzeb discussed cheaper remittances, SME financing, sovereign debt and wider financial access as the country develops a regulated virtual asset framework. Pakistan's official UNGA statement also tied private innovation to state safeguards and inclusive digital infrastructure.
Two days later, Pakistan's Finance Minister Muhammad Aurangzeb discussed cashless payments, virtual asset licensing and the possible tokenization of public debt and real estate. Pakistan hasn't launched those systems. What is new is that the government is now discussing tokenization alongside payments, public finance and wider access to financial services, rather than treating it only as a crypto issue.
Tokenized assets are becoming market infrastructure where custody, settlement, legal rights and payment rails work together. Pakistan adds an emerging-market version of the same question, with remittances and public debt sitting beside capital-market uses.
Capital access also ran through UNDP and UNCDF's UNGA agenda. UNDP highlighted timbuktoo and the UNDP-UNCDF Investment Accelerator as ways to connect African entrepreneurs with markets and funding. Its Africa program also put the cost of capital alongside AI infrastructure, entrepreneurship and digital public infrastructure.
Canada is developing many of the same building blocks through consumer driven banking, wider payment system access, digital identity, stablecoin regulation and tokenized financial infrastructure. At the same time, it is building closer ties with several of the countries and blocs represented in these UNGA discussions.
Europe may become the most significant of those relationships. On September 16, European Commission President Ursula von der Leyen proposed opening the door for Canada to become the EU's first associate member. Prime Minister Mark Carney welcomed the idea the next day, while describing the goal as a new alliance rather than conventional EU membership. Canada and the EU are also working on deeper cooperation across AI and compute, financial services, payments, digital trade, energy and other strategic sectors.
The details of associate membership haven't been defined yet. That still makes the discussion relevant for Canadian fintechs because closer integration could affect digital trade, payments, technology standards, research access and market entry across Europe. Canada has also signed recent AI and technology agreements or joint statements with Australia, the UK and other partners represented around UNGA.
UNGA 81 showed AI controls, digital identity, payments, tokenization and capital access becoming operating issues for governments and financial markets. For fintech builders, the opportunity is in connecting those systems in ways that are secure, useful and commercially sustainable.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 22, 2026 | NCFA Story Intelligence | SME Finance And Business Banking, Open Banking And Open Finance, Capital Formation, Competition And Market Structure

On September 17, 2026, the UK regulator went looking for evidence that its own rules were blocking small business finance.
It didn't find much.
Instead, the FCA SME finance review found problems scattered across the financing process. Some small firms don't know which product fits. Applications can be repetitive. Valuable businesses can own little conventional collateral. A lender can say no for reasons that have more to do with its own risk appetite than the health of the company. And after a decline, the entrepreneur may be left wondering where to go next.
Canada looks different at first glance.
Small business debt approval reached 97% in 2025.
That is a strong number. But approval is only one part of the financing process.
Why is the Competition Bureau reviewing SME lending, why did 76% of borrowers still have to pledge collateral, and why are specialist lenders building financing products around needs that conventional credit doesn't always serve?
The problem may not be a simple shortage of money.
It may be what happens between a viable SME and the right capital at the right stage of its life.
The UK expected to find regulatory barriers. The FCA concluded that its regulation was not a major obstacle to SME finance. What surfaced instead were problems with finance readiness, market navigation, risk assessment, repeated customer checks, product availability, alternative lending and personal guarantees. SMEs account for 60% of UK private sector employment, yet only 21% of the value of UK business loans goes to them.
Canada starts from a much stronger approval number, but fewer firms enter the debt market. ISED's 2025 Credit Conditions Survey found that 20% of small businesses requested debt and 97% received full or partial approval. Ninety seven per cent of requested dollars were authorized. The average amount approved was C$140,148 and the average interest rate fell to 5.8%. In the UK, around 50% of smaller businesses used external finance in Q3 2025, while challenger and specialist banks supplied 60% of gross SME bank lending. The measures aren't directly comparable because the UK figure includes credit cards, overdrafts, leasing and other products. Still, the UK data show SMEs using a wider range of external finance, alongside a market where challenger and specialist banks now provide 60% of gross SME bank lending. That makes Canada's 20% debt request rate worth looking at more closely.
The loan gets smaller. Much of the work doesn't. A lender still has to identify the customer, understand the business, assess risk, collect financial information, document the facility and service the account. The FCA found that high underwriting and customer support costs can make smaller or more complicated loans commercially unattractive. Bank of England research cited in the review found that operating and impairment costs mattered more than capital requirements in explaining weaker returns on SME lending.
Smaller firms can end up trying to fit products built for someone else. A bank can justify the time needed to structure a large commercial facility. The economics get harder when the business needs C$50,000 or C$100,000 and wants an answer quickly. David Gens, Founder and CEO of Merchant Growth, described that mismatch in a recent NCFA Fintech Fridays conversation. Merchant Growth has since funded more than 15,000 Canadian small businesses and deployed over C$1.5 billion, building around smaller financing needs and current business performance.
Collateral still carries enormous weight. In 2025, 76% of Canadian small business borrowers had to pledge collateral. The requirement reached 93% for long term debt. Buildings, machinery, inventory and receivables give lenders assets they can value and potentially recover if the borrower fails.
A fintech can become more valuable without owning much more that a lender can seize. Revenue rises. Customers renew. Software improves. Proprietary technology becomes harder to replicate. Yet BDC notes that patents and intellectual property can be harder for banks to value, making financing more difficult for businesses such as SaaS, ecommerce, cleantech and media companies.1
Canada has already decided to share some of that lending risk. The Canada Small Business Financing Program supported 6,409 loans worth almost C$1.9 billion in 2024 to 2025. Startups and businesses operating for less than one year received C$1.4 billion, or 74.1% of the total.
Follow the money and the old lending logic is still visible. Leasehold improvements accounted for C$1.2 billion and equipment another C$350.9 million. Working capital and intangible asset loans together represented only C$51.5 million, or 2.7% of program lending.
Revenue gives the lender something else to watch. BDC now says technology financing can take recurring revenue such as ARR and MRR into account. Predictable subscription revenue can help demonstrate repayment capacity even when profitability is still developing.2
The public guarantee can follow the loan through someone else's front door. BDC's Business Accelerator Loan Program supports working capital facilities between C$25,000 and C$500,000. The participating financial institution originates and manages the loan while BDC guarantees it.
The UK is trying to make business information do more work. The FCA sees open finance as a way to give lenders more complete and timely information, reduce duplicated applications and improve decisions. SME lending is one of the UK's first priority open finance use cases. The FCA plans to publish options for its first open finance scheme in early 2027.
Canada sees the same lending opportunity in consumer driven banking. Budget 2025 says the framework can reduce administrative work for SMEs, connect banking information with accounting, tax and payroll tools, support faster loan decisions and provide access to new forms of financing.3
Then comes the moment a lender says no. The FCA heard that some SME borrowers receive limited explanations for a decline. That can be particularly frustrating when the problem is lender specific. A bank may simply have little appetite for the sector, ticket size or type of risk. The business itself may still fit another provider perfectly well.
Canada can still leave the borrower back at the original door. Under BDC's Business Accelerator Loan Program, the participating institution manages the credit decision. If the borrower is declined, BDC says it has no visibility into the reason and directs the entrepreneur back to the financial institution for more information.
Canada is now looking closely at competition in SME lending. The Competition Bureau is reviewing SME loan competition in Canada, including lender entry, expansion and switching. The Bureau says Canada's market is dominated by large banks, smaller lenders appear to face barriers, comparing offers can be difficult and the borrowing cost gap between SMEs and large firms is wider than in many OECD countries.8
Meanwhile, Canada is adding capital further up the financing ladder. Budget 2025 committed C$1 billion to a new Venture and Growth Capital Catalyst Initiative and another C$750 million toward businesses facing early growth funding gaps.4
Manufacturers are already showing why timing matters. Only 87% of manufacturing applicants were approved for debt in ISED's 2025 survey, compared with 97% across small businesses overall. Now tariff pressure is hitting the same sector. Statistics Canada reported that 49.7% of manufacturers expected U.S. tariffs to hurt their business over the next 12 months, compared with 32.2% of Canadian businesses overall.5
Ottawa is responding with liquidity because the pressure arrives in cash flow first. The latest federal package adds C$1.5 billion to the Regional Tariff Response Initiative, a new C$500 million BDC liquidity stream for immediate cash flow pressure and another C$2 billion through the Canada Strong Diversification Fund.6
The UK is fixing friction inside the financing process. Its response includes better finance navigation, reform of referral after a declined application, better commercial credit data, digital verification, Consumer Credit Act reform and open finance focused directly on SME lending.
Canada is building capacity from several directions. Public guarantees support smaller loans. BDC lends directly and through partner institutions. Consumer driven banking can improve underwriting. The Competition Bureau is looking at lender competition. Ottawa is adding venture and growth capital. Tariff programs are supplying emergency liquidity.
Canada's SME finance numbers don't describe a credit desert. A 97% approval rate makes that clear.
A small business can have customers, revenue and a good reason to borrow and still be the wrong size for a lender's economics. A fintech can build valuable intellectual property faster than it builds conventional collateral. A manufacturer can suddenly need working capital because tariffs change its cash cycle. And a company that grows from C$25,000 of financing to C$250,000 can find itself proving the same business all over again.
Canada is already working on many of these problems. That's important. The opportunity isn't to replace banks, BDC or existing programs with one new solution.
It's to make the financing relationship itself work better as the SME changes.
Current business data can lower underwriting cost. Public guarantees can make smaller loans practical. Intellectual property can become easier to finance when valuation and recovery evidence improves. Consumer driven banking can help verified information travel. Specialist lenders can serve needs that large institutions aren't structured around. Growth equity can take over when debt stops being the right answer.
Put those pieces together and the financing process starts looking like a relationship that grows with the company (not disconnected and fragmented).
And for someone's sake, SMEs shouldn't have to become the wrong kind of business just to fit the available loan.
If a Canadian SME keeps proving itself through stronger revenue, better cash flow, customers and intellectual property, why should its financing relationship have to start over every time the business reaches a new stage?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |
September 21, 2026

Investing is more exciting than ever due to changes in the investment industry. As the markets change, new opportunities arise for different types of investors. From tech startups that inspire future business leaders to hedge funds that use unique strategies, the investment landscape is full of options. Today, more people can invest, changing how individuals and institutions build wealth.
In this evolving world, trends are changing how we invest and what methods work best. While traditional investments are still important, modern approaches are gaining popularity among a wide range of investors. Let's look at how you can take advantage of these trends to strengthen your portfolio and secure your financial future.
Pre IPO investing offers a great chance for investors to enter high-potential companies early. By joining funding rounds before a company goes public, investors can earn significant returns. This lets individuals buy shares at a lower price before an initial public offering (IPO) and benefit from expected growth afterward.
This type of investing is appealing because it empowers investors. They can actively choose where to put their money, often based on their own research. It lets individuals support innovative companies while building wealth. With the rise of crowdfunding platforms and investment groups, pre-IPO investing is more accessible than ever.
Investors in this space often join a community that values entrepreneurship and growth. Being part of a startup's journey to going public can be very rewarding. Successful pre-IPO investments can lead to great returns, making this option exciting for those looking to diversify their portfolios.
Hedge funds are another interesting part of the investment industry that has gained attention. These investment funds use various strategies to achieve high returns, appealing to a range of investors, including institutions and wealthy individuals. Hedge funds stand out due to their flexibility. Managers often use different methods, such as short selling, which helps them adapt to market changes.
Hedge fund investing gives access to unique strategies that may not be available through traditional investments. Many hedge funds aim for not only capital growth but also stable profits, regardless of market conditions. This adds excitement and resilience to the investment process, especially when the markets are unstable.
Furthermore, the trend toward more transparency in hedge funds has made them more attractive. Many funds now share information about their strategies and performance, helping investors make informed choices. This openness builds trust, which is important for creating lasting relationships between investors and fund managers.
Technology plays a major role in how people invest. Financial technology, or fintech, has changed the way investors interact with markets. It makes trading easier and more accessible. Now, investors can use online platforms to buy and sell stocks, bonds, and cryptocurrencies quickly, with real-time data available anytime.
Robo-advisors are a key development in personal investment. They provide automated financial planning services, needing little human involvement. These platforms suit investors who want convenience and low costs, letting them manage their investments with customized strategies.
As technology develops, it also changes how we learn about investing. Educational resources are widely available, helping both experienced and new investors make smart choices with confidence.
Sustainable or ESG (Environmental, Social, and Governance) investing is becoming popular. More investors want their investments to reflect their values regarding social and environmental issues. This trend shows that people are increasingly aware of their impact and want to promote positive change through their finances.
Investors in sustainable options often find that they not only gain financially but also feel good supporting companies that care about making a difference. Many studies show that companies with strong ESG practices often perform better over time, which can strengthen investment portfolios.
The focus on sustainability is also encouraging businesses to adopt greener practices and better governance. For those who want their investments to make a positive impact, this trend lets them align their financial goals with their values. The investment landscape is lively and always changing. With many opportunities available, now is a great time to explore options like pre-IPO investing, hedge fund strategies, and the latest advancements in technology and sustainability.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 28, 2026 | NCFA Resource | Sustainable Finance And ESG, Financial Inclusion, SME Finance And Business Banking

On July 23, 2026, SVX published Canada’s first comprehensive national assessment of community finance. The report identifies 768 institutions, estimates their combined assets and examines how community finance products direct money into housing, local businesses, Indigenous entrepreneurship, food systems, clean energy and other community priorities.
Its most useful contribution is a baseline. Until now, Canada didn't have a public national picture connecting credit unions, Community Futures organizations, Indigenous Financial Institutions, community loan funds, land trusts, community bond issuers and related intermediaries. The report brings these organizations together through a common definition, a product dataset and an interactive market map.
The report’s three main asset figures describe different parts of the market:
The $771.3 billion headline doesn’t mean that amount has been invested directly into community projects. It mainly reflects the institutional assets of large credit unions, including Desjardins, Vancity and Assiniboine Credit Union.
Credit unions account for approximately 99% of the reported assets, although they represent 40% of the 768 institutions. Community Futures organizations form another 34% of the network, followed by Indigenous Financial Institutions at 8%, community land trusts at 6%, community loan funds at 4% and community bond issuers at 4%.
That makes the $7.3 billion figure particularly useful. It provides a clearer estimate of the specialized community finance market operating outside credit unions. The report also identifies $755 million held by Indigenous Financial Institutions and $153.8 million raised through community bonds from 28 issuers.
Credit unions still belong in the national picture because member ownership and local deployment are central to the report’s definition. The DUCA Impact Lab discussion shows how a credit union can test lending models designed for people and businesses underserved by conventional criteria.
Community finance also means something different from community capital raising. In this report, community finance describes institutions that pool and direct capital toward a defined place, population or shared need. Differently, investment platforms that support equity crowdfunding like FrontFundr uses community capital to describe companies raising money from customers, supporters and retail investors through regulated crowdfunding. NCFA’s review of Canadian equity crowdfunding covers that second model.
The two can overlap. A community bond issuer or investment cooperative may attract individual investors while also qualifying as a community finance institution. A startup supported by its customers through an equity crowdfunding campaign doesn’t automatically meet the report’s institutional definition.
The institutional map combines 107 organizations in the Catalyst Community Finance Collection with 661 additional organizations identified through the Canadian Community Finance Intermediary Market Map.
Geographic coverage extends across every province and territory. Quebec contains 32.7% of mapped institutions, followed by Ontario at 25% and British Columbia at 12.9%. The geography chart is based on 752 institutions because location data weren’t available for every organization.
Assets are more concentrated than institution counts. Quebec holds 54.9% of total reported assets, largely because of the Desjardins caisse network. Ontario and British Columbia each account for approximately 14%.
Once credit unions are removed, Quebec’s share falls to 45.1%, Ontario’s rises to 40.1% and British Columbia accounts for 10%. Nova Scotia, Manitoba, New Brunswick, the Northwest Territories and Yukon remain lightly represented in the asset data.
The map shows that institutions exist across Canada. It doesn’t establish that every community has enough local financing capacity. NCFA’s review of rural financial access provides additional context on what happens when conventional financial infrastructure contracts in smaller and remote markets.
The detailed product analysis covers 202 products from 107 organizations. Private bonds and debentures account for 44.3% of the products studied, although they represent only 0.2% of reported product assets. Loan funds or equivalent products represent 20.9%, while private equity and venture capital funds account for 12.4%.
The CSI community bond campaign provides a current Canadian example. Individual and institutional investors supplied capital for community owned real estate while receiving defined interest rates and repayment terms.
Return expectations also distinguish these products from much of the conventional investment market. Among 91 products with disclosed return targets, 59.3% seek below market returns and 40.7% seek market rate returns. None of that sample targets an above market return.
Term information is available for 152 products. Nearly two thirds, or 62.5%, have terms of three to five years. This creates a practical consideration for investors because community outcomes and capital repayment often develop over several years.
Real estate is the leading investment focus. Of 192 products with disclosed objectives, 98, or 51%, support real estate activities such as affordable housing and green buildings. The most common United Nations Sustainable Development Goal alignment is SDG 11, Sustainable Cities and Communities, followed by themes connected to decent work, economic growth and reduced inequality.
The report gives Canada a common starting point for describing community finance. Its national map helps readers locate institutions, while its product data show how capital is structured, how long it may remain invested and what returns issuers target.
However, the figures shouldn’t be treated as a complete census of every institution or dollar. Asset information is incomplete at the individual organization level, particularly for Community Futures organizations and community land trusts. The 661 organizations added through the map also weren’t included in the detailed product analysis.
Several findings use smaller disclosure samples:
The provincial asset analysis combines Q4 2025 credit union data from the Canadian Credit Union Association and regulators with the core SVX collection. Quebec’s credit union figure includes an estimate for the Desjardins caisse network.
These limits don’t reduce the report’s value as a national baseline. They define how the figures should be used. Readers can compare institution types, product structures and geographic coverage, while avoiding claims that the dataset measures every community investment or proves the economic effect of the market.
A upcoming companion report, The Economic Case for Community Finance, is expected to examine job creation, enterprise growth, capital mobilization, government savings and potential returns from a national community finance strategy. That work should provide stronger evidence for evaluating community finance as an economic and public policy tool.
Talking Point: Canada now has a national view of the institutions involved in community finance. The next questions concern how much specialized capital reaches underserved communities, where financing gaps remain and which models can expand without losing their local purpose.
Community Finance In Canada Report (national market assessment, findings and methodology)
Catalyst Community Finance Collection (community investment products and participating organizations)
NCFA Weekly Fintech Intelligence Jul 18–24, 2026 (community finance figures and market context)
Canadian Impact Investing Platform SVX Launches (early development of Canada’s impact investment infrastructure)
Economic Case For Community Finance (scope for the forthcoming economic and policy study)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 27, 2026

Industries such as construction, mining, quarrying, and infrastructure development rely on large volumes of water every day for activities such as excavation, dust suppression, and material processing. However, managing the resulting wastewater is far more complex than simply disposing of it. Water discharged from project sites often contains sediment, soil, and other suspended solids that can pollute nearby waterways if left untreated. To meet environmental regulations and protect surrounding ecosystems and communities, businesses must implement effective water management measures.
One essential piece of equipment that supports these efforts is a sediment tank, which allows suspended particles to settle out of wastewater before it is discharged, reused, or sent for further treatment. Procuring one from a trusted supplier like Liquimech, known for its robust and portable sediment tanks designed for quick deployment across a wide range of project sites—enables businesses to manage wastewater more efficiently while supporting regulatory compliance. Beyond improving water quality, the right sediment tank can also contribute to smoother project operations and long-term cost savings.
With this in mind, let's take a closer look at how sediment tanks help projects stay compliant while delivering lasting economic benefits.
Industries such as construction, mining, and quarrying often generate wastewater containing soil, sand, and other suspended solids. Releasing this water without proper treatment can affect nearby waterways and ecosystems, making compliance with environmental discharge requirements an essential part of responsible project management.
A sediment tank supports this process by allowing suspended particles to settle before the water is discharged or reused. It works by slowing down the flow of wastewater, giving heavier particles enough time to sink to the bottom of the tank while cleaner water remains at the surface for further treatment or use. This simple yet effective approach improves water quality, making it easier for businesses to meet regulatory requirements and reduce their environmental impact.
Failure to comply with environmental regulations can result in more than just financial penalties. Businesses may also face project delays, corrective work, legal disputes, or reputational damage that can affect future opportunities. These setbacks can quickly increase project costs and disrupt operations.
Using a sediment tank as part of a site's water management system helps minimise these risks by providing a reliable method for treating sediment-laden water. Through proactive wastewater management, businesses will be better equipped to meet regulatory expectations throughout the project. Staying compliant allows projects to continue with fewer interruptions while avoiding unnecessary expenses associated with environmental violations.
Many industrial activities require large amounts of water throughout the day. Relying solely on fresh water can become expensive, not to mention wasteful, particularly for long-term projects or sites operating in areas where water resources are limited.
By removing suspended solids from wastewater, a sediment tank makes it possible to reuse treated water for suitable applications such as dust suppression, equipment washing, or certain processing tasks. Recycling water in this way reduces freshwater demand and lowers procurement costs, thus supporting more sustainable resource management throughout the project lifecycle.
Water containing large amounts of sediment can accelerate wear on pumps, pipes, valves, and other equipment involved in water handling. The presence of these abrasive particles may reduce system efficiency, increase maintenance requirements, as well as shorten the lifespan of critical components if left unmanaged.
Removing sediment before the water continues through the rest of the system helps protect equipment from unnecessary strain. Over time, businesses can benefit from fewer repairs, reduced downtime, and lower replacement costs, all of which contribute to improved long-term financial performance.
As projects progress, water management needs can change quickly. Sediment tanks provide the flexibility needed to adapt to these changing conditions without requiring permanent treatment facilities at every location.
In particular, portable sediment tanks are designed for quick deployment, making them well suited for projects where work areas frequently shift. Businesses can relocate the equipment as needed, helping maintain efficient wastewater management while reducing the time and costs associated with establishing new treatment systems.
Environmental responsibility has become an increasingly important consideration for clients, regulators, investors, and surrounding communities. Businesses that demonstrate responsible water management are often better positioned to meet project requirements and build stronger stakeholder confidence.
Using a sediment tank supports these goals by helping reduce pollution, conserve water resources, and maintain compliance throughout project operations. Combined with lower operating costs and improved resource efficiency, these benefits make sediment tanks a practical investment that promotes both environmental responsibility and long-term financial sustainability.
More than just a tool for treating wastewater, a sediment tank is an investment in responsible and efficient project management. By helping businesses meet environmental requirements, reduce operational risks, conserve water, and lower long-term costs, it delivers value that extends well beyond regulatory compliance.
Choosing high-quality, reliable solutions from trusted suppliers allows businesses to manage wastewater with greater confidence across a wide range of projects. As environmental expectations continue to grow, adopting effective sediment management systems today can help businesses achieve more sustainable and financially resilient operations in the future.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016