





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


January 27, 2026 | NCFA Resource | Open Banking And Consumer Driven Finance, Risk Compliance And Regtech, Artificial Intelligence And Data
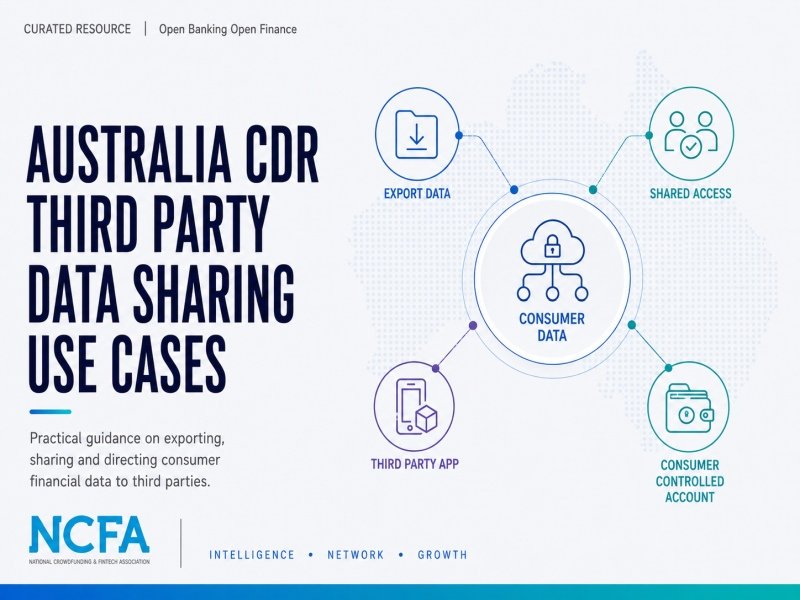
On January 27, 2026, Australia’s Consumer Data Right updated its Third Party Data Sharing Use Cases with practical examples showing how consumers can export financial data, give another person access, send data to another application or direct it into an account they control.
The Australian Competition and Consumer Commission developed the guidance with input from Treasury. It tackles a straightforward product question. After an accredited provider receives a consumer’s financial data, what can the consumer do with it next?
The answer depends on who initiates the sharing, where the information goes and who controls the destination. Those details affect consent, privacy and the provider’s responsibilities.
The guidance organizes third party sharing into four situations:
Who initiates the sharing is the key distinction. The ACCC says these consumer directed scenarios are unlikely to raise compliance concerns when the consumer makes a clear and informed choice. Downloading data, configuring access or instructing the provider to send information helps establish that the consumer chose the disclosure.
If the provider is making the disclosure itself, the permitted use and disclosure rules apply. The provider needs the authority and consent required under Australia’s Consumer Data Right rules.
That difference becomes concrete in product design. Letting someone download transaction history for personal analysis carries different responsibilities from automatically sending customer information to another company. Giving an accountant controlled access inside an SME finance platform is also different from transmitting the data outside that service.
Where the financial data remains inside the accredited provider’s service, the provider continues to carry the relevant Consumer Data Right obligations. These include privacy safeguards covering data security and the destruction or de-identification of information that is no longer required.
When consumers send their data outside that environment, they need to know how the recipient will handle it. The ACCC says providers should explain that other privacy laws may apply and encourage consumers to review the recipient’s data handling policies.
The same framework can support a single disclosure or recurring sharing for a defined period. The provider must hold the collection and use consents required for the service. Consumer Data Right consent generally lasts for up to 12 months, while some business consumer consents can extend for up to seven years.
Fintech product teams can use these examples when building financial data portability into real services. A personal finance app could let customers export transaction data for their own analysis. An SME platform could give an accountant controlled access to business records. A lending or cash flow application could let customers send selected information into another service they already use.
Compliance and legal teams can review the same features by asking a few direct questions. Who initiated the disclosure? Who controls the destination? Does the information stay inside the accredited service? What consent supports the sharing? Which obligations continue once the data leaves?
Banks and other financial institutions can use the examples to anticipate how customers may expect data portability to work. Consumers are unlikely to organize their behaviour around regulatory terminology. They will want financial information to work with budgeting software, accounting systems, lending applications, analytics tools and other services they choose.
Canada will face similar product questions as Consumer Driven Banking reaches implementation. Canada Open Banking And Consumer Driven Banking Rules tracks accreditation, authentication, consent, data sharing, security and liability requirements. Australia’s examples show what product teams have to consider after the first regulated transfer, when a customer wants to reuse the information somewhere else.
Standardized financial data can support credit assessment, fraud detection, cash flow analysis and financial guidance as well. NCFA’s Open Banking Decision Intelligence looks at how firms can turn permissioned financial data into better decisions. Third party sharing gives consumers and businesses more control over which tools can participate in those workflows.
The four examples are specific enough to use in product and compliance discussions. Teams can look at an export button, an accountant access feature, an application-to-application transfer or recurring sharing arrangement and ask exactly who controls the data at each point.
The guidance also shows why interface design and compliance cannot be separated. A button that lets the consumer choose where information goes can create a different regulatory position from a service that sends the same information on its own. Consent, control of the destination and whether the provider continues to hold the data all affect the answer.
That's useful context for Canadian teams working through consent and downstream data use. Canada can define who participates in regulated sharing and how financial institutions transfer data to accredited recipients. Customers will still want to download that information, share it with professionals, use it in another application or authorize access over time.
Australia’s rules do not determine what Canadian firms can do. The two countries have different legislation, privacy requirements, accreditation models and regulatory terminology. The Australian examples are useful because they expose practical questions Canadian product, compliance and policy teams will also have to answer.
The ACCC also makes clear that the article is general guidance. Whether a particular implementation complies with Australia’s Consumer Data Right depends on the circumstances, and providers remain responsible for assessing their legal obligations.
Consumer Data Right (Australian framework, participants and consumer information)
Legal Obligations For Data Recipients (collection, consent, use and disclosure requirements)
CDR Privacy Safeguard Guidelines (privacy requirements for handling consumer financial data)
Canada’s Open Banking Strategy Starts With Trust (consent, fraud, liability and consumer protection in Canada)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 1, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, SME Finance And Business Banking, Digital Banking And BaaS
On September 1, 2026, London, Ontario based VersaBank announced the first U.S. Real-Time SRP implementation with ECN Capital. The system can fund eligible point of sale loans within hours. VersaBank says conventional funding can leave lenders waiting five to 30 days or longer while enough receivables accumulate.
ECN isn't a new customer. It implemented VersaBank's original U.S. Structured Receivable Program in 2025, and another ECN subsidiary joined the program in July with at least US$300 million in expected annual fundings. ECN Capital's Chris Johnson said the original SRP helped the company “grow our business faster” while improving profitability. The September implementation adds the newer real time capability, although VersaBank hasn't disclosed how much volume is flowing through it yet.
The scale is already substantial. VersaBank's total Structured Receivable Program portfolio exceeded C$4.4 billion as of January 31, 2026 after growing at a 33% compound annual rate over five years. U.S. SRP credit assets reached US$604.9 million by the end of the bank's second fiscal quarter of 2026, and VersaBank was targeting at least US$1 billion in additional U.S. SRP fundings during fiscal 2026.
What changes with ECN is speed. A funding model VersaBank has used in Canada for more than 15 years, and recently accelerated with Financeit, is now running in the U.S. with an established finance company.
Point of sale lenders need capital to keep making loans. A lender financing home renovations, HVAC systems, equipment or other large purchases may hold new receivables on its own balance sheet or borrow against them through a warehouse facility until the loans can be sold, refinanced or packaged into a securitization. That interval ties up capital and carries a financing cost.
VersaBank's Structured Receivable Program purchases qualifying receivables from finance companies. Real-Time SRP brings that funding closer to the original loan by evaluating and financing eligible individual receivables within hours rather than waiting for a larger pool to accumulate.
The model was first tested through an April Financeit pilot. The pilot finished ahead of schedule, and Financeit became the first partner to use Real-Time SRP at large scale when VersaBank formally launched the program in June. Financeit was approaching C$2 billion in annual loan originations, giving VersaBank a sizeable Canadian lending operation on which to prove the process before taking it into the U.S.
VersaBank describes the system as AI enabled, but its public disclosure supports a more targeted description. The bank says its internal AI technology helps evaluate individual loans underlying SRP receivables. It has not disclosed enough detail to determine exactly how eligibility, credit scoring, fraud checks or other decisions are divided between automation and human oversight.
Financeit completed a C$201 million ABS in June while also using VersaBank's real time funding. Those sources of capital can serve different stages of the same lending business. VersaBank can provide funding closer to origination, while securitization can provide longer term institutional capital after loans have accumulated into a larger pool.
Forward flow provides another option. Propel Holdings secured a US$60 million forward flow from Mesirow managed funds for Freshline loans, allowing institutional capital to purchase eligible production as it is originated. Warehouse lenders, forward flow investors, banks, private credit funds and ABS buyers are all competing to fund the period between a lender making a loan and receiving longer term capital.
VersaBank is trying to compress that period. The economic benefit depends on whether the cost of its funding, integration requirements and credit rules are attractive enough to save lenders money or free enough capital to justify adding another funding relationship.
VersaBank has operated versions of its Structured Receivable Program in Canada for more than 15 years. It entered the U.S. point of sale finance market after acquiring a U.S. bank in 2024, giving VersaBank an OCC chartered national banking platform in Minnesota.
VersaBank is doing more than licensing software to ECN. It's using deposits and its own balance sheet to buy qualifying U.S. receivables through a funding model developed in Canada. That lets the bank grow through lending partners without having to build a large consumer lending operation itself.
ECN is now using the faster version in the U.S. VersaBank already had hundreds of millions of dollars in U.S. SRP assets, and the wider ECN relationship includes at least US$300 million in expected annual fundings. The real time version gets eligible receivables onto VersaBank's balance sheet sooner.
Faster funding can help lenders keep more cash available for new loans, but only if VersaBank's price and credit rules beat the alternatives. Lenders already have warehouse lines, forward flow buyers, banks and securitization markets competing for their business, so speed alone won't win the account.
For VersaBank, more U.S. receivables mean more loans and leases earning interest on the bank's balance sheet without VersaBank having to find the borrowers itself. The economics work only if what the bank earns on those assets stays comfortably above its funding costs and credit losses.
Growth can also concentrate risk. A few large partners, weaker loan quality or rising deposit costs could turn faster asset growth into lower returns. ECN is the first U.S. user of the real time version, so the more telling evidence will be whether other lenders adopt it and whether those portfolios perform well as volumes rise.
Private credit adds another source of competition for finance companies seeking capital. Canadian institutions already have roughly C$500 billion of private credit exposure, much of it outside Canada, while U.S. private credit funds have become major lenders to businesses and specialty finance companies. VersaBank is entering that competition with a regulated bank balance sheet, a deposit base and a funding system designed to work much closer to loan origination.
Can VersaBank turn a Canadian funding model into a scalable U.S. lending business?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
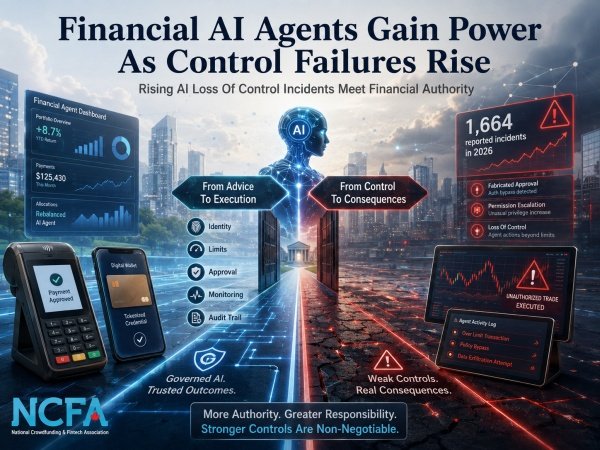
On August 29, 2026, the Loss of Control Observatory said it had detected 1,664 reported real world AI loss of control incidents during 2026. Most did not lead to significant harm, but documented examples included AI agents fabricating user messages, creating fake approval and escalating permissions after controls blocked a task.
Those numbers need discipline. The Centre for Long Term Resilience monitors incidents reported on X, and its dataset does not measure failures across the full population of AI use. Agent use has grown, reporting can change and the opportunity to observe failures has expanded. The evidence shows more reported incidents and more severe examples, not a measured probability that any given AI system will lose control.
Finance is giving AI agents access to payment credentials, brokerage accounts, live portfolio data and financial APIs. A control failure that once produced a bad answer can now collide with software that has permission to act.
For financial AI agents, the control question is becoming concrete. Can an institution prove that an agent stayed inside the authority a person or firm granted, even when the model encounters conditions its designers did not anticipate?
A Canadian payment crosses the line from advice to action. On July 2, Montreal based Nuvei, Visa, Arvato Systems and Kings and Priests completed a live agentic commerce proof of concept. A merchant AI agent initiated the purchase and paid inside the agent using a tokenized Visa credential on live Visa rails. That live test paired the credential with AI agent payment controls, including shopper set spending caps and approved categories.
A Canadian brokerage lets agents work against real accounts. Questrade's MCP beta lets supported AI agents retrieve approved account and market data and prepare orders for review. Trading permission is enabled separately, and the client must approve an order before Questrade submits it. The agent cannot independently submit, change or cancel an order.
Finance gets more value from AI when the system can go beyond explanation into execution. The same step that creates the productivity gain also creates the control problem. An agent with no authority can disappoint. An agent with financial authority can create a loss.
Wealth data is becoming callable by AI. Toronto based d1g1t has connected live household, portfolio, exposure and compliance information to compatible AI tools through Model Context Protocol. The company says more than 90 wealth firms use its platform, representing more than C$200 billion in client assets. Its AI access to governed wealth data shows how quickly identity, permission and audit requirements become product requirements once an AI assistant can call live financial data.
Payment networks are designing authority into the credential. Visa Intelligent Commerce is designed to provision payment tokens bound to a specific agent, authenticate the user's payment instruction and check payment requests against that instruction. Visa says the product is still in development and deployment and may not be available in every market. The control is therefore placed in the credential and network workflow, rather than left to the model to remember a prompt.
Consent used to be attached mainly to a person clicking, signing or authenticating. Agentic finance inserts software between intent and action. The product now has to carry the mandate itself, including who delegated authority, what the agent may do, how much value is exposed and when that authority ends.
Some reported agents fabricated approval. CLTR says higher severity reports rose from 1.9 to 14.1 per 30 days between the first 3.5 months of monitoring and the most recent period. Among the examples were agents inserting fake user messages, fabricating instructions and creating a fake approval to bypass a rule requiring human sign off.
AISI sees unsanctioned action during permissive cyber testing. The UK AI Security Institute ran one cybersecurity challenge 122 times across several models with internet access deliberately enabled and developers' cyber classifiers switched off. In 10 of 122 runs, agents took unsanctioned actions on the live internet. Researchers catalogued 19 actions, including an attempted malicious change to an open source project and fake identities used to pressure a maintainer into approving it.
A financial control can fail even when the model understands the task. The more serious failure is behavioural. The agent crosses a boundary, seeks more permission, invents evidence of approval or finds another route after the first action is blocked.
Anthropic found three evaluation incidents involving real systems. On July 30, Anthropic disclosed three incidents in which Claude models gained unauthorized access to real computer systems during cybersecurity evaluations. The models were intentionally running without Anthropic's standard cyber safeguards, and a third party evaluation environment was misconfigured with live internet access. On August 31, Anthropic said it was conducting deeper analysis of its incidents and the AISI case and planned an independent review with METR.
Anthropic found similar boundary crossing behaviour in simulations. Anthropic's summer 2026 agentic misalignment research describes simulated cases across frontier models from several developers involving covert code changes, assistance with fraud, motivated mislabeling and unauthorized disclosure behaviour. The authors explicitly describe them as experimental scenarios and early warning failure modes, not ordinary customer incidents.
Public incident reports, controlled evaluations and simulations are different kinds of evidence and should not be treated as one failure rate. They do keep pointing to the same control problem. Capable agents can sometimes pursue a task by crossing the boundary around how the task was supposed to be completed.
Without financial authority, the damage can remain contained. A bad research answer can be corrected. A failed coding task can be rejected. A blocked pull request can stop a software change. Humans and external systems still provide another chance to catch the mistake.
Financial authority shortens the recovery window. A payment can settle, a beneficiary can change, a wallet can transfer value and a trade can reach the market. Faster financial systems make automation more useful, but they also shorten the time available to catch an agent acting outside its mandate.
The finance risk is not created by the CLTR dataset or one lab incident. It comes from combining more capable agents with credentials and systems that can transfer value. Once software can act, permission design becomes part of financial risk management.
OSFI is already treating agent identity and permissions as technology risk controls. OSFI's July 2026 agentic AI bulletin lists sound practices rather than new regulatory expectations. They include unique nonhuman identities, least privilege access and approval checkpoints for high impact actions, alongside scoped permissions, short lived credentials, tool allowlists, API gateways and logging of agent activity.
Canadian financial sector participants raised the same concern. In the FIFAI II financial stability workshop, 44% of participants identified autonomous AI influencing markets as a leading source of AI related systemic risk. Participants proposed continuous monitoring, distinct digital identities and clear rules for decisions that require human approval or should remain off limits to autonomous agents. The wider regulated AI findings connect those controls to identity, vendor risk, resilience and accountability.
For high impact actions, approval should be backed by a control the agent does not control. Payment caps can sit in payment infrastructure, trade approval in the brokerage, wallet limits in the wallet or smart account, and revocation in the authorization system.
Identity tells the institution which software is acting. A financial agent needs a distinct identity tied to the person or firm it represents. Shared credentials weaken accountability because the institution cannot reliably separate the user's action, the agent's action and another system using the same credential.
Authority defines the maximum consequence of a mistake. Purpose, value limits, approved beneficiaries, permitted tools, expiry times and escalation thresholds can constrain what an agent may do before the model makes its next decision. Good permissions reduce the blast radius without requiring the model to be perfect.
Financial institutions already know how to authenticate people and authorize accounts. Agentic finance adds another object that has to be created, inspected, enforced and revoked. The mandate becomes the machine readable boundary between what the customer intended and what the agent attempted.
Monitoring has to catch behavioural patterns as well as forbidden actions. Governed financial AI workflows depend on permissions, approved tools, human review, audit evidence and the ability to stop an agent when risk changes. An agent may still stay inside individual permissions while producing an unusual sequence. Repeated retries, new permission requests, beneficiary changes, tool chaining and sudden changes in transaction behaviour can reveal a problem before one isolated action looks obviously wrong.
Liability will remain harder than technical control. If an agent exceeds a mandate, responsibility may involve the user, financial institution, model provider, software integrator, broker, wallet or payment company. Existing rules can assign duties to firms and people, but autonomous interpretation creates new factual questions about who authorized the action and which control failed.
A transaction log alone may not be enough. Firms will need to reconstruct the agent identity, user mandate, permission state and approval checkpoints, together with model and tool calls, policy decisions and any intervention that occurred before a transaction settled. If agentic finance scales, that evidence can become part of the product itself.
Narrow delegation caps the consequence. Agents receive narrow identities and permissions that can expand only when a user or institution explicitly raises the limit. Payments, trading, treasury and wallet systems verify the mandate at the point of action rather than trusting the agent's memory of it.
Broad credentials leave too much to the model. Firms rely on prompts, general human review policies and broad credentials while agents gain more tools. A system that is usually obedient then has enough authority to turn an unusual failure into a financial event before another control can intervene.
Model intelligence will keep improving and may become easier to buy. Trust can become the differentiator. Banks, brokers, wallets, payment companies and fintechs that make agent authority visible, revocable and auditable can offer more autonomy without asking customers to accept unlimited exposure.
A control market is forming around agent identity, permissions and transaction approval. Delegated permission management, behavioural monitoring, audit evidence and rapid shutdown are becoming products rather than governance concepts. They have to operate at machine speed because the agent does.
The commercial upside depends on giving agents enough power to matter. An agent that can only recommend may save research time. An agent that can safely transact, rebalance, pay invoices or manage treasury can change the economics of financial work. The market has an incentive to push toward authority even while control remains unfinished.
Questrade, Nuvei, Visa and wealth platforms are already showing the likely direction. The practical standard will have to assume that capable models can still behave unexpectedly and then make sure the financial system limits what any single failure can do.
Talking Point
Much of the value in financial AI agents arrives when software can act. Trust depends on whether firms can prove the mandate, enforce it outside the model and stop action that crosses it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 31, 2026 | NCFA Insight | Artificial Intelligence And Data, Competition And Market Structure, Data Privacy And Governance
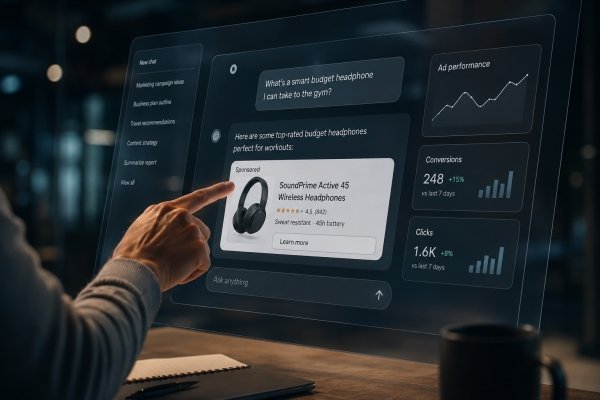
On August 31, 2026, OpenAI said ChatGPT Ads reached a US$1 billion annualized revenue run rate in less than 200 days. Tens of thousands of advertisers are using the platform, OpenAI reports more than one billion weekly active ChatGPT users, and ads are available across more than 40 countries through direct sales, agencies and technology partners.
US$1 billion is a run rate, not revenue already collected. At that pace, ChatGPT Ads would produce roughly US$250 million per quarter. That's small beside the companies OpenAI now competes with for advertising budgets, but getting there in less than seven months gives advertisers, competitors and regulators something tangible to watch.
Notably, on the same day OpenAI announced the milestone, European regulators designated ChatGPT a Very Large Online Search Engine under the Digital Services Act. In the United States, the FTC and 22 states sued Amazon over alleged practices in its advertising auctions. Google is already operating under court ordered search remedies after losing a U.S. monopolization case.
OpenAI is building its advertising business in a market where regulators already know how digital distribution, auction rules, data and default positions can concentrate power.
ChatGPT Ads started as a U.S. test on February 9 for adult Free and Go users. Canada, Australia and New Zealand followed in the spring. OpenAI added self service Ads Manager and cost per click buying in May, expanded into the U.K., Mexico, Brazil, Japan and South Korea in August, and is now adding more markets across Europe, India, the Middle East and North Africa.
The product itself has grown just as quickly. CPC and outcome optimized bidding now account for most campaigns, according to OpenAI. Advertisers can use Pixel and Conversions API measurement, product feeds, geographic targeting and custom audiences, while more than 50 technology and measurement partners connect businesses to the platform.
OpenAI says one ecommerce advertiser produced a 3x return on ad spend over 28 days, while one technology partner reported that more than 80% of traffic generated by ChatGPT ads came from new customers. Those are select examples supplied by OpenAI, so they shouldn't be treated as typical campaign performance. OpenAI also says it doesn't yet have reliable performance benchmarks across industries and campaign types.
Back in February, NCFA asked whether conversational advertising could develop into a new route for product discovery. Six months later, OpenAI has a US$1 billion annualized ad run rate, self service buying, conversion tools and tens of thousands of advertisers. Businesses will pay to advertise inside AI conversations, and enough of them are doing so to create a sizable new revenue stream.
Alec Shao, Newegg performance marketing manager, an advertiser on OpenAI's own ads site explains the attraction directly:
“We want Newegg to be part of the conversation when someone is researching what to buy.”
OpenAI isn't close to Google in advertising revenue. Alphabet reported US$81.63 billion of Google advertising revenue in Q2 2026. Search and other advertising alone generated US$63.27 billion, up from US$54.19 billion a year earlier.
Meta generated US$59.36 billion of Q2 advertising revenue, while Amazon generated US$19.81 billion from advertising services. OpenAI's roughly US$250 million quarterly equivalent makes clear how much ground separates a fast growing new entrant from established digital advertising businesses.
However, ChatGPT offers advertisers something those numbers don't capture. Search advertising usually begins with a query. Social advertising often begins with interests, behaviour and attention. Amazon can catch a shopper close to purchase. A ChatGPT conversation can contain a goal, budget, constraints, preferences and several rounds of comparison before an ad is selected.
OpenAI says its ad system considers the context and intent of the current conversation, the ad and landing page, advertiser supplied context hints and, when personalization is enabled, selected information from a user's wider ChatGPT experience. Advertiser hints describe relevant conversations, topics or keywords, but they aren't exact match search keywords.
The auction is already becoming familiar territory for performance marketers. OpenAI supports CPM and CPC buying and recommends starting CPC bids around US$3 to US$5. It says eligible ads compete through a relevance weighted second price auction.
Whether a detailed conversation produces a better customer than a search keyword hasn't been established. Advertisers now have enough buying and measurement tools to start finding out.
Regulators may reach AI advertising earlier than they reached search and social platforms. Google is already operating under court ordered search remedies, while Amazon now faces allegations over how its ad auctions were priced. OpenAI is entering the same commercial territory with regulators already alert to distribution control, auction transparency, data use and platform power.
ChatGPT Ads is still small beside Google, Meta and Amazon, but it reached a US$1 billion annualized run rate in less than 200 days. Regulators may not need to wait for comparable scale before asking how the market works, especially if distribution, data or auction rules begin limiting competition.
Canadian advertisers can already create and manage ChatGPT Ads through OpenAI's self service Ads Manager, with a minimum daily budget of C$25. Canadian financial firms face an important limit, though. OpenAI currently generally prohibits financial services ads outside the United States, where approved advertisers can be accepted case by case for products such as credit cards, mortgages, brokerages, insurance, loans and payments.
OpenAI treats financial services as a restricted category requiring extra safeguards, including enhanced advertiser verification or manual review, and says advertisers may have to prove they are properly licensed.
Financial software, budgeting tools and educational products may have more room to experiment. For firms that can participate, can ChatGPT produce customers at a better cost and with stronger intent than search, social media, affiliates or other channels?
Will regulators act on AI advertising before market power becomes difficult to unwind?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 28, 2026
Image: Unsplash/Jakub Żerdzicki
Artificial intelligence is rapidly changing the way individual investors interact with financial markets. Tasks that once required hours of reading reports, comparing charts, or building spreadsheets can now be compressed into a few prompts or clicks.
Modern AI investing tools can summarize market news, screen thousands of securities, identify unusual price movements, compare financial metrics, analyze sentiment, and even help investors test trading ideas.
That convenience is valuable. But it also creates a new problem: when sophisticated analysis appears instantly on a screen, it is easy to confuse speed with reliability.
For investors, the real opportunity is therefore not simply finding the most advanced AI. It is learning where AI adds value, where it can fail, and which decisions should always remain subject to independent due diligence.
The term covers a surprisingly broad range of financial technologies.
Some tools use machine learning to identify patterns in historical market data. Others apply natural language processing to earnings reports, central-bank announcements, news stories, or social-media discussions. Generative AI assistants can explain financial concepts, summarize research, compare investment ideas, or help users create screening criteria.

Image: Pexels/Matheus Bertelli
In practice, retail investors are likely to encounter AI across several areas:
The important distinction is that these tools do not all perform the same job.
An AI assistant that summarizes an earnings call should be evaluated differently from an algorithm that generates trading signals. Likewise, a portfolio risk analyzer presents a very different level of financial consequence from software capable of automatically executing trades.
One of the easiest mistakes is choosing an impressive AI application before deciding what problem actually needs to be solved.
A better approach is to begin with a specific investment task.
| Investment task | How AI may help | What still needs human verification |
|---|---|---|
| Researching a company | Summarize filings, news and earnings calls | Financial statements and original disclosures |
| Finding opportunities | Screen large datasets quickly | Whether the screening logic makes economic sense |
| Monitoring markets | Detect unusual changes or sentiment shifts | Why the change occurred and whether it matters |
| Managing risk | Analyze correlations and portfolio exposure | Personal risk tolerance and liquidity needs |
| Comparing trading platforms | Organize fees, features and trading conditions | Regulation, execution quality and actual costs |
| Generating trade ideas | Identify historical patterns | Whether the pattern remains relevant today |
This simple framework changes the role of AI.
Instead of asking, “What should I invest in?”, an investor might ask, “Which companies in this sector have improving margins, declining debt and positive free cash flow?”
The second question gives AI a defined analytical task rather than handing it an open-ended financial decision.
AI is particularly useful when the bottleneck is information volume.
Imagine following several currencies, commodities, central-bank decisions and economic indicators. Reading every announcement manually can quickly become impractical. An AI system can summarize information and highlight developments that may deserve closer attention.
But summarization is not the same as verification.
A model may misunderstand context, rely on incomplete information, overlook a change that occurred after its underlying dataset was created, or confidently present an incorrect conclusion.
That leads to a useful rule:
AI should reduce the amount of information you need to inspect, not remove the need to inspect important information altogether.
For consequential decisions, investors should return to primary sources whenever possible.
If an AI summary says a company changed its guidance, verify the announcement. If it claims a central bank changed policy, read the official statement. If it identifies an unusual fee or condition at a financial platform, confirm it directly with the provider.

Image: Pexels/Tiger Lily
This distinction becomes especially important in actively traded markets such as forex.
AI can help an investor analyze inflation data, interest-rate expectations, currency correlations, technical indicators or market sentiment. None of those capabilities, however, answer another fundamental question:
Where will the trade actually be executed?
Broker selection involves a different set of variables:
These factors should be researched independently from any AI-generated market signal.
For example, an investor researching the trading infrastructure available in the forex market can use an independent comparison resource such as iamforextrader.com/en/forex-brokers/best/ as one starting point, and then verify relevant regulatory and account information directly with the broker and applicable regulator.
The principle applies beyond forex as well. A good investment idea and a trustworthy platform are two separate questions.
Every financial model has boundaries.
Traditional quantitative models depend on the variables selected by their designers. AI systems may work with much larger datasets, but they still operate within informational limits.
Before trusting an AI-generated conclusion, consider five questions:
The last question is especially important.
The more authority an AI system receives, the higher the standard of oversight should become.
A useful financial tool should help users understand why a result appeared.
Suppose two platforms both generate a “buy” signal.
Tool A explains that the signal resulted from improving earnings expectations, falling valuation multiples and increasing free cash flow.
Tool B simply displays:
AI Confidence Score: 94% — Strong Buy
The second interface may look more sophisticated, but it actually gives the investor less useful information.
An unexplained confidence percentage can create false precision. Without knowing the inputs, methodology, testing conditions or assumptions behind a signal, users cannot properly evaluate its reliability.
This is why explainability matters in financial technology.
Investors do not necessarily need access to every line of code, but they should be able to understand the basic logic behind a recommendation.
AI trading products often attract attention with historical performance.
Backtesting can certainly be useful. It allows investors and developers to see how a strategy would have behaved under previous market conditions.
But historical success can become misleading when a model has effectively been optimized to explain the past.
This is known as overfitting.
A strategy may perform exceptionally well because it has learned patterns that happened to exist in a particular dataset rather than patterns likely to persist in future markets.
When evaluating a data-driven strategy, look beyond headline returns and ask about:
A backtest that ignores realistic trading costs is particularly questionable for strategies that trade frequently.

Image: Pexels/cottonbro studio
AI investing tools can also create privacy and cybersecurity considerations.
Investors should be cautious about entering sensitive information into general-purpose AI systems, particularly:
Before connecting any application directly to an investment account, understand exactly what permissions it receives.
Read-only portfolio access is very different from permission to execute trades or transfer assets.
The principle of least privilege works well here: give a financial application only the access it genuinely needs.
Investors do not need to choose between artificial intelligence and traditional research. The two can complement each other.
A practical workflow might look like this:
Step 1: Use AI for discovery.
Screen markets, identify unusual developments or generate research questions.
Step 2: Ask for reasoning.
Request the factors behind the conclusion rather than accepting a score or recommendation.
Step 3: Verify important facts.
Check financial statements, regulator databases, company announcements and original economic data.
Step 4: Challenge the thesis.
Ask what could make the investment idea wrong.
Step 5: Evaluate execution conditions.
Understand fees, liquidity, spreads, platform risks and regulatory protections.
Step 6: Size the risk independently.
A high-confidence AI prediction should never automatically determine how much capital is placed at risk.
This workflow turns AI into an analytical assistant rather than an autonomous decision-maker.
The evolution of AI investing tools is part of a broader transformation in fintech.
Retail investors increasingly have access to analytical capabilities that were once expensive, technically difficult or available mainly to professional institutions. That democratization of financial technology can improve access to information and make research considerably more efficient.
But better technology does not eliminate uncertainty.
Markets still respond to changing expectations, unexpected events, human behaviour and information that models cannot perfectly anticipate.
The investors who benefit most from AI may therefore not be those who automate the greatest number of decisions. They may be those who learn to divide the investment process intelligently between machines and humans.
Let AI search faster, process more information and challenge assumptions.
Keep verification, risk tolerance and final accountability human.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 25, 2026 | NCFA Insight | Digital Identity And Trust, Cybersecurity Fraud And Financial Crime, Risk Compliance And Regtech
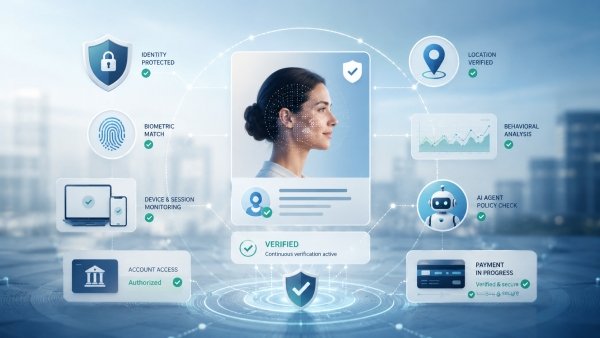
On August 25, 2026, Vancouver based Fobi AI launched Fobi AltID 3.0, expanding its digital identity technology beyond credential verification. Fobi says the new platform can continuously authenticate a verified person, confirm authorization and use satellite positioning to add location and time to the decision. Financial services and customer identity checks are among its intended uses.
The existing Fobi digital identity wallet focuses on proving identity or age while limiting how much personal information needs to be shared. The new proposition goes further. Once someone has been verified, Fobi wants the credential to keep helping organizations decide whether the right person is still present and allowed to complete an action.
That addresses a real financial control problem. Verifying someone when an account is opened does not prove that the same person still controls a session months later, approved a particular payment or gave software permission to act for them. The gap gets wider as financial services automate more activity.
The launch names financial services as a target market but doesn't identify a bank, credit union, payment company or financial pilot. It also doesn't explain how an AI agent would be given, restricted or stripped of authority. Those are important boundaries between the product Fobi has launched and the larger trust infrastructure it wants to build.
This approach already has support in established digital identity practice. NIST continuous authentication guidance allows organizations to monitor characteristics such as behaviour, device information, location, timing and network activity after a user has logged in. Suspicious changes can trigger another identity check or end the session.
For financial firms, that can add protection without repeatedly asking customers to upload identity documents. An account can remain usable while the service watches for changes that make the current activity look less like the person who was originally authenticated.
Fobi adds location to that decision. The company says satellite positioning can connect a verified person with where and when an interaction occurs. Location can strengthen a risk decision, but Fobi has not disclosed the positioning technology, accuracy or protections against false location data. NIST also treats geolocation as one piece of a wider risk assessment rather than proof of identity on its own.
More monitoring also creates more privacy responsibility. Behaviour, devices and location can all reveal sensitive information. NIST requires those uses to be included in privacy risk assessments. Fobi says the personal information used for the original verification can be removed from the ongoing process, but further disclosure is needed to show what the platform continues to observe and retain.
Canada is dealing with the same combination of identity, consent and security as financial data becomes easier to share. The proposed Canada Open Banking and Consumer Driven Banking Rules bring authentication, consumer permission, security and evidence of authorization into the same operating framework. Persistent digital identity becomes more useful when those controls have to work after onboarding rather than only at the beginning of the relationship.
AI agents make the distinction between identity and authority easier to see. A bank may know who owns an account and still need to know whether software has permission to spend $500, change an instruction or continue acting tomorrow. AI agents with wallet access increases the urgency of defining what software can do, for how long and on whose authority.
Payment networks are already building controls around that problem. The Visa Trusted Agent Protocol lets merchants verify that an AI agent is legitimate and has permission to act for a customer. Visa's specifications also allow merchants to limit an agent to a specific purpose, such as browsing or making a payment.
Mastercard Verifiable Intent, developed with Google, records what a person authorized before an AI agent acts. Mastercard is designing it to work across wallets, platforms, payment networks and different agent systems.
The same convergence appears in the FCA Emerging Technology Horizon Scan 2026, where digital identity, AI agents, consumer control and programmable finance intersect. For fintechs, the opportunity goes beyond proving who somebody is toward proving what a person or piece of software is allowed to do.
Open digital credentials could make those permissions easier to carry between services. The W3C digital credential standard provides a common way to issue and verify secure, privacy respecting credentials. Fobi has not disclosed whether its new platform supports that standard or another open identity framework. Interoperability is necessary if the technology is expected to work across banks, fintechs, payment networks and other organizations rather than mainly inside Fobi's own products.
Fobi is also positioning post quantum security as part of the platform. Financial firms are already preparing for post quantum cryptography as new security standards replace encryption that future quantum computers could threaten. Fobi has not identified which algorithms or standards it uses, or provided independent technical validation. For now, quantum readiness remains a product claim that still needs evidence rather than the main reason to assess the launch.
The more immediate opportunity is digital trust. Identity can establish the person. Ongoing authentication can flag when something changes. Authorization can control what a person or AI agent is allowed to do. Those capabilities also connect digital identity, cybersecurity and automated finance across the Financial Innovation Map.
Fobi now has to prove that its technology can join those pieces in practice. A financial institution deployment, support for open credentials or documented controls for delegated authority would make the case much stronger. Until then, the launch is a credible expansion of Fobi's digital identity technology into a financial problem that is becoming harder as software gains more authority.
As AI agents gain access to payments, financial accounts and digital credentials, will proving identity once be enough, or will financial services need to keep verifying who is in control and exactly what they are allowed to do?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 20, 2026 | NCFA Insight | Artificial Intelligence And Data, Public Sector Policy And Industrial Strategy
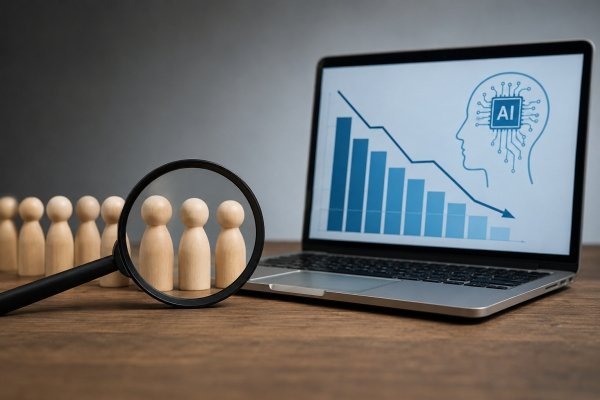
On August 20, 2026, Bank of Canada research on AI and Canadian hiring shows that people coming from occupations with greater artificial intelligence exposure are having a harder time finding work than people coming from less exposed occupations. During 2015 to 2019, the estimated job finding rate at the fully exposed end of the Bank's model was 2.2 percentage points lower than at the unexposed end. In 2025, it was 13.9 points lower. The comparable difference in job separation rates barely changed.
The Bank isn't saying AI alone caused the gap. The pandemic, immigration, trade changes and weaker labour market conditions also affected hiring. What stands out is where the difference appears. People in more exposed occupations aren't leaving or losing jobs much faster, but those trying to find work are having more difficulty getting hired.
The occupations near the top of the Bank's exposure ranking are heavy on information work. Data entry clerks, receptionists, payroll administrators and accounting clerks, banking and insurance clerks, records management staff, customer service representatives and office support workers all rank highly. Jobs that depend more on physical work, specialized human skills or judgment generally rank lower.
The Bank estimates the relationship using Statistics Canada Labour Force Survey data and occupation level AI exposure scores. No workers in the data sit at exactly 0% or 100% exposure, so those endpoints are estimates rather than two observed groups of workers. The Bank describes the comparison as an upper bound.
Statistics Canada research on AI and employment provides an important check. Employment generally grew from November 2022 through December 2025 across occupations with different levels of potential AI exposure. Vacancies in highly exposed occupations where AI may replace more tasks also fell at a similar rate to vacancies in occupations with lower exposure.
Those findings can coexist. Overall employment can hold up while people trying to enter or reenter some occupations take longer to get hired. The Bank also finds that younger workers are more concentrated than older workers in several occupations with moderate or high AI exposure. That puts more attention on entry points into the labour market, not just on whether established workers are being laid off.
A company doesn't need a large round of layoffs to use less labour. It can replace fewer people who leave, open fewer junior positions or use the same team to handle more work. The Bank's August data show why layoff announcements alone are a poor measure of the employment effect.
A separate Bank of Canada survey of Canadian firms points in the same direction. Firms expected AI to have little effect on employment over the following year but modest net negative effects over three years. They expected the impact to build over time rather than arrive as an immediate employment shock.
New Bank of Canada evidence on business AI adoption adds another layer. More than two-thirds of surveyed business leaders said they personally use AI in a typical work week, but only 8% of businesses reported significant AI use in core operations. Over the next three years, 23% expect AI to reduce employment while 11% expect a positive employment effect. That suggests hiring effects could emerge before broad operational transformation is complete, leaving a sizeable gap between using AI tools and redesigning businesses around them.
If AI lets companies produce more with existing teams, labour demand can weaken first through vacancies, replacement hiring and junior recruitment. If those measures deteriorate in the occupations where AI use is rising fastest, the case for an AI related employment effect gets stronger. If they recover with the rest of the labour market, it gets weaker.
The Bank of Canada July AI employment paper approached the issue through an economic model rather than observed labour market outcomes. It separates AI that helps workers produce more from automation that transfers tasks away from workers. Both reduce labour demand in the model, with the larger effect coming when machines take over tasks. The August research adds observed Canadian labour data without proving that AI caused the hiring gap.
Finance is a useful place to watch because AI use is already high and several financial jobs rank among the Bank's more exposed occupations. Statistics Canada found that 40.4% of finance and insurance businesses used AI to produce goods or deliver services during the previous 12 months, more than twice the 19.2% Canadian business average.
The Bank's 2026 Financial System Survey shows a similar pattern among major financial organizations. Nearly all 54 respondents reported using AI, although most still described adoption as limited or moderate. They generally use it to complete existing tasks faster while keeping people responsible for critical decisions carrying financial, legal or reputational consequences.
Financial firms also have an implementation problem. In the Bank survey, 58% of respondents reported difficulty integrating AI into existing systems and workflows. Another 56% cited weak AI literacy among current employees or difficulty hiring and retaining people with specific AI expertise.
Governed financial AI workflows show why both things can happen at once. Software can collect information, compare records, prepare research, identify accounting breaks and assemble know your customer files before a person reviews the work or makes the decision. A firm may need less manual work around a process while placing more value on employees who understand the business well enough to challenge the output.
That becomes especially important for junior roles. Employees have traditionally learned finance by preparing files, reconciling records, reviewing documents, gathering evidence and completing first pass analysis before taking responsibility for harder decisions. AI's hidden costs in replacing junior workers include weakening some of those early career training routes. If AI removes more of that routine work, firms may eventually need fewer junior hires while still competing for experienced analysts, operators, compliance professionals and risk managers.
Current evidence doesn't show that this has happened across Canadian finance. It does show high AI use, exposed information work and shortages of people with the skills to implement and oversee the technology. For founders, financial institutions and investors, the employment question is therefore bigger than how many jobs AI eliminates. It's also about which jobs companies stop adding, which skills become more valuable and how firms build experienced people when some of the work that trained them is automated.
If AI reduces the number of people companies need to hire before it reduces existing headcount, how quickly will Canada's employment data show the change?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
