




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Nov 3, 2026

Technology makes many parts of life easier, and home financing is no different. Whether you are buying your first home or refinancing your current mortgage, you can use digital tools to help. You no longer have to spend hours dealing with paperwork or making phone calls. Instead, technology helps you find information, compare options, and make smart decisions about your home financing.
You can now complete your mortgage application from your couch, compare multiple lenders with a few clicks, and track your application in real time. This change saves you time and creates a smoother experience, keeping you informed every step of the way. Let's look at how you can use technology to navigate home financing.
Mortgage calculators are helpful tools that give you quick estimates of your loan options. By entering details like home price, down payment, and interest rate, you can learn important facts about your monthly payments and total loan costs. This tool helps you see how different choices affect your budget, so you can make changes before you decide.
Many platforms also offer advanced calculators that include taxes, insurance, and private mortgage insurance (PMI). This detailed approach helps you see your financial commitments more clearly, so you can plan better. You can access these calculators anytime to update your numbers or rethink your plans.
Technology makes it easier to track mortgage rates Canada. Online platforms give you real-time information on current rates, trends, and forecasts. This helps you find the best time to lock in a rate. With this clear information, you don't have to guess if you're getting a good deal. Everything is just a few clicks away.
You can also easily compare what different lenders offer. Many websites show how rates have changed over time. This information helps you make smart choices that fit your financial goals.
Mobile apps put home financing in your hands. Several apps target borrowers, letting you track interest rates, find loan details, and communicate with lenders. Many of these apps are easy to use and guide you through each step of the financing process, making it clearer what you need to do.
For example, some apps let you upload documents directly from your smartphone. You can easily send your financial statements or proof of income without visiting a lender or broker. This feature saves time and simplifies paperwork, improving the overall process.
Using a mortgage broker can improve your home loan experience. Brokers work between you and lenders to find the best rates and terms for you. Today, many brokers use online tools to assess your finances and offer customized options quickly.
Technology helps brokers speed up paperwork and even run simulations to show how different choices affect your loan. They gather lots of information upfront, so you don't have to meet with many lenders. Your broker does the work and provides the best options based on your needs.
Technology also makes it easier to communicate with your broker. You can reach them by email, chat, or video call, making it simple to ask questions. This keeps you informed and comfortable throughout the loan process.
One major advancement in home financing is virtual consultations. Many lenders and mortgage brokers now offer video calls so you can discuss your options from home. This saves you time and the hassle of in-person meetings while still letting you ask questions and get personalized advice.
During these calls, you can review documents, look at different loan products, and address any concerns. Virtual consultations make it easier to connect with industry professionals, ensuring you feel supported and informed throughout the financing process.
You no longer need to search for paper documents or sort through files. Digital document management systems let you keep all your important papers in one secure place. Whether it's bank statements, tax returns, or job verification, scanning and organizing documents online makes your life much easier.
Many lenders let you submit documents online, saving time and reducing stress during the loan application process. You can access your documents from anywhere, so you can keep moving forward with your financing even when you're busy.
Technology is changing how we secure a mortgage. From calculators and apps to knowledgeable brokers and easy document management, technology offers helpful tools that make getting a loan simpler. These resources can make your home financing experience clearer and more efficient.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
October 16, 2026 | Market Activity | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Competition And Market Structure
On October 15, 2026, Toronto-based Pineapple Financial launched Pentiv, a new operating brand and AI mortgage intelligence platform aimed at commercializing technology already used within its mortgage brokerage business. Its Recruitment Agent and Alternative Mortgage Renewal Agent operate within Pineapple+, while the new Pentiv platform is designed to bring those capabilities to independent brokerages and mortgage networks.
Pentiv also marks a change in Pineapple's business strategy. Rather than keeping its mortgage technology exclusively inside the brokerage, the company wants to commercialize tools developed through years of operating experience. The plan includes recurring software revenue and a potential separation of its technology and mortgage brokerage businesses, subject to corporate review and approvals.
Pentiv's Recruitment Agent helps brokerage managers identify promising mortgage professionals, prioritize outreach and organize recruiting activity. Its Alternative Mortgage Renewal Agent identifies upcoming or potentially at risk renewals, suggests customer outreach and helps manage supporting documentation. Both address recurring sources of revenue for brokerages: recruiting productive agents who originate new business and maintaining relationships with existing borrowers as their mortgages mature.
Pineapple has already reported results from its earlier AI recruiting initiatives. On May 5, 2026, the company reported adding 83 licensed agents to its national network since the beginning of the year. Management attributed part of that recruiting momentum to AI tools that shortened the process of bringing new agents from initial contact to active status. The result provides operating evidence behind Pineapple's recruitment strategy, although it doesn't establish how many hires were directly attributable to Pentiv's current application.
Renewals offer another source of commercial revenue. An alternative mortgage borrower may need new financing when a loan matures, particularly if income, property values or qualification requirements have changed. Brokers who identify those customers early have more time to discuss options, prepare documents and retain the relationship. Pentiv is targeting that work rather than replacing mortgage underwriting or loan origination systems.
The company has built both applications around workflows already used by Pineapple's mortgage professionals. This gives its developers direct feedback on where recruiting efforts stall, where customers need attention and which tasks consume staff time. The challenge in selling that technology externally is making it useful across brokerages with different systems, procedures and customer data.
Mortgage Professionals Canada's 2026 research found that 38% of recent homebuyers used a mortgage broker, up six percentage points from 2024. Among recent first-time buyers, broker use reached 48%. The survey also found that 83% of broker clients would recommend their broker and 72% of borrowers who used a broker for their current mortgage would use one again.
Mortgage software is already competitive. Filogix expanded Expert Pro renewal visibility in June 2026, enabling brokers to identify upcoming renewals associated with additional properties owned by existing borrowers. Pentiv will need to distinguish its intelligence tools from established mortgage software and demonstrate that they work effectively alongside systems brokerages already use. Its focus on professional recruiting gives it another area in which to compete.
Canada's banks are also investing in AI for mortgage operations, including TD's expansion of agentic AI. Pentiv is approaching the market from the brokerage side, where smaller firms often lack the resources to develop their own software. A commercially accessible intelligence platform could give those firms capabilities that would otherwise require significant internal technology investment.
The Pentiv announcement includes a corporate development with significant implications for investors. An October 15 SEC filing confirms that Pineapple's board established an independent special committee on October 9 to review a proposed restructuring. The plan contemplates separating the technology platform and digital asset treasury operations from the mortgage brokerage business, potentially followed by a brokerage spin-off. These proposals remain under review, with no completed separation announced.
Under the proposed arrangement, the brokerage could continue using Pentiv as an anchor customer while the technology business sells its applications more widely. That would preserve access to operating feedback while giving the software operation a different commercial focus. The arrangements governing technology ownership, customer data, licensing and financial relationships would become important parts of the proposed separation.
Usman Maher, Pentiv's newly appointed Chief Financial Officer and Chief Strategy Officer and a former SoFi executive, described the company's approach:
"We will prove the economics inside Pineapple, extend the platform to external brokerages, and scale adoption to build a durable intelligence company and long-term shareholder value."
Pentiv plans to report operating results from its recruiting and renewal applications, external brokerage pilots, customer agreements and recurring platform revenue over coming quarters. Pineapple Financial remains the legal reporting company, trading on NYSE American as PAPL, with a ticker change to PTIV anticipated around October 26, 2026. Its proposed corporate name change to Pentiv Inc. requires shareholder approval.
Pentiv's real commercial opportunity is turning proprietary brokerage experience into software that competitors are willing to pay for. Independent customer adoption, measurable financial returns and recurring revenue will determine whether Pentiv can command a valuation beyond its mortgage brokerage business.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 13, 2026 | Market Activity, Banking And Digital Banking, Mortgage Lending, Artificial Intelligence And Data

On October 13, 2026, TD Bank Group expands use of agentic AI into Canadian mortgage funding and discharge operations, building on its May deployment for mortgage application reviews. TD reports that its earlier system reduced average preparation time from 15 hours to less than three minutes. Its new funding capability enables employees to complete initial reviews in up to half the time, while a separate application prepares mortgage discharge information for employee review.
TD is extending AI beyond application assessment into the administrative work required to complete mortgage transactions. For a bank processing large lending volumes, reducing that work could lower operating costs and increase employee capacity.
TD introduced agentic AI for mortgage pre-adjudication in May 2026. Developed by its Layer 6 AI team with lending, technology and risk specialists, the system classifies application documents, extracts financial information, calculates income and checks selected policy requirements. It also flags discrepancies before preparing a summary for underwriters, who retain responsibility for lending decisions. TD's May mortgage AI announcement reported that this preparation process fell from an average of 15 hours to less than three minutes. Worth noting that the result doesn't represent the full time required to approve a mortgage.
For funding, the new AI capability brings together client and property information from different systems and prepares a case summary for employees. TD says the initial review can take up to 50% less time, but hasn't reported a corresponding reduction in the time needed to release funds. Its discharge capability assembles information for a mortgage discharge statement when a loan is paid off or transferred, while employees check the statement before issuance.
Mortgage administration requires employees to verify documents, reconcile information and resolve exceptions before transactions can proceed. TD is using AI to handle more of that repetitive work across several stages of the same lending business. If accuracy holds, employees can devote more time to complex files while the bank handles additional volume without a matching increase in administrative staffing.
While the May results give TD an operating basis for expanding its investment, the commercial case now depends on performance across complete transactions. Faster document preparation has limited value if funding still stalls over missing information or staff must repeat an AI review. For mortgage technology providers, software must work with existing bank systems, produce reliable records and allow employees to identify and correct errors. TD is also investing in faster credit processing through its Trust Science lending deployment in auto finance, where borrower information verification presents a related challenge.
TD keeps employees responsible for credit decisions and final document reviews. AI prepares information for underwriters, funding teams and discharge staff rather than independently approving mortgages or completing legal discharges. That division of AI vs human is important because errors in income calculations, property records or discharge statements can delay transactions and expose both borrowers and lenders to additional costs.
The controls align with OSFI's frontier AI risk concerns as Canadian banks introduce more capable software into regulated operations. OSFI's agentic AI bulletin identifies sound practices for limiting system access, reviewing consequential actions and preserving accountability.
TD's mortgage AI expansion raises a bigger business question than processing speed. As automation reduces routine work, banks must decide how to use the capacity gained, whether through growth, lower costs or smaller teams. Will TD reinvest the savings in better mortgage service, or will workforce reductions become part of the return on its AI investment?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 16, 2026

A development budget is the most-read document in a real estate deal and the least understood. Investors read it to decide whether to fund. Lenders read it to size the loan. The developer reads it to find out whether the project makes money. All three assume the number came from somewhere solid, and in a surprising share of projects it came from a per-square-foot figure someone remembered from the last one.
I prepare construction cost estimates for developers and builders, from full-building takeoffs down to concrete estimating services for the structural package alone, which means I see a lot of budgets after they have been built and a fair number after they have failed. The failures rarely trace back to a bad market. They trace back to a budget that was assembled top-down, from a total that felt right, instead of bottom-up, from the work that actually has to happen. Here are the five habits that separate the budgets that hold from the ones that do not.
The hard cost line, the physical construction, is usually 60 to 70 percent of a development budget and it is where most of the error lives. A square-foot rate borrowed from a comparable project carries that project's accidents inside it: its soil, its subcontractor pricing that month, its owner who never changed anything.
The alternative is a takeoff. Measure the drawings, even schematic ones: cubic metres of excavation, square metres of slab, linear metres of foundation wall, storeys of structure, square metres of envelope, number of units and their fit-out. Price each line with material and labour separated. Anyone who has priced the structural package will tell you it alone can swing 15 percent between a slab-on-grade and a podium over parking, and a rate per square foot cannot see the difference. A takeoff can.
At the pre-development stage the drawings will be thin. Measure anyway, and record every assumption next to the quantity so it can be corrected when the design firms up.
Soft costs, meaning design fees, permits, legal, financing, marketing, development management, are often budgeted as a flat percentage of hard costs, and that is how they become the second-largest surprise in the pro forma.
Soft costs are driven by time, not by construction value. An architect's fee is tied to the contract, but the development manager, the interest reserve, the insurance, and the property taxes during construction all run by the month. A project that was budgeted for 18 months and takes 26 does not overspend its soft costs by a little; it overspends them by 40 percent or more, and the interest line is the one that compounds.
Build the soft cost budget from a schedule. List each cost, its start and end month, and its monthly rate. Then stress it: what does the number look like at 22 months, at 26. If the deal only works at 18, the deal does not work.
Most budgets carry one contingency line, five or ten percent of hard costs, and treat it as a single bucket. The problem is that risk is not evenly spread across a project. It is concentrated in the ground, in the existing structure if there is one, and in anything the drawings have not yet decided.
A better approach is to carry contingency by area. Site and foundations, where unknown soil and buried utilities live, might carry 15 to 20 percent. Structure and envelope, which are well understood once designed, might carry 5. Interior fit-out, where the owner's selections can still change, carries something in between. Add a separate design contingency at the early stages that burns down as the drawings mature, and an owner's contingency that nobody but the owner can touch.
The total may still land near ten percent. The difference is that when the excavator hits rock in month two, the money is already sitting in the line that expected it.
The contractor's price is a bid, and a bid is a sales document as much as a cost document. It is produced by the party who wants the job, under time pressure, in a competitive situation, and it reflects that.
An independent estimate is a different animal. It is prepared by someone whose only job is to measure and price, with no stake in winning the work. Set against the contractor's bid, it does two things. It tells you whether the bid is realistic, which protects you from the low number that becomes a change-order machine in month nine. And it tells you where the bid is fat, which gives you something specific to negotiate instead of a general plea for a discount.
On a project of any size, the cost of that second number is a rounding error against the cost of finding out the first one was wrong.
A development budget is not a document; it is a series of them. The number at land acquisition, at schematic design, at permit, at tender, and at contract award should each be a fresh budget, built from the information available at that gate, and each should be saved alongside the one before it.
The history is where the learning lives. When the tender comes in 12 percent over the schematic estimate, the comparison shows exactly which lines moved and why, and the next project's early budget gets better. Developers who overwrite the old number with the new one lose that, and they make the same optimistic assumptions on every deal.
Investors and lenders will forgive a project that is late. They rarely forgive one that is over, because an overrun is money that has to be found from somewhere, usually from them, usually at the worst possible moment. The budget that prevents it is not clever. It is measured, it is time-based, it is honest about where the risk sits, and it is checked by someone with nothing to gain. Everything else in the pro forma sits on top of that number, so build it first and build it properly.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 15, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Embedded Finance, Artificial Intelligence And Data
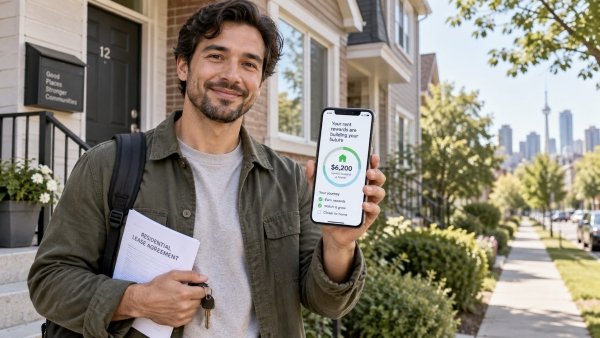
On September 15, 2026, Toronto-based Canadian proptech Zown updated its homebuying app with Rent Rewards alongside AI property search, affordability estimates, mortgage pre-approval and transaction services. Zown advertises up to 8% back on rent, giving it a reason to start working with consumers years before many will be ready to buy a home.
The 8% combines two potential rewards. Zown Money says Zown currently provides up to 4% cashback directly on rent, while an eligible credit card can add up to another 4% depending on the card's terms. At C$2,500 in monthly rent, Zown's 4% portion would equal C$100 a month or C$1,200 a year. If a renter also earned the full additional 4% through their card, the total could reach C$200 a month or C$2,400 a year before any card or payment-related costs.
The Canadian iPhone app, developed by Zown Realty Inc., also lets users upload a lease and proof of rent, search properties through an AI assistant called Zoro, view estimated affordability, request showings with licensed agents, seek mortgage pre-approval, submit offers and coordinate parts of closing. Zown Realty is an Ontario-registered real-estate brokerage. Mortgage rates, terms and qualification are provided through Vine Mortgage Group, and Zown says it isn't a direct mortgage lender.
Zown's model starts with a difficult Canadian problem. CMHC's 2026 Mortgage Consumer Survey found that recent buyers needed an average 4.4 years to save a down payment, while first-time buyers needed 4.7 years. Savings supplied the largest share of the down payment for 51% of first-time buyers. Another 23% of homebuyers received a financial gift, with a median gift of C$30,000. Rent Rewards give Zown a recurring reason to stay connected during those years.
Zown already has a more established incentive for buyers. Its Down Payment Boost returns up to 1.25% of a home's purchase price, capped at C$25,000, using part of the brokerage economics generated when a customer buys through Zown. On a C$1 million home, 1.25% equals C$12,500. Despite the product name, Zown's current guidance says the money arrives at closing and isn't counted as part of the mortgage down payment itself. Buyers can use it for closing and post-closing expenses.
Zown isn't alone in treating rent as financially useful activity. KOHO introduced rent cashback and credit reporting in Canada, while FrontLobby reports verified rent history to credit bureaus. Zown takes a different approach by connecting rent rewards with a later property purchase and the services surrounding it.
1. Rent is becoming a financial product. Canadian fintechs are attaching payments, rewards and credit reporting to one of the largest monthly household expenses. Toronto-based Chexy shows how quickly the category can scale. In March, the company raised C$14 million after starting with rent payments and said it had reached more than C$1 billion in annual payment volume and C$20 million in rewards value. Zown is pursuing a different end market, but rent serves the same commercial purpose of establishing a recurring financial interaction before other higher-value services are needed.
2. Housing costs are attracting more fintech models. Rent reporting, payment routing, rewards and short-term financing are competing for the same household expense. NCFA has tracked how fintech is entering rent and housing payments through companies including KOHO, Borrowell, Zenbase and Chexy. Zown adds another model by using rent rewards to encourage future homeownership and then connecting the renter to brokerage and mortgage services.
3. AI is getting closer to the financial decision. CMHC found that 16% of mortgage consumers who searched online used AI for mortgage information in 2026. HouseSigma says its Canadian platform has more than two million registered users and over five million monthly web visits, with AI used for valuation and market analysis. Zown's Zoro is competing in the same environment, focused on helping someone make a better property or financing decision. NCFA has identified the same commercial issue in decision intelligence across financial services.
It's a competitive field already. Wahi competes on digital brokerage and buyer cashback, Perch on digital mortgage readiness, FrontLobby on rent reporting, and HouseSigma on property search, valuation and market data. Zown's difference is the attempt to connect those stages much earlier, while the customer is still renting.
The economics improve if Rent Rewards keep customers engaged rather than simply subsidizing renters who eventually buy elsewhere. A traditional brokerage usually starts competing once someone begins seriously looking for a home. Zown can enter much earlier, stay connected through monthly rent, introduce affordability and mortgage tools, and eventually earn brokerage revenue if that renter buys through the platform.
That could lower the cost of finding future buyers and generate more revenue from each customer relationship. It can also become expensive if Zown funds rewards for several years without converting enough renters into completed transactions. The operating number worth watching should therefore be how many Rent Rewards users eventually become profitable Zown homebuyers?
Canadian mortgage companies, brokerages and property apps usually compete once someone is already thinking seriously about buying. If Zown can give renters enough financial value to earn their attention four or five years earlier, how much of the future homebuyer relationship can it own before the mortgage application even begins?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 15, 2026
Image credit: Pexels
Market volatility remains a persistent factor in wealth management, driving investors to seek strategies that balance capital stability with strategic diversification. While physical property has traditionally served as a tangible asset class, direct ownership often carries operational friction and localized concentration risk. Real estate funds present a structured alternative, pooling capital to access larger-scale assets under professional administration. However, evaluating these vehicles requires a realistic understanding of their risk profiles, liquidity terms, fee structures, and underlying statutory frameworks.
Managed real estate portfolios offer distinct operational benefits while introducing clear structural constraints:
While European Union institutions have increasingly pressured member states to restrict residency-by-investment programs, specific national jurisdictions maintain defined statutory pathways. Hungary’s Guest Investor Program offers a structured framework for international investors seeking European mobility alongside capital allocation.
Unlike former European programs that encouraged direct residential purchases—often driving up local housing prices—the Hungarian framework emphasizes institutional, regulated fund vehicles. Under this legal framework, securing a Hungary Golden Visa through real estate fund investment requires strict adherence to statutory criteria:
Long-term portfolio resilience requires evaluating operational realities beyond the initial statutory holding period:
Regulated real estate funds operate under strict prudential oversight, with the MNB supervising legal compliance, market solvency, and reporting standards. While professional management aims to optimize operational performance and generate targeted income distributions, yields are never guaranteed and remain subject to market conditions, management fee drag, and occupancy rates.
When integrated into a broader wealth strategy, managed real estate funds offer a transparent method for participating in property markets and achieving long-term mobility goals—provided investors align their liquidity expectations with the regulatory realities of the underlying vehicle.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 17, 2026 | NCFA Market Activity | Banking And Credit, Artificial Intelligence And Data

On August 17, 2026, Montréal-based Brdg confirmed a C$850,000 pre-seed round to expand its construction finance platform. One week earlier, Toronto-based Mortgage Automator launched Construction Draw Management, bringing construction budgets, draw schedules and approvals into the active loan file.
Brdg organizes project information across developers, cost consultants and lenders. Mortgage Automator brings draw control into the lender's loan system.
Brdg isn't a lender. Its software organizes the documents, budgets and project information used to prepare and review construction financing.
The platform accepts documents through email or upload, classifies them and organizes them into a project record. It tracks budgets, project progress and funding information, checks draw readiness across legal, contract, construction and financial categories, and produces lender-ready reports. Brdg provides separate workflows for developers, lenders and cost consultants. Its construction finance platform also shows document ingestion, project dashboards, cash-flow tracking and draw-disbursement readiness.
Brdg reports 30,000+ construction-related documents processed, more than C$300 million in development and active construction, and an average 5.5-day reduction in draw cycle time.
The document volume and reported time savings indicate that Brdg is being used in live construction finance workflows. The C$300 million figure describes development and active construction associated with Brdg's work. It is not revenue, loans originated, financing arranged or assets under management.
Brdg also describes the product as AI-powered and uses labels including Intelligence Agent and Submission Agent. Public evidence supports AI-assisted document and workflow processing. It does not establish autonomous underwriting or credit decisions.
Forum Ventures invested in Brdg, and the company joined its Summer 2026 cohort. Co-founder Ness Cabessa describes Brdg as replacing spreadsheets, email and manual draw processes with a structured construction finance platform.
Mortgage Automator starts from the lender side.
Its Draw Management feature keeps the construction budget inside the same system as the loan. Lenders build budget categories, line items and amounts in Mortgage Automator, then manage planned or ad hoc draw requests against that budget.
The system flags variances and can enforce configurable loan-to-cost limits. Project Health compares work completed with funds already disbursed, giving lenders another way to identify budget drift across active construction loans.
Mortgage Automator says the feature responds to private mortgage lenders, including construction and fix-and-flip lenders that were managing loans in one system while tracking construction budgets in spreadsheets or separate software.
A developer may prepare budgets, invoices and supporting documents. Cost consultants review project costs and progress. Lenders determine whether conditions have been met before additional funds are released.
Construction loans release financing in stages because lenders need evidence that work and project costs are progressing before advancing more capital.
That process is visible in Canada's public construction financing system. CMHC's Apartment Construction Loan Program provides loans starting at C$1 million and can finance up to 100% of the residential component's cost for qualifying projects.
The federal program has been expanded to more than C$55 billion in loan funding. Some program streams use monthly construction draws once the loan agreement is in place.
Every draw can bring another set of budgets, invoices, progress information, contracts, approvals and supporting reports into the financing process.
Cost consultants are also part of that control chain. They can review construction progress, costs and supporting documentation before lenders release additional financing.
Brdg structures project information before and during lender review. Mortgage Automator keeps budgets and draw controls attached to the active loan.
The next evolution is to carry the same structured project data from developers and cost consultants into lender systems without rebuilding it at each stage.
That would reduce duplicate data entry, make budget changes easier to trace and give lenders a clearer record of what changed between draw requests.
The open question is how the market develops from here. Lenders may prefer draw tools built into their loan systems. Developers and cost consultants may need platforms that work across several lenders. Integrations could eventually connect the two.
Will construction finance software remain split between developer, consultant and lender workflows, or will shared project data eventually connect the full draw process?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016