





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 22, 2026 | NCFA Market Activity | Banking And Credit Infrastructure, Payments And Market Infrastructure, Lending Consumer Credit And BNPL, Artificial Intelligence And Data
On May 21, 2026, Wealthsimple unveiled a major expansion of its financial services platform during its live product event, “Wealthsimple Takes Over Your Life”. The announcements included family accounts, business chequing, USD accounts, portfolio backed credit, spend insights, overdraft protection, and a monthly $1M client rewards program. The company said more than 4 million Canadians now use Wealthsimple and hold $150B in assets on the platform.
Wealthsimple isn't a Schedule I bank, but it delivers banking style services through regulated Wealthsimple entities, infrastructure access, and partner financial institutions. Wealthsimple says chequing balances are held in trust with CDIC member institutions, while Wealthsimple Payments Inc. and Wealthsimple Investments Inc. are not CDIC member institutions. Power Corporation disclosed a controlling interest in Wealthsimple through Power Financial, Great-West Lifeco, and IGM. In Q1 2026 results, Power valued its Wealthsimple ownership at $3.8B as of March 31, 2026.
NCFA also covered Wealthsimple’s $750M financing and $10B valuation, which gave Canadian fintech markets one of the rarest and strongest scaleup stories.
The event hit home how far Wealthsimple has moved beyond investing and trading. The company now wants a larger share of daily financial activity across deposits, payments, borrowing, business banking, and household finance.
This builds on earlier product expansion when Wealthsimple added credit and loan tools in 2025, including a cash back credit card and low interest credit line. The latest event pushes that same strategy further into operating accounts, secured borrowing, and household controls.
The business banking launch carried the clearest fintech impact. Wealthsimple introduced business chequing with online setup in less than 20 minutes, virtual cards, automated CRA payments, recurring transfers, interest bearing balances, and higher e transfer limits.
Those features target familiar problems for Canadian SMEs. Many owners still deal with low transfer limits, little or no yield on operating balances, manual tax payments, and weak cash management tools.
The Portfolio Line Of Credit may become one of the company’s most important financial products. Wealthsimple said eligible clients can borrow against portfolios at rates as low as prime minus 0.5%, or about 3.95% at the time of the event.
Clients can borrow up to 35% of portfolio value. A client with $200,000 on the platform could access up to $70,000 in credit, subject to eligibility and risk controls.
The product gives clients a way to fund business expenses, inventory purchases, major purchases, or debt refinancing without selling investments. This type of secured liquidity has historically been more common in private banking and wealth management.
For Wealthsimple, portfolio credit also deepens the customer relationship. The more assets clients keep on the platform, the more useful the credit product becomes.
Wealthsimple introduced three family finance products. Kids and teens accounts give parents card controls, alerts, limits, instant transfers, and parent paid interest. Households lets partners choose what they share, track accounts inside and outside Wealthsimple, and view family finances in one place.
Authorized traders lets a trusted family member make trades on another person’s behalf without password sharing. That addresses a practical issue. Many Canadians already help spouses, parents, or relatives manage investments informally. Wealthsimple is formalizing that process with permission based account access.
Wealthsimple also pointed to deeper access across Canadian payment systems. The company linked that access to cheaper wire transfers, free incoming wires, faster payroll deposits, lower FX costs, instant virtual card issuance, cash deposits through Canada Post, and ATM fee reimbursements.
Wealthsimple gained direct Swift access, becoming the first Canadian fintech to do so. It supports the company’s push into wires, cross border money movement, and lower cost global payments.
The Canada Post cash deposit feature gives clients access to more than 5,000 deposit locations. Wealthsimple said it processed cash deposit transactions in more than 900 communities during the first two months after launch.
Infrastructure access increasingly matters for large fintech platforms. It can improve speed, pricing, product flexibility, and customer experience while reducing dependence on older branch based banking workflows.
Wealthsimple’s Monthly Millionaire program will award $1M each month to one client. Every dollar deposited or saved creates an entry, while direct deposit doubles entries. Move over 'roll up the rim to win'!
The structure encourages clients to move payroll deposits and savings activity onto the platform. For Wealthsimple, that supports higher deposits, stronger engagement, and more primary account usage.
Canadian fintech competition is increasingly focused on who controls the broader financial relationship, not just a single product category. Wealthsimple now spans deposits, payments, investing, borrowing, family finance, business banking, and cross border accounts.
That puts the company into more direct competition with incumbent financial institutions across several revenue areas at once. The company's expansion shows how quickly a Canadian fintech can move when scale, capital, trust, and distribution come together.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 24, 2026 | NCFA Feature | AI Finance And Data Governance
On Mar 23 2026, OSFI and the Global Risk Institute published the FIFAI II final report based on four workshops held between May and November 2025. More than 170 participants took part across banks, insurers, asset managers, fintechs, vendors, regulators, academics, and consumer voices.
The report confirms that AI adoption is here, citing 72% AI use at work in financial services and 75% organizational support for AI. While AI is already in use. The real issue is what still limits its use in regulated decisions and customer outcomes.
The series covered four areas that affect operational, prudential, consumer, and system-wide risk at the same time. Full report and framework: FIFAI II final report and AGILE framework PDF
One of the clearest takeaways is that AI will not spread across finance at the same speed. The first gains will come in internal functions such as fraud detection, surveillance, reporting, cyber defence, and operations. Those areas already have strong data, measurable outputs, and clearer accountability.
Customer-facing decisions are different. Underwriting, advice, product recommendations, and self-serve tools carry more pressure around explainability, fairness, consent, and complaints handling.
AI powered Canadian finance will likely grow faster in control functions than in customer-facing decisions.
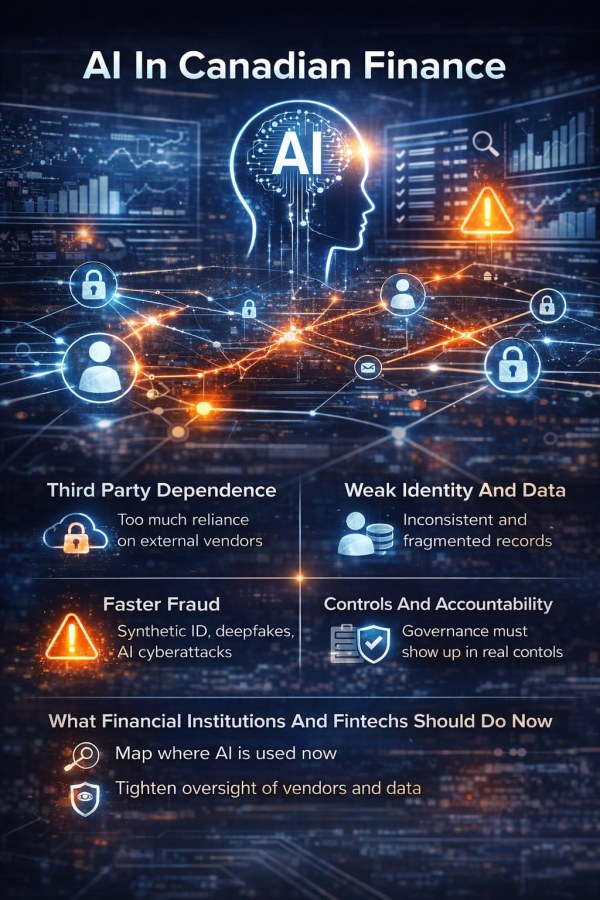
The report treats third party AI as more than a procurement issue. It highlights growing dependence on external providers for models, infrastructure, and data, along with limited visibility into how those systems work and who sits behind them.
It's important because a failure, outage, or change in access at one provider can affect more than one function at the same time. Fraud controls, underwriting tools, customer service, and risk monitoring can all be exposed together. The financial stability workshop adds to that concern by linking third party dependency to concentration and system level risk.
Banks, insurers, and fintechs will need stronger oversight of models and providers, better audit access, tested fallback plans, and clearer visibility into the wider supply chain behind key AI services.
AI is improving both offence and defence. The final report points to synthetic identity, deepfakes, voice spoofing, AI assisted cyberattacks, fraud as a service, and disinformation. It notes a sharp rise in deepfake attacks and growing concern about voice verification as AI voice cloning improves.
This reality changes the operating environment. Static controls lose value faster when attack tools get cheaper, stronger, and easier to use. Manual review and occasional rule updates will not be enough. Firms will need faster detection, stronger identity controls, better information sharing, and systems that can adjust while attacks are happening.
Data problems come up across the whole series, but the larger issue is bigger than data quality alone. Weak identity and fragmented data still limit how far AI can go in regulated finance. The report points to inconsistent data, incomplete records, fragmented platforms, offshore storage concerns, and weak data lineage as barriers to both efficiency and safety.
The report doesn't mince words on identity. Canada still doesn't have a widely adopted secure digital identity layer. That leaves onboarding, authentication, consumer channels, remote work, and agent based systems more exposed than they should be. If identity and data remains weak, AI will keep working best in narrower internal use cases and face more limits in customer facing execution.
The final report introduces the AGILE framework as part of its overall findings, which stands for Awareness, Guardrails, Innovation, Learning, and Ecosystem Resiliency. The framework calls for stronger governance and oversight, stronger data and risk controls, continued investment in technology and talent, and deeper public private collaboration.
AI oversight cannot remain just at the strategy level. If AI is used in lending, fraud, underwriting, complaints, or customer recommendations, governance has to show up in controls, evidence, escalation, and accountability. In regulated finance, that's what turns AI use from experimentation into something firms can defend and scale.
The workshop series points to a practical sequence:
First, identify where AI already impacts decisions and controls.
Second, separate the use cases that can scale now from the ones that still need stronger explainability and customer safeguards.
Third, tighten vendor oversight before dependency grows further.
Fourth, invest more in identity, data lineage (origin and how it's used and updated), and real time fraud controls.
Fifth, show boards stronger evidence instead of high level claims and broad assurance language.
The report also carries a warning worth taking seriously. Firms that move too slowly can fall behind on productivity, resilience, and customer expectations while still facing external AI enabled threats. One participant line stands out: “The biggest risk is not doing enough.”
Canada’s national AI strategy work has focused heavily on trust, safety, and responsible adoption. That is necessary, but this workshop series adds something more useful for operators. It shows where AI use slows once it enters regulated finance: concentrated provider risk, weak identity, fragmented data, explainability pressure, fraud risk, and unclear accountability.
There's a call to action policy lesson here too. Canada doesn't just need AI ambition and adoption. It needs stronger execution layers around Digital ID, data governance, third party oversight, and information sharing if it wants regulated financial AI to scale beyond contained pilots.
The OSFI and GRI workshop series is useful because it takes a holistic approach to identifying and adapting to AI risks in finance. AI is already inside financial systems. The advantage now goes to firms that can prove control, trust, and accountability in live decisions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 19, 2026 | CIX Summit | NCFA Community Partner Update

The CIX Summit, Powered by Elevate, is almost here! This one day strategic conference for investors and founders takes place in Toronto on March 25, and this is the final window to secure your spot. If you are raising capital or actively investing, this is where founders and investors meet for conversations that can move toward real deals.
NCFA is a community partner because CIX brings a concentrated mix of high growth startups, active investors, and decision makers into one room, in one day.
CIX is built around access. Founders get in front of investors. Investors get direct exposure to companies that are actively building and raising. That opportunity gets tighter as the event gets closer. The strongest attendees lock in meetings early and show up with a clear plan.
NCFA has already covered the 2026 CIX startup award winners, the Wealthsimple Innovator of the Year recognition, and the CIX Summit 2026 agenda release. At this stage, the only question you need to ask yourself is whether you need to be in the room?
NCFA is sharing a 20% community partner discount on CIX Summit passes for its community.
Use CIXNCFA20 for 20% off. CIX runs on March 25, 2026 in downtown Toronto.
Secure your spot through CIX Summit 2026 ticket details and March 25 venue information.
If you are serious about raising, investing, or building relationships that can move a deal forward, register now.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 5, 2026 | NCFA Fintech Market Insight | Open Banking And Policy And Market Structure

Image: Freepik/Drazen Zigic
On Mar 5 2026, the Bank of Canada made open banking timing comments at an Open Banking Expo highlighting timing and delivery risk. The central bank is still in the requirements stage and it will not commit to a launch date.
“somewhat daunted”
“the information-gathering stage alone will take months.”
In a LinkedIn post, Claire Brownell of The Logic also wrote that Ron Morrow, Executive Director of Payments, Supervision and Oversight, at the bank, “stopped short of confirming” that a 2026 launch is no longer realistic and said the information gathering stage “could take months,” with a clearer timeline only after that work finishes. Canada is still defining how open banking works before it can ship.
Yes, you heard it right. After almost a decade of analyzing, preparing, announcing, and promising the implementation of Consumer-driven Finance (aka Open Banking), the market learns that the bank is still in the information gathering phase.
Requirements work sounds boring, but it sets the rails for everything that follows. It decides which data gets shared, how consent works, how liability lands, how disputes get handled, and what the security bar looks like for every approved participant.
Canada already has a policy target, but the issue is execution speed. Canada's consumer driven banking framework describes open banking as a secure system that lets people and businesses share financial data with approved providers of their choice. Delay keeps Canadians stuck with expensive workarounds for data sharing and money movement like screen scraping.
Firms need clear standards on what data gets shared, how consent works, who is responsible when something goes wrong, and who can join the system. Without that clarity, banks and larger firms delay and smaller firms waste time building for rules that may change.
Delay also changes what gets built. Fintechs keep using screen scraping, password sharing, and one off partnerships because those options work today. That rewards the firms that already control customer access, instead of the firms building safer permission based tools.
Fintechs who have in some cases been waiting years for Open Banking's arrival can continue planning for two tracks. Keep shipping products that work under today’s rails, but design the next version around consumer permissioning, clean audit trails, and repeatable consent. Treat identity, consent, and dispute handling as core product work, not legal add ons. Companies that have these pieces in place will be ready when approval and accreditation rules finally arrive.
The cost of delay is that Canada keeps paying for friction, and Canadian fintechs keep competing with one hand tied behind their back.
If the requirements stage takes months, what needs to change so Canada ships a clear rule set fast enough for fintechs and banks to invest with confidence?
Hopefully this latest timing hiccup will lead to a safer, and more competitive data and payments layer in Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 5, 2026 | CIX Summit 2026

Image courtesy of CIX, Powered by Elevate, March 25, 2026
On March 4, 2026, CIX Summit confirms the 2026 summit agenda now live and tees up the March 25 Toronto event, with NCFA participating as a community partner.
The agenda puts investor founder connection at the center of the day, with an Investor Forum built for candid capital conversations and a Founder Forum focused on fundraising and scaling. It also includes Scale Beyond Borders with Global Affairs Canada and founders sharing practical market entry experience, plus Cracking the VC Code on funding strategies for women founders and how to navigate fundraising in today’s market.
CIX also spotlights this year’s Innovator of the Year fireside chat with Wealthsimple CEO and co founder Mike Katchen
CIX also names 14 Canadian startup award winners for 2026, which helps founders and investors see who CIX is already ranking as standout teams.
CIX confirms that on March 9 at 12:00 PM EST Meeting Exchange bookings become open (must be CIX Startup passholder, format is one to one). These meetings are for startups from pre-seed to growth capital, with investor types that include incubators, accelerators, angels, venture funds, corporate venture teams, and debt providers across major tech sectors.

NCFA is sharing a 20% community partner discount on CIX Summit passes for its community. Use CIXNCFA20 for 20% off. CIX runs on March 25, 2026 in downtown Toronto. CIX publishes ticket options and event logistics on its official page for CIX Summit 2026 ticket details and March 25 venue information.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 5, 2026 | NCFA Fintech Market Insight | Digital Assets And Policy And Regulation

On January 29 2026, at the joint SEC CFTC event in Washington titled CFTC SEC Harmonization U.S. Financial Leadership in the Crypto Era.
CFTC Chair Michael S. Selig’s remarks laid out a detailed US policy direction for crypto market structure. The speech goes past broad support for innovation and points to specific rule work on tokenized collateral, perpetual derivatives, software safe harbours, retail leveraged crypto trading, and event contracts.
SEC Chair Paul S. Atkins’ remarks support the same direction from the SEC side, which is part Project Crypto.
“Fragmented regulation in an integrated market is not a safeguard for investors so much as a source of confusion among them.”
That line from Atkins defines the problem. Unclear boundaries change how firms structure products, where they launch, and how much they spend on compliance before they can scale.
“Project Crypto recognizes that crypto markets span across our agencies’ respective regulatory boundaries.”
Selig starts from the point that crypto products don't fit neatly into older lines between agencies. Clearer lines are needed to cut the cost of operating in uncertainty.
“I have directed CFTC staff to develop rules to enable the responsible deployment of additional forms of eligible tokenized collateral.”
Eligible collateral is what a trading venue accepts to back positions. It decides how much margin traders need, how fast funds move, and how safely trades settle. If the CFTC allows more tokenized assets to count as eligible collateral, more crypto trading can happen inside regulated U.S. markets, but custody and collateral movement will need tighter controls and clearer proof that assets are protected and available when they are needed.
“The CFTC will use the tools at its disposal to onshore perpetual and other novel derivative products so that they can flourish across both centralized and decentralized markets, subject to appropriate safeguards.”
Perpetuals are a popular kind of crypto futures that many platforms offer outside the U.S. If U.S. rules start allowing them in a regulated way, more trading, market making, and new product builds can move onshore. That would also make it harder for offshore exchanges to keep growing just because the U.S. has no clear legal path today.
“The CFTC will explore ways in which the agency can encourage innovation in software development and support builders as they work toward product market fit, including by assessing whether an innovation exemption may be appropriate in certain circumstances.”
This targets a hard issue in crypto regulation. Wallets, interfaces, and on chain software do not fit cleanly into rules built around centralized intermediaries. If the CFTC creates clearer room for software development and early stage testing, legal uncertainty will be reduced for teams building core infrastructure.
“As part of this harmonization effort, we will examine whether substituted compliance can achieve equivalent or better regulatory outcomes at lower costs for market participants.”
This is about cost, duplication, and speed. Overlapping requirements can turn compliance into a barrier to entry. Substituted compliance can cut repeated work where two regimes are trying to solve the same control problem.
“Within the bounds of the law and where appropriate, market participants should be able to offer multiple products through a single platform without navigating an inefficient patchwork of registrations and overlapping regulatory regimes.”
This points to a model where firms can run more of their product stack under one platform instead of splitting activity across separate legal and operational silos. That can improve operating leverage for exchanges, brokers, and infrastructure firms that want to offer more than one regulated product. Also see broader SEC direction in Atkins crypto rules testimony.
“I have directed CFTC staff to begin drafting rules clarifying when leveraged, margined, or financed retail commodity transactions in crypto may be offered off-exchange under an ‘actual delivery’ exception.”
Retail users can already get leveraged crypto in some places, but U.S. rules have left big gaps in what is clearly allowed. If the CFTC writes clearer rules, firms will know which leverage products they can offer, which ones are off limits, and what steps they must follow to stay compliant.
“I have directed CFTC staff to explore the creation of a new category of DCM registration that is tailored specifically to retail leveraged, margined, or financed crypto asset trading.”
This suggests the CFTC may create a new kind of regulated exchange category built specifically for retail leveraged crypto trading. If it does, firms will be able to design products and go to market using a clearer venue rulebook, and exchanges will compete on who can offer the best compliant access and distribution.
“First, I have directed CFTC staff to withdraw the 2024 event contracts rule proposal that would prohibit political and sports-related event contracts and the 2025 staff advisory.”
This removes a major source of uncertainty around prediction markets.
“Second, looking ahead, and in the spirit of markets that trade on expectations, I have directed CFTC staff to move forward with drafting an event contracts rulemaking.”
Withdrawing the old proposal reduces near term uncertainty, but new event contract regulations would spell out which event-based contracts are allowed, what monitoring and controls platforms must run, and how firms can build prediction style products without guessing where the line is.
These speech commitments point to a practical attempt to aggregate more products, more liquidity, and more infrastructure into regulated US channels. Tokenized collateral, perpetuals, retail leveraged crypto, and event contracts are all in the spotlight with real market share potential. Companies that can meet the bar for custody, risk controls, disclosures, and auditable operations can begin building onshore products more confidentially than they could before.
The CFTC and SEC discussion focuses on market structure, but tokenized collateral and onshore crypto venues still rely on a settlement instrument that can hold up under supervision. That is why the stablecoin perimeter matters.
On February 25, 2026, the OCC issued a notice of proposed rulemaking (See: OCC stablecoin NPRM) to implement the GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins Act) for payment stablecoin issuance and related activities under OCC jurisdiction, including national banks and their subsidiaries, federal savings associations and their subsidiaries, federal branches and their subsidiaries, and foreign payment stablecoin issuers, along with entities approved as federal qualified payment stablecoin issuers and certain state qualified issuers. The OCC points to a new 12 CFR 15 that covers reserve assets, redemption, risk management, audits and supervision, custody, applications and registrations, examination of foreign issuers, and a capital and operational backstop.
While the OCC moves ahead with rulemaking under the GENIUS Act, the legislative framework for crypto market structure is still contested in Washington. A Reuters report from March 5, 2026 on the crypto bill impasse in Congress describes renewed disagreement over stablecoin related customer rewards and whether they could draw deposits away from banks. The dispute shows that even as regulators move ahead with rules for trading infrastructure, tokenized collateral, and stablecoin issuance, Congress is still debating how far crypto firms should be allowed to compete with the traditional deposit system.
If the CFTC and SEC push tokenized collateral, perpetuals, and event contracts into regulated channels while the OCC pushes stablecoin issuance into a bank style rulebook, does the next U.S. advantage move to firms that can run both market structure and the cash leg under supervision?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
CIX Summit 2026 | February 11, 2026

Image courtesy of CIX Summit, Powered by Elevate
On February 10, 2026, Elevate announced the 2026 CIX Startup Award winners across fintech, climate, defence, health, and marketing technology, naming fourteen Canadian companies selected from more than 370 applications reviewed by 94 North American investors. CIX confirms that the winners present live at the CIX Summit on March 25, 2026 at the Design Exchange in Toronto, with the program bringing together 600 plus investors, founders, and tech leaders.
In the release, CIX reaffirms their commitment to the startup ecosystem as they call out a difficult funding moment, with trade tension between the US and Canada and the lowest level of Canadian VC investment since 2020.
2026 CIX Startup Award recipients across emerging, early, and growth categories.
Emerging includes PRE in marketing technology from Toronto, Sonaro in health technology from Montreal, Cashew Research in marketing technology from Calgary, Elle, MD Biotechnologies in health technology from New Minas, NS, and Xubin Aerospace in defence technology from Oakville.
Early includes Qidni Labs in medical technology from Kitchener, WeavAir in climate technology from Toronto, Pontosense in medical technology from Toronto, MedMe Health in health technology from Toronto, and LiORA in climate technology from Calgary.
Growth includes Venn in fintech from Toronto, Eavor Technologies in climate technology from Calgary, Loopio in sales automation from Toronto, and Hiive in fintech from Vancouver.
In a year where capital remains disciplined and deployment cycles lengthen, fintech infrastructure companies continue to attract investor attention. The 2026 CIX Growth category includes two fintech scaleups, Venn and Hiive.
Venn operates in digital financial services infrastructure for businesses (embedded finance and SME operating layer). In Venn's public announcement following the award, the company confirmed that more than 5,000 businesses have chosen Venn to run their finances over the past year, highlighting product coverage across banking, payments, cards, and automation.
Hiive builds marketplace infrastructure for private company share transactions. As venture timelines extend and liquidity windows narrow, structured secondary marketplaces play an increasingly important role in capital efficiency. Recognition in the CIX Growth category places Hiive among a cohort of scaleups building market infrastructure rather than consumer facing apps.
Both companies operate at the financial layer of the innovation economy. One focuses on modernizing how businesses manage money. The other addresses private market liquidity. Together they reflect two core pressures in today’s ecosystem: operational efficiency and capital access.
Beyond fintech, the 2026 CIX winners span climate technology, health technology, defence technology, and enterprise software across emerging, early, and growth stages. Companies such as WeavAir, LiORA, and Eavor Technologies represent climate innovation, while others address diagnostics, aerospace, marketing intelligence, and automation.
CIX states that more than 370 applications were reviewed by 94 North American investors, with a minimum of 15 judges evaluating each submission across business model, innovation, market opportunity, management depth, and leadership diversity, equity, and inclusion. In a slower venture market, that level of screening provides an important validation signal for founders seeking capital.
Neha Kera, Managing Partner at Innovobot Resonance Ventures and CIX Startup Awards Co Chair:
“It is a challenging time for entrepreneurs, and so it was wonderful to see the quality of this year's CIX winners,” and adds, “We are eager to see what else they will accomplish in the years to come, and I hope everyone can learn more about them at CIX”.
Matthew Leibowitz, Managing General Partner at Plaza Ventures and CIX Startup Awards Co Chair:
“The competition was intense with over 350 applicants, and our selection committee did a stellar job in selecting the winners,” and adds, “We're thrilled to shine a spotlight on this year's recipients and can't wait to meet them at CIX Summit.”
The announcement also highlights a practical reason founders show up. It says Meeting Exchanges include over 75 investors taking 1 to 1 meetings with founders, creating over 450 meeting opportunities across the day. CIX also describes a closed door Investor Forum for VCs and LPs, plus a Founder Forum focused on seed round execution, cap table structure, and non dilutive capital.
Congratulations to all fourteen teams. Canada needs more companies that keep building through hard cycles, keep hiring, keep shipping product, and keep finding customers. NCFA looks forward to tracking these founders as they turn national recognition into revenue, partnerships, and global growth.
NCFA is sharing a 20% community partner discount on CIX Summit passes for its community. Use CIXNCFA20 for 20% off. CIX runs on March 25, 2026 in downtown Toronto. CIX publishes ticket options and event logistics on its official page for CIX Summit 2026 ticket details and March 25 venue information.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
