





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Apr 3, 2026 | NCFA Innovation Perspective | Moonshot Thinking

On April 1, 2026, Canada’s Artemis II mission reaches launch as Canadian astronaut Jeremy Hansen boards NASA’s Orion spacecraft, becoming the first Canadian and first non American on a mission beyond Earth orbit to the Moon.
It’s the first crewed Moon mission since 1972, and the 10 day flight around the Moon is designed to carry humans further from Earth than any mission before. For Canada, it’s proof that bold ambition still counts when a country backs talent, engineering, and strategic partnerships over a long stretch of time.
Artemis II isn’t the result of a quick push or a short funding cycle. It reflects decades of work in robotics, advanced systems, and international collaboration. Canada didn't get this seat by accident. It earned it. More founders, investors, institutions, and policymakers should stop and think about that.
Big outcomes rarely appear overnight. By the time the world sees the launch, the hard part has already been building quietly for years. Artemis II carries four astronauts around the Moon and back. Hansen’s place on that crew shows that Canada still plays a meaningful role in one of the most important technology programs now underway. That role is tied to long term Canadian contributions in space robotics, including the Canadarm legacy and Canada’s Canadarm3 commitment to the Lunar Gateway.
Ambition on its own is cheap. Everyone says they want to build big things. What matters is whether people keep going when the payoff is far away, the standards stay high, and the result is still uncertain. Artemis II shows what can happen when the mission stays clear and people stay committed.
This reaches far beyond aerospace. In fintech, financial infrastructure, artificial intelligence, and other serious technology sectors, people often talk about transformation. But real transformation asks for something uncomfortable. It asks for patience from backers, fellow builders and community. It asks for coordination. It asks for institutions that can think beyond the next quarter.
If Canada wants stronger digital identity systems, better financial infrastructure, more globally competitive AI companies, deeper capital markets, and more durable domestic champions, it can’t keep thinking small and expect outsized results. Those goals take time. They take conviction. They take leadership that sticks with the work long enough for the advantage to build.
Artemis II gives Canada a live example of what that looks like when the bet is real, the timeline is long, and the standard doesn’t drop.
Canada has talent. It has real technical depth. It has researchers, engineers, operators, and builders who can compete globally. What it often lacks is the willingness to place bigger bets and stay with them long enough. Artemis II is important for at least one key moonshot innovation reason. It exposes a familiar Canadian habit. We talk like a country with big potential, then act like one that is afraid to commit.
This mission shows that Canada can still contribute at the highest level when it decides to stay in the game. It also shows that credibility is earned over time. You don’t get invited into missions like this because people are being polite. You get there because your contribution is important and your capability is trusted. That should sound familiar to anyone trying to build a serious company in a serious market.
Moonshot thinking does not mean reckless thinking. It means taking on problems that are hard enough to matter and important enough to justify sustained effort. In practical terms, that could mean building financial infrastructure that removes friction across the system, creating AI tools that solve real regulated workflow problems, or designing funding models that help strong Canadian companies scale here instead of leaving early.
At first, that kind of ambition can look expensive, slow, or unrealistic. Later, it often looks obvious. That’s how breakthroughs actually play out. Artemis II is a reminder that countries don't build lasting relevance by backing lots of small bets. t’s built by committing to the work that defines what comes next.
Jeremy Hansen’s flight around the Moon gives Canada a rare public moment people can feel right away. The deeper value sits underneath that moment. This mission shows what long horizon ambition looks like when people actually follow through. It shows younger builders what serious technical achievement looks like. It shows investors and policymakers that long cycle bets can produce real global relevance. And it shows that Canada still has the ability to achieve moonshots when it chooses to commit.
The question now is whether Canada treats Artemis II as a celebration or as a standard. One gives us a proud moment. The other gives us something much more valuable. It gives us permission to think bigger, build longer, and stop pretending that incremental ambition will somehow produce exceptional results.
If this is what Canada can build over decades, what are you building today that is worth the same commitment?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 24, 2026 | NCFA Feature | AI Finance And Data Governance
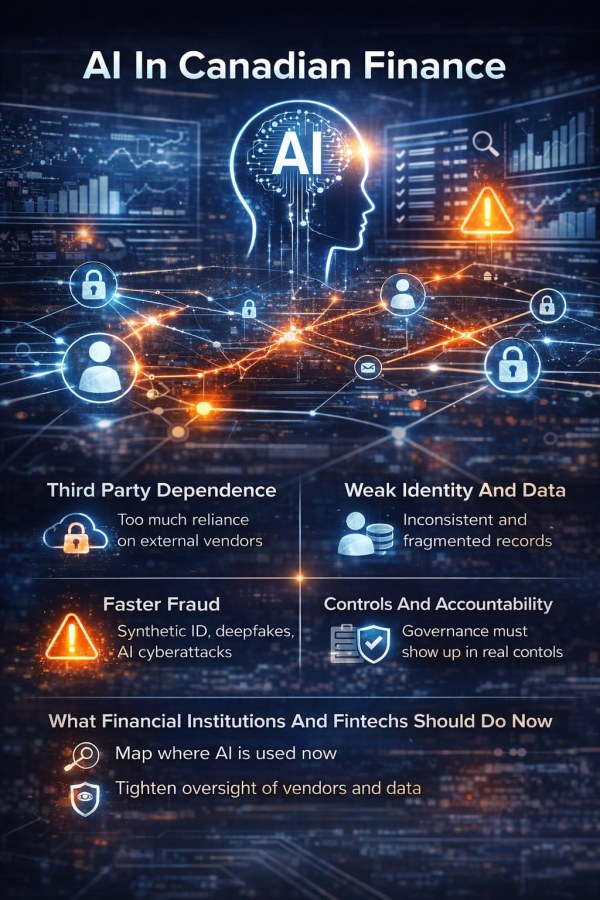
On Mar 23 2026, OSFI and the Global Risk Institute published the FIFAI II final report based on four workshops held between May and November 2025. More than 170 participants took part across banks, insurers, asset managers, fintechs, vendors, regulators, academics, and consumer voices.
The report confirms that AI adoption is here, citing 72% AI use at work in financial services and 75% organizational support for AI. While AI is already in use. The real issue is what still limits its use in regulated decisions and customer outcomes.
The series covered four areas that affect operational, prudential, consumer, and system-wide risk at the same time. Full report and framework: FIFAI II final report and AGILE framework PDF
One of the clearest takeaways is that AI will not spread across finance at the same speed. The first gains will come in internal functions such as fraud detection, surveillance, reporting, cyber defence, and operations. Those areas already have strong data, measurable outputs, and clearer accountability.
Customer-facing decisions are different. Underwriting, advice, product recommendations, and self-serve tools carry more pressure around explainability, fairness, consent, and complaints handling.
AI powered Canadian finance will likely grow faster in control functions than in customer-facing decisions.
The report treats third party AI as more than a procurement issue. It highlights growing dependence on external providers for models, infrastructure, and data, along with limited visibility into how those systems work and who sits behind them.
It's important because a failure, outage, or change in access at one provider can affect more than one function at the same time. Fraud controls, underwriting tools, customer service, and risk monitoring can all be exposed together. The financial stability workshop adds to that concern by linking third party dependency to concentration and system level risk.
Banks, insurers, and fintechs will need stronger oversight of models and providers, better audit access, tested fallback plans, and clearer visibility into the wider supply chain behind key AI services.
AI is improving both offence and defence. The final report points to synthetic identity, deepfakes, voice spoofing, AI assisted cyberattacks, fraud as a service, and disinformation. It notes a sharp rise in deepfake attacks and growing concern about voice verification as AI voice cloning improves.
This reality changes the operating environment. Static controls lose value faster when attack tools get cheaper, stronger, and easier to use. Manual review and occasional rule updates will not be enough. Firms will need faster detection, stronger identity controls, better information sharing, and systems that can adjust while attacks are happening.
Data problems come up across the whole series, but the larger issue is bigger than data quality alone. Weak identity and fragmented data still limit how far AI can go in regulated finance. The report points to inconsistent data, incomplete records, fragmented platforms, offshore storage concerns, and weak data lineage as barriers to both efficiency and safety.
The report doesn't mince words on identity. Canada still doesn't have a widely adopted secure digital identity layer. That leaves onboarding, authentication, consumer channels, remote work, and agent based systems more exposed than they should be. If identity and data remains weak, AI will keep working best in narrower internal use cases and face more limits in customer facing execution.
The final report introduces the AGILE framework as part of its overall findings, which stands for Awareness, Guardrails, Innovation, Learning, and Ecosystem Resiliency. The framework calls for stronger governance and oversight, stronger data and risk controls, continued investment in technology and talent, and deeper public private collaboration.
AI oversight cannot remain just at the strategy level. If AI is used in lending, fraud, underwriting, complaints, or customer recommendations, governance has to show up in controls, evidence, escalation, and accountability. In regulated finance, that's what turns AI use from experimentation into something firms can defend and scale.
The workshop series points to a practical sequence:
First, identify where AI already impacts decisions and controls.
Second, separate the use cases that can scale now from the ones that still need stronger explainability and customer safeguards.
Third, tighten vendor oversight before dependency grows further.
Fourth, invest more in identity, data lineage (origin and how it's used and updated), and real time fraud controls.
Fifth, show boards stronger evidence instead of high level claims and broad assurance language.
The report also carries a warning worth taking seriously. Firms that move too slowly can fall behind on productivity, resilience, and customer expectations while still facing external AI enabled threats. One participant line stands out: “The biggest risk is not doing enough.”
Canada’s national AI strategy work has focused heavily on trust, safety, and responsible adoption. That is necessary, but this workshop series adds something more useful for operators. It shows where AI use slows once it enters regulated finance: concentrated provider risk, weak identity, fragmented data, explainability pressure, fraud risk, and unclear accountability.
There's a call to action policy lesson here too. Canada doesn't just need AI ambition and adoption. It needs stronger execution layers around Digital ID, data governance, third party oversight, and information sharing if it wants regulated financial AI to scale beyond contained pilots.
The OSFI and GRI workshop series is useful because it takes a holistic approach to identifying and adapting to AI risks in finance. AI is already inside financial systems. The advantage now goes to firms that can prove control, trust, and accountability in live decisions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 19, 2026 | NCFA Feature | AI Finance Policy
On Jan 27 2026, the UK Financial Conduct Authority launched the Mills Review into the long term impact of AI on retail financial services to examine how AI could reshape consumers, firms, markets, and regulation through to 2030. NCFA flagged the review earlier in NCFA Weekly Fintech Intelligence Jan 24-30, 2026.
On Mar 4 2026, Innovate Finance submitted its response to the Mills Review, setting out where the UK fintech industry believes deployment will stall unless policy and infrastructure move faster. The paper cites Bank of England and FCA data showing 75% of firms now use AI, up from 58% in 2022. The issue is no longer whether AI adoption will happen. It is what still blocks firms from using AI inside live financial workflows at scale.
AI is clearly evolving from chatbot assistance to execution at scale. The submission describes AI agentic systems that can act on behalf of users. One example is an AI bot that handles everything from comparing mortgage deals to submitting the application and coordinating with conveyancers under user permission.
The value is no longer only in the model itself (ie. speed, quality, cost, expertise), but rather the full operational chain from customer permission to data access to execution to payment. That's why industry is focused on a stacked layer of tech solutions from Open Finance and Digital ID to payment access and rulebook friction to ensure AI can fully complete financial tasks.
The same logic applies to industry concerns over gatekeepers. As AI agents begin to initiate and route transactions, control moves to the layer that connects the agent to the payment method and the financial product. If that layer becomes concentrated, a small number of providers can influence access, routing, and competition.
The response uses real commercial examples and market data, highlighting that AI in finance is already underwriting, trading, core banking, and compliance.
The next phase isn't whether or not firms can build AI tools. It is whether regulation and infrastructure will allow them to use those tools in broader customer and transaction flows.
The stronger points made is that AI in finance won't scale on model quality alone. It will however scale on the stack around the model. That means smart data, Open Finance, Digital ID, fraud data sharing, wallet infrastructure, and payment access. Without those layers, AI stays stuck in narrow support roles. With them, it can move into lending, advice, payments, and automated execution.
That is why the response is more useful than another generic values and ethics based AI policy statement. It identifies where deployment slows, where control could become concentrated, and what has to move together if the UK wants AI to scale significantly inside financial services.
Canada is also building its next AI strategy. The federal government launched an AI Strategy Task Force in September 2025 as part of a 30 day national sprint, and later said it heard from more than 11,000 Canadians and 28 task force members. The Canadian process is broad. It is focused on national AI leadership, trust, safety, adoption, and public interest.
That broad approach is already raising execution questions. NCFA covered this earlier in its analysis of Canada’s AI strategy and capital flight risk, which argued that deployment, investment, and commercialization need clearer direction.
The UK industry response to the Mills Review is more targeted. It focuses on what is blocking AI deployment inside financial services today. Open Finance, Digital ID, payment access, wallets, third party model assurance, and rulebook friction sit at the center of that response.
Canada is still discussing the national direction of AI while UK fintech industry is already laying out what has to change for AI to work inside live financial workflows. The lesson for Canada is straightforward. AI policy cannot move on its own. Open Finance, Digital ID, wallet policy, payments modernization, and data access frameworks need to move with it or adoption in regulated finance will stay limited.
There is also a market structure lesson. If agent led payments grow, whoever controls the interface between the agent, the wallet, and the payment rail can control distribution. Policymakers who want competition and innovation to hold need to keep that layer open.
The industry response to the Mills Review is not just a call for clearer AI rules. It argues that the next barrier sits outside the model. Data access, identity, payments, and regulatory clarity now decide whether AI in finance stays at the support layer or moves into execution. The firms and jurisdictions that solve those bottlenecks will have the advantage.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 5, 2026 | NCFA Advocacy | Data Governance
Sent by email:
Dear Minister
Power of Data
We (the undersigned – data driven tech and policy experts) very much support the letter of 4 Feb 2026 to you from CCPA – https://www.policyalternatives.ca/news-research/open-letter-to-the-honourable-melanie-joly-minister-responsible-for-statistics-canada/.
We add to that letter the following points:
1. At a time when we need more data, not less, to support evidence-based decision making and community engagement in Canada, the staffing and other cuts already started at StatsCan are misguided. Even if the cuts will “have a ‘low’ or ‘limited’ impact on existing service levels” (a position which is contestable), we echo concerns about the long-term impact on data collection, statistical reliability, and public trust in government institutions.
We ask StatsCan to outline how core programs, release schedules, and quality standards will be maintained. How do we reconcile the cuts with the Digital Research Infrastructure Strategy - https://ised-isde.canada.ca/site/ised/en/programs-and-initiatives/digital-research-infrastructure? Clarifying how “modernization” will offset reductions would strengthen confidence in the transition.
2. Our need for data is magnified by the attacks on data collection in the US, keeping in mind that in the past we have relied on much of that data. The attacks show how quickly statistical capacity can erode and how difficult it is to rebuild.
3. StatsCan plays an important coordinating role in maintaining statistical standards. Although StatsCan is not necessarily the body that should be collecting all the data we need in Canada, we suggest that StatsCan should be the body to oversee an inventory of what Canada does collect (or should be collecting) and to consult on and publish best practices for collection and governance. However, the cuts will clearly constrain an expanded governance role for StatsCan for the foreseeable future.
To provide some examples of data that is sorely needed:
(a) commercialization from Canadian universities, along the lines of the UKRI spinout registry (https://www.ukri.org/news/world-leading-register-of-uk-university-spin-outs-published); *
(b) data on emerging tech commercialization for defence (https://www.nato-pa.int/document/2024-dual-use-technologies-report-baldwin-051-esc and https://www.cigionline.org/publications/intellectual-property-is-economic-and-national-security/); and
(c) data on the outcomes of research spending.
4. Under the World Bank’s Statistical Performance Indicators, Canada’s statistical system ranks highly – https://www.worldbank.org/en/programs/statistical-performance-indicators. While we do not doubt that reform of StatsCan is needed in an increasingly tech-driven economy, wholesale cuts are not the way to do it. Expertise will be lost, collaborative connections across organizations will be lost, mistakes will be made, there will be loss of morale, and direct costs of “redundancy” will be high, when strong statistical capacity is even more essential to support productivity and competitiveness.
5. The timing could not be worse. We are facing enormous challenges, and Canada’s need for reliable data is increasing as the economy evolves. To provide but one example, Canada is increasing defence spending under a new defence industrial strategy and engaging in “nation-building” projects. As noted in the Institute for Research in Public Policy report (https://irpp.org/research-studies/how-industrial-policy-can-strengthen-canada/), these projects must be “accompanied by rigorous evaluation and good governance practices” which can only be effective when Canadian institutions, including StatsCan, collect high quality data and use it to connect action to outcomes.
6. Rebuild or shred? (‘The Doom Loop’ and the future of the global order – https://www.youtube.com/watch?v=6ULm87aidxM). This is a moment for careful planning to ensure institutional capacity is preserved and to plan for rebuilding, not shredding.
Respectfully
Signed
Kyle Briggs - https://www.linkedin.com/in/kyle-briggs/
David Durand – https://www.linkedin.com/in/daviddurandavocat/
Craig Asano, CEO National Crowdfunding & Fintech Assn of Canada - https://ncfacanada.org/
Robin Ford, Robin Ford Consulting - https://www.linkedin.com/in/robinericaford/
Peter Morand, Past President of the Natural Sciences and Engineering Research Council of Canada (NSERC)
Patrick Leblond, CN-Paul M. Tellier Chair on Business and Public Policy, University of Ottawa
José Carlos Marques, Associate Professor, Telfer School of Management, University of Ottawa
* While Canada invests billions in research, we translate very little of the value created into long-term economic and social benefit for Canadians. StatsCan recently attempted to survey Canadian universities on their commercialization activities but was unsuccessful. StatsCan removed the report from the website following complaints that the data was incomplete.
In contrast, the UK recently created a “spin-out register” of all startups commercializing IP created during publicly funded research (https://www.ukri.org/blog/university-spin-out-register-a-step-change-in-insights-for-all/). This register is already providing valuable insights that are helping UK policy makers make better funding decisions.
Canada’s world-class research institutions could contribute far more to Canada’s economy and economic security (https://www.cigionline.org/publications/intellectual-property-is-economic-and-national-security/), but without high-quality data, we struggle to identify and fix the problems.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 23, 2026 | NCFA Market Activity | DAOs
On February 22 2026, Jupiter DAO closes the Net Zero Emissions option vote, moving JUP toward a supply tightening direction and a buyback first treasury posture. On chain reporting shows about 75% support for the Net Zero Emissions option and states the vote concluded at 7:00 PM ET. During the voting window, on chain analysis reports more than 24.5k votes recorded within the first 48 hours, with more than 13k individual voters backing the Proceed with Jupuary option by raw voter count, while the Net Zero Emissions option leads by voting weight at more than 73.9% during that same early period, on a voting distribution analysis that breaks down wallet counts and voting weight.
The proposal says net new emissions move from about 1.2B JUP to effectively zero, if the DAO approves the package. The proposal also states it postpones Jupuary and returns 700M tokens to the Community Cold Multisig, and it states Jupiter routes 50% of on chain revenues to open market buybacks. Jupiter already burns 3B tokens and it states founders lock tokens, including a founder lock to 2030.
Legacy allocations shape why the DAO focuses on offsets. On chain analysis reports Mercurial stakeholders receive 5% of total supply or 350m tokens, with about 182m vested by February 2026 and 168m remaining to unlock, also on the voting distribution analysis that quantifies the Mercurial allocation and vesting status.
Maker uses surplus auctions where the system auctions surplus Dai for MKR and then burns the MKR received from the winning bid, which contracts MKR supply, as described in Maker Protocol documentation on the Flapper surplus auction mechanism.
Aave documentation states the Aave DAO operates a buyback program funded by protocol revenue with a $50 million annual budget and weekly purchases that range from $250,000 to $1.75 million, with tokens sent to the DAO Ecosystem Reserve rather than burned, on Aave protocol documentation describing the buyback program budget and execution.
The proposal turns token governance into capital policy that stakeholders can measure. It targets a defined dilution outcome by moving net new emissions from about 1.2B JUP to effectively zero, and it pairs that supply stance with a stated rule that routes 50% of on chain revenues to buybacks. That combination gives the market a simple scoreboard, emissions near zero plus ongoing buy pressure funded by revenue, not inflation.
Early vote analysis shows more than 24.5k votes within 48 hours and it shows a divergence where the Jupuary option leads by raw voter count while Net Zero Emissions leads by voting weight. Token weighted voting aligns outcomes with economic exposure, but it can widen the gap between how many people show up and who decides. Fintech builders can reduce that gap with delegation tooling, transparent quorum logic, and reporting practices that make governance outcomes feel earned.
Offsets move sell pressure from the open market to treasury management. The proposal describes a treasury approach that aims to neutralize known future sell flows tied to vesting and distribution decisions, which creates a new execution test, the treasury must manage price, timing, and credibility in public. That's the same category of operational accountability that capital markets packaging requires.
Canada adds a practical lens because Canadian fintechs increasingly package products for institutional distribution where buyers demand explicit mechanics and predictable governance. Ledn’s Bitcoin backed ABS deal entering institutional markets shows how an institutional wrapper forces defined rules and clear investor expectations. Tokenized finance teams can apply that same discipline to emissions rules, treasury authority, and public reporting so partners can underwrite the model rather than debate it.
If a token stops emitting, who pays for growth and liquidity next, users through fees, builders through treasury, or the market through higher risk premiums?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Policy Consultation | February 11, 2026
On February 5, 2026, Innovation Science and Economic Development Canada (ISED) released the official Engagements on Canada’s Next AI Strategy Summary of Inputs. The report summarizes a 30 day consultation that ran from October 1 to 31, 2025 and confirms that 11,300 participants submitted 64,600 responses across 26 policy questions about Canada’s next AI strategy.
The consultation addressed the full AI policy landscape, including research and talent, adoption across industry and government, education and skills, infrastructure resilience, national security, environmental sustainability, Indigenous data sovereignty and inclusion. The process ran under The Honourable Evan Solomon, Minister of Artificial Intelligence and Digital Innovation, supported by a National AI Strategy Task Force composed of startup operators, investors, researchers and civil society leaders.
This article focuses on what matters most for fintech founders and investors, where the strongest inputs from the consultation relate to capital formation, procurement design, intellectual property retention and domestic scaling incentives.
The consultation drew wide participation. 83% submitted as individuals. 17% responded on behalf of organizations, and reflected national engagement across technology, finance, academia, professional services and public institutions.
52% identified as interested Canadians. 19% came from business. 13% represented academia or research. The rest included government, associations and other sectors.
Ontario accounted for 39% of responses. British Columbia 20.6%. Alberta 7.8%. Québec 7.6%.
Across submissions, one theme stood out. Canada produces AI research. It struggles to anchor AI companies at scale.
Respondents called for sovereign capital vehicles, modernization of SR&ED and IRAP, and stronger intellectual property retention frameworks. Intellectual property retention refers to keeping ownership of core technology, patents and data assets inside Canada rather than transferring them through early acquisition or foreign incorporation. Stakeholders expressed a preference for patient domestic capital tied to retention conditions, not simply additional grants. That implies potential co-investment models, domestic head office commitments and scaling tools designed to prevent early exits or foreign acquisition.
Canada ranks among global leaders in AI research output. Yet growth stage capital is still significantly thinner than in the United States. In 2025, Canadian VC firms raised just over $2.1B, with fundraising concentrating as the five largest Canadian venture funds captured 83% of all capital raised while emerging managers raised $249M. That level of concentration narrows the number of scaled domestic capital sources available to support long runway AI and fintech growth.
When companies reach scale, many incorporate abroad or raise major rounds outside Canadian markets. Capital migration reduces ownership, long term tax capacity and domestic control over strategic assets. This consultation reflects recognition that Canada’s scaling architecture requires structural reform.
For fintech founders following new AI minister prioritizes growth over rules, this reinforces the need for commercialization outcomes and ownership durability rather than additional regulatory layering.
Respondents pushed for standardized procurement playbooks and real pathways from pilot to deployment. Suggestions were for coordinated procurement models that create anchor customers at scale.
Predictable domestic revenue reduces investor risk perception and strengthens valuations. It also strengthens Canadian firms’ credibility when competing internationally. Procurement design therefore influences capital formation and competitive positioning.
This matters most in regulated sectors. When government adoption aligns with frameworks such as the CIRO digital asset custody framework, compliance becomes a strategic advantage rather than a cost centre. Procurement validation can reinforce regulatory credibility and accelerate scaling.
Participants identified gaps in domestic compute capacity and reliance on foreign cloud providers. Calls for Canadian controlled infrastructure go beyond just hardware investment. They imply potential changes to data residency expectations, cloud dependency exposure and compliance thresholds.
Sovereign compute investment could open infrastructure financing opportunities while raising entry costs for firms dependent on foreign controlled platforms. Infrastructure choices influence market structure.
Submissions supported proportionate, risk tiered regulatory frameworks, independent audits and clearer liability standards. Respondents generally favoured governance models where obligations scale with actual risk exposure rather than one size fits all rules.
Regulatory preference was for clarity, predictability and alignment between risk level and compliance burden. High impact AI applications would face stronger safeguards, while lower risk use cases would not carry unnecessary constraints.
If thresholds are calibrated carefully and compliance pathways are clear, early stage firms gain certainty and investors price regulatory exposure more confidently. If risk categories are broad or implementation complex, governance costs rise and time to market slows.
The strategic issue is how regulatory architecture affects scaling speed, capital formation and Canada’s cost competitiveness relative to larger markets. Governance design influences who scales, who consolidates and who exits.
The consultation closed on October 31, 2025. The Engagement on Canada's Next AI Strategy summary report states that the inputs will inform drafting of Canada’s 2026 AI strategy, which the federal government plans to release later this year.
The report doesn't however specify any fiscal commitments or program design details. Those decisions will appear, if at all, in the final strategy document and subsequent budget measures.
From a market perspective, founders and investors should watch for concrete triggers for a sovereign capital vehicle with defined funding, commercialization linked SR&ED reform, procurement commitments beyond pilot programs, budget allocations for domestic compute infrastructure, and enforceable intellectual property safeguards.
If those elements appear with timelines and capital attached, they strengthen Canada's domestic scaling environment. If not, capital migration and entrepreneur drain will likely persist. The final strategy with design and implementation choices will be known this year.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 4, 2026 | NCFA Expert Intelligence | AI Risk and Governance
On February 3 2026, Dentons published a Voice from the Market North American Legal AI report following the firm’s inaugural Legal AI Summit. The report captures data insights from legal, business, and operations leaders across sectors about how organizations are handling real world AI deployment, specifically where AI adoption is creating legal and governance risk before regulators provide clear framework.
The findings matter for fintech founders and operators because legal teams are often the first to see where risk accumulates, such as in contracts, vendor relationships, employee use, and product liability, long before the market or regulators respond.
Most organizations in the survey reported they are designing their own AI governance frameworks because universal regulations do not exist yet. That gap puts legal risk in the critical path for AI use inside financial products and services.
“We want to cover the basics, but we don’t want to stymie innovation or scare people away with too many ‘do nots.’”
This comment above is from a survey participant highlighting the tension leaders face: Smart governance is needed, but overly prescriptive rules can impede experimentation and execution. So it's a real operational conflict that stakeholders must resolve long before policy catches up.
The governance gaps in the report align with real risks fintechs already encounter:
Many fintechs are building AI capability faster than they are formalizing guardrails, which can expose firms to legal, operational, and compliance risk across functions where AI is integrated in workflows. Whether that's in credit decisions, document review, marketing, fraud monitoring, or customer support.
It also intersects with other areas NCFA has covered. For example, recent regulatory signals from the CSA–CIRO joint finfluencer guidance and the rise of stablecoin policy frameworks both show that Canada’s regulatory perimeter is tightening around behaviour and risk, not just product categories.
If legal risk surfaces first in AI contracts, vendor relationships, and internal use, where should fintechs build their earliest governance guardrails: in contracts, in internal policy, or in product design?
Regulation typically always lags innovation. Legal and governance frameworks are being created inside enterprises today because no universal rulebook exists. Fintech innovators and operators who anticipate these gaps and embed guardrails early will be better positioned to scale responsibly and avoid costly legal exposure down the road.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
