





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 28, 2026 | NCFA Market Activity + Insight | Capital Markets And Market Infrastructure, Risk Compliance And Regtech, Regulation And Policy, Wealthtech Investing And Trading
On August 28, 2026, the Commodity Futures Trading Commission penalized Gabriel Perez for prediction market insider trading after finding that he used confidential presidential speeches to trade event contracts for his own benefit. Perez worked as a White House technical adviser and teleprompter operator, which gave him access to prepared remarks before President Donald Trump delivered them.
Perez generated US$107,539.02 in profits by trading contracts on words and phrases the President would mention. He must return those profits, pay a US$65,000 civil penalty, stop violating the Commodity Exchange Act and stay out of CFTC regulated trading for three years. Perez consented to the settlement without admitting the CFTC's findings or legal conclusions, and the Commission says his cooperation justified a substantial reduction in the civil penalty. The CFTC also thanked KalshiEX for assisting the investigation.
As event contracts attract more volume, products and mainstream distribution, exchanges need to do more than price outcomes and settle trades. They need credible ways to identify when someone may know the answer before everyone else.
A mention market lets traders take a Yes or No position on whether a word, phrase or term will appear during a defined event. Perez opened his Kalshi account on December 8, 2025 and traded markets tied to presidential speeches, including addresses, rallies, policy remarks and the State of the Union.
The CFTC order says Perez generally saw prepared remarks about an hour before the President spoke. He bought Yes contracts when the target word appeared in the speech and No contracts when it did not. On one occasion, he changed his position after watching the President skip part of the prepared text.
Perez traded across 14 presidential mention markets and made money on 39 of 43 contracts. He was not making a better forecast than other traders. He had already seen the prepared remarks and knew whether many of the words being traded were present.
Traditional financial markets already deal with executives, advisers and employees who may hold valuable information before investors receive it. Event contracts can create a much wider group of people with direct knowledge of an outcome. A political speech can involve writers, production staff, government employees and technical crews, while sports, entertainment and corporate events can involve players, coaches, producers, employees, advisers or others close to the result.
That risk was visible before federal enforcement arrived. Kalshi's earlier insider trading cases included a MrBeast editor and a California political candidate, and the exchange said it had opened roughly 200 investigations or probes. Those cases showed that integrity work was already becoming part of running an event market. The Perez action is more consequential because the CFTC is now applying federal commodities law directly to misuse of confidential information in prediction market contracts.
The integrity problem can also extend beyond advance knowledge. Some traders may know an outcome early, others may be able to influence it, and some may hold information through a public duty or private relationship. That makes the source of the information as important as the trade itself.
The CFTC order and what the public record shows is that investigators could connect Perez's account, government role, speech access, trading times and profits. For prediction markets, knowing who is behind an account matters as much as spotting an unusual trade.
Traditional surveillance remains important. Exchanges can look for unusual profits, concentrated positions, repeated success, trading immediately before an event and activity that doesn't fit a customer's normal behaviour. Prediction markets add another requirement because suspicious trading may only make sense once the account is connected to a job, relationship or source of access outside financial markets.
A trader repeatedly winning presidential speech contracts becomes far more interesting if the exchange or regulator also knows that person works on presidential events. The same logic applies to sports personnel trading injury or lineup contracts, employees trading corporate outcomes or production staff trading entertainment events.
Exchanges need to know who is trading, what access they may have to the event and whether their trading pattern fits that access. Reliable customer identity, account history and information about relevant jobs or relationships can help investigators decide whether an unusual trade deserves a closer look. Surveillance teams need tools that can connect trading patterns with occupations, relationships and event access. Case management, alert review and auditable investigation records become more important as the number of contracts and traders grows.
This boosts the commercial case for regulated event contract infrastructure. Market surveillance, identity controls, outcome verification, compliance workflows, investigation tools and regulator reporting are becoming part of what platforms need to operate credible markets, alongside matching, pricing and settlement.
Different contracts also require different surveillance assumptions. An inflation contract settles on a formal public release. A presidential mention contract may depend on a speech seen by staff shortly before delivery. A sports contract can depend on injury or lineup information known to a relatively large group before the public learns it. Exchanges need to understand how each event is produced, who may know the answer early and who can influence the result before they can decide what suspicious trading looks like.
Prediction markets are reaching customers through larger financial platforms, which brings more liquidity but also more accounts and more activity to monitor. Recent CSA and CIRO guidance on prediction markets keeps sports and entertainment event contracts outside Canada's securities dealer channel, while Wealthsimple Investments and Interactive Brokers Canada can offer a narrower set of economic, environmental and financial contracts under CIRO conditions.
The CFTC case also shows that regulators are prepared to use existing commodities rules when confidential information is abused. Exchanges and distributors therefore need to spot suspicious activity early, connect it to useful account information, investigate it and keep records that can support enforcement.
That creates a practical market for surveillance, identity, behavioural analytics and case management tools. Prediction markets have already proved they can attract products, liquidity and mainstream distribution, but can market integrity keep up.
Can prediction markets scale faster than their ability to detect who knows the outcome before everyone else?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
August 26, 2026 | NCFA Insight | Regulation And Policy, Artificial Intelligence And Data, Risk Compliance And Regtech, Competition And Market Structure
On August 26, 2026, U.S. attorneys general announced a settlement with Meta worth up to US$17.1 billion over allegations that Facebook and Instagram were designed to keep children and teens engaged despite risks to their health and well-being. If the court approves the agreement, Meta also has to limit how long minors can use its apps, restrict overnight access and school-hour notifications, strengthen age checks and give families more control over what young users see.
Meta isn't required to admit it did anything wrong under the settlement. It does expect to record an approximately US$10 billion legal expense in Q3 2026. Governments aren't only extracting billions from Meta. They're putting enforceable limits on features that help determine how often young people open Facebook and Instagram, how long they stay and what keeps them scrolling.
Users under 18 will start with a combined two-hour daily limit across Facebook and Instagram. Parents can approve more time, but teens can't simply turn the limit off themselves. Meta also has to block most access from midnight to 6 a.m. by default and mute most notifications during school hours.
The agreement goes deeper. Teens get regular break prompts and more control over personalized feeds, autoplay and visible like counts. Meta also has to strengthen age assurance, identify children under 13, improve parental controls and maintain protections against harmful content and unwanted adult contact.
Recommendations, notifications, autoplay and frictionless consumption help technology companies turn attention into usage, retention and advertising revenue. That's why the settlement is strategically important. A feature can be commercially valuable for years and still become expensive if evidence eventually shows that the same behaviour driving engagement is contributing to harm.
NCFA's Algorithms Go On Trial As AI Scales Across Society unveiled the lawsuits challenging recommendation systems, infinite scroll, autoplay and notifications as deliberate product choices rather than simply arguing about what users post. Those cases have now produced jury findings, large financial awards and operating restrictions. The debate over addictive design is becoming much harder for boards to leave with legal counsel or the product team.
Meta can afford the settlement though. The company earned enough to absorb an approximately US$10 billion quarterly legal charge without changing the financial guidance it gave investors in July. Markets also reacted positively after the settlement was announced, reflecting relief that Meta avoided the potentially larger uncertainty of continuing the federal trial.
That is precisely why boards should study what happened.
Years of complaints, research, lawsuits and internal evidence accumulated around the same basic concern: were Facebook and Instagram using product features to keep children engaged in ways that could harm them? The exposure grew from a difficult policy issue into jury verdicts, court-ordered controls and now one of the largest state settlements ever reached with a single company.
August coverage of the New Mexico Meta ruling showed how quickly the consequences were already expanding. That case combined a US$375 million jury award with a further US$567 million abatement fund and requirements affecting teen usage, notifications, age assurance, adult contact and AI chatbot interactions involving minors.
If management keeps getting signals that a profitable feature may be harming young users and keeps pushing it anyway, the issue eventually belongs with the board. Investors should know when those warnings reach directors, what they’re told and who can decide that the revenue is no longer worth the risk.
Meta also negotiated an unusually strategic feature into the settlement.
Its own disclosure describes an approximately US$18 billion payment structure over ten years. About US$12.7 billion is allocated to participating states regardless of what competitors do. Roughly US$5.3 billion is released only if both TikTok and YouTube adopt specified teen protections and make matching payments.
That gives Meta billions of reasons to bring its competitors along.
Commercially, the logic makes sense given the amount of competition. If Facebook and Instagram restrict teen usage while TikTok and YouTube remain more permissive, users and coveted 'attention' can migrate to competing apps. Meta bears the cost while rivals gain more opportunity to capture the hours, content consumption and advertising inventory Meta gives up.
The terms get tougher if TikTok and YouTube participate. Meta's daily limit falls from two hours across Facebook and Instagram to one hour per app, while its nighttime block expands from midnight to 6 a.m. to 10 p.m. through 7 a.m.
So Meta isn't simply asking competitors to copy its safety policies. It is trying to prevent child-safety rules from becoming a competitive handicap carried mainly by Facebook and Instagram.
TikTok and YouTube haven't agreed to the framework. Until they do, Meta could still end up operating under restrictions its largest rivals don't share.
Concern about how digital products affect children has been building for years. In 2023, NCFA analyzed Canadian research into children's privacy and consent that called for stronger safeguards to be built into digital products from the start. Children don't assess consent, persuasive design or data collection the way adults do, yet personalization and recommendation systems routinely influence what they watch, read and do next.
Meta's settlement gives those concerns a much larger financial consequence. Governments are no longer relying only on warnings or disclosure requirements. They are specifying age checks, usage limits, notification controls, parental oversight and independent monitoring.
Once those requirements appear in a multibillion-dollar agreement, other platforms know what regulators may ask for next. The settlement doesn't create legal precedent, but it gives attorneys general a detailed set of measures they can use in future negotiations and enforcement.
AI companions and conversational assistants can respond personally, remember context and keep conversations going. Research into youth use of AI reported that 72% of teens had tried AI companions and examined evidence of young people using generative AI for emotional and mental health support.
AI can change the type of exposure a child experiences. A recommendation feed influences what a young person sees next. An AI system can respond directly, adapt to the conversation and encourage the user to keep engaging.
For companies serving children or vulnerable users, it's even more important to know what the system is encouraging, where harmful patterns are appearing and who can change the product when the interaction becomes uncomfortable.
The same principle can be seen in fintech where younger customers use digital wallets, investing apps, financial education tools and AI assistants. Meta's settlement rules don't apply to those products. The relevant lesson is that companies need to understand how their own systems influence behaviour before a regulator or court does it for them.
Meta's US$17.1 billion settlement shows how expensive the problem can become when concerns about engagement, harm and product design build for years without a convincing response.
When a company knows a profitable engagement feature may be harming young users, who should have the authority to decide when growth has gone too far?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 21, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Regulation And Policy, Competition And Market Structure
On August 18, 2026, the Canadian Securities Administrators published its 2025–2026 Year in Review. One capital formation result stands out. After regulators increased the limits for the Listed Issuer Financing Exemption, hundreds of listed issuers used it to raise almost $4 billion in the first year, at eight times the pace under the original limits.
That is unusually useful regulatory evidence. It doesn't prove the higher limits caused every additional financing, since issuer demand and market conditions also affect activity. But the market used the exemption far more heavily after regulators made it more practical. The result also strengthens a larger question NCFA recently explored around whether Canada can turn access into productive participation rather than stopping at permission on paper.
NCFA reviewed the expanded LIFE exemption when the CSA initially increased how much eligible listed companies could raise without preparing a prospectus for each financing.
The new usage data take that reform beyond policy design. Companies had a less burdensome financing route available and hundreds chose to use it.
The LIFE exemption gives eligible reporting issuers a more efficient way to raise public capital while retaining specified disclosure and investor protections. This matters most when the fixed costs of a conventional financing become large relative to the amount a smaller company needs to raise. A financing route can exist legally and still see limited use if its cost, complexity or timing makes the economics unattractive.
The first year under the higher limits provides evidence that those economics are essential. Hundreds of issuers used LIFE and almost $4 billion was raised, compared with a much lower pace under the previous limits. The important result is not simply that Canada permitted more financing. Issuers actually used the additional room.
That gives regulators a stronger basis for the next round of evaluation. Which companies used LIFE, how large were the financings, what did it cost them to raise the money, how did investors fare and how much activity would have occurred through another route anyway? Those questions can help distinguish a rule that merely looks simpler from one that materially improves capital formation.
The CSA is reducing different forms of friction elsewhere in the market. Eligible venture issuers with less than $10 million in annual revenue can voluntarily file financial results semiannually rather than quarterly under an interim regime. Regulators can use what they learn from that regime when considering permanent rules, making issuer cost and actual market use part of the feedback process.
The proposed self certified investor exemption approaches participation from the investor side. People who satisfy specified education or experience criteria could invest even if they don't meet the financial thresholds for accredited investors, with investments capped at $50,000 per calendar year across multiple businesses. The proposal would give Canadian issuers another potential source of private capital while widening access for investors regulators believe have enough knowledge or experience to understand the risks.
Accredited investor rules largely use wealth and income as proxies for the ability to bear risk, while the proposed exemption would also recognize relevant knowledge or experience. If adopted, its value should eventually be judged by more than the number of investors who become legally eligible. Issuer uptake, investment activity, losses, complaints and other investor outcomes would show whether wider access produces a useful market.
The same focus on actual market use is reaching new securities infrastructure. NCFA covered the launch of Project Tokenization when the CSA opened stakeholder engagement through the Collaboratory and identified a possible route toward live testing. The CSA now says the project has engaged more than 240 organizations spanning issuers, fintech companies, custodians, marketplaces, clearing agencies, professional firms and other participants.
The CSA Collaboratory gives novel products and market structures a way to engage regulators before launch and can support controlled testing where appropriate. That's important because tokenized securities depend on more than an issuer receiving permission to create a digital asset. Custody, ownership records, trading, settlement, compliance and investor protection all have to work well enough for a product to operate economically.
Tokenization is a more complex extension of the LIFE lesson. LIFE shows what happened after one capital raising constraint was relaxed. The U.S. is also reconsidering how securities rules apply to crypto asset capital raising, including proposals that could expand how much eligible issuers can raise under lighter offering requirements. In Canada, Project Tokenization can show whether regulators and market participants can identify which requirements are essential, which need adapting and which create enough cost or uncertainty to prevent otherwise viable infrastructure from being built here.
Ontario's commitment to join Canada's securities passport system tackles another longstanding source of friction. Our Ontario securities passport story traced how the province moved from pursuing a national regulator to joining the existing passport model. The CSA says Ontario's participation is intended to strengthen national harmonization, remove interprovincial barriers and reduce regulatory burden for companies doing business across Canada.
For firms operating nationally, duplicated provincial processes can become an operating cost even when the underlying securities requirements are similar. The useful evidence after Ontario joins will be whether companies encounter less duplication, lower compliance costs and easier national market access. Regulatory reform becomes much more informative when policymakers can compare what they changed with what companies and investors actually did afterward.
Lower friction does not mean removing protections wherever market participants find them expensive. The CSA issued 763 investor alerts, cautions and warnings during the year, more than 85% involving crypto assets, and facilitated the deactivation of 11,728 malicious investment websites representing 19,860 URLs.
Some rules clearly protect investors and market integrity. Others may now be costing the market more than they protect.
LIFE gives Canada a rare piece of evidence about that balance. Almost $4 billion and an eightfold increase in financing activity give regulators a reason to look for other places where better calibrated rules could produce more usable markets without sacrificing the protections that keep those markets credible.
If higher LIFE limits were followed by an eightfold increase in capital raised through the exemption, which other securities rules should Canada now test against actual issuer and investor behaviour?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 20, 2026 | NCFA Insight | Artificial Intelligence And Data, Public Sector Policy And Industrial Strategy
On August 20, 2026, Bank of Canada research on AI and Canadian hiring shows that people coming from occupations with greater artificial intelligence exposure are having a harder time finding work than people coming from less exposed occupations. During 2015 to 2019, the estimated job finding rate at the fully exposed end of the Bank's model was 2.2 percentage points lower than at the unexposed end. In 2025, it was 13.9 points lower. The comparable difference in job separation rates barely changed.
The Bank isn't saying AI alone caused the gap. The pandemic, immigration, trade changes and weaker labour market conditions also affected hiring. What stands out is where the difference appears. People in more exposed occupations aren't leaving or losing jobs much faster, but those trying to find work are having more difficulty getting hired.
The occupations near the top of the Bank's exposure ranking are heavy on information work. Data entry clerks, receptionists, payroll administrators and accounting clerks, banking and insurance clerks, records management staff, customer service representatives and office support workers all rank highly. Jobs that depend more on physical work, specialized human skills or judgment generally rank lower.
The Bank estimates the relationship using Statistics Canada Labour Force Survey data and occupation level AI exposure scores. No workers in the data sit at exactly 0% or 100% exposure, so those endpoints are estimates rather than two observed groups of workers. The Bank describes the comparison as an upper bound.
Statistics Canada research on AI and employment provides an important check. Employment generally grew from November 2022 through December 2025 across occupations with different levels of potential AI exposure. Vacancies in highly exposed occupations where AI may replace more tasks also fell at a similar rate to vacancies in occupations with lower exposure.
Those findings can coexist. Overall employment can hold up while people trying to enter or reenter some occupations take longer to get hired. The Bank also finds that younger workers are more concentrated than older workers in several occupations with moderate or high AI exposure. That puts more attention on entry points into the labour market, not just on whether established workers are being laid off.
A company doesn't need a large round of layoffs to use less labour. It can replace fewer people who leave, open fewer junior positions or use the same team to handle more work. The Bank's August data show why layoff announcements alone are a poor measure of the employment effect.
A separate Bank of Canada survey of Canadian firms points in the same direction. Firms expected AI to have little effect on employment over the following year but modest net negative effects over three years. They expected the impact to build over time rather than arrive as an immediate employment shock.
New Bank of Canada evidence on business AI adoption adds another layer. More than two-thirds of surveyed business leaders said they personally use AI in a typical work week, but only 8% of businesses reported significant AI use in core operations. Over the next three years, 23% expect AI to reduce employment while 11% expect a positive employment effect. That suggests hiring effects could emerge before broad operational transformation is complete, leaving a sizeable gap between using AI tools and redesigning businesses around them.
If AI lets companies produce more with existing teams, labour demand can weaken first through vacancies, replacement hiring and junior recruitment. If those measures deteriorate in the occupations where AI use is rising fastest, the case for an AI related employment effect gets stronger. If they recover with the rest of the labour market, it gets weaker.
The Bank of Canada July AI employment paper approached the issue through an economic model rather than observed labour market outcomes. It separates AI that helps workers produce more from automation that transfers tasks away from workers. Both reduce labour demand in the model, with the larger effect coming when machines take over tasks. The August research adds observed Canadian labour data without proving that AI caused the hiring gap.
Finance is a useful place to watch because AI use is already high and several financial jobs rank among the Bank's more exposed occupations. Statistics Canada found that 40.4% of finance and insurance businesses used AI to produce goods or deliver services during the previous 12 months, more than twice the 19.2% Canadian business average.
The Bank's 2026 Financial System Survey shows a similar pattern among major financial organizations. Nearly all 54 respondents reported using AI, although most still described adoption as limited or moderate. They generally use it to complete existing tasks faster while keeping people responsible for critical decisions carrying financial, legal or reputational consequences.
Financial firms also have an implementation problem. In the Bank survey, 58% of respondents reported difficulty integrating AI into existing systems and workflows. Another 56% cited weak AI literacy among current employees or difficulty hiring and retaining people with specific AI expertise.
Governed financial AI workflows show why both things can happen at once. Software can collect information, compare records, prepare research, identify accounting breaks and assemble know your customer files before a person reviews the work or makes the decision. A firm may need less manual work around a process while placing more value on employees who understand the business well enough to challenge the output.
That becomes especially important for junior roles. Employees have traditionally learned finance by preparing files, reconciling records, reviewing documents, gathering evidence and completing first pass analysis before taking responsibility for harder decisions. AI's hidden costs in replacing junior workers include weakening some of those early career training routes. If AI removes more of that routine work, firms may eventually need fewer junior hires while still competing for experienced analysts, operators, compliance professionals and risk managers.
Current evidence doesn't show that this has happened across Canadian finance. It does show high AI use, exposed information work and shortages of people with the skills to implement and oversee the technology. For founders, financial institutions and investors, the employment question is therefore bigger than how many jobs AI eliminates. It's also about which jobs companies stop adding, which skills become more valuable and how firms build experienced people when some of the work that trained them is automated.
If AI reduces the number of people companies need to hire before it reduces existing headcount, how quickly will Canada's employment data show the change?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
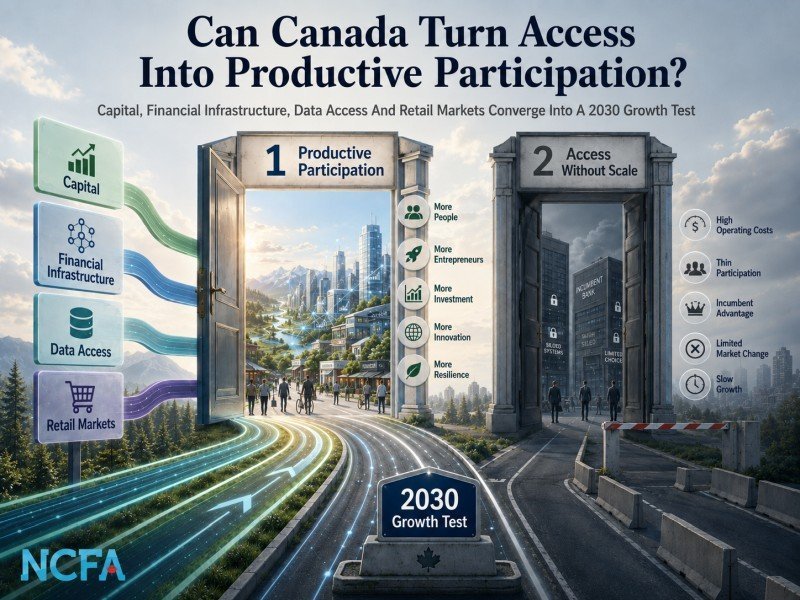
On August 21, 2026, Canada's founder drain returned to the national debate with a harder number attached to it. The Dominion List, a curated catalogue rather than a census, now tracks 517 U.S.-based companies with a Canadian-linked founder. Together they have raised roughly US$414 billion. About 88% of the founder links include education at a Canadian university, and 56% of the companies are headquartered in San Francisco.
The pace in the list also accelerated during the AI boom. Jesse Rodgers' Barn Ventures analysis counts 60 newly founded U.S. companies with Canadian-linked founders in 2023, 93 in 2024 and 87 in 2025, compared with roughly 20 to 30 a year from 2016 through 2022. The dataset is curated and recent companies may be easier to capture, so it should not be treated as a population estimate. The direction is still difficult to ignore.
Canada clearly produces ambitious builders. The strategic question is whether enough of them can find the capital, customers, infrastructure, investors and operating density needed to build more of the resulting value here. That makes founder retention part of a wider participation problem, not a standalone brain-drain story.
Canadian universities are producing founders at global scale
The Dominion List links 88% of its founder records to Canadian universities. Waterloo alone accounts for 216 founders across 180 U.S.-based companies in the current dataset, while Toronto, McGill, UBC and Queen's are also major feeders.
The value capture concentrates somewhere else
The 517 companies in the list have raised about US$414 billion. Fifty-six are valued at US$1 billion or more, 19 are public and 59 have been acquired. San Francisco alone hosts 287 of them.
Canada's problem is not producing ambitious people. It is converting more of that talent into companies, jobs, ownership and follow-on investment that compound inside the Canadian economy.
U.S. founder programs start earlier and remove more friction
Barn Ventures maps programs that reach students before graduation, then layer in early capital, founder communities, recruiting, immigration support and dense investor networks. The argument is that the U.S. offer is a system rather than one accelerator or one cheque.
Canada's response cannot be one more accelerator
Keeping more founders does not mean preventing mobility or copying Silicon Valley. It means giving more builders credible reasons to start, finance, hire and scale from Canada before the strongest networks and ownership structures form elsewhere.
Capital matters, but so do density, access, customers, infrastructure and the speed of getting from talent to a company with traction. Founder retention makes the wider participation thesis concrete because Canada can create the input and still lose much of the compounding.
The Forum looks across the financing lifecycle
NCFA's review of the SEC Small Business Forum shows why the process is useful for Canada. The 2026 Forum program again moved from early-stage financing to growth capital and smaller public markets.
The same frictions keep returning in new forms
Finders, investor eligibility, offering limits, fund structures, secondary liquidity and small-public-company economics remain active issues because one reform can solve one bottleneck while exposing another.
The transferable lesson is not a U.S. securities rule. It is the habit of bringing market participants back into the process and testing whether a framework is producing the market it was intended to create.
Canada already has detailed market evidence
CVCA tracks venture and private equity, while NACO tracks angel investing. Regulators and departments publish market studies, consultations and program data. Canada does not lack information about every part of the financing system.
Canada is also actively intervening
The federal government is preparing another C$1 billion venture and growth capital program. The Competition Bureau is studying SME financing. Payments, data access and retail private markets are also being redesigned.
Canada already has consultations, programs and market data. The harder test is whether each reform produces enough real participation to change who can compete, invest and scale.
Institutional venture capital is getting a larger engine
The Venture and Growth Capital Catalyst Initiative is designed to attract more private and institutional capital into Canadian venture funds, strengthen fund managers and support high-growth companies from pre-seed through growth.
SME financing is being tested against a broader business population
NCFA's SME financing competition review examines lender entry, expansion, switching friction and the market position of alternative finance providers. The Competition Bureau market study is the primary verification source.
Growth VCCI can deepen capital for companies that fit venture mandates. It does not automatically finance every viable manufacturer, service company or local employer whose growth profile, asset base or financing need sits outside institutional venture economics.
Financial data is moving toward regulated access
NCFA's Canada Open Banking Rules intelligence tracks accreditation, liability, data scope, security and technical standards as consumer-driven banking moves toward operation. Finance Canada's proposed regulations provide the primary policy source.
Core payment infrastructure is opening to a wider membership base
PSPs and more credit unions can join Payments Canada, while the Real-Time Rail rules and access are moving toward the planned Q4 2026 launch. Payments Canada remains the primary launch and system source. Wider eligibility gives PSPs and credit unions a clearer route into core payment infrastructure.
Formal access changes who is allowed to participate. Competition changes only when entrants can absorb compliance, technology, integration and operating costs and still build products customers want.
Fintechs can gain more control over the customer experience
More direct access to data, payments and settlement can reduce dependence on incumbent-controlled infrastructure and give challengers more control over pricing, product design and service delivery.
Smaller financial institutions can compete through shared capabilities
Credit unions and regional firms may not need to build every payments, AI, compliance, data or digital-asset capability internally if specialized providers can deliver those functions at workable scale.
The payoff is not a longer list of fintech entrants. It is more providers controlling enough of their infrastructure and economics to put sustained pressure on incumbents.
Managed access gives households professional selection
Ontario's long-term asset fund work could give retail investors diversified exposure to venture capital, private equity, private debt, infrastructure and other long-duration assets through professionally managed funds. The OSC LaunchPad notice verifies the project and its retail-access objective.
Direct access gives households the company decision
Equity crowdfunding lets an investor choose an individual company. It can connect businesses with customers, employees and supporters, but it also concentrates risk and usually offers little liquidity.
Managed access can broaden exposure to private-market returns. Direct access can broaden the number of people deciding which companies receive their money. Both can widen participation, but they create different markets.
Canada is building the managed channel for wider retail use
Managed structures can bring diversification, diligence, portfolio construction and product-level controls around valuation and liquidity. They can also preserve professional gatekeeping over where retail capital is deployed.
Canada's direct channel remains comparatively constrained
NI 45-110 allows a Canadian issuer to raise up to C$1.5 million in 12 months. Ordinary investors are generally limited to C$2,500 per offering, or C$10,000 when a registered dealer determines suitability.
If more company value is created while businesses remain private, wider retail access affects more than issuer financing. It influences which households can accept productive risk and participate earlier in private-market returns.
Canadian direct demand can reach the existing ceiling
Blossom, Edison Motors and Gander have used community capital alongside accredited, offering memorandum or other financing. Their raises show direct retail capital can complement professional capital rather than replace it.
International peers provide more room for direct participation
Australia permits eligible issuers to raise A$5 million in 12 months and caps retail investment at A$10,000 per company annually. U.S. Regulation Crowdfunding allows eligible issuers to raise up to US$5 million.
Canada's smaller market does not prove regulation caused weak activity. Issuer quality, investor demand, distribution, awareness, liquidity and platform execution also matter. It does show why market-opening rules should eventually be judged by whether enough issuers, investors and intermediaries can participate economically.
One future produces more viable participants
New payment participants build useful services. Open-banking firms turn permissioned data into products customers adopt. Smaller institutions buy modern capabilities instead of rebuilding them. More businesses find financing that fits their stage and economics.
The other future opens rules without changing market power very much
Accreditation, integration, compliance, distribution and technology remain expensive enough that the largest institutions and professional managers capture most new activity. Formal access widens while competitive intensity changes only at the margin.
The evidence will be practical. Entrants that survive. Products customers use. Capital reaching different kinds of companies. Investors using managed and direct routes. Smaller institutions offering capabilities once reserved for much larger competitors.
Better participation can improve the inputs to productivity
More financing choices, faster settlement, stronger data access and better financial tools can give businesses more capacity to invest, automate, hire, commercialize and serve customers.
Stronger companies can create the next round of participation
Businesses that build revenue, productivity and international reach create more investable opportunities. When more founders build and exit from Canada, employees, angel investors and repeat entrepreneurs can recycle capital, experience and networks into the next generation.
More viable participants can increase competition. Better competition can improve products, distribution and capital allocation. Better tools and financing can support more investment. Stronger companies can create more opportunities for households and institutions to participate again.
The U.S. process expects the friction to change
Market participants return because new rules, market conditions and business models keep changing the problem. A recommendation can be implemented and still leave a new bottleneck elsewhere.
Canada will need the same feedback discipline across more than capital
As payments, data, private markets and financing become more open, policymakers will need to know who entered, who could not, which businesses became sustainable and where access failed to generate enough economic activity.
Canada has spent years opening doors. The next phase is finding out which openings create viable markets. That means judging regulation and public programs by the participation, competition and productive activity they generate while preserving the protections that made wider access possible.
Participation is not a complete explanation for Canada's productivity problem. Management capability, commercialization, industrial structure, R&D, domestic demand, risk appetite and global scale all matter. The value of the thesis is that Canada is now opening enough capital, data, payments and investor channels at the same time to test whether participation becomes a measurable growth mechanism.
Talking Point
Canada already produces globally competitive talent and holds deep pools of capital, technology and institutional capacity. The opportunity between now and 2030 is to connect more of those assets before founders, ownership and future value compound somewhere else. If today's reforms create viable participation rather than permission alone, Canada could end the decade with more competitors, more investable companies and more ways for households and institutions to share in productive growth.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 18, 2026 | NCFA Feature | Regulation And Policy, Digital Assets, Capital Markets And Market Infrastructure

On August 18, 2026, the U.S. Securities and Exchange Commission proposed Regulation Crypto Assets (download 402 page PDF Proposed Regulation Crypto Assets document), a tailored securities framework for certain investment contracts involving crypto assets. The 402-page proposal would create a startup exemption of up to US$5 million over four years, a larger fundraising exemption with US$20 million and US$75 million tiers, crypto-specific disclosures, new SEC forms, secondary-market provisions, state-law preemption and a process for determining when an investment contract has ended.
The scope is narrower than the name might suggest. Regulation Crypto Assets would apply to what the SEC calls a covered investment contract. A crypto asset must be subject to the investment contract, the crypto asset itself must not be a security and no other asset can be subject to that contract.
That builds on the SEC's March 2026 crypto interpretation. The March action addressed when transactions involving a non-security crypto asset can create an investment contract and when that relationship can end. Regulation Crypto Assets would add an operating framework around that lifecycle.
The proposal is significant because it goes beyond creating two new fundraising limits. The SEC is designing rules for how certain crypto investment contracts could be offered, disclosed, distributed and resold, and how the underlying crypto asset could eventually separate from the investment contract.
The proposed Regulation Crypto Assets isn't a comprehensive U.S. crypto rulebook. It doesn't create the general regulatory regime for payment stablecoins, programmable payments, crypto custody, crypto lending, mining or conventional securities that happen to be tokenized. Those activities may fall under other federal or state laws, other regulators or separate SEC work.
Payment stablecoins are a good example. Regulation Crypto Assets says permitted payment stablecoins could be accepted as consideration in a covered offering and would count toward its offering limit. It does not establish the rules for issuing payment stablecoins.
That work is proceeding separately under the federal GENIUS Act. On August 17, one day before the SEC proposal, the U.S. Treasury issued a proposed payment stablecoin rule covering implementation of the separate federal framework for their issuance, offering and sale.
Other crypto activities can intersect with Regulation Crypto Assets without becoming generally regulated by it. The proposed Startup Exemption contemplates certain distributions connected with development and use of a crypto network, including circumstances involving airdrops, staking, governance, gas fees and testing. The legal question remains whether the particular transaction involves a covered investment contract.
The proposal also doesn't create a new legal category for tokenized stocks or bonds. Tokenized conventional securities remain securities. Regulation Crypto Assets instead addresses a narrower case where the crypto asset itself isn't a security but is subject to an investment contract.
It's important for founders, investors, lawyers and trading platforms to know that a crypto asset, an investment contract involving that asset and a tokenized security, can look technologically similar while carrying very different securities-law consequences.
The proposed Startup Exemption could be used for no more than four years after an issuer's initial Form NOR filing. The issuer and its affiliates could conduct covered transactions up to an aggregate US$5 million during that period and couldn't simply restart the four-year clock for the same or a substantially similar crypto asset.
The issuer definition is unusually flexible. The proposal would allow an entity, an individual or a group of individuals or entities to qualify, subject to the other conditions. That accommodates crypto projects that may begin with a development team before they resemble a conventional corporate securities issuer.
The fundraising mechanics are also important. The proposed startup route would permit general solicitation, impose no individual investment limit on retail purchasers and require neither financial statements nor use of a registered intermediary. Covered investment contracts sold through the exemption would not be restricted securities under federal law and would not carry a separate rule-based holding period.
Disclosure doesn't disappear. Before conducting covered transactions, the issuer would file Form NOR on EDGAR and make the disclosures required by Rule 103 publicly available free of charge.
Those disclosures are designed around the investment contract and crypto network. They include offering terms, management and conflicts, the crypto asset, development plans, network or application security, source code where applicable, token economics and allocations, governance, the related crypto ecosystem and material risks. The information must remain publicly available, with material changes addressed under the proposal's update requirements.
Bad-actor disqualifications would apply as well, and issuers would remain subject to federal antifraud and antimanipulation rules. This is a different compliance model, not an absence of securities regulation.
The most revealing comparison is Regulation Crowdfunding. Reg CF also permits up to US$5 million, but over a 12-month period. It requires a registered broker-dealer or funding portal, financial disclosure and investment limits for non-accredited investors, while securities generally face a one-year resale restriction.
The SEC makes that comparison itself. Its economic analysis estimates average Reg CF intermediary fees at approximately 6.6%, with a 6% median, and identifies the absence of mandatory financial statements and an intermediary as potential cost savings under the crypto Startup Exemption.
There is little evidence that current Reg CF rules have produced a large crypto financing market. SEC data identify 42 crypto-related Reg CF offerings by 41 issuers between 2016 and 2024. Reported proceeds totalled approximately US$13.6 million, with an average of US$545,300 among offerings for which proceeds were reported. The SEC cautions that the proceeds total is incomplete and likely represents a lower bound.
The proposal is therefore testing more than a higher ceiling. It asks whether removing particular intermediary, financial reporting, investor and resale frictions would make a public capital route more workable for qualifying crypto projects.
Larger projects could instead use the proposed Fundraising Exemption. Tier 1 would permit up to US$20 million in 12 months. The issuer would have to file Form 1-CRYPTO and couldn't sell covered investment contracts until the SEC qualified the offering statement.
The offering circular would combine the crypto-specific Rule 103 disclosures with financial information about the issuer. Tier 1 financial statements generally wouldn't require an audit, but the issuer would still enter an ongoing reporting regime using annual Form 1-KC, semiannual Form 1-SC and Form 1-UC for specified current events.
Retail investors would also face a restriction that doesn't apply under the Startup Exemption. A non-accredited investor generally couldn't purchase more than 10% of the greater of annual income or net worth. For a non-natural person, the test would use revenue or net assets.
Tier 2 would permit up to US$75 million in 12 months. Like Tier 1, it would require Form 1-CRYPTO, SEC qualification before sales, ongoing reporting and the 10% non-accredited investor limit. The key additional financial requirement is that Tier 2 statements would have to be audited by an independent accountant under the proposed standards.
The larger Fundraising Exemption also comes with a strong U.S. nexus. The issuer would have to be an entity organized under U.S. law, a majority of its executive officers or directors would need to be U.S. citizens or residents, more than half of its assets would need to be in the United States and its business would have to be administered principally there.
Canada appears explicitly in the SEC's request for comment. Question 86 asks whether Canadian issuers, or other foreign issuers, should be permitted to rely on the Fundraising Exemption.
That is more than a passing jurisdictional detail. Regulation A already allows qualifying Canadian issuers, while the proposed Regulation Crypto Assets fundraising route currently does not. Whether the SEC changes that provision could affect how useful the US$20 million and US$75 million routes become for Canadian crypto companies.
The proposal's treatment of secondary transfers may prove almost as important as its fundraising limits. The SEC says existing exemptions can impede the network effects of crypto assets when they restrict who can participate or how quickly securities can be resold.
Both proposed exemptions would therefore allow issuers to sell covered investment contracts that are not restricted securities under federal law. Investors wouldn't face the federal holding periods associated with restricted securities, although contractual restrictions and other applicable laws could still affect a transfer.
That differs from common Regulation D offerings and from Reg CF's first-year resale limits. The SEC's rationale is specific to crypto networks. Wider ownership and use can contribute to how a network operates and how the crypto asset derives value, so distribution restrictions can affect more than investor liquidity.
Rule 500 would address another obstacle by proposing federal preemption of certain state registration and qualification requirements. It would treat purchasers in qualifying Regulation Crypto Assets transactions as qualified purchasers for that purpose and extend the treatment to specified secondary-market transactions.
The preemption isn't unlimited. Secondary-market treatment would depend on the issuer remaining current with the disclosure, filing or reporting requirements attached to the applicable exemption. States would also retain antifraud authority, powers over unlawful broker or dealer conduct, notice filing requirements and applicable fees.
For trading platforms and intermediaries, the proposal introduces an additional status question. They may need to distinguish between the underlying non-security crypto asset, an outstanding covered investment contract involving it and an asset for which that investment-contract relationship has ended.
Rule 400 addresses one of the most distinctive features of the proposal. The SEC's existing securities rules generally deal with financial instruments whose fundamental legal character doesn't change over time. A crypto asset can present a different problem because an investment contract surrounding it may end while the crypto asset continues to exist and circulate.
The proposed safe harbor would apply when the issuer has completed or permanently ceased all essential managerial efforts that it represented or promised under the covered investment contract. The issuer also couldn't be making, or intending to make, new promises to perform those essential managerial efforts.
An issuer seeking to use the safe harbor would file Form TR. The filing would include a certification and an analysis supporting the conclusion that the required managerial efforts have ended.
Meeting those conditions would mean the crypto asset is deemed no longer subject to that investment contract for the relevant definitions of a security under the Securities Act and Exchange Act. That doesn't mean Form TR can convert a security into a non-security simply because an issuer files it. The substantive conditions still have to be satisfied, and the SEC can challenge an issuer's analysis.
Nor does the proposal replace Howey or the March interpretation. The safe harbor creates one defined route for dealing with the end of an investment contract. The SEC acknowledges that a covered investment contract could also cease to exist outside the safe harbor under the applicable securities-law analysis.
That lifecycle helps explain why the proposal is more consequential than a new exemption schedule.
The SEC is contemplating a regulatory sequence in which a project can finance development through an investment contract, distribute the associated crypto asset widely and potentially reach a point where the investment contract itself no longer exists.
Canada has dealt with token offerings for years. Canadian securities regulators issued guidance on cryptocurrency offerings in 2017 and followed with more detailed token offering guidance in 2018. The CSA has made clear that coins or tokens can involve investment contracts and distributions of securities depending on their economic substance and how they are offered.
There have also been Canadian security-token initiatives and exempt-market token offerings. The difference isn't that Canada has avoided token issuance. Canada has generally applied its existing securities laws, prospectus exemptions and registration framework rather than creating a dedicated crypto lifecycle regime comparable to Regulation Crypto Assets. That difference also fits Canada's wider capital formation gap.
Capital formation makes that difference more important. Canada's NI 45-110 startup crowdfunding exemption currently permits an eligible issuer to raise up to C$1.5 million over 12 months. An investor generally can invest up to C$2,500 in an offering, or C$10,000 when a registered dealer determines that the investment is suitable, and the offering must take place through a funding portal.
The Canadian market is also much smaller. FrontFundr reports that it processed C$4.79 million from 4,320 investors under NI 45-110 in 2025 and accounted for 93% of activity under the exemption. Because that 93% figure comes from FrontFundr rather than an official national regulatory dataset, it should be treated as a platform estimate rather than an official Canadian market total.
There is stronger evidence that the C$1.5 million ceiling is becoming binding for some issuers. Edison Motors raised C$1.491 million under NI 45-110 in 2025, roughly 99% of the limit. Blossom Social raised C$1.450 million, approximately 97%.
The more direct U.S. comparison is Regulation Crowdfunding. Reg CF already allows eligible companies to raise up to US$5 million in 12 months, but requires an SEC-registered intermediary, limits investments by non-accredited investors and generally restricts resale for one year. The proposed US$5 million crypto Startup Exemption would use the same headline ceiling with a different compliance model.
The larger crypto Fundraising Exemption is more directly comparable with Regulation A. Existing Reg A already uses US$20 million Tier 1 and US$75 million Tier 2 limits, with additional audit, investor-protection and ongoing-reporting requirements at Tier 2.
Canada is a different comparison. NI 45-110 isn't a crypto-specific equivalent to Regulation Crypto Assets, but it is Canada's nationally harmonized startup crowdfunding route. It remains capped at C$1.5 million over 12 months, with a funding-portal requirement and investor limits of C$2,500 per offering or C$10,000 with suitability advice from a registered dealer.
NCFA has been advocating for a C$5 million or higher issuer cap for years, arguing that the C$1.5 million ceiling can limit the usefulness of the exemption for growing companies. That concern is now easier to test against actual market activity, with some Canadian crowdfunding campaigns reaching close to the current ceiling.
The relevant policy question is therefore wider than whether Canada has an identical crypto exemption. The U.S. already offers Reg CF and Regulation A for different stages of capital raising and is now proposing a separate crypto-specific framework built around fundraising, token distribution, resale and the eventual end of an investment contract.
That matters because Canada's capital formation system already has funding gaps, while some Canadian crowdfunding campaigns are reaching the NI 45-110 ceiling. Regulation Crypto Assets could add another financing and regulatory option to the U.S. market without a directly comparable Canadian crypto-specific route.
The proposed US$75 million Tier 2 also raises a separate competitiveness issue. The SEC is asking whether Canadian issuers should eventually be eligible for the Fundraising Exemption. If they are included, qualifying Canadian crypto companies could gain access to a much larger U.S. pathway. If they remain excluded, access to U.S. capital could become another factor projects consider when deciding where to organize and raise funds.
None of this means Canadian regulators should copy the SEC. It does strengthen the case for examining Canada's startup financing limits, token-offering rules and capital-market pathways together rather than as separate policy files.
For Canada, the challenge is whether existing rules can protect investors while giving legitimate companies enough financing capacity and regulatory flexibility to build here. If the U.S. adds specialized crypto fundraising routes on top of Reg CF and Regulation A, that competitive comparison becomes more difficult to ignore.
If the U.S. adds a dedicated crypto capital-formation and investment-contract lifecycle regime on top of Reg CF and Regulation A, while Canada still relies on existing exemptions and a C$1.5 million startup crowdfunding cap, how long can Canada treat crypto regulation and capital-formation reform as separate policy questions?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 13, 2026 | NCFA Insight | Artificial Intelligence And Data, Competition And Market Structure, Public Sector Policy And Industrial Strategy

On August 10, 2026, Meta published The Future Is For Everyone, Mark Zuckerberg's wide sweeping proposal for how superintelligence should fit into society.
The central idea is personal empowerment. Zuckerberg argues that advanced AI should give individuals more ability to create, learn, build businesses, improve their health and pursue their own goals rather than placing most of that intelligence under the control of governments, large institutions or a handful of AI companies.
Meta's vision imagines personal agents working continuously on a user's behalf, small teams building companies that once required much larger organizations, personalized tutors, faster scientific discovery and powerful creative tools available to billions of people.
Meta wants AI capability spread widely, while the compute, models, release decisions and government relationships needed to provide it remain concentrated among a handful of organizations.
Mark Zuckerberg, Founder and CEO, Meta:
“The defining questions of our age are who will have access to superintelligence and what will we direct it towards.”
One of Zuckerberg's strongest economic arguments is that AI's biggest contribution could come from helping people invent things rather than simply automating today's jobs.
Meta expects individuals to become capable of doing work that currently requires larger teams, more capital or specialized expertise. Zuckerberg predicts more small businesses, more experimentation and potentially more employment as people use AI to create products, services and jobs that don't exist today.
That is a different vision from a future where AI mainly replaces knowledge work. Meta argues that if personal agents increase people's capabilities quickly enough, workers can adapt and new demand can grow alongside automation.
For founders, that could change the economics of starting a company. Product development, research, design, marketing and operations could require fewer people and less initial capital. Small firms could reach meaningful scale much earlier.
Financial services will feel the same pressure. Meta already has AI that can plan work, connect with email and calendars and continue tasks after the user leaves. As agents gain access to financial information and connected services, permissions and accountability become part of the operating model, especially when an agent can act rather than simply advise.
The more unusual part of Zuckerberg's argument is about safety.
He rejects the idea that one centrally controlled superintelligence can be aligned to a single set of values that works for everyone. People disagree about politics, economics, culture and what makes a good life.
Meta's answer is to distribute powerful AI widely enough that people, businesses, governments and competing AI systems check one another.
It is essentially a balance of power argument. One person with vastly better legal, financial or cybersecurity intelligence could gain an enormous advantage. If many people have access to comparable capabilities, Meta argues that power becomes harder to monopolize. (There’s some irony here. Zuckerberg built his fortune by controlling access to data, distribution and network effects that others couldn’t easily replicate.)
That philosophy also influences Meta's approach to alignment. Personal agents should primarily help users pursue their own goals within legal and safety boundaries rather than enforce one company's view of what those goals should be.
Meta says it plans to build a private mode where even Meta can't access a user's information, and it intends to resume releasing some open models. It is also giving its independent board authority to approve safety criteria for model releases rather than leaving those decisions entirely with Zuckerberg or management.
Meta's existing algorithmic products are already under legal scrutiny, including a federal trial involving 29 U.S. states over alleged harm to children. Meta denies the allegations. A company asking people to trust far more capable personal agents will have to show that user empowerment, privacy and safety work in practice. Algorithmic accountability is already moving into the courts as AI and automated systems take on a larger role in people's lives.
Zuckerberg's decentralization argument has limits.
He wants individuals to have broad access to powerful AI, but he also argues that the United States and its allies should retain leadership in advanced models, silicon and infrastructure. Meta supports continued restrictions on exports of leading chips to geopolitical rivals and wants U.S. policy to make it easier to build data centres and energy capacity.
He also proposes closer cooperation between frontier AI labs and government. Rather than waiting until an advanced model is finished, Meta wants labs to share intermediate model checkpoints and technical staff so governments can identify cybersecurity and other security risks earlier.
The result still leaves considerable power with governments, frontier labs and the companies that control advanced compute. Individuals would gain far more capability. Governments would receive earlier access for security purposes. Independent boards would get more authority over release standards. Frontier labs would still control development of the most capable models.
Meta's vision is therefore decentralized at the user level while retaining substantial institutional coordination at the frontier.
Meta expects capital spending of US$130 billion to US$145 billion in 2026 and spent US$31.08 billion in the second quarter alone. It is investing in models, data centres, energy, networking, its own chips and outside accelerators while trying to deliver AI across products already used by billions of people.
If personal superintelligence is going to be free or affordable at global scale, someone still has to pay for the compute..
Meta wants superintelligence broadly distributed, but scarce compute still has to be allocated. Its answer is a dynamic auction for additional capacity, which means the vision of AI for everyone could still produce tiers of access based partly on what users can afford. (conflict?)
The business model hasn't been proven. Meta's second quarter free cash flow fell to US$784 million as infrastructure spending accelerated, even while its core advertising business remained highly profitable.
Meta is making these commitments under real pressure. Its infrastructure spending has climbed rapidly, the company is still building the compute capacity and custom chips needed to compete at the frontier, and its existing platforms face growing legal scrutiny.
The scale of the investment also reinforces a central tension in Zuckerberg's vision. Meta wants personal AI to give individuals more power, but only a small number of companies can currently finance the systems needed to provide it.
Meta's vision has clear upside for Canada.
Canadian entrepreneurs, researchers and smaller businesses could gain access to capabilities they would never be able to finance themselves. If AI lowers the cost of creating companies, learning new skills and developing new products, a smaller economy can participate without matching U.S. frontier model spending dollar for dollar.
Canada is already debating how to keep more domestic intellectual property, capital and compute capacity while using global AI platforms. The country's AI sovereignty debate is partly about preserving enough domestic capability to avoid becoming only a customer of technology developed and controlled elsewhere.
A recent pro-human AI initiative backed by researchers, business and labour groups also argues for human agency, limits on concentrated power and accountability for AI companies. Zuckerberg reaches some similar principles from a very different starting point.
Canada needs enough choice, competition, data control and domestic capability for its companies and citizens to use increasingly powerful AI on their own terms.
Zuckerberg's bet is that superintelligence can give individuals more power to learn, invent, work and build. Meta has the reach and financial capacity to put that idea in front of billions of people. The cost of doing so is already putting heavy pressure on cash flow.Whether users ultimately gain more control will depend on who controls the models, data, compute and rules behind their personal AI.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
