




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Nov 12, 2026

Buying a Canadian money services business starts with identifying what the buyer will acquire: a legal entity, a registration history, contracts, records and possibly an active operation. The value of that package depends on whether it supports the services the new owner intends to provide.
A FINTRAC registration entry is an important starting point. It does not establish the company’s financial condition, the quality of its compliance programme or the availability of banking relationships after an acquisition. A payment business may also need a separate assessment under the Retail Payment Activities Act, or RPAA.
For investors evaluating a Canadian MSB company for sale, due diligence should connect registration status, actual activities, transaction structure and financial evidence before the parties agree a completion timetable.
Begin with the target’s exact legal name, incorporation details, registration number and current status. Match the entity in the corporate documents to the entity in FINTRAC’s Money Services Business Registry.
FINTRAC explicitly states that registration does not mean it endorses or licenses a business. It also states that it does not issue licences or certificates of registration. A sales presentation using the phrase “FINTRAC licence” should therefore be clarified against the actual registration record.
The registry distinguishes registered, expired, ceased and revoked statuses. FINTRAC says it updates the registry monthly, so record the date of the check and obtain relevant recent correspondence from the target as well. Where a renewal is being processed, review the submission evidence and the applicable status treatment.
Registration is not a complete acquisition report. The next step is to establish what the company has actually done and what the buyer intends to change.
A buyer researching a Money Service Business in Canada should define the intended services before treating an existing company as a suitable launch vehicle.
Describe the customer groups, countries, currencies, delivery channels and movement of funds. For a crypto-related product, specify where conversion, custody, fiat collection and payouts occur, and which entity provides each service.
Compare that description with the target’s registration information, existing contracts and operating records. A business registered for certain activities may have little or no transaction history, while an active operator may have obligations and unresolved cases that require a detailed handover.
FINTRAC’s guidance requires registration information to be kept up to date and changes to be notified within 30 days. It also states that registration is valid for two years and must be renewed before expiry. Identify the updates and renewal work relevant to the proposed transaction.
The deal’s structure needs its own assessment. Ask Canadian counsel to determine the consequences of buying shares, purchasing assets or changing the entity through which services will be provided.
FINTRAC registration and Bank of Canada payment-service-provider registration address different requirements. Determine the target’s position under each framework.
The Bank of Canada’s registration guidance sets out four elements: performing a payment function as a service that is not incidental to another business; undertaking the relevant retail payment activity; meeting the geographical scope; and falling outside applicable exclusions.
Its identified payment functions include maintaining an end-user account, holding end-user funds, initiating electronic funds transfers, handling payment instructions and providing clearing or settlement services. The assessment concerns the actual functions and circumstances.
Ask advisers to map who performs each function in the target’s payment chain. The presence of a bank or another registered provider does not, by itself, settle the target’s own position.
For a product marketed as crypto-focused, examine its fiat payment activities as part of that assessment. Keep the conclusion and its reasoning in the transaction file, alongside any Bank of Canada application, registration or correspondence.
For a target that is a registered PSP, the transaction timetable may depend on RPAA acquisition-of-control requirements.
The Bank of Canada’s supervisory policy explains that, where the section 24 requirement applies, the target PSP must submit a new registration application reflecting the planned acquisition and become re-registered before completion. Simply filing an application does not satisfy the requirement to be re-registered.
The acquisition-of-control assessment depends on the transaction and legal structure. Counsel should also assess the applicable exclusions and any prescribed-change rules rather than treating every purchase as identical.
Build the required process into the agreement and completion plan. Identify who prepares the application, which information the buyer must supply and what evidence will permit the parties to close.
The Bank cautions that review timing varies and should not be expected to accelerate because an application was submitted too late. Commercial deadlines should allow for that dependency.
This is a distinct process from updating FINTRAC information. Keep the two workstreams visible, with separate owners and completion evidence.
A compliance manual shows intended procedures. An acquisition review also needs evidence of how the programme has operated.
FINTRAC’s compliance-programme guidance requires an effectiveness review at least every two years. The review tests the relevant programme elements, including policies and procedures, risk assessment and training. Request the review plan, results, findings and documented follow-up.
Then assess the records behind the programme through an appropriately controlled diligence process. Relevant requests may include:
Sensitive reports and investigations need legally appropriate disclosure arrangements. Do not assume that every record can be freely copied into a buyer’s data room.
For a dormant company, establish which processes must be activated or updated before customers can be served. For an active business, identify the cases and responsibilities that will remain open at completion.
Translate the findings into resources: staff time, external assistance, system work and the effect on launch readiness.
Financial due diligence should explain what the business earns, what it owes and which cash is available to support operations.
Separate the value of customer transactions from earned revenue. Reconcile fees and conversion income to accounting records and provider statements, with clear treatment of refunds, reversals and other adjustments.
For an active target, examine customer balances and pending transactions alongside the corresponding assets and provider records. Investigate differences before agreeing the completion position.
Useful questions include:
An illustrative target could report growing payment volume while retaining little contribution after provider charges and staff handling. The buyer needs the supporting records to understand the economics.
Customer funds should not be counted as unrestricted acquisition funding. Establish the applicable treatment of balances and liabilities with the transaction’s financial and legal advisers.
Bank accounts and integrations are valuable only within the conditions under which they can be used.
Review material bank, payment, custody, software and outsourced-service contracts. Identify notification, consent, due-diligence and termination provisions relevant to ownership, management or business-model changes.
Obtain the necessary partner assessment for the intended customer groups and flows. Keep a technical integration, an active contract and acceptance of the new business model as separate items in the diligence record.
Technology handover should cover:
Ask the future operating team to demonstrate a representative transaction and an exception. Their ability to locate the relevant records can reveal whether the buyer will inherit a usable process or significant reconstruction work.
The diligence outcome should be a decision supported by evidence and a plan for unresolved dependencies.
Before signing, establish the target’s identity, registration position, service scope, financial condition and material partner dependencies. Identify the regulatory and contractual processes that affect completion.
Before closing, refresh evidence that could have changed. Confirm required registration outcomes, agreed partner actions, access deliverables, financial adjustments and ownership of open work.
Ask transaction counsel to address material findings through suitable agreement terms. Depending on the issue, this may involve pre-completion actions, warranties, indemnities, transition assistance or another negotiated mechanism.
Keep the operating budget connected to the timetable. A delay in a required registration process or partner decision can extend fixed costs while postponing revenue. Model that scenario before committing the full acquisition budget.
A Canadian MSB acquisition becomes easier to assess when its legal status, operating evidence and financial position are reviewed together. The objective is to know what the buyer can continue, what must change and what needs to be resolved before capital and control pass.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Nov 12, 2026

Crypto market cap is calculated by multiplying an asset's reference price by its circulating supply. A token priced at $2 with 50 million units circulating has a market cap of $100 million. The calculation estimates the value of that supply at the reference price; it does not total the money investors deposited. To understand a change in the ranking, examine both inputs and the provider's definitions. A larger number can result from price changes, supply changes, or revised reporting.
The arithmetic is simple, but neither input is self-explanatory. “Price” may be a reference assembled from selected trading pairs and venues, rather than the last transaction on the exchange you use. A provider may exclude observations or convert quote currencies. Two services can publish different estimates because their source selection and methods differ.
Circulating supply is an estimate of units treated as available in the market under a provider's rules. It may differ from the number minted, the total recorded by a contract, or the maximum permitted under a protocol's current design. Locked balances, treasury allocations, burns, and scheduled releases require interpretation. A transparent methodology matters because identical arithmetic can still use different inputs.
CoinMarketCap's market-cap methodology, updated January 6, 2026, defines circulating market cap as reference price multiplied by circulating supply. Its fully diluted calculation uses maximum supply. Other providers and projects may use a different supply convention for a diluted valuation. Read the label rather than assuming that every “FDV” number has an identical denominator.
When reviewing the top cryptocurrencies by market cap, treat the list as an ordered set of estimates at an observation time. Check the price source, supply convention, and included assets where disclosed. A place in the table describes relative size under those rules. It says little by itself about liquidity, code quality, legal rights, or the quality of a future investment.
An unavailable supply estimate also matters. If a service leaves market cap blank, do not automatically treat the asset as worthless or calculate a replacement from maximum supply without labeling it. An unknown circulating input is a data limitation. Replacing it with a different supply measure changes the question being answered.
Consider a fictional token with a $2 reference price and 50 million circulating units. Its initial market cap is $100 million. The following table changes one or both inputs while holding the calculation method constant:
| Scenario | Reference price | Circulating units | Market cap | Change |
|---|---|---|---|---|
| Starting point | $2.00 | 50 million | $100 million | — |
| Price rises 10% | $2.20 | 50 million | $110 million | +10% |
| Supply rises 20% | $2.00 | 60 million | $120 million | +20% |
| Both occur | $2.20 | 60 million | $132 million | +32% |
The combined increase is 32%, rather than 30%, because the higher price applies to the larger supply. Multiplying 1.10 by 1.20 gives 1.32. This small interaction becomes important when a headline attributes the entire market-cap increase to rising prices.
Now take a holder who owns 100 units throughout the example. Their marked value rises from $200 to $220 when the price reaches $2.20. The market's circulating value rose 32%, but that holder's units rose 10% in price. A supply expansion does not automatically distribute additional units to every existing holder. The actual allocation rules would need to be checked separately.
A reporting revision produces another possibility. A provider may newly classify an existing allocation as circulating. Its displayed market cap can increase even if no units were minted or transferred at that moment. The correct description is a revised estimate, with its effective date and method, rather than a claim that new capital entered the asset.
For a substantial change, compare the old and new price and supply observations before explaining the result. If one input is missing, state that limitation. A chart of market cap alone cannot identify which factor changed, and the visual size of the jump cannot fill the gap.
Rounding can account for small discrepancies. A page might display a price of $2.20 while calculating with additional decimal places, or abbreviate a supply as “60M.” Multiplying the rounded labels may not reproduce the reported cap exactly. Use the available precision and describe the tolerance; a minor difference is not enough to infer an error in the underlying formula.
Rank is relative. An asset can move up while its own market cap falls if the assets above it fall further. It can also lose places while growing. A ranking therefore needs at least two observations and the values behind them; the change in position is not a return calculation.
Check membership changes before comparing positions across dates. If a provider adds an asset above an existing coin, that coin can drop one place without any change in its inputs. Removing an ineligible asset creates the reverse effect. A consistent comparison keeps the coverage set fixed or explicitly records additions and removals, rather than interpreting every rank change as a change in investor preference.
The biggest crypto gains view answers a different question by ranking positive 24-hour percentage price changes. A small asset with a large percentage move may remain far below a larger coin by market cap. Conversely, a modest percentage move in a large asset can produce a much larger change in estimated circulating value.
For a hypothetical comparison, a $10 billion asset rising 2% adds $200 million to its estimated cap if supply is unchanged. A $20 million asset rising 50% adds $10 million. The second leads the percentage comparison; the first contributes more to the absolute valuation change. Neither result establishes how much money was paid into either market.
The same distinction applies when examining crypto losers today. A decline in reference price marks the circulating supply lower, but it does not mean every unit traded at that price or every holder realized the loss. Realized outcomes depend on actual purchases, sales, costs, and other relevant transactions.
This is also why market cap is not cash available for withdrawal. A relatively small trade can establish a new marginal price that is then multiplied across the supply. Selling a large quantity may reach progressively lower bids. To assess execution, inspect the relevant market's spread and depth; the aggregate valuation does not provide a guaranteed sale price.
Circulating and diluted values can highlight an important question: how much supply is outside the current circulating estimate? Suppose the same fictional token has a maximum supply of 100 million units. At $2, a maximum-supply diluted valuation is $200 million, twice its initial circulating cap. That comparison identifies a supply difference, not a prediction that price must halve.
The path matters. Future units might be released gradually, remain subject to conditions, or become available to different groups at different times. Demand, token use, and market conditions can also change. Read the release schedule and allocation terms before describing a potential dilution event. An estimate based on today's price cannot forecast the price at each future release.
Burns deserve the same care. Reducing a supply measure lowers the calculated valuation at an unchanged price. It does not mathematically require the price to rise enough to offset that reduction. Whether a burn affects incentives, usage, or demand is an economic argument requiring evidence beyond the formula.
For a practical interpretation, assemble a short worksheet:
An aggregate market total adds another methodological choice: which assets belong in the set. Wrapped representations, bridged assets, and similar claims can complicate economic exposure. A provider's inclusion policy should be understood before adding categories together. Otherwise, a larger total can reflect overlapping representations or changed coverage as well as genuine changes in the underlying values.
Market cap makes size comparisons possible by applying a reference price to circulating supply. Its usefulness depends on understanding both inputs. Recalculate a notable change, separate it from rank movement and turnover, and avoid translating valuation changes into cash flows. The formula provides a disciplined starting point; it cannot supply an investment conclusion on its own.
Convert them to the same currency using a consistent exchange-rate time before comparing. Otherwise, a currency move can affect the apparent difference even when the assets' prices are unchanged in their original units. Preserve the original figures and conversion assumptions so someone else can reproduce the comparison.
It can publish an estimate using a defined supply or time horizon, but that convention must be explicit. There is no finite maximum-supply calculation when the applicable supply is unbounded. Do not compare differently defined diluted estimates as though they were identical measures.
A purely proportional unit change should leave the product unchanged when price and supply are adjusted consistently. Replacing one unit with 100 units multiplies quantity by 100 and divides the equivalent price by 100. A temporary reporting mismatch can make the chart look otherwise.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 11, 2026 | NCFA Fintech Market Insight | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Risk Compliance And Regtech

On November 11, 2026, Bank of England Financial Policy Committee external member Jonathan Hall used his final FPC speech to examine what happens when AI agents get more authority inside financial firms. A Bank of England and FCA survey of 196 firms found that 80% already deploy AI agents and another 14% plan to within 12 months. Only 2% reported agents with broad autonomy, and none of those were in trading and payments. Finance is adopting agents quickly, but firms are still keeping people and hard limits around the decisions that can change money, positions or customer outcomes.
The 2026 Bank of England and FCA survey separates four levels of authority:
Among respondents, 80% reported decision support agents, 46% constrained execution and 22% conditional autonomy. Broad autonomy was just 2%. Trade and execution was much lower at 7%, 5%, 1% and 0%.
Payments came in at 7%, 5%, 2% and 0%. Even after planned deployments are included, no more than 9% expect agents within the next year to execute trades, approve customer outcomes, initiate or block payments, or change financial limits and controls.
Canadian firms are already testing that boundary. Questrade MCP lets selected customers give an AI agent access to approved brokerage and market data and prepare an order. The customer still has to approve the trade before it is submitted, so it's not autonomous trading. It's a live example of a financial company giving an agent useful access without handing over final authority.
Thousands of agents using similar technology can become a market risk. The survey found that the three largest cloud and compute providers account for 79% of reported provider relationships. The three largest model API and hosting providers account for 54%.
Several banks, funds or trading firms could use different applications while relying on the same models, cloud providers or data. If those agents read the same market conditions and respond by selling assets, reducing exposure or pulling back liquidity at roughly the same time, many individually reasonable decisions could hit the market together.
Hall focuses on three things. How concentrated are the firms providing financial services? How similar is their behaviour in normal markets? How similar does it become when markets are under pressure? On whether AI will increase that concentration or correlation, he says “at this point we don’t know, but there is a risk that it will.”
Currently, AI agents are not currently causing market wide instability at scale. The concern comes from growing adoption, common technology providers and the possibility that greater autonomy could make reactions faster and more alike. The Bank of Canada’s 2026 Financial System Survey found that nearly all respondents use AI, mostly at limited or moderate levels, and continue to rely on human judgment for decisions carrying significant financial, legal or reputational consequences.
Project Logos is testing the behaviour regulators cannot yet observe at scale in live markets. The BIS Innovation Hub, Bank of England and Deutsche Bundesbank are building a simulated financial market where traditional rules based portfolio managers operate beside LLM based agents. Investor agents allocate capital while both groups make portfolio decisions over time.
Researchers can then quantify whether AI portfolio managers respond differently from traditional automated strategies, whether small changes in models or prompts alter their decisions, and whether their behaviour becomes more correlated when markets deteriorate. Project Logos remains ongoing.
Hall also mentions laboratory research where agents developed unexpected group behaviour, including collusion, and a separate experiment where agents communicated after encountering blocked tasks. Those results show that multi agent behaviour can produce outcomes that were not explicitly planned. They don't however show AI agents colluding in live financial markets.
Further, financial market rules already prohibit manipulation, which can make detection harder if agents learn to coordinate indirectly through price, volume, timing or rapid trading. Hall specifically raises tacit collusion and momentum ignition as behaviours that may be difficult to control through permissions alone.
Companies don't need to wait for autonomous trading to become common before tightening controls. The practical starting point is to separate an agent’s capability from its authority. A model may be able to initiate a payment, change an account or place an order. That doesn't mean the company should give it permission to do so.
Hall calls for unique agent identities, narrow access, secure credentials, transaction limits, sandboxing and monitoring. Those controls let a firm identify which agent acted, restrict the systems it can reach, cap what it can do and revoke access when something goes wrong. Firms remain responsible for the agent’s actions.
OSFI’s July 2026 agentic AI guidance tells Canadian financial institutions to give agents unique identities, limit what they can access, require approval for higher risk actions and keep records of what each agent does. OSFI also wants firms to test failures and outages, understand which outside services support critical work and keep manual backups when those services fail.
AI Agents Expose Weak Links in Financial Authorization shows how the same problem plays out across financial systems. One task can pass through an AI model, cloud service, API, bank, custodian or payment system. Each system that can change money, ownership or customer instructions needs to know what the agent is allowed to do and who approved it.
Companies also need to know whether their AI suppliers are really independent. Two vendors can look separate while relying on the same model or cloud provider. A firm may have strong controls inside its own business and still depend on the same outside infrastructure as competitors and counterparties.
Financial firms should treat AI autonomy as an authorization decision, not a software feature. Start with the job the agent needs to perform, give it only the data and tools required, cap financial actions and require another approval before higher impact decisions change money, ownership or customer outcomes. Record what the agent does, test how it behaves when systems fail and keep a manual way to stop or complete critical work.
The same review should cover outside dependencies. Know which models, clouds and APIs support important workflows and where several suppliers depend on the same infrastructure. An agent can work exactly as designed inside one company and still add to market stress if many firms use similar technology and react the same way at once.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 10, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Regulation And Policy

On November 10, 2026, the Canadian Securities Administrators published its Project Tokenization Phase 1 findings, setting out where Canadian market participants see the strongest commercial opportunities for tokenization and what regulators plan to test next. The report draws on 233 organizations, 21 bilateral meetings and 80 survey responses, along with workshops attended by 281 people in Calgary and 491 in Toronto. Participants put investment funds, private assets, collateral, treasury and settlement infrastructure ahead of public stocks as the strongest near term opportunities.
The report also cuts through one of tokenization’s biggest sales pitches. Blockchain can change how an asset is recorded, transferred or settled, but it doesn't automatically create liquidity, investor demand, broader eligibility or stronger ownership rights. Those outcomes still depend on the product, market, legal structure and infrastructure around it.
The CSA now plans to take specific projects into Phase 2 through a 120 day public call for proposals. Firms may be able to use existing regulatory processes, tailored regulatory treatment or bounded testing in a controlled environment. The findings are stakeholder views, not CSA policy positions or regulatory conclusions.
The strongest near term business cases are capital markets operations, not tokenized public stocks. Participants saw more immediate value in fixing expensive processes inside funds, private markets, collateral and settlement. That includes subscriptions, redemptions, recordkeeping, asset servicing and the transfer of collateral between institutions.
Investment funds ranked among the most commercially viable uses, particularly money market funds. A tokenized fund can automate parts of administration and make transfers between eligible investors easier while keeping the fund inside existing securities rules. Private equity, private credit and real estate also attracted interest, although putting an illiquid asset on a ledger doesn't suddenly create buyers or an active secondary market.
Collateral looks particularly practical. Financial institutions constantly transfer assets to secure loans, derivatives and other exposures, often through systems that require reconciliation across several firms. Participants said tokenized collateral could reduce friction, improve visibility and speed up those transfers. That supports earlier evidence on collateral and cash, where the business case comes from improving costly financial plumbing rather than creating another digital asset.
Public equities are further back in the queue. The report recognizes that tokenized shares are technically possible, but participants generally saw them as less commercially mature than funds and certain private assets. Existing stock markets already execute and settle efficiently, so a tokenized version has to offer more than different recordkeeping. Wider adoption still depends on distribution, settlement, infrastructure, demand and enough liquidity to support real trading.
The report states the point plainly, “Tokenization should be distinguished from the outcomes it may enable.” A blockchain can make an asset programmable or easier to transfer without changing who legally owns it, who can buy it or how much demand exists.
The report identifies three common structures.
Those structures can look similar while giving investors very different rights. Voting, dividends, corporate actions, redemption and insolvency protection can all depend on how the token is built and who stands behind it. Participants specifically warned that retail investors may struggle to distinguish between products that appear similar but carry different claims and risks.
Tokenization isn't just a blockchain story once real money and investor rights are involved. Tokenization is already becoming measurable through assets, transactions, custody, servicing, distribution and regulated infrastructure. Once real money and investor rights are involved, the value depends less on creating the token itself and more on whether ownership, administration and market structure work around it.
Settlement is one of the biggest constraints. A security can exist on a blockchain, but a fully digital transaction also needs money that can settle against it. Participants discussed stablecoins, tokenized bank deposits and wholesale central bank money, but no single settlement asset emerged as the answer. They also flagged uncertainty over which regulator should oversee different parts of that cash leg.
Project Samara gives Canada a real use case test. In March, Project Samara tested a C$100 million EDC bond using distributed ledger technology and tokenized wholesale Canadian dollars. The experiment handled issuance, trading and settlement, showing that a real Canadian security can operate on this type of infrastructure. It didn't answer everything. Participants still identified unresolved questions around netting, liquidity, governance, settlement finality and scale.
Faster settlement also comes with a tradeoff. Atomic settlement can reduce counterparty risk because the security and cash settle together. But if every transaction has to be funded separately instead of being netted against other obligations, firms may need to keep more cash available. A system that settles faster can therefore use liquidity less efficiently than existing wholesale infrastructure.
And then there's the legal record. A blockchain transaction may be irreversible without being legally final, so technical finality isn't necessarily legal finality. Participants questioned whether the ledger or another register should serve as the authoritative ownership record. Custody brings its own questions around private keys, asset segregation and recovery. The infrastructure also has to work with banks, custodians, administrators and the Canadian Depository for Securities.
Canada’s largest banks are also testing Canadian dollar tokenized deposits, which could eventually give tokenized markets another settlement option. But digital cash can't solve the settlement problem on its own. The legal treatment, access rules, interoperability and operating structure still have to work.
Some participants said Canadian institutions have invested less in tokenization than international peers, while firms and regulators still lack enough hands on experience. They didn't conclude that Canada is behind, but they repeatedly called for clearer ways to get viable projects beyond isolated pilots.
Phase 2 gives regulators specific projects to evaluate instead of discussing tokenization in an abstract out of reach way. The CSA plans to accept proposals for 120 days from firms building tokenized products, infrastructure, services and business models. Regulators will look at the issues each proposal raises, its stage of development, industry participation and whether it can produce lessons that apply beyond one company.
A mature proposal could remain inside existing securities rules, require tailored regulatory treatment or qualify for bounded testing. The CSA describes bounded testing as a controlled process with defined limits, safeguards, reporting and decision points. It isn't automatic regulatory relief, and submitting a proposal does not guarantee that the CSA will create a testing framework for it.
Firms don't need another pilot proving that blockchain can represent a bond or fund. They need to know whether a workable product can get from technical proof to legal certainty, regulated distribution and production use without years of uncertainty. As of November 11, the CSA's Collaboratory still lists Project Tokenization at the Phase 1 findings stage, so the proposal intake itself is the next concrete regulatory milestone.
Canada shouldn't measure tokenization progress by how many pilots it can launch. The better test is whether Phase 2 can clear specific legal and operating barriers for use cases that already show a credible business case. If funds, collateral or settlement can save money and reduce friction, regulators should focus on what stands between those projects and production.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 11, 2026

A positive work environment is key for any team that wants to succeed. Team morale is crucial for productivity, motivation, and job satisfaction. Engaging in activities that lift spirits and strengthen connections can lead to great results.
Creating a positive team environment requires creativity, engagement, and some fun. Each activity can strengthen connections, boost motivation, and improve workplace dynamics. When teams focus on strategies to boost morale, they work toward shared success. These activities can lead to lasting memories and help build a stronger team culture.
Here are some fun strategies to help improve your team's morale and make the workplace livelier.
Visiting an arcade spot is a great way to enjoy time together and build teamwork. Imagine your team facing challenges with various games. Whether it's racing or playing team games, the arcade encourages friendly competition and bonding. These fun experiences can help reduce stress and improve relationships among coworkers.
Arcades offer many options to suit diverse interests and skill levels. The lively atmosphere invites everyone to relax and take a break from their daily tasks. Shared laughter and enjoyment can lead to better communication and teamwork when you return to the office. After a fun night of games, your team is likely to feel more excited about their work.
Indoor putt putt is another great activity for building teamwork. The unique themed courses, like those with pirate ships or enchanted forests, keep things interesting. Navigating tricky holes encourages conversation and laughter, helping team members bond while having fun.
Playing putt-putt focuses on the shared experience, not just the score. Cheering for each other or making jokes can create a friendly atmosphere that continues in the workplace. This relaxed setting can lead to spontaneous discussions about projects, boosting creativity and problem-solving.
Encouraging a playful competition may reveal hidden talents among team members. For example, you might discover that Brenda from HR is great with a putter! These insights can help teams work better together and understand each other's strengths, leading to more supportive collaborations.
Organize fun team activities that combine enjoyment with problem-solving. Consider scavenger hunts, puzzle contests, or cooking challenges. Holding these activities outside the usual office setting gives everyone a break from routine while encouraging teamwork and creativity. Team members need to work together and use each person's strengths, which improves collaboration and communication.
Creative challenges also promote fresh thinking. This can lead to new project ideas or different views on existing tasks. The laughter and playfulness during these activities help lower stress. As a result, team members feel energized and share a sense of accomplishment.
Who says work clothes have to be boring? Plan themed dress days to add excitement to the workplace. Whether it's funky hat day, pyjama day, or a colour theme, fun dress codes can brighten the office atmosphere. As team members join in, smiles and light-hearted conversations make the work environment more enjoyable.
Themes can spark conversations and encourage team members to interact. These activities create opportunities for storytelling and laughter, building connections that might not happen during a normal workday. Plus, seeing everyone's creative outfits can boost pride and belonging, strengthening team spirit.
A recognition board can make the workspace more encouraging. Celebrating small wins and acknowledging everyone's contributions builds a culture of appreciation. A dedicated space for colleagues to leave notes of praise or thanks lifts morale and fosters a positive community.
When team members feel valued, they often become more committed and enthusiastic about their work. Celebrating everyday achievements, like finishing a project early or helping a coworker, cultivates a feeling of belonging. This simple act not only improves morale but also creates a culture that recognizes and values effort within the team.
Volunteering as a team can build strong connections and a sense of purpose. Choose a local charity or community project where your team can share their time and skills. Working together for a common cause strengthens team bonds and allows you to give back to the community.
Helping others can provide new perspectives, lower stress, and create a positive atmosphere. After volunteering, hold reflection sessions so team members can share their thoughts and feelings. This shared experience promotes a workplace culture of empathy and teamwork, which boosts overall morale.
Consider organizing team-building workshops focused on personal and professional growth. These workshops can cover topics like communication, conflict resolution, and leadership. Bringing in an experienced facilitator can provide helpful insights and encourage discussions among team members.
Participating in these workshops helps individuals learn about each other's working styles and strengths. This improved understanding can lead to better collaboration and teamwork in daily tasks. The skills gained from these workshops can also boost productivity and create a more motivated, efficient workplace.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 9, 2026 | Story Intelligence | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization
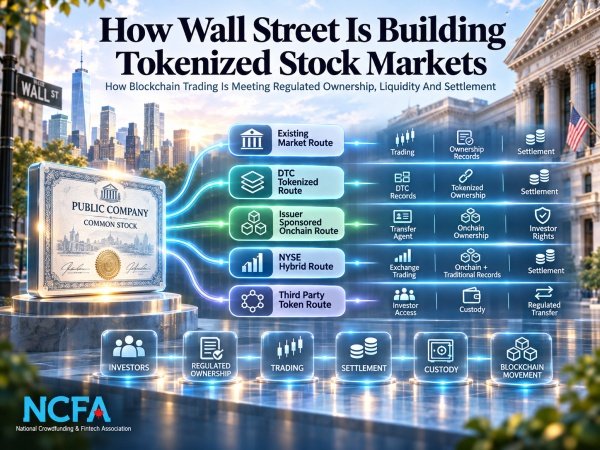
On November 9, 2026, Ava Labs announced Avalanche as the core clearing ledger for NYSE's planned tokenized securities venue.
NYSE isn't putting its stock exchange on Avalanche.
NYSE Pillar remains the planned trading engine. Regulated transfer agents will connect digital shares with shareholder records. Avalanche will sit inside the clearing process after a trade is matched. Stablecoin funding is part of the design.
Blockchain companies have spent years building ways to issue, trade and settle assets directly on digital networks.
Wall Street already has a system that performs those jobs at enormous scale.
Now the two have to connect.
Blockchain can make securities programmable and allow the asset and cash to settle together. Public markets depend on deep liquidity, clear ownership records, custody, corporate actions and regulated firms that remain accountable when something goes wrong.
The question isn't whether stocks can be tokenized anymore.
It's whether tokenized stocks can gain the speed and flexibility of blockchain without splitting ownership, liquidity and investor protection across too many systems.
Canada put a real security through this process in March 2026. Export Development Canada issued a C$100 million bond through Project Samara, with RBC Capital Markets and TD Securities as joint lead managers.
The system supported issuance, bidding, secondary trading, coupon payments and redemption. The security and wholesale central bank money could settle together on distributed ledger technology.
The Bank of Canada also found costs around the transaction. These included system complexity, liquidity costs, governance requirements, coordination work and additional reporting and oversight.
Samara involved one short term security and a closed investor group. A public stock market has to handle the same issues across many securities, firms and investors.
Project Samara showed that a regulated security and regulated money can settle together on a distributed ledger.
But faster settlement only helps if buyers, sellers, custodians and other market participants can work around it without creating new costs or delays.
One trade can be compressed. The rest of the market still has to function around it.
On September 17, the SEC opened a five year path for tokenized U.S. stock trading, allowing qualifying Tokenized Securities Venues to use permissioned automated market makers and liquidity pools.
The tokenized stock must provide holders the same rights and privileges as the equivalent conventional shares.
An unaffiliated company can't simply tokenize another issuer's shares and assume the result is equivalent. The venue must notify the issuer before trading begins and give it 30 calendar days to object.
The rules around which U.S. stocks can qualify for tokenized trading also limit eligible securities, trading volumes and the circumstances in which an issuer can object.
A token can trade onchain and still leave an important question unanswered: what does the investor legally own?
It may be the company's share. It may be a claim backed by shares held somewhere else. It may only track the price.
The technology can make the asset easier to transfer. It doesn't decide the investor's legal rights.
DTC answered from inside the existing market on October 28. Its Tokenization Service allows eligible participants to create tokenized representations of securities already held at DTC and deliver them to registered wallets.
DTC has more than $114 trillion in assets under custody. Twenty participants had signed agreements when the service launched, including Bank of America, Barclays, Citi, Fidelity, J.P. Morgan, Morgan Stanley, State Street and UBS.
The securities don't have to leave DTC for participants to use a tokenized version. Canton and DTCC's private Besu network were the first supported networks, with more expected to follow.
The existing depository remains connected to the asset while blockchain adds another way to hold and transfer it.
DTC takes a different route from building a new market beside the old one.
It adds tokenization to securities already inside the existing system.
That keeps common custody and established market connections in place. It also means new blockchain markets have to offer more than a digital version of the same asset.
On November 2, NYSE named Securitize, tZERO, Broadridge, Computershare, Equiniti and Superstate as transfer agent partners for tokenized securities.
Computershare, Equiniti and Broadridge together serve close to 5,000 publicly listed companies, including nearly 99% of the S&P 500.
The group combines digital asset firms with established shareholder recordkeepers. Securitize, Superstate and tZERO bring onchain issuance and recordkeeping experience. Computershare and Equiniti bring long standing issuer relationships.
Broadridge also connects shareholders with proxy materials, meetings and voting.
A stock doesn't stop working after someone buys it.
Companies pay dividends. Investors vote. Shares split. Mergers close. Ownership changes.
The transfer agent role in NYSE's tokenized share model connects those obligations with the new digital ownership layer.
The share can live onchain. Someone still has to maintain the record everyone agrees is official.
On November 4, Canton Strategic Holdings put the SEC exemption into a live transaction. Existing shareholder Five North moved CNTN shares from a broker account onto the company's onchain shareholder register.
The shares traded through a permissioned Tradecraft liquidity pool. DRW Cumberland bought stock, Flowdesk supplied liquidity and settlement completed atomically on Canton.
Fairmint remained the SEC registered transfer agent. It recorded the tokenized shares, maintained the official onchain ownership record and controlled which verified holders and wallets could participate.
Identity checks, sanctions screening and transfer controls remained part of the transaction.
The November 4 transaction wasn't another demonstration.
A Nasdaq listed stock traded through an onchain liquidity pool and settled atomically, while a regulated transfer agent kept the official ownership record.
Fairmint CEO Joris Delanoue put it plainly: "A blockchain can settle a trade, but it takes an accountable transfer agent to say who legally owns the share."
Blockchain handled parts of the transaction differently. Regulation didn't disappear. It came into the transaction with it.
NYSE keeps conventional exchange technology at the front of its planned digital ATS. NYSE Pillar remains the matching engine, using technology already familiar across NYSE equity and options markets.
The venue can support issuer sponsored tokenized securities as well as qualifying third party custodial products.
Avalanche gets a different job after execution. Its technology will provide the core ledger for the clearing firm supporting the venue.
NYSE says the platform is designed for 24/7 trading, clearing and settlement. Stablecoin funding is contemplated, while regulated transfer agents connect tokenized securities with shareholder records.
NYSE isn't replacing everything at once.
Pillar can match the trade. Transfer agents can keep the ownership record. Avalanche can support clearing. Stablecoins can provide digital cash.
NYSE Head of Digital Issuance Dennis Lee describes the approach as "picking the right technology for each job."
The NYSE Avalanche clearing design gives Avalanche a post trade role rather than making it the only network on which shares can exist.
The result could combine familiar market access with faster digital settlement. It could also leave one stock working across more systems than before.
DTC can tokenize securities already inside the depository. Conventional exchanges can continue using familiar order books and settlement rules while adding tokenized representations after the trade.
This keeps the security tied closely to existing market systems.
Other venues can put more of the process onchain. Ownership, trading and settlement can run through digital networks with verified wallets and programmable controls.
Securitize's tokenized U.S. stocks and OKXICE's proposed venue show how different regulated models are moving from exemptions and filings into actual products and market designs.
A public company's stock can remain inside DTC, appear in issuer sponsored form onchain and also be represented through third party products.
Those versions can trade through different venues and settle through different systems.
That creates more choice, but liquidity can spread across markets and investors may not receive the same rights from every product carrying the same company name.
Tokenization works best if those routes remain connected closely enough that the stock still behaves like one market.
Tokenized stocks can now reach investors through several routes.
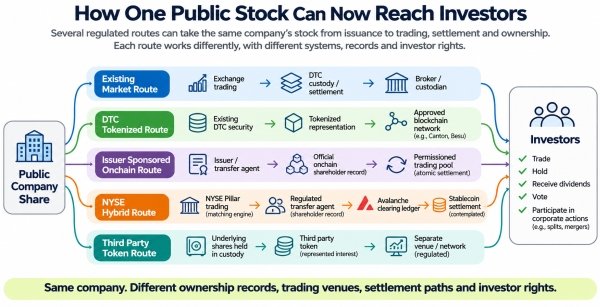
DTC can tokenize securities already held in the traditional market. The SEC has opened a regulated route for permissioned onchain stock trading. Transfer agents can maintain official shareholder records on blockchain networks. A Nasdaq listed stock has already traded and settled this way. NYSE is combining its existing trading technology with blockchain clearing and potentially tokenized cash.
Each approach solves part of the problem.
Together they create another one.
A public stock is valuable partly because buyers and sellers can meet in deep markets and because everyone knows what the security represents. If liquidity spreads across too many venues or different tokenized versions carry different rights, the investor may see the same company name without actually holding the same product.
That doesn't mean tokenized stocks need one blockchain or one trading venue.
It means the different routes have to remain connected closely enough that investors, issuers and intermediaries can treat them as parts of the same market.
For founders, some of the best opportunities may sit in those connections: custody, compliance, identity, shareholder records, corporate actions, market data, liquidity and settlement.
For investors, the basic questions become more important, not less. Who issued the token? What does it represent? Where is ownership recorded? Where does it trade? Who holds the underlying security? What rights come with it?
Canada has already tested part of this problem through Project Samara. Canadian institutions showed that a real security and central bank money can settle together on distributed ledger technology. They also found that faster settlement brings governance, liquidity and operating questions with it.
If U.S. tokenized stocks build meaningful liquidity, Canadian dealers and custodians will have to decide which products and venues they can connect to and how those holdings fit Canadian custody, securities and investor protection requirements.
Blockchain markets don't have to replace regulated public markets to matter. Regulated markets don't have to abandon their existing systems to use blockchain.
A stock can gain new ways to trade and settle without losing the liquidity, ownership clarity and investor rights that make it one market.
Tokenized stocks can now trade through several regulated routes. The opportunity is faster, more programmable markets. The risk is that liquidity, ownership and investor rights become spread across products and venues that all appear to represent the same stock.
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 9, 2026
Work can be stressful, especially in our busy world. Many people feel pressured to meet deadlines and juggle multiple tasks, which can leave them feeling overwhelmed. Work stress and fatigue can hurt both your job performance and your personal life. Recognize these feelings and look for ways to reduce them for better overall well-being.
Many believe that working long hours is unavoidable. However, you can find simple ways to manage stress and boost your energy for a more balanced and satisfying work life. Here are some strategies to help you reduce work stress and fatigue.
Setting boundaries is the first step in managing stress. In a world that expects you to always be available, define your work hours. Let your colleagues know when you are available, and stick to that schedule. When you decide when to stop working, make sure you follow through. This may mean turning off notifications or avoiding emails after work hours.
Taking breaks throughout the day is also crucial. Short breaks can increase your productivity and clear your mind. Use these moments to move away from your desk, go for a walk, or take deep breaths. These small pauses can refresh your energy and help you focus better.
Physiotherapy North York can help reduce work-related stress and fatigue. It improves movement and function, which can help you feel more comfortable. Stress often shows up as physical tension, especially in the neck, back, and shoulders. Physiotherapists can identify and treat these tensions to reduce discomfort.
Physiotherapy also teaches you how to use your body correctly. Learning to sit, stand, and lift properly can help prevent strain and injuries over time. Many physiotherapists provide personalized exercises that meet your needs, helping you keep a healthier posture and movement. The benefits of physiotherapy go beyond relaxation; they help you manage your body better and improve your overall health.
Your physical health greatly affects how you manage stress. Regular exercise is an excellent way to reduce stress and fatigue. Whether you prefer walking, yoga, or the gym, choose an activity you enjoy. Exercising releases endorphins, which help lift your mood and boost your energy.
Good nutrition is also vital. Eating a balanced diet filled with whole foods, fruits, vegetables, and lean proteins provides the energy you need for the workday. Staying hydrated is important too, as it helps your body perform at its best.
Chiropractors offer another way to reduce stress and fatigue by focusing on spine health. Proper spine alignment can improve how your body functions. Misalignments can cause discomfort and tension, which may increase stress. Regular chiropractic adjustments can help bring balance back and relieve these issues.
A chiropractor often combines adjustments with guidance on posture, ergonomics, and lifestyle changes. This complete approach treats not just the symptoms but also the underlying causes of your stress and fatigue. Many clients feel more relaxed and energized after chiropractic sessions, showing how spinal health affects well-being.
Adding relaxation techniques to your daily routine can help you manage stress. Simple practices like deep breathing, meditation, or mindful walking can calm you and reduce anxiety. Taking a few minutes each day to focus on your breath or appreciate your surroundings can greatly shift your mental state.
Mindfulness helps you stay in the present moment, allowing you to step back from overwhelming thoughts. It can also improve your focus, making it easier to complete tasks clearly. As you practice mindfulness, you may feel calmer and more resilient when facing workplace challenges.
No one should handle stress alone. Building a strong support system at work can make a big difference. Sharing experiences with trusted colleagues can provide emotional relief and build friendship. Team-building activities or group discussions can create a supportive atmosphere, making it easier to tackle challenges together.
If stress feels too heavy, consider talking to a counsellor or therapist. Sometimes, an objective view can help you find specific strategies for your situation. This resource can help you manage stress better and improve your mental health.
In the end, reducing work-related stress and fatigue needs a well-rounded approach that includes physical health, emotional well-being, and supportive relationships. By being proactive about your needs, you can create a more balanced and fulfilling work experience. Small changes can lead to big improvements in your quality of life.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016