





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 4, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Digital Assets, Embedded Finance
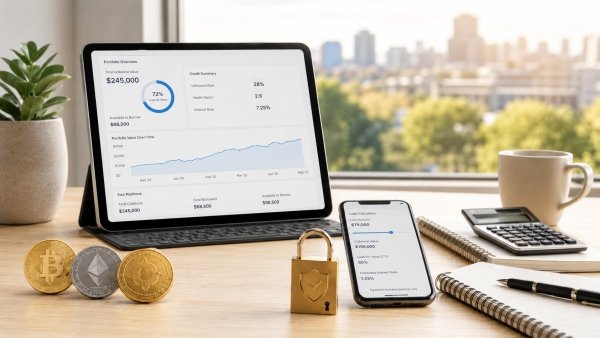
On September 3, 2026, Toronto-based APX Lending launched a five-year crypto-backed line of credit that lets eligible borrowers pledge Bitcoin, Ethereum or both, draw funds, repay them and borrow again. APX says the facility supports borrowing up to 60% loan to value, with annual rates from 10.49% to 11.99% depending on the outstanding balance.
Interest applies only to money actually borrowed, with no charge on unused capacity. APX also says there are no origination, prepayment or liquidation fees. The biggest change from APX's existing fixed-term loans is that borrowers can use the credit line more than once. They can keep approved collateral in place, draw funds when needed, repay them and borrow again.
APX gives the example of C$200,000 of Bitcoin and C$100,000 of Ethereum supporting up to C$180,000 of borrowing at the maximum 60% LTV. Available credit changes with the value of the collateral, so a falling crypto market can reduce borrowing capacity quickly.
The basic idea will be familiar to anyone who has used a securities-backed line or borrowed against property. The difference is the collateral. Bitcoin and Ethereum trade around the clock and can fall sharply in a short period, which makes ongoing collateral management a much bigger part of the borrower experience.
For long-term crypto holders, the attraction is access to cash without selling the underlying asset. That can help with business funding, debt repayment or other liquidity needs, although borrowing costs above 10% mean APX still has to compete with conventional secured credit where borrowers have access to it.
APX begins warnings when a loan reaches 80% LTV. At 90%, collateral is partially sold until the loan returns to 85% LTV. APX introduced the 90/85 liquidation model in August and says there is no liquidation fee.
A borrower can still lose Bitcoin or Ethereum when prices fall. APX's approach changes how much gets sold once the threshold is reached rather than removing liquidation risk altogether.
Custody is part of the product design as well. The OSC decision granting APX exemptive relief says collateral held under the lending arrangement is not rehypothecated (not reused or lent out to other parties). APX says assets are held in segregated BitGo Trust cold-storage wallets. Client accounts are not protected by CDIC or the Canadian Investor Protection Fund.
The revolving line follows APX's July launch of embedded crypto lending with Netcoins. Eligible Netcoins users can access APX loans through the platform while APX supplies the capital, underwriting, collateral management, compliance and servicing.
APX therefore doesn't have to rely entirely on finding borrowers through its own brand. Exchanges and wealth platforms can potentially add crypto-backed credit without building the lending operation themselves. The new revolving facility has not been announced as a Netcoins product, so the partner channel and the new line should be treated separately for now.
Ontario's securities regulator granted APX time-limited exemptive relief for its crypto-backed lending model, with the decision extending to participating jurisdictions through Canada's passport system. The order covers Bitcoin and Ether collateral and sets conditions around custody, disclosure and account suitability. It is tailored to APX and expressly says the decision should not be treated as precedent for other applicants.
APX is entering a market where other Canadian platforms are experimenting with similar products. Shakepay's Bitcoin-backed credit line, launched in August, gives eligible Canadians another way to borrow against digital assets. Cayman-based Ledn also continues to offer Bitcoin-backed Dollar Loans in most Canadian provinces, although Quebec, New Brunswick, Nova Scotia and Saskatchewan are excluded. APX differs by supporting both Bitcoin and Ethereum and by offering a five-year revolving facility rather than Ledn's standard 12-month Bitcoin-backed loan.
One platform can own more of the lending relationship itself; another can plug into a specialist lender such as APX. For exchanges and wealth platforms, embedded credit creates a way to earn more from customers who already hold digital assets without forcing those customers to sell them.
Will crypto holders use Bitcoin-backed credit often enough to make it a mainstream secured lending product?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
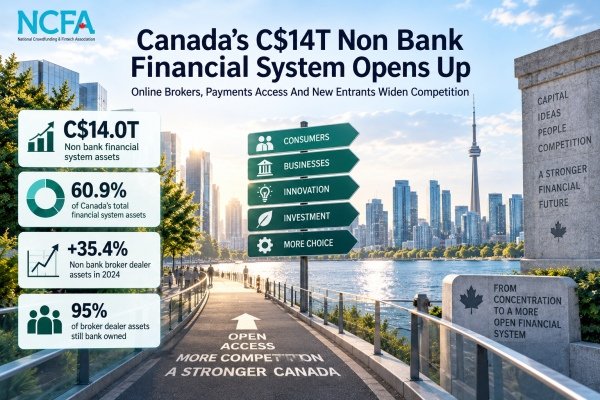
On September 3, 2026, Bank of Canada staff released new non bank finance data showing that Canada’s non bank financial sector held C$14.0 trillion in assets at the end of 2024, equal to 60.9% of the financial system. The Bank's broad definition includes pension funds, insurers, investment funds, financial auxiliaries and other intermediaries. Much of the 2024 increase also came from stronger market valuations.
The headline number is only part of the story. Faster growth is appearing in narrower bank like activities, online brokerage and specialty finance, while commercial banks still retain enormous asset and distribution advantages.
Canada already had a huge financial system outside deposit taking banks. What's changing is how customers reach it, where credit can originate and how many firms can compete for data, payments, investing and banking services.
Canada already had a vast financial system outside banks before fintech took off. Pension funds, insurers and investment funds have held enormous pools of financial assets for decades. The Bank says non bank assets have grown at an average annual rate of 6.9% since 2010.
The C$14 trillion also grew faster in 2024 because markets rose. Other investment funds increased 18.8%, pension assets rose 9.6% and insurance assets rose 9.8%. The Bank attributes much of that growth to stronger valuations.
Fintech arrived inside a financial system that was already enormous. Since then, investing has become easier to distribute online, more credit products have appeared outside traditional bank lending, payment firms have gained access to national infrastructure and financial data is being opened to approved competitors. Customers now have more ways to reach financial products without starting at a bank branch.
Online brokerage is one of the clearest changes in the Bank's data. Non bank broker dealer assets grew 35.4% in 2024, and the Bank says online brokers drove the increase.
Digital investing can win customers quickly because opening an account, moving cash and buying securities no longer requires the same physical distribution network.
The incumbents are nowhere close to disappearing. Non bank firms account for only about 5% of Canada's broker dealer assets. Bank owned broker dealers hold the other 95% of those assets.
The contrast is striking. Challenger activity is changing customer behaviour much faster than it is changing institutional asset share.
A Canadian can now invest through a digital broker, buy an ETF, hold cash inside an investing app and compare financial products without spending much time inside a traditional branch. The banks still own enormous distribution and balance sheet capacity. They no longer own every customer entry point.
Specialty finance has grown quietly beside the banks. Finance companies represent 11.8% of the narrow non bank measure and grew 7.1% in 2024. Statistics Canada includes consumer lending, corporate lending, leasing, mortgage investment corporations and mortgage finance corporations in its non bank credit work.
The official statistics have also expanded over time to capture newer models such as buy now pay later financing.
A mortgage can start outside a bank and still end up inside one. Mortgage finance corporations can originate loans through brokers and then sell them to regulated financial institutions. A borrower may meet a non bank lender first while a bank later funds or owns the mortgage.
Competition and cooperation can exist in the same transaction.
Canadian finance is becoming more distributed without becoming neatly divided into banks on one side and challengers on the other. Origination, funding, servicing, securitization and ownership can happen at different institutions. That makes the system more competitive in places and more interconnected at the same time.
Private credit shows the same Canadian pattern. Non bank loans have supplied about 15% of external funding for Canadian non financial businesses for roughly a decade. Private credit has not rapidly replaced domestic bank lending.
Canadian institutions are still heavily involved. The Bank estimates that private lending by Canadian investors plus Canadian bank lending to private credit funds totalled about C$500 billion around the beginning of 2026, with most of the activity in the United States.
Canadian pensions, insurers and banks know the asset class well. Much of the capital is simply being deployed elsewhere.
That divide is already visible in Canada's C$500 billion private credit exposure. Canadian institutions have substantial capacity to invest in private lending, while Canadian businesses still depend much more heavily on banks and public debt markets.
Payments access is opening to firms that historically could not participate directly. Payments Canada says registered payment service providers can now apply for membership and Real Time Rail participation. Wise, KOHO, Float, Paramount Commerce and Brim were among the first PSP members admitted in 2026.
The Real Time Rail is scheduled to launch in the fourth quarter of 2026 with instant clearing and settlement and support for direct PSP participation.
Financial data is opening too. Canada's consumer driven banking framework makes competition an explicit objective and creates accreditation routes for regulated financial institutions and registered payment firms.
Approved providers will be able to request customer permissioned financial data instead of relying on screen scraping or proprietary bank connections.
The opening of Canada's payments system now extends into consumer driven banking. A challenger with payment access and customer approved data has more room to build a financial relationship without depending on an incumbent for every connection.
In June, OSFI launched a streamlined approvals framework for targeted new entrants. It covers eligible credit unions and firms with technologically innovative or emerging banking models.
OSFI is aiming for a clearer three phase process and a targeted 12 month review after a complete formal application is accepted.
Foreign banks already have a formal route into Canada. OSFI assesses applications for full service and lending branches and recommends eligible applications to the Minister of Finance.
Entry is still tightly supervised. Capital, liquidity, governance, business plans, home country supervision, security and risk management remain part of the approval process.
A firm that qualifies for federal entry can pursue much more than a better financial app. Regulated banking capacity, payment access and customer approved data can put more of the customer relationship inside the challenger itself. The requirements remain demanding, but the route is clearer.
Securities rules are changing at the same time. The Canadian Securities Administrators has expanded the Listed Issuer Financing Exemption, allowed eligible venture issuers to adopt semi annual reporting and introduced other measures intended to reduce financing and disclosure friction.
In July, the CSA said more than 10% of eligible companies had already opted into semi annual reporting and that significant capital had been raised under the expanded exemption.
More financial assets do not automatically create more productivity. A pension portfolio can rise because markets rise. A fund can buy existing securities. Canadian institutions can invest abroad. None of those outcomes guarantees more financing for a Canadian company trying to commercialize technology, buy equipment or scale internationally.
That allocation question runs directly into whether Canada can turn financial access into productive participation.
The C$14 trillion headline makes the productivity problem harder to dismiss. Canada is not short of financial assets. The harder question is whether more of the system can connect viable Canadian businesses with capital on terms that let them invest, grow and compete.
The Bank itself recognizes the upside. Its paper says these non bank firms can foster innovation, increase competition, serve underserved markets and improve financial system efficiency.
The same activities can also carry leverage and transform credit or liquidity in ways that spread stress through funds, dealers and financing markets. More activity outside bank balance sheets can distribute risk while making some connections harder to see.
The Bank's 2026 work on private credit and market based finance reflects that concern without treating every non bank institution as a threat.
As activity spreads across funds, dealers, lenders and platforms, risk travels with it. Credit, liquidity, customer data and operating dependencies become harder to follow when they are shared across more institutions. Regulators have to preserve the benefits of wider competition while keeping those connections visible.
Banks still anchor the system. Their share of total financial system assets barely changed in 2024. They still dominate broker dealer assets, business lending, deposits and many of the funding relationships behind non bank finance.
The starting points are multiplying. Online brokers compete for investors. Specialty lenders compete for borrowers. PSPs can gain direct payment access. Approved providers can compete around financial data. Eligible new entrants can pursue federal regulation through a clearer process.
Canada's banks remain deeply entrenched, but more of the financial activity around them is open to competition. Incumbents keep the scale while challengers gain more ways to reach customers, move money, originate credit, raise capital and, in some cases, become regulated institutions themselves.
Talking Point
Canada already has C$14 trillion of finance outside traditional banks. More firms are now gaining ways to compete for customers, payments, data, credit and regulated entry while the banks remain dominant.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
On September 3, 2026, Nvidia announced a definitive agreement to acquire Hugging Face for US$12.9303 billion. The deal would put one of the biggest platforms for open source and open weight AI alongside the company that already dominates much of the market for AI computing.
The price includes about US$11.9 billion for Hugging Face stockholders and up to US$1 billion in equity awards for employees joining Nvidia. The transaction hasn't closed. Nvidia says it expects completion in the first half of 2027, subject to regulatory approvals and other closing conditions.
Nvidia is making a very public promise with the deal. Hugging Face will remain open. Developers will still be able to choose their models, clouds, inference providers and computing platforms. Nvidia hardware will not be required.
That promise goes directly to the tension. Hugging Face became valuable because developers, startups, researchers and rival chip companies could all build there. Nvidia can make that ecosystem stronger. Ownership can also make some of those same users wonder whether an open source AI platform can feel as independent once one of the most powerful companies in AI owns it.
Hugging Face has grown into one of the main places developers find, share and use open AI models. Nvidia says more than 18 million developers, researchers and creators use the platform, along with more than 200,000 companies.
The company was worth far less only three years ago. Hugging Face raised US$235 million in 2023 at a US$4.5 billion valuation, with investors including Google, Amazon, Nvidia, Intel, AMD, Qualcomm, IBM and Salesforce.
Nvidia is now paying close to three times that valuation. The premium makes more sense when Hugging Face is viewed as distribution, developer access and influence over how open models get discovered and deployed.
Hugging Face is valuable because millions of people already use it to decide what to build with. Nvidia is buying that relationship as much as the software behind it. The more developers stay, the more valuable the acquisition becomes.
Nvidia already has enormous power in AI computing. Reuters Breakingviews says Nvidia holds more than 80% of the AI accelerator market, while its chips have become a reference point for a growing market in GPU rental pricing.
That power is one reason the acquisition attracts attention. Nvidia will own a major open model platform while selling the hardware many of those models run on.
Hugging Face has also become important to Nvidia's competitors. Its own 2026 data says AMD and Nvidia are the two most active publishers of new open models on the Hub, with each releasing more than 200 model repositories this year.
AMD uses open models to prove its chips can run real workloads. Google, Microsoft, IBM and other companies also publish and distribute models through the platform.
The acquisition does not remove AMD, Google or other hardware and cloud providers from Hugging Face. Nvidia says support for rival silicon will continue. The tension comes from whether those companies remain just as comfortable investing there when the owner also competes with them.
Nvidia says rival chips will stay welcome. Nvidia's CEO Jensen Huang says developers will keep choosing their own models, frameworks, clouds, inference providers and computing platforms. Nvidia compute will not be required to build on or deploy through Hugging Face.
Developers are already debating what ownership could mean in practice. Some community reactions welcome Nvidia because open models create demand for compute. Others worry about future defaults, private repositories, hardware preference and whether another independent open source AI platform will eventually be needed.
Nvidia doesn't have to close Hugging Face for ownership to change how the platform feels. Developers will notice which hardware gets optimized first, which services are easiest to connect and whether rival products remain equally visible and easy to use.
Open models fit Nvidia's economics surprisingly well. Hugging Face says hardware vendors are publishing open models because a model optimized for their chips is one of the clearest ways to prove the hardware works.
Nvidia can therefore benefit even when the model itself is free to download. More open model use can create more inference and training demand across data centres, enterprises and local machines.
That dependence cuts both ways. Some of Nvidia's biggest customers, including hyperscalers and AI labs, are building their own chips. The Hugging Face deal gives Nvidia a wider developer base at a time when those customers are trying to reduce their own dependence on Nvidia hardware.
Open source AI gives Nvidia access to thousands of smaller users instead of relying only on a few giant buyers.
Nvidia can support open source AI and still benefit commercially from its growth. The company does not need every developer to buy a proprietary Nvidia model. It benefits when more models create more computing demand.
China is pushing hard in the same open model market. Hugging Face data shows Chinese labs released many of the largest open models in 2026. Qwen has become one of the most important model families on the Hub, with more than 151,000 derivative repositories.
Hugging Face says Qwen based models reached more than 2 billion downloads across repositories with declared parameter counts this year.
Chinese open models are also competing on access and cost. Hugging Face found that 59% of Chinese releases above 20 billion parameters used Apache 2.0 licences and another 22% used MIT licences during the period it studied, although some very large releases have begun adding commercial restrictions.
That gives developers another source of capable models as U.S. companies debate how open their own ecosystems should remain.
Open models are part of the technology rivalry between the United States and China. Nvidia's Hugging Face acquisition gives a U.S. company more influence over a global platform at the same time Chinese model families are winning large developer communities of their own.
One possible response to Nvidia ownership is that developers simply stay. Hugging Face already has millions of models, datasets, applications and established workflows. Rebuilding that network somewhere else would be difficult.
Microsoft's GitHub acquisition offers one useful precedent. Microsoft promised GitHub would stay open and independent, and competing developers and platforms continued using it after the acquisition.
Another possibility is that developers begin spreading their work across more places. ModelScope, GitHub, local model tools, cloud registries and private enterprise repositories already give users alternatives for parts of the Hugging Face experience.
A future competitor would not need to copy every Hugging Face feature on day one. It could win users by offering easier migration, open governance, strong model provenance or a clearer commitment to hardware independence.
Network effects make a full replacement difficult, but communities can fragment before platforms collapse. Developers can keep models on Hugging Face while using other tools for discovery, inference, deployment or discussion. Competition may arrive piece by piece rather than through one new platform.
No price increase has been announced. Nvidia says Hugging Face will remain open and hardware choice will continue. That leaves plenty of room for the acquisition to improve reliability, inference tools and enterprise deployment without raising basic access costs.
Costs could still change indirectly. Developers may pay more if the easiest experience ends up depending on premium services, Nvidia optimized infrastructure or harder to replace integrations. The opposite is also possible. Better tooling and stronger open models could lower the cost of running AI compared with closed model APIs.
The acquisition does not automatically mean higher prices. The more interesting cost risk is switching. A service can remain affordable while becoming expensive to leave because models, workflows, integrations and teams are built around it.
Startups could gain from Nvidia's reach. A stronger Hugging Face can give model companies better distribution, more reliable infrastructure and easier access to enterprise customers.
For founders trying to get an open model discovered, being close to a platform used by 18 million developers can be commercially powerful.
Startups may also have less bargaining power if distribution, compute and enterprise access become more concentrated around the same company. A startup can benefit from the platform while still wanting credible ways to deploy elsewhere.
That tension is already visible in competition for cheaper AI inference, where AMD and other hardware companies are trying to give developers alternatives to Nvidia's dominant GPU position.
The upside is distribution. The risk is dependence. Founders will care less about who owns Hugging Face than whether they can still take their models, customers and economics somewhere else when they need to.
Financial institutions face the same ownership question from a different angle. Banks and insurers are already putting AI into governed workflows where data controls, approvals, audit evidence and operational resilience are required.
Governed financial AI workflows become harder when a firm cannot easily change models, clouds or providers without rebuilding controls around them.
Portability can therefore matter more than ownership alone. A bank may be comfortable using Hugging Face under Nvidia if models can still travel across clouds and chips and the institution can keep its own data, controls and audit evidence.
Regulators are also paying more attention to AI vendor concentration and operational dependence as financial firms embed more external technology into critical work.
Financial institutions do not need every AI supplier to be independent. They do need credible ways to change suppliers, hardware and deployment environments without losing control of regulated workflows.
The deal could still produce a strong outcome for open source AI. Nvidia has the engineering resources, compute and enterprise distribution to make Hugging Face faster, more reliable and easier for companies to use.
If AMD, Google, cloud providers, Chinese model labs and independent developers keep contributing, Nvidia can own the platform while the ecosystem remains genuinely competitive.
The harder outcome is quieter. Hugging Face stays open, but developers gradually find Nvidia products easier, cheaper or better supported than alternatives. No door closes. Choice simply becomes less balanced over time.
That is why Nvidia's promise will be judged through product behaviour rather than the announcement itself.
The most valuable version of Hugging Face may be one where Nvidia owns it and its competitors still want to build there. If that happens, Nvidia gets a larger open source AI ecosystem without destroying the trust that made the platform worth almost US$13 billion.
Talking Point
Nvidia does not need to close Hugging Face to gain more influence over open source AI. The deal becomes more valuable if developers, startups and rival chipmakers keep using the platform anyway.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 3, 2026 | NCFA Market Activity | Digital Banking And BaaS, Regulation And Policy, Payments Infrastructure And Money Movement
On September 3, 2026, Revolut received conditional U.S. bank approval from the Office of the Comptroller of the Currency form Revolut Bank US, N.A., a federally chartered national bank headquartered in Stamford, Connecticut. Revolut says it is still working through FDIC, Federal Reserve and final OCC approvals and remains on track for a 2027 launch. U.S. customers cannot open accounts with Revolut Bank US yet.
Revolut already serves U.S. customers, but the regulated banking are with other institutions. Lead Bank supports Revolut's prepaid card accounts and banking services, while Savings Vault funds are held at Cross River Bank. Revolut controls the app and customer experience, but those partner banks hold deposits and perform key regulated functions.
Revolut says the proposed bank would offer loans, credit cards and FDIC insured deposits, alongside access to stablecoins and cryptocurrencies. Its charter application also describes deposits, savings, business credit, payments, remittances and foreign exchange. Some investment and digital asset services could still sit with affiliates or outside providers rather than inside the bank itself.
Revolut has been working toward this for months. It dropped plans to buy a U.S. bank earlier this year and chose to apply for a new national bank instead. The OCC received the Revolut Bank US application on March 4. Conditional approval six months later gets the company much closer to owning the bank behind its U.S. app.
Today, Revolut can build the app, price subscriptions and design much of the customer experience, but it still depends on banks such as Lead Bank and Cross River Bank for core banking functions. That arrangement helped Revolut enter the U.S. without taking on the full cost of becoming a bank, but it also means product changes, deposit economics and parts of the customer relationship depend on outside institutions.
With its own bank, Revolut could keep more of that customer relationship inside the company. Deposits could sit at Revolut Bank US, lending income could stay within the group and the company could build products without asking a partner bank to support every change. Revolut also says direct access to payment networks such as Fedwire and ACH could make transfers faster and cheaper.
The economics become more interesting at Revolut's current size. Its 2025 financial results included US$6.0 billion in revenue, US$1.7 billion in net profit, US$67.5 billion in customer balances and a US$2.9 billion lending portfolio. Revolut now serves more than 80 million customers worldwide and is adding roughly one million customers every 17 days.
The U.S. opportunity is still much less developed than Revolut's business in Europe and some other markets. A bank charter gives the company a chance to compete for deposits, credit and primary banking relationships rather than mainly offering an app connected to somebody else's bank. Revolut has also committed to invest US$500 million in the U.S. over the next few years as it builds the products and operations around that effort.
Conditional OCC approval is a major regulatory step, but it is not permission to open the bank tomorrow. Revolut still needs FDIC approval for deposit insurance, Federal Reserve approvals for its U.S. holding structure and final OCC clearance. The company also has to finish staffing, capitalization, technology, compliance and operational testing before customers can be moved onto the new bank.
Owning a bank also changes the risk Revolut takes on. A partner bank carries much of the regulated balance sheet today. Revolut Bank US would have to manage its own capital, liquidity, credit losses, consumer compliance, BSA and AML controls, cybersecurity, governance and federal examinations.
Lending makes that especially real. A payments app can process money without taking the same credit risk as a bank making personal or business loans. Once Revolut starts lending from its own balance sheet, growth has to be backed by sound underwriting, reserves, collections and enough capital to absorb losses when borrowers struggle.
The company is already building that structure though. Its application calls for a separate U.S. bank board and senior executives responsible for finance, risk, compliance, legal, lending and operations. Revolut says it remains on track for 2027, but the launch date still depends on regulators being satisfied that the bank is ready to operate safely.
Revolut's first Canadian attempt ended very differently. The company launched a limited beta in 2019 and left Canada in 2021 without establishing a domestic bank. The earlier product was much narrower than the banking business Revolut now operates in several markets.
Jan Pilbauer now leads Revolut Canada, and Revolut has described the market as attractive, but there is still no announced launch date or public Canadian bank licence application. A U.S. national bank charter certainly doesn't give Revolut permission to take deposits or operate a bank in Canada.
If Revolut does return, it would arrive as a much larger and more regulated company than the one that left five years ago. It now operates licensed banks in multiple countries, carries a growing lending book and is building local banking operations rather than relying only on cards and foreign exchange. Canada has also changed, with OSFI's streamlined approvals framework giving eligible new entrants a clearer federal application process.
None of that means a Canadian relaunch is close. It does mean the next attempt, if it happens, could look much more like a full digital bank than the limited product Revolut tested here before.
Revolut is now trying to do something large fintechs often avoid for as long as they can it seems. That is to own a regulated bank, the deposits, the lending and more of the customer economics. That can produce more revenue and more control, but it also means the compliance failures, credit losses and funding mistakes belong to Revolut too.
How much more can Revolut earn when it owns the bank behind the app?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 3, 2026 | NCFA Market Interest | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Wealth Investing And Trading
Kraken parent Payward has reportedly delayed its U.S. IPO again, this time to the second quarter of 2027 at the earliest. The company confidentially filed a draft registration statement in November 2025, then put the listing on hold in March as crypto prices, trading volumes and valuations weakened. Payward hasn't confirmed the new 2027 timing, so it remains a reported window rather than a scheduled IPO date.
The delay comes at an interesting point for the business. Payward reported US$508 million in Q2 adjusted revenue, up 17% year over year. Funded accounts rose 42% to 6.6 million, while assets on the platform were US$40 billion. Adjusted EBITDA was much thinner at US$23 million, and total platform transaction volume fell 18% to US$310 billion as crypto spot trading cooled.
Those numbers give Payward a pretty clear reason to wait. Revenue and customers are growing, but the company is still proving how much earnings it can generate when trading activity softens. Going public now would put that question in front of investors every quarter.
Kraken is still central to Payward, but the parent company now earns money from more than crypto spot trades. Asset based and other revenue accounted for 60% of adjusted revenue in Q2, up from 55% a year earlier. Payward also owns NinjaTrader, has added regulated U.S. derivatives through Bitnomial, and expanded into payments and card issuing through Reap.
Those businesses and revenue lines are important when trading slows. Payward's transaction volume fell 18% year over year, yet adjusted revenue still rose 17%. That doesn't make the company immune to crypto cycles, but it does show that the revenue mix is changing.
The acquisitions have also made Payward more complicated. Investors eventually have to decide whether futures, derivatives, payments, tokenized equities and infrastructure services add up to a stronger financial business or simply a larger collection of products. Staying private gives management more time to answer that with operating results.
Payward's recent transactions have valued its equity at about US$20 billion. The company also says it closed an US$800 million private funding round backed by investors including Citadel Securities, Jane Street, Oppenheimer and Tribe Capital.
The capital gives Payward capital and time, but the valuation also raises expectations for an eventual IPO. Public investors will want to see more than account growth. They will be looking at earnings, cash generation, trading volumes and whether the businesses Payward has bought can produce dependable revenue together.
The current quarter gives them both sides of the argument. A record 6.6 million funded accounts and 17% revenue growth are strong. US$23 million of adjusted EBITDA on US$508 million of adjusted revenue leaves much more room to prove that scale can turn into profit.
Payward's xStocks business is expanding beyond Kraken. xStocks distribution already reaches third party exchanges, wallets and blockchain applications, and Payward now says the products have passed US$40 billion in total volume, including more than US$20 billion settled onchain, across more than 200,000 holders.
The company took another step on September 1 when LSEG and Payward announced plans to explore tokenized UK public equities. Subject to regulatory approval, the London Stock Exchange intends to list xStocks on its planned LSE 24 venue in 2027.
If everything takes, that would put Payward beside a traditional exchange operator at the same time its own IPO waits. It is a good example of how far the company has travelled from being known mainly as a crypto exchange.
The biggest question is earnings. Payward can keep adding accounts and products, but public investors will want to see whether those businesses can produce stronger profits when crypto trading is weak. Q2 showed that revenue can keep growing while transaction volume falls. The next step is showing that more of that revenue reaches the bottom line.
The acquisitions also have to work together. NinjaTrader brings traditional futures clients. Bitnomial adds regulated U.S. derivatives. Reap adds payments and card issuing. xStocks adds tokenized equities. Payward Services sells some of the same technology to banks, fintechs and other platforms. If customers start using several of those products together, the company can earn more from each relationship without depending as heavily on one trading market.
Payward Canada is registered as a restricted dealer, giving Kraken regulated access across Canada. xStocks are still unavailable to Canadian retail clients, so Payward's wider product expansion won't automatically arrive here. Canadian access will depend on what regulators approve and which products the company decides to bring north.
Payward has private capital, growing accounts and several businesses still being integrated. It doesn't have to accept a public valuation today if management believes another year of results can support a better one.
There is risk in waiting too. Crypto markets can weaken further, acquisitions can disappoint and the IPO market may not improve on Payward's schedule. A private US$20 billion valuation is only as strong as the earnings and growth the company can eventually show public investors.
Kraken's IPO delay is therefore more than a calendar change. Payward is using the extra time to prove that it can grow into a larger financial platform, make its acquisitions pay off and earn enough outside crypto spot trading to support the valuation it wants when it finally lists.
Can Payward turn product growth into enough profit to support a US$20 billion public valuation?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
On September 3, 2026, Canada's July trade report put two stories beside each other. Exports to the United States fell 6.6%, while exports to countries outside the U.S. rose 7.4% to a record C$25.6 billion. Canada's merchandise trade surplus with the world narrowed from C$4.2 billion in June to C$769 million. Its surplus with the United States fell from C$10.3 billion to C$5.9 billion.
Those numbers now sit inside a much rougher political relationship. On August 22, the United States imposed a 50% tariff on roughly US$20 billion of Canadian exports, while the Government of Canada values the affected goods at C$27.6 billion. Canada has rejected the terms on offer and announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
Canada is still deeply tied to the U.S. economy, but the reaction is no longer confined to government. Buy Canadian sentiment has returned. Companies are reviewing suppliers and customers. Travel choices have changed. More Canadian businesses are looking beyond the U.S. at the same time that Ottawa is asking them to absorb the cost of doing it.
The question running through this story is whether the tariff fight is merely disrupting Canada U.S. trade or helping create commercial relationships that remain different even after the politics cool.
The evolving trade war began with a border argument. Washington said Canada was not doing enough on fentanyl and border security. Ottawa said the scale of the problem did not justify an economy wide tariff and answered with retaliation rather than concession.
Ottawa disputed the premise while tightening the border anyway. Canada argued that the U.S. was imposing an economic penalty far larger than the border problem it cited. At the same time, Ottawa strengthened enforcement, giving the fight an early contradiction that never really disappeared.
North America already has a trade agreement designed to make cross border commerce predictable. The surprise is not that Canada and the U.S. disagree. It is that the disagreement can still produce sweeping tariffs while CUSMA remains in force.
CUSMA then became the shield Canadian companies hoped it would be. A large share of continental trade kept moving under the agreement, offering businesses a degree of protection from the broad tariff threat.
The most politically sensitive sectors did not get the same protection. Steel, aluminum and autos became proof that a trade agreement could survive while the industries most tied to jobs, factories and regional politics still took direct hits.
CUSMA remains in place, but businesses now know that compliance with the agreement does not eliminate every tariff risk. A company can remain inside the North American trade framework and still be exposed to a separate sector fight.
Canada entered the 2026 CUSMA review looking for certainty and left without it. Ottawa wanted companies to know the North American rules would hold for another generation of investment. The review did not deliver that reassurance.
The United States did not give Canada the long runway it wanted. The agreement stayed alive, but companies making plant, supplier and capital decisions measured in years were left with a shorter political horizon.
The agreement remains in force. But the failed long term extension means companies can no longer assume the relationship will simply return to the old operating model after one review.
Then the tariff ceiling moved again. After bilateral talks failed, Washington raised the pressure to levels that made another Canadian response almost unavoidable. The dispute was no longer about whether tariffs would remain. It was about how much economic pain each side was willing to absorb.
Canada chose retaliation over the deal on the table. Ottawa said the U.S. terms would leave Canadian workers and businesses worse off. Canada announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
This is where the fight stops looking like a temporary tariff negotiation and starts looking like a choice about economic autonomy. Canada is accepting the risk of another round of costs rather than take terms Ottawa says would leave important industries worse off.
Trump then turned Lake Ontario into part of the dispute. The Lake America order gave Canadians something more visceral than a tariff table to react to. A fight over market access suddenly had a symbol that touched geography, identity and sovereignty.
The symbolism hit a country already primed to push back. The tariff fight had been accompanied by statehood rhetoric and repeated claims that Canada depended too heavily on the United States. The lake renaming made the argument feel less like a dispute over customs schedules and more like a challenge to Canadian identity.
A tariff can feel remote until it affects a price, a contract or a job. Renaming a shared Canadian lake for U.S. federal purposes created a cultural symbol that was easier to understand and harder to separate from the wider sovereignty argument.
Canadian resistance is showing up in everyday choices. Buy Canadian sentiment has strengthened as consumers reconsider groceries, travel, technology, vehicles and other purchases. Businesses are also reviewing where they source products and whether U.S. dependence still looks commercially sensible.
American opinion is much less supportive of the escalation. A Reuters Ipsos poll found 57% of Americans opposed the latest tariffs on Canada and only 20% supported them. The same poll found 63% opposed Lake America and 14% supported it.
Canadian patriotism has many sources, so the tariffs should not be treated as the sole cause. But the observable response to repeated tariff threats, statehood rhetoric and Lake America includes stronger Buy Canadian behaviour, support for retaliation and a more explicit case for economic self reliance.
Some companies are acting on the anger instead of waiting it out. Reuters reported that Chapman's Ice Cream plans to cut U.S. imports by 70% by mid 2027. Other firms are reviewing suppliers, sourcing more at home and looking for customers outside the United States.
Once a supplier is replaced, politics may not put the old relationship back together. New contracts, certifications, logistics routes and internal processes create switching costs. A future agreement could remove a tariff quickly while leaving behind commercial relationships built during the dispute.
This is where a patriotic reaction can become structural economic change. The first purchase may be emotional. The lasting effect depends on whether Canadian and non U.S. alternatives become good enough to keep the customer or supplier relationship after the anger fades.
The July numbers show Canada really is looking elsewhere. Exports outside the United States rose 7.4% to a record C$25.6 billion. Non U.S. destinations accounted for roughly one third of Canadian merchandise exports in July.
America is still too large to replace quickly. Canada's trade surplus with the U.S. fell to C$5.9 billion in July, while Canada ran a C$5.1 billion deficit with countries outside the U.S. More trade elsewhere reduces concentration before it replaces the commercial value of the American market.
The record non U.S. export figure shows diversification was already underway before the August 22 escalation. It does not prove the newest tariffs caused the change. It does show Canada was already finding more business outside the U.S., even while the American market remained too large to replace quickly.
Every new route creates another bill before it creates resilience. New buyers can require longer shipping, different payment terms, more foreign exchange and more working capital. New suppliers can require deposits, inventory changes and fresh credit checks. The cost arrives before the exporter knows whether the new relationship can match the economics of the old one.
Canada can become less exposed to one market while making individual companies more complicated to finance. Diversification works only if firms have enough liquidity to survive the period between leaving an old relationship and making a new one profitable.
Lenders now have to see tariff risk before the financial statements do. U.S. customer concentration, tariff sensitive inputs, margin exposure and the time needed to replace a buyer can change a borrower's risk within weeks. Historical revenue can therefore look healthy while the economics underneath it are already deteriorating.
Payments, foreign exchange and treasury providers face the opposite problem. More destinations create more currencies, settlement routes, counterparties and cash timing issues. The same diversification that reduces geographic concentration can increase demand for cross border payments, hedging, trade finance, receivables tools and working capital.
Trade policy becomes financial services work once companies start changing customers and suppliers. Credit has to recognize new exposure sooner. Payments have to reach more markets. Treasury teams have to manage more currencies. Working capital has to cover the period before new trade relationships mature.
Markets still assume some of this confrontation eventually fades. Currency forecasts are already looking past the current hostility and pricing a calmer relationship later. Businesses have less freedom to wait for that version of the future.
Businesses cannot wait for that forecast to come true. Carney said on September 1 that the United States must start being serious before talks can resume. At that point no new bilateral negotiations were scheduled. A company choosing a supplier, market or plant location has to make the decision under today's rules.
That is the deeper consequence of the dispute. Governments can reverse tariffs quickly. Companies that have spent months replacing suppliers, winning customers and building payment routes may have less reason to go back. The tariff war could therefore leave a commercial footprint that lasts longer than the tariffs themselves.
Talking Point
Trump's tariff campaign has done more than raise the cost of Canada U.S. trade. It has turned economic dependence into a Canadian political issue, revived Buy Canadian behaviour and pushed companies to look harder for customers and suppliers elsewhere. The unresolved question is whether that response leaves Canada with stronger companies and more durable trade relationships or simply a more expensive way to do business.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 3, 2026
A credit card payment at an online casino costs the operator between 2.5% and 5% in processing fees, takes one to three days to settle, and carries a chargeback risk that averages 0.8% to 1.2% of total transaction volume. A USDC transfer on Solana or Base costs less than $0.01, settles in under three minutes, and cannot be reversed once confirmed on chain. For fintech professionals watching how stablecoin infrastructure performs under real production stress, online casinos have quietly become one of the most revealing test environments in payments.
This is not a story about which casino accepts crypto. It is a story about why the payment rails built under pressure from hostile acquirers are now structurally superior to legacy alternatives, and what that means for broader fintech infrastructure.
Online casinos operate under merchant category code 7995, one of the most restricted classifications in card network underwriting. Most tier-one payment processors refuse to onboard iGaming merchants entirely. Those that do charge premiums well above standard interchange rates, often landing between 3% and 5% per transaction.
The structural challenges compound from there. Chargeback rates in iGaming regularly exceed the thresholds set by Visa and Mastercard, triggering remediation programs that can end in merchant termination. Players expect withdrawals within minutes, yet ACH settlement runs on T+1 to T+3 timelines, and SWIFT transfers take three to five business days. The gap between player expectations and banking infrastructure creates friction at every point in the payment lifecycle.
These pressures created a forcing function. Operators that wanted to scale needed payment rails capable of high velocity cross-border flows, instant finality, reduced credit risk, and independence from acquirer gatekeeping. Stablecoin rails, particularly USDC, addressed all four requirements simultaneously.
When a player requests a withdrawal at a stablecoin casino, the transaction never touches an acquiring bank, a card network, or a correspondent banking chain. It travels on chain.
The operator's treasury system holds a liquid float in a hot wallet, sized to cover 24 to 48 hours of rolling withdrawal demand. The player's withdrawal request triggers a signed transaction broadcast to the blockchain. On Base or Solana, confirmation arrives in seconds with cryptographic finality. There is no authorization hold, no batch settlement window, and no reversal mechanism.
Chain selection matters at scale. ERC-20 USDC on Ethereum carries gas fees of $0.50 to $2.00 per transaction depending on network congestion. Solana reduces that below $0.001. Base sits below $0.01. For an operator processing 50,000 withdrawals per month, the choice of chain alone becomes a six-figure annual decision.
According to Circle, USDC has settled more than $70 trillion in cumulative on-chain transactions across institutional, B2B, and consumer use cases. This is production-scale infrastructure running across financial services, payments, and iGaming.
A direct comparison makes the economic case clearer than any narrative.
| Payment Rail | Settlement Time | Operator Fee | Volatility Exposure | Chargeback Risk |
| Credit Card | 1 to 3 days | 2.5% to 5%+ (iGaming premium) | None | High (MCC 7995) |
| Bank Wire (SWIFT) | 3 to 5 business days | $25 to $65 flat + FX spread | FX exposure | Low |
| Bitcoin (BTC) | 10 to 60 minutes | $1 to $30 variable | High | None |
| USDC (Base/Solana) | Under 3 minutes | Below $0.01 per transaction | None | None |
For an operator processing $10 million per month on card rails at a blended 3% iGaming rate, shifting to USDC represents roughly $300,000 in annual fee savings before accounting for chargeback losses.
Bitcoin is not a viable substitute at scale. Price volatility means any operator holding BTC in treasury carries mark-to-market risk on the liability side. A 10% price decline on a $1 million player balance creates an immediate $100,000 accounting gap. USDC, pegged 1:1 to USD and redeemable through Circle Mint, carries no equivalent risk. The liability stack stays USD-denominated throughout.
Platforms already running on these rails demonstrate the production reality. A live USDC casino operating at scale today faces none of the acquirer relationship risk, chargeback remediation exposure, or cross-border correspondent banking friction that card-dependent operators manage as ongoing cost centers.
In Canada, FINTRAC requires operators handling virtual assets, including stablecoins, to register as virtual asset service providers. This registration carries obligations for Travel Rule compliance at the transaction level and ongoing AML monitoring programs.
The regulatory trajectory is converging across jurisdictions. Canada's VASP framework, the EU's MiCA regulation, and emerging US stablecoin legislation all emphasize disclosure, reserve attestation, and Travel Rule compliance. USDC's monthly reserve attestation model, published by an independent accounting firm, already satisfies the transparency requirements taking shape in all three regulatory environments.
Operators building on Circle's infrastructure can inherit compliance controls directly. Circle's Payments Network includes built-in OFAC screening, Travel Rule messaging support, and AML monitoring capabilities. This reduces the compliance engineering burden materially compared to building a custom integration from scratch.
For Canadian fintech professionals, the key milestone to watch is FINTRAC's expected expansion of VASP reporting thresholds to cover stablecoin-specific transaction patterns. Operators and payment processors building on USDC rails now will have a compliance architecture head start when those requirements arrive.
On-chain settlement introduces a transparency layer that legacy payment infrastructure cannot replicate. Every deposit, withdrawal, and balance change is recorded on an immutable public ledger, creating a continuous audit trail without reliance on third-party attestation.
In iGaming, this connects directly to the concept of provable fairness. Understanding what is RTP in slots has traditionally required trust in third-party testing labs that certify return-to-player percentages. On-chain settlement opens the door to cryptographically verifiable RTP calculations, where players and regulators can independently confirm that game outcomes match published odds. This shift from trust-based to verification-based fairness represents a meaningful evolution for both player protection and regulatory oversight.
Programmability adds further capabilities that card rails cannot match. Smart contract-based bonus logic, automated affiliate settlement, and on-chain provable fairness are native to blockchain infrastructure. None require a third-party processor, a settlement delay, or a revenue-share arrangement with a payments intermediary.
The shift away from card rails in iGaming is structural, not cyclical. Card networks retain the unilateral right to remove a merchant category from acquirer eligibility without notice. That existential counterparty risk has no analog in stablecoin settlement, where the protocol itself has no commercial relationship with the merchant.
The cross-border advantage is equally concrete. USDC is natively issued across 37 blockchains and available in over 185 countries. Sending USD from Canada to a licensed offshore operator through a correspondent banking chain costs $30 to $60 per transfer and takes three to five business days. A USDC transfer costs less than a cent and settles in under a minute.
The onboarding friction for USDC is real: players still need a non-custodial wallet or an account on a centralized exchange. That friction is the primary reason card rails coexist in hybrid operator stacks. But for operators targeting experienced crypto users, the economics are unambiguous. And as wallet infrastructure improves, that friction is shrinking quarter by quarter.
A stablecoin casino is an online casino that accepts and settles player balances in USD-pegged stablecoins like USDC or USDT rather than fiat currencies or volatile cryptocurrencies. Operators use stablecoin rails to achieve near-instant withdrawals, eliminate chargeback exposure, and reduce payment processing fees to fractions of a cent per transaction.
On low-fee chains like Base or Solana, on-chain confirmation occurs in seconds with cryptographic finality. This compares to bank wire settlement of three to five business days and card processing of one to three days. The speed is structural, built into the protocol's confirmation mechanics, rather than dependent on processor batch windows or banking hours.
Licensed online gambling operates under provincial regulatory frameworks in Canada. Platforms handling virtual assets, including stablecoins, must comply with FINTRAC's VASP registration requirements, implement Travel Rule compliance, and maintain AML monitoring programs. Players should verify that their chosen platform holds valid licensing and is registered under the applicable VASP framework.
USDC is redeemable 1:1 for USD through Circle Mint at all times. Operator treasuries holding USDC carry no BTC or ETH price risk. The entire liability stack is USD-denominated, which means accounting, regulatory capital calculations, and player balance reconciliation all operate in the same fiat reference currency. This is a fundamental structural difference from Bitcoin or Ethereum reserves, where a price move creates an immediate liability gap.
Both are USD-pegged stablecoins, but they differ on compliance transparency and regulatory alignment. USDC, issued by Circle, publishes monthly reserve attestations from an independent accounting firm and is natively issued on 37 blockchains. USDT, issued by Tether, carries higher consumer adoption but provides fewer issuer-level compliance disclosures. For operators building compliance-forward stacks, USDC's attestation model aligns more directly with the disclosure requirements emerging under MiCA, FINTRAC, and US stablecoin legislation.
Online casinos did not adopt stablecoin rails out of ideological alignment with decentralized finance. They adopted them because card acquirers either refused to underwrite MCC 7995 or charged rates that made the business model unworkable.
The infrastructure built under that pressure is now the same infrastructure payment professionals are deploying for remittances, B2B settlement, and embedded finance. Near-zero fees, instant finality, zero chargeback exposure, and a USD-denominated treasury that requires no foreign exchange management: these properties are not specific to gambling. They represent the core value proposition of stablecoin payment rails in any high-volume, cross-border merchant category. The proving ground is already running at scale.
Circle - USDC Overview: https://www.circle.com/usdc
FINTRAC - Crypto Asset Guidance: https://www.fintrac-canafe.gc.ca/re-ed/crypto-eng
Wild.io USDC Casino: https://wild.io/casino/usdc-casino
Wild.io RTP Guide: https://wild.io/academy/articles/what-is-rtp
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
