




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


November 11, 2026 | NCFA Story Intelligence | Competition And Market Structure, Wealthtech Investing And Trading, Regulation And Policy

On November 7, 2026, the federal government proposed something Canadian investors have complained about for years. Banks would no longer be allowed to charge most investment account transfer fees, which typically cost about $150 per account. Ottawa also wants clearer transfer information and tighter timelines for moving investments to another financial institution.
The fee matters because leaving can already be slow and frustrating. Receiving firms often reimburse the outgoing charge to win the account. That means a fee collected by the institution losing the customer can become part of the acquisition cost for the institution trying to win that customer.
Canada's six largest banks hold roughly 93% of banking assets. The Competition Bureau was warning about barriers facing fintech competitors in 2017. Ottawa began reviewing open banking in 2018. A federal advisory committee later recommended an operating system by January 2023 and warned that government should not delay.
January 2023 came and went.
Real Time Rail also slipped years beyond its first expected launch. Meanwhile, Canada's productivity performance kept falling behind major peers. In 2024, the Bank of Canada called the problem an emergency. By 2025, Senior Deputy Governor Carolyn Rogers was directly connecting productivity, competition and Canada's highly concentrated banking sector. She also said the debate had become more urgent after U.S. trade policy delivered a major economic shock to Canada.
Then more barriers started coming down.
Payment companies came under supervision. Payments Canada opened membership to more firms. Consumer driven banking advanced. NSF fees were capped. Real Time Rail finally launched. Budget 2026 targeted bank entry, ownership and regulatory competition. Now Ottawa wants to make investment accounts cheaper and faster to leave.
The $150 exit fee is the latest part of a much longer story about how difficult Canada has made it for customers to switch and for competitors to win them.
Canada had already been debating these barriers for years. In 2017, the Competition Bureau called for stronger competition and innovation in financial services. NCFA agreed that regulatory burdens could favour large incumbents and pointed to the UK's more aggressive support for fintech and new competitors.
Customers faced their own friction. Bundled products, recurring payments, transfer charges, branch relationships and the hassle of changing providers all made staying easier than leaving. In a concentrated market, those small frictions can add up to a powerful advantage.
Ottawa launched the open banking review in 2018 while Canadians were already connecting outside apps to bank accounts through screen scraping. Privacy, security, liability and technical standards required real work, but the January 2023 target still passed without an operating system.
Interac was selected as the RTR exchange provider in 2021 when launch was expected in 2022. The rail did not reach production until November 2026, leaving Canadian firms to build around older settlement infrastructure for several more years.
In March 2024, Bank of Canada Senior Deputy Governor Carolyn Rogers said Canada's productivity problem had reached emergency status. Canada was producing far less output per hour than the United States and had lost relative ground against major peers over several decades.
By October 2025, Rogers was talking directly about competition. She pointed to Canada's concentrated banking market, said stronger competitive pressure can improve productivity and warned that new U.S. trade policies had made the need to perform better at home more urgent.
Bank of Canada supervision of payment service providers began on September 8, 2025. Expanded Payments Canada eligibility followed later that month. By October 2026, 22 new members had joined after access opened, including fintechs, payment companies and credit unions that couldn't qualify under the old rules.
Consumer driven banking advanced through 2026 while new open banking rules started turning accreditation, consent, security and data access into practical requirements. On November 9, Real Time Rail went live after years of delay.
Federal rules cut NSF fees to a maximum of $10 on March 12, 2026. Typical charges had been about $45 to $48. The rules also block repeat NSF charges within two business days on the same personal deposit account and prohibit the fee when the shortfall is under $10.
By November, Budget 2026 widened the competition push with proposals covering faster bank entry, a secondary competition objective for OSFI, ownership rules, credit union funding and customer switching.
Finance Canada estimates about 17,000 transfers would be covered in the first year of its model. It assumes no increase in transfer volumes because there isn't enough evidence yet to know how customers or institutions will respond once the barrier is removed.
Banks could also respond by improving offers to keep customers. Easier switching doesn't require everyone to leave to create pressure. The possibility of leaving more easily can give the customer more leverage before the account ever goes anywhere.
The recent changes reach almost every part of the customer relationship. Some open the system to more competitors. Others lower fees, make switching easier or give customers more control over their money and data.
Canada is now changing who can enter, who can reach payment infrastructure, who can use customer data, what institutions can charge, how quickly money can travel and how easily a customer can leave.
For years, these problems could be treated as separate files. Open banking sat in one department. Payments modernization sat somewhere else. Banking fees were a consumer issue. Productivity was an economic problem. Competition had its own consultations.
They are harder to separate now.
Canada needs firms to invest faster, grow further and compete in a tougher economy. A financial system that makes entry, customer acquisition and switching more expensive than they need to be works against that goal.
The country knew about many of these barriers years ago. What has changed is how many of them are finally coming down at the same time.
Canada's recent competition reforms aren't about handing fintechs or challenger banks an advantage. They're about removing advantages that can protect an incumbent relationship before price, service, product quality or trust gets a chance to decide who wins the customer.
The results should become visible. Transfers should get faster if the rules work. Receiving firms should spend less reimbursing exit fees. New payment participants should be able to offer services they couldn't offer before. Incumbents may respond with better prices, products and service.
The bigger question is whether all of that produces the competitive pressure Canada has been missing.
Canada knew about many of these competition and productivity problems years ago. Why did it take this long for so many financial barriers to come under pressure at once?
Share this story → Explore related intelligence → Subscribe
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Nov 10, 2026
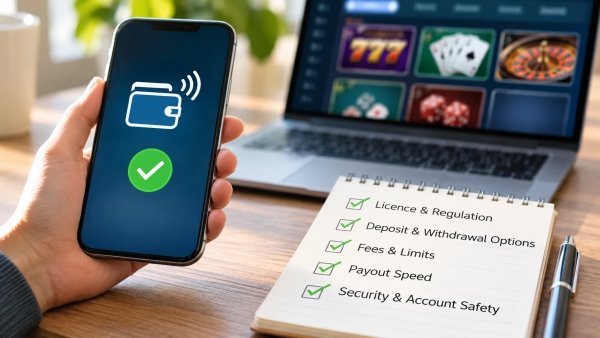
Paying with your phone has become second nature for most Canadians, whether you're grabbing a double-double or splitting a dinner bill. So it makes sense that more players want to fund their casino accounts the same way. If you've been browsing Google Pay Casinos Canada, you've probably noticed that not every site handles this wallet equally well. Some make deposits feel effortless, while others bury Google Pay behind extra steps or fees. Here's how we'd go about picking a good one.
Before you sign up anywhere, it helps to know what separates a smooth Google Pay experience from a frustrating one. We look at a few key areas every time we test a site.
No payment method can make an unsafe casino safe. Check the footer of the site for a licence from a recognized regulator. If you're in Ontario, look for iGaming Ontario and AGCO approval. Elsewhere in Canada, many players use offshore sites licensed in places like Malta or Curaçao. Whatever the licence, you should be able to click through and confirm it's real. If the casino hides this information, we'd move along.
This is the step many players skip. Plenty of casinos accept Google Pay for deposits, but far fewer let you withdraw back to it. When cashouts aren't supported, you'll need a second method, often Interac e-Transfer or a bank transfer. That's not a deal breaker, but it's good to know before you play, so you're not caught off guard when it's time to cash out. Check the banking or cashier page, or ask live chat directly.
Look at the minimum deposit. A friendly site will let you start with $10 or $20 rather than asking for $50 up front. Also check whether the casino charges a processing fee on Google Pay. Most don't, but your card issuer might treat the transaction differently, so it's worth a quick look at your bank's terms too. And always confirm the site lets you play in Canadian dollars, so you're not losing a few loonies to conversion on every top-up.
Fast deposits are nice, but what really matters is how a casino treats you when you win. A site that takes your money in seconds but makes you wait two weeks for a withdrawal isn't one we'd recommend.
Look for clear processing times, daily or weekly cashout limits, and any pending period. The most trustworthy sites spell this out in plain language. If you want a head start, our list of best payout online casinos highlights sites with strong return-to-player rates and quick cashouts. Just remember that a higher payout percentage is a long-term average, not a promise of winnings in any single session.
Most casinos ask for ID before your first withdrawal. Uploading your documents right after you sign up saves you a lot of waiting later. It's a small step that makes the whole experience feel much smoother.
One reason we like Google Pay is that the casino never sees your actual card number. The wallet uses tokenization, which swaps your card details for a one-time digital code. On top of that, payments are confirmed with your fingerprint, face, or phone PIN. This kind of mobile payment tech is one of the bigger stories in Canadian fintech right now, and if you're curious about where it's heading, you can learn more here.
That said, a secure wallet doesn't replace good habits. Use a strong password on your casino account, turn on two-factor login if it's offered, and avoid making deposits on public Wi-Fi.
Payment options matter, but they're only one part of a good casino. Take a moment to look at the rest of what's on offer.
Since Google Pay lives on your Android phone, the casino should work just as nicely on a small screen. Try a few slots or a round of blackjack on mobile before you deposit. Pages should load quickly, and the cashier should be easy to find.
A welcome bonus can stretch your budget, but read the fine print. Some casinos exclude e-wallet deposits from promotions. Check the wagering requirements, the maximum bet while playing with bonus funds, and how long you have to use it.
Send live chat a quick question about Google Pay before you sign up. A fast, friendly answer is a good sign of how they'll treat you later.
Always remember that online gambling is meant to be entertainment, not a way to earn money. Even at the best site with the fastest wallet, the house always keeps an edge over time. Set a budget before you play, use deposit limits if the casino offers them, and take breaks when you need to. Google Pay makes topping up quick, which is exactly why it's worth keeping an eye on how often you do it.
If you take the time to check the licence, the banking rules, payout speed, and the overall experience, you'll find a Google Pay casino that feels safe, simple, and enjoyable to come back to.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 9, 2026 | Market Activity | Wealthtech, Investing And Trading, Fundraising And Capital Markets
On November 6, 2026, National Bank of Canada agreed to acquire Embark Student Corp. for an estimated $226 million, adding more than $6 billion in RESP assets under management and approximately 436,000 beneficiaries. The deal gives National Bank immediate scale in Canada’s $98.6 billion RESP market and strengthens its digital competition with Wealthsimple, Questrade and other investment platforms. The transaction is expected to close by mid fiscal 2027, subject to court, regulatory and other customary approvals.
National Bank already competes in Registered Education Savings Plan (RESP) accounts. It offers advisor supported RESPs and its direct brokerage lets customers manage RESP investments themselves. Embark brings a national digital business focused specifically on managed education savings, grant administration and RESP servicing. The acquisition gives National Bank a third way to compete for families without building that specialist operation one customer at a time.
Embark is one of Canada's largest direct to consumer RESP providers and operates as a Scholarship Plan Dealer across Canada. Its platform handles account administration, investment management, government grants and digital servicing around one financial goal. Its current student plans use target date portfolios that gradually reduce investment risk as a beneficiary approaches post secondary education.
National Bank's existing bank RESP starts with an advisor relationship, while National Bank Direct Brokerage gives investors a self directed route. Embark operates between those models. Families hand over portfolio management but can manage much of the RESP relationship digitally through a provider built around education savings.
National Bank is buying scale with it. Embark brings more than $6 billion in RESP assets and about 436,000 beneficiaries. For comparison, National Bank's Wealth Management segment reported approximately $939 billion in assets under administration and $207 billion in assets under management at April 30, 2026. Embark is small beside that platform, but highly concentrated in a financial relationship that can last from a child's early years through post secondary withdrawals.
The acquisition also adds another route for National Bank's expansion outside Quebec. The bank says Embark increases its reach in Ontario and Western Canada. That follows its acquisition of Canadian Western Bank, which added banking scale in Western Canada. Embark adds something different, a national consumer savings platform without requiring another branch network.
Canada's RESP market now puts banks, digital wealth platforms and investment dealers against each other with very different models. National Bank can offer advice, self directed investing and, if the Embark deal closes, a specialist managed RESP platform. Wealthsimple combines managed and self directed RESPs with a much broader digital financial relationship. Questrade also offers both models but leans heavily into investment choice, investor control and lower published management fees.
| National Bank + Embark | Wealthsimple | Questrade | |
|---|---|---|---|
| Total Platform Scale | National Bank Wealth Management about $939B AUA and $207B AUM at April 30, 2026 | $169.2B AUA and 3.8 million clients at September 30, 2026 | $80B+ AUA |
| RESP Scale Disclosed | Embark $6B+ AUM and about 436,000 beneficiaries | RESP assets not separately disclosed | RESP assets not separately disclosed |
| Managed RESP | Embark specialist managed education savings plans | Wealthsimple managed portfolios | Questwealth managed ETF portfolios |
| Managed RESP Fee | 1.65% MER plus applicable tax. Embark says this covers investing, management and administration | 0.50% standard management fee, falling to 0.40% above $100,000. Some higher tier clients qualify for lower pricing. Underlying portfolio MER also applies | 0.25% below $100,000 and 0.20% at $100,000 or more, plus underlying ETF MER |
| Self Directed RESP | Available through National Bank Direct Brokerage | Available through Wealthsimple | Available through Questrade |
| Self Directed Fees | $0 online stock and ETF commissions. NBDB charges a $100 annual administration fee unless an exemption applies, including at least $20,000 in eligible assets | $0 stock and ETF commissions. A 1.5% currency conversion fee can apply when converting between Canadian and U.S. dollars | $0 stock and ETF commissions. RESP account, platform and inactivity fees are $0 |
| Product Fit | Families wanting specialist managed RESP support, bank advice or a separate self directed brokerage route | Digital households wanting education savings alongside investing and other financial products in one platform | Investors focused on cost, portfolio choice and control, with a lower cost managed option available |
| What's Unique | Combines a major bank with a large specialist RESP business and an existing bank owned brokerage | RESP inside a broad digital household finance ecosystem | Strong brokerage orientation with managed and self directed investing at low published fees |
| Strategic Play | Buy RESP specialization and an installed customer base | Grow the family relationship across more financial products | Compete on cost, choice and investor control |
Embark's current 1.65% MER is materially higher than the standard managed pricing published by Wealthsimple and Questrade. Its proposition has to carry more than portfolio management. National Bank is paying for specialized RESP administration, grant handling, digital servicing and a large base of funded plans that already exists.
Wealthsimple competes differently. Its RESP can exist alongside chequing, trading and other investment accounts within the same digital relationship. It reported $169.2 billion in assets under administration and 3.8 million clients at the end of September. Its advantage is less about RESP specialization and more about making education savings another product inside a growing household finance platform.
Questrade combines a low cost managed option with a brokerage model built around investor control. It reports more than $80 billion in assets under administration, offers Questwealth managed portfolios and lets RESP customers directly hold stocks, ETFs, options, bonds, GICs and mutual funds. National Bank can already answer that self directed model through NBDB. Embark strengthens the part of the market where families want management without relying on a conventional advisor relationship.
Canadian RESP assets reached $98.6 billion at the end of 2025, up from $89.8 billion in 2024 and $78.9 billion in 2023, according to the federal government's 2025 education savings statistics. Canadians contributed another $6.5 billion during the year, while 3.2 million beneficiaries received the Canada Education Savings Grant.
The CESG take up rate was 54% in 2025, with 318,233 beneficiaries receiving the grant for the first time. That leaves substantial room for providers to win new education savings relationships even before competing for assets already held elsewhere.
The market is also split across different types of providers.
Embark's managed RESP carries a materially higher fee than the managed options offered by Wealthsimple and Questrade, while National Bank already competes with both through its own direct brokerage. National Bank therefore has to show that specialist RESP administration, grant support and a dedicated education savings experience justify the premium while using its broader wealth platform to deepen those relationships over time.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 6, 2026
Planning for retirement often takes a backseat, especially when life gets busy. Many people find themselves thinking about retirement later than expected. This can happen for financial reasons, personal choices, or unexpected events. If you are approaching retirement later in life, you need careful planning. The good news is that with thoughtful preparation and informed choices, you can still enjoy a fulfilling retirement.
Here are some ways to prepare for a secure financial future.
Start by understanding your resources. Evaluate your current assets, savings, and other income sources. Check your savings accounts, retirement accounts, and any investments. Financial tools or software can help you track your finances. A financial advisor can give you specific insights to help you stretch your resources effectively.
Also, think about potential income you can earn after retirement. This could come from part-time work, freelance jobs, or even hobbies. The key is to recognize what resources you have and how to use them to support your retirement plans.
Creating a realistic budget is crucial as you near retirement. Review your current expenses and consider how they might change when you retire. Think about costs like healthcare, housing, daily living expenses, and leisure activities. Many retirees find that some costs go down, while others, like medical expenses, can increase.
Build flexibility into your budget for peace of mind. A well-planned budget allows you to adjust if unexpected costs arise or if you want to prioritize certain activities. Aligning your budget with your values can enhance your overall retirement experience. Budgeting is a powerful tool during this transition.
Retirement homes like Delmanor Prince Edward can be a good option for those planning for their later years. These communities offer various lifestyles and provide an engaging environment for residents. They encourage social interaction and a fulfilling lifestyle, creating a comforting sense of community.
Living in a retirement community can ease some burdens of home maintenance and daily tasks. This allows you to focus on hobbies, social events, and new experiences. Many facilities offer activities and outings, making it easy to meet new friends and explore interests that you may have set aside during a busy working life.
Assisted living is another appealing choice for older adults who want to be independent but also need some support. These facilities balance independence and assistance, helping residents enjoy activities and social opportunities.
Often, assisted living communities like Delmanor Northtown provide tailored services to meet individual needs, allowing you to manage your daily routines effectively. Whether it's coordinating healthcare or providing meals, these communities empower you to live your best life while ensuring support is available when you need it. This means you can enjoy a vibrant lifestyle in a community that understands and supports you.
As you approach retirement, review your investment strategies. A diverse investment portfolio can help protect your money from market ups and downs. Depending on how much risk you can handle and when you plan to retire, different types of investments may work for you.
Look at your stocks, bonds, and other assets to ensure they match your short- and long-term goals. Making changes early can help you be better prepared for retirement. Choose investments that help your money grow, but also keep in mind the need to protect your capital as retirement gets closer.
Healthcare planning is crucial as retirement approaches. Medical costs can be one of the biggest expenses during retirement, so starting your healthcare planning early can save you money. Learn about options like supplemental insurance to understand what medical coverage you will have after you retire.
Create a healthcare budget. This can help you manage unexpected medical bills and give you peace of mind about your health costs. You may also want to consider health savings accounts (HSAs), which can provide tax benefits and help you save for future medical expenses.
If retirement is coming soon and you feel pressed for time, remember that every effort you make to prepare helps—each decision you take shapes your future. Consider engaging with your community through retirement homes or assisted living options that can improve your quality of life and provide the support you may need. Stay informed, take action, and look forward to the possibilities ahead. Taking control of your financial future is empowering, no matter where you are in life.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 3, 2026
Plumbing problems tend to appear at the worst possible time, whether that is a pipe that starts leaking on a holiday weekend or a basement floor drain that fills with wastewater in the middle of the night. Knowing which problems call for an emergency plumber Toronto homeowners can reach at any hour, and which ones can wait for a regular appointment, helps a household act quickly and limit water damage in the first few minutes.
Some plumbing problems get worse with every minute. A burst pipe or a leak that sprays or pours water across the floor is the clearest example, since water travels under flooring, into walls, and down to lower levels quickly. Sewage rising through a basement floor drain, a toilet, or a tub is equally urgent, because it signals a blocked or backed-up sewer line and brings health risks into the home.
Other urgent cases include a toilet that keeps overflowing after the water supply is turned off, a water heater leaking from the tank itself, a sump pump that has stopped working while water rises in the pit, and a sudden loss of water to the whole house. In each of these cases, the help of an emergency plumber Toronto residents trust is worth arranging right away rather than the next business day.
Not every plumbing issue is a plumbing emergency. A single slow drain, a dripping faucet, or a toilet that runs after flushing is inconvenient, but these problems seldom cause damage overnight. If one fixture is clogged while the rest of the house drains normally, it is usually safe to stop using that fixture and book a regular visit.
The simplest way to decide is to ask two questions: is water escaping where it should not be, and does wastewater have nowhere to go? If either answer is yes, the situation should be treated as urgent, while a problem that is contained and stable can generally wait for a scheduled appointment.
The most useful step in any plumbing emergency is stopping the flow of water. In most homes, the main shut-off valve sits in the basement or utility room, close to where the water line enters the house and often next to the water meter. Turning the handle clockwise closes it and stops water from reaching every fixture.
Many fixtures also have their own valves. A shut-off valve under a sink or behind a toilet can isolate a single leak without cutting water to the whole house, and the cold-water valve above a water heater stops the tank from refilling. Locating these valves before anything goes wrong, and checking that they turn freely, saves valuable time later. A simple tag on the main valve helps every member of the household find it quickly.
A sewer backup calls for a different response from a clean-water leak. The first priority is to stop all water use in the house, since every flushed toilet, running tap, or load of laundry adds to the volume that has nowhere to go. Everyone in the home should hold off on using water until the plumber has cleared the line.
Sewage can carry harmful bacteria, so it is best not to touch it. Children and pets should be kept away from the affected area. Belongings can be moved to higher ground if it is safe to do so. Pouring chemical drain cleaners into a backed-up line is best avoided, as they rarely clear a main-line blockage and can make the work more hazardous for the technician.
Standing water near outlets, extension cords, or appliances is a serious hazard. If the electrical panel can be reached without walking through water, switching off power to the affected area reduces the risk. If it cannot be reached safely, it is better to stay out of the flooded space and wait for help.
Once the source of water is under control, removing what can be saved, opening windows for airflow, and taking photographs of the damage are sensible next steps. Wet drywall, carpet, and insulation can develop mould within a few days, so drying the area promptly matters as much as the repair itself.
Typing “emergency plumber Toronto” into a phone late at night is usually the first step. The call that follows goes more smoothly when the caller explains what happened, where the water is coming from, whether it is clean water or sewage, and whether the main valve has been closed. Mentioning the age of the house, the location of the problem, and any access issues, such as a locked side gate or a finished basement ceiling, helps the plumber arrive prepared.
Keeping the phone close after the call is also wise, so the plumber can share an arrival update or ask a quick question about access. If the situation changes while the household waits, for example water spreading into another room or a second fixture backing up, a follow-up call keeps the plumber informed.
The first task for the emergency plumber Toronto homeowners call in is to confirm that the source of water is stopped and the area is safe to work in. From there, the plumber assesses the cause, which may be a failed fitting, a split pipe, a blocked sewer line, or a worn-out appliance.
Some problems can be repaired on the spot, while others need a temporary fix to make the home usable until parts or additional work can be arranged. When a sewer line keeps backing up, a camera inspection may be recommended to find the cause. A clear explanation of what failed and what comes next allows the household to plan with confidence.
Many emergencies are preceded by warning signs that are easy to overlook. Drains that slow down repeatedly, gurgling sounds from fixtures, damp patches on ceilings, and a water bill that rises without explanation are all worth investigating before they turn into a crisis.
A simple meter test can reveal hidden water leaks. Turning off all the water in the home, recording the reading on the water meter, and checking it again after at least twenty minutes is all it takes. If the reading has changed, water is escaping somewhere. Testing the sump pump before spring, keeping grease out of kitchen drains, and protecting exposed pipes in unheated areas all reduce the chance of needing an emergency plumber Toronto families depend on at an inconvenient hour.
Drain Express provides emergency plumbing services across the Greater Toronto Area twenty-four hours a day, seven days a week, including holidays. Its highly qualified plumbers serve both residential and commercial clients, the work comes with a warranty, and the team has completed more than 5,000 jobs.
A little preparation makes every plumbing emergency easier to manage. Knowing where the shut-off valves are, recognizing which problems cannot wait, and having the number of an emergency plumber Toronto households can count on all help turn a stressful night into a problem that is contained, repaired, and behind them.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 3, 2026

Technology makes many parts of life easier, and home financing is no different. Whether you are buying your first home or refinancing your current mortgage, you can use digital tools to help. You no longer have to spend hours dealing with paperwork or making phone calls. Instead, technology helps you find information, compare options, and make smart decisions about your home financing.
You can now complete your mortgage application from your couch, compare multiple lenders with a few clicks, and track your application in real time. This change saves you time and creates a smoother experience, keeping you informed every step of the way. Let's look at how you can use technology to navigate home financing.
Mortgage calculators are helpful tools that give you quick estimates of your loan options. By entering details like home price, down payment, and interest rate, you can learn important facts about your monthly payments and total loan costs. This tool helps you see how different choices affect your budget, so you can make changes before you decide.
Many platforms also offer advanced calculators that include taxes, insurance, and private mortgage insurance (PMI). This detailed approach helps you see your financial commitments more clearly, so you can plan better. You can access these calculators anytime to update your numbers or rethink your plans.
Technology makes it easier to track mortgage rates Canada. Online platforms give you real-time information on current rates, trends, and forecasts. This helps you find the best time to lock in a rate. With this clear information, you don't have to guess if you're getting a good deal. Everything is just a few clicks away.
You can also easily compare what different lenders offer. Many websites show how rates have changed over time. This information helps you make smart choices that fit your financial goals.
Mobile apps put home financing in your hands. Several apps target borrowers, letting you track interest rates, find loan details, and communicate with lenders. Many of these apps are easy to use and guide you through each step of the financing process, making it clearer what you need to do.
For example, some apps let you upload documents directly from your smartphone. You can easily send your financial statements or proof of income without visiting a lender or broker. This feature saves time and simplifies paperwork, improving the overall process.
Using a mortgage broker can improve your home loan experience. Brokers work between you and lenders to find the best rates and terms for you. Today, many brokers use online tools to assess your finances and offer customized options quickly.
Technology helps brokers speed up paperwork and even run simulations to show how different choices affect your loan. They gather lots of information upfront, so you don't have to meet with many lenders. Your broker does the work and provides the best options based on your needs.
Technology also makes it easier to communicate with your broker. You can reach them by email, chat, or video call, making it simple to ask questions. This keeps you informed and comfortable throughout the loan process.
One major advancement in home financing is virtual consultations. Many lenders and mortgage brokers now offer video calls so you can discuss your options from home. This saves you time and the hassle of in-person meetings while still letting you ask questions and get personalized advice.
During these calls, you can review documents, look at different loan products, and address any concerns. Virtual consultations make it easier to connect with industry professionals, ensuring you feel supported and informed throughout the financing process.
You no longer need to search for paper documents or sort through files. Digital document management systems let you keep all your important papers in one secure place. Whether it's bank statements, tax returns, or job verification, scanning and organizing documents online makes your life much easier.
Many lenders let you submit documents online, saving time and reducing stress during the loan application process. You can access your documents from anywhere, so you can keep moving forward with your financing even when you're busy.
Technology is changing how we secure a mortgage. From calculators and apps to knowledgeable brokers and easy document management, technology offers helpful tools that make getting a loan simpler. These resources can make your home financing experience clearer and more efficient.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 3, 2026

Photo by Gabrielle Henderson on Unsplash
Most families meet their notary and their financial planner at different moments, in different offices, often years apart. The will gets signed in one place, the life insurance policy is arranged in another, and the retirement plan takes shape somewhere else again.
For Jason Barakat, President and CEO of Nolos Cabinet Multidisciplinaire Inc. in Montreal, that separation is where family protection tends to come apart. His view is easy to state and harder to put into practice. He sees the legal plan and the financial plan as two halves of the same promise a parent makes to a family, and when the people who build each half never speak, the family ends up carrying the risk.
A complete family protection plan has legal and financial sides. The legal side covers documents such as wills, protection mandates for incapacity, and marriage or cohabitation agreements, while the financial side covers life and disability insurance, retirement savings, and the beneficiary designations attached to each account and policy.
Each side can be done well on its own and still work against the other. A beneficiary designation on an insurance policy might send money somewhere the will never intended, or a will might divide an estate in a way that looks fair on paper but leaves heirs without the cash to settle debts or taxes. Nobody in either office made a mistake; the two plans just never met.
That gap is familiar ground for Jason. From 2003 to 2021, he served as President and Principal Officer of La Capitale Services Conseils, where he developed specialized financial services for Quebec's public sector employees and helped workers plan for retirement.
During that period, the firm's assets under management grew from $300 million to over $3 billion. Working at that scale keeps a leader close to the moment when financial plans meet real family life.
In Quebec, the notary holds a distinct place in family matters. A notarial will, for example, does not need to be probated by a court, which can spare a grieving family time and cost. Notaries also draft protection mandates and marriage contracts, the documents that decide who acts and who inherits when life changes suddenly.
Financial planners deal with a different set of questions. How much income would the family need if a parent could no longer work? Is there enough coverage to carry the household, or to fund the children's education? Are retirement savings on track, and who receives them?
According to Jason Barakat, those two sets of questions belong in the same conversation. The notary understands what the law allows and requires, and the planner knows what the family can afford and what it would need in a crisis. With both looking at the same plan, contradictions surface early, while there is still time to fix them.
That conviction shaped the company he founded in 2022. Nolos Cabinet Multidisciplinaire Inc. brings FinTech, InsurTech and LegalTech together on one platform, with an ecosystem that includes a Quebec-based legal firm, a notarial study and a national financial MGA (Master General Agency) distributing protection and wealth solutions from Canada's top financial institutions.
The team was built to match. Lawyers, notaries, financial planners, and experts in related fields work inside the same organization, so a family's legal and financial needs get looked at together from the start.
The structure serves a mission of access. Nolos was built to open legal and financial services to middle-class families, the households that often can't justify hiring several separate professionals and asking them to coordinate. Wealthier families have long had that coordination through family offices, a world Jason knows well.
In 2021, he partnered with Peartree Canada to help family offices, high-net-worth individuals and organizations with strategic giving and philanthropic planning. Nolos applies a similar principle of coordinated advice to a much wider group of Canadians.
Putting professionals under one name is only a first step; they also need to share information, keep documents consistent, and give families a clear view of where their plan stands.
Jason's answer to that challenge is technology. In 2022, he acquired Skylegal, a Quebec legaltech firm. More recently, he acquired a tech firm that develops software and applications for public and private institutions, adding further technological capabilities to the Nolos platform. His aim is to bring legal and financial services under one roof so the family using them experiences something coherent and not a collection of separate appointments.
He is equally clear that technology supports the human relationship. A family deciding who will care for their children, or how to provide for a spouse, needs a trusted professional across the table, and good systems give that professional a fuller picture of the family's situation.
Jason's interest in this field runs through his own education and service. He studied finance and business law at Concordia University's John Molson School of Business and completed extensive studies in estate planning, individual and group insurance, and strategic philanthropy.
In 2023, he launched a charitable foundation, later named the Nolos Foundation, with a mission of access to justice and family legacy planning. The foundation carries the same belief that drives the company, namely that financial knowledge and legal protection should be within everyone's reach, including people who can't afford a full team of advisors.
As a husband and father of two, he also approaches the subject personally. Estate planning works best when it begins with the conversations a family has before a crisis, while decisions can still be made calmly and together.
For families who have never brought their advisors together, the first step can be modest. Gather the existing documents, meaning the will, any protection mandate, insurance policies and the beneficiary designations on retirement accounts, and ask whether the people who prepared them have ever compared notes. Often they haven't.
Jason Barakat believes that single question is where better family protection begins. Through Nolos and its foundation in Montreal, he continues to build a model where notaries and financial planners work from the same plan, so more Canadian families can count on protection that holds together when they need it most.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016