





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 23, 2026 | NCFA Fintech Market Activity | Wealthtech, Capital Markets And Funding, Fintech And Innovation
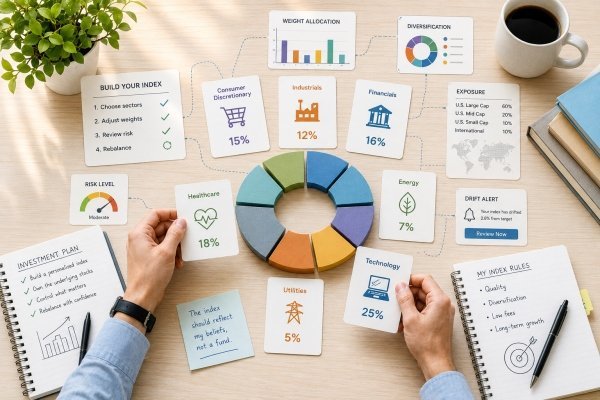
On June 2, 2026, Questrade launched Custom Indexing, describing it as Canada’s first personalized index investing product with no management fees. The product lets self directed investors build a customized index portfolio, own the underlying stocks through fractional shares, and rebalance in one click.
The product page positions Custom Indexing as a middle ground between ETFs and stock picking. Investors can start with a template, adjust stocks or sectors, receive drift alerts, and rebalance when their index moves away from target weights.
Wealthtech competition is evolving beyond low cost trading and into portfolio controls. Questrade is betting that some DIY investors want the simplicity of index investing without giving up control over what they actually own.
ETFs give investors diversified exposure, but the investor owns units of a fund rather than the individual holdings inside it. Questrade’s Custom Indexing gives users direct ownership of the securities in their index through fractional shares.
Investors can remove or adjust holdings, change sector exposure, and maintain a customized portfolio without building every position manually. Questrade says the product has no management fees, no MERs, and no commissions, although all indexes are held in US dollars and foreign exchange fees still apply.
Custom Indexing currently supports US securities only, with Canadian fractional shares expected later. It also requires a dedicated Custom Indexing account, available through TFSA, RRSP, FHSA, or Cash account types, so the index remains separate from other holdings.
Custom Indexing doesn't try to replace every ETF or every advisor.
It targets investors who want more control than a pooled fund gives them, but less manual work than managing a basket of individual stocks.
The product uses templates, stock and sector level customization, drift notifications, and one click rebalancing. Questrade says investors can start with as little as $10, then edit the index over time as their preferences change.
Custom indexing brings Questrade closer to one of the key retail wealth question. How much personalization can digital investing platforms give users before the product becomes too complex for everyday investors?
Envestnet expanded direct indexing in Canada, giving registered firms more control over tax treatment, exclusions, personalization, and security level portfolio design.
Wealthsimple launched IPO access, adding another retail investing feature that shifts competition toward access, loyalty, and differentiated wealth products.
Wealthsimple acquired Fey to add AI research tools and strengthen its trading platform.
OSFI cleared Questrade to open Questbank, pointing to a broader move from brokerage into banking and deeper financial relationships.
DIY investing continues gaining traction in Canada as more investors seek control, personalization, and lower cost access.
If custom indexing gains traction with self directed investors, more wealth platforms may have to compete on portfolio design, not only fees, access, or trading tools. The product could also make direct indexing feel less like an advisor only capability and more like a retail wealth feature.
More control can create better fit, but it can also create more responsibility. Investors still need to understand concentration, sector exposure, currency costs, taxes, and when customization improves a portfolio versus simply making it more complicated.
NCFA's Financial Innovation Map tracks wealthtech opportunities including personalized investing, direct indexing, portfolio automation, investor intelligence, and digital advisory models.
If personalized indexing becomes easy for retail investors, will the next wealthtech fight be about fees, access, or who gives investors the best control without adding confusion?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 22, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, SME Finance And Business Banking, Artificial Intelligence And Data
Payment processing is getting easier to buy. Merchant relationships are not.
On June 18, 2026, Deluxe announced an agreement to acquire Celero Commerce for approximately $625 million in cash. The acquisition adds a payment platform serving small and mid sized businesses, expands Deluxe's distribution network, and increases its exposure to payments and data services.
Deluxe expects Payments and Data to represent 57% of 2026 pro forma revenue following the acquisition, compared with 31% in 2020. The numbers suggest a company evolving well beyond its legacy association with checks and deeper into merchant payments, software channels, and transaction data.
Celero generated more than $200 million in revenue during 2025 and reported a 28% adjusted EBITDA margin. Together, Deluxe and Celero processed approximately $70 billion in gross transaction volume during the year.
And then there's distribution. Celero operates through roughly 375 active partners and added about 60 new partners in 2025. Those relationships include banks, software firms, independent sales organizations, and other channels that already sit close to merchants.
Processing volume can be bought from other providers, but trusted business relationships are harder to replicate. Deluxe isn't simply buying transaction flow. It's buying access to merchants through networks that took years to build.
Barry McCarthy, President and CEO of Deluxe, said the acquisition:
“immediately accelerates our transformation” and expands the company's reach across financial institutions, software providers, and partner channels.
The strategy reflects a widening trend in payments. Small businesses rarely purchase payment acceptance in isolation. They buy tools that help them sell, get paid, manage operations, understand customers, and make decisions. Payments are increasingly part of larger software and data ecosystems.
That helps explain why payment providers continue investing in merchant distribution, software integrations, embedded finance capabilities, and business data services.
SumUp entered Canada targeting SME payments, banking, and business software services.
TD partnered with Fiserv and adopted Clover technology as part of its merchant services strategy.
Ownership questions around Moneris continue to highlight changing priorities in merchant acquiring and payment infrastructure.
Fiserv continues expanding Clover beyond payment acceptance into software and data driven business services.
Revolut expanded merchant payment capabilities for larger businesses through new in person payment infrastructure.
If merchant relationships continue becoming more valuable than processing capacity, firms with trusted distribution networks may gain advantages across software, lending, treasury services, embedded finance, and business intelligence. The transaction suggests that payment providers increasingly view merchant access as a strategic asset rather than simply a source of transaction volume.
The tension is whether those relationships become easier or harder to transfer over time. As software platforms, payment providers, and embedded finance firms compete for the same businesses, distribution alone may not be enough. Firms will still need to demonstrate value beyond the payment itself.
If payment processing becomes widely available, what becomes harder to replicate, the payment rail or the merchant relationship?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 8, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech
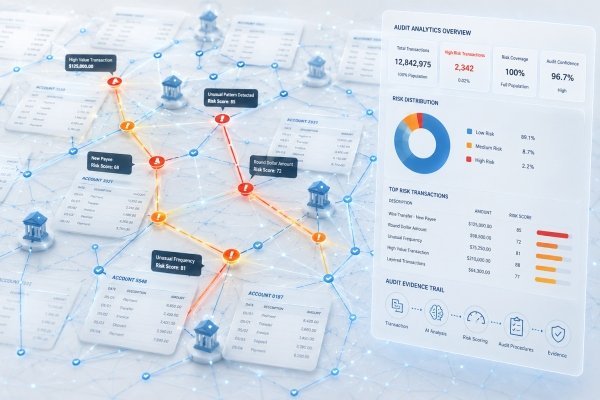
On June 8, 2026, Ottawa based MindBridge expands its AI audit and assurance platform to help audit teams review larger transaction populations and assess risk faster. The update adds full population analysis, subledger analysis, a Monetary Flow Dashboard, transaction level risk assessment, duplicate transaction controls, and large file processing.
MindBridge says KPMG deploys its platform through a global audit platform used in more than 60 countries. The company also points to recent partnerships with BDO and Buzzacott.
Sarah McGinnity, General Manager, Audit & Assurance Solutions at MindBridge:
“Audit and assurance teams are being asked to oversee larger transaction populations, more complex systems, and increasingly automated financial processes without adding proportional time or resources.”
The most important part of the announcement is the focus on full population analysis.
Audit teams have traditionally relied on sampling. AI driven software now makes it possible to review entire transaction populations and identify unusual activity across much larger data sets. That can help auditors spend less time searching for issues and more time investigating the transactions that matter.
MindBridge is positioning its platform around that shift. The latest release gives users more visibility into transaction flows, subledger activity, and risk indicators across financial records.
Many AI products compete on productivity. MindBridge competes on audit quality, risk assessment, and financial controls.
It alters the buying decision. Audit firms, finance teams, and regulated organizations already need oversight, documentation, and evidence. They aren't looking for experimentation. They're looking for better ways to review growing volumes of financial data.
The trend extends beyond audit. Financial institutions are adopting AI in compliance, fraud detection, transaction monitoring, and operational risk. As NCFA noted in its coverage of regulated AI controls and governance, buyers increasingly want systems that support human judgment and provide a clear record of how decisions are made.
If audit software can test full transaction populations instead of samples, the value changes from finding anomalies after the fact to proving where financial risk may occur before judgment calls are made. That's where AI audit tools become useful to CFOs, auditors, and regulators: not as automation, but as evidence infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 5, 2026 | NCFA Insight | Artificial Intelligence And Data
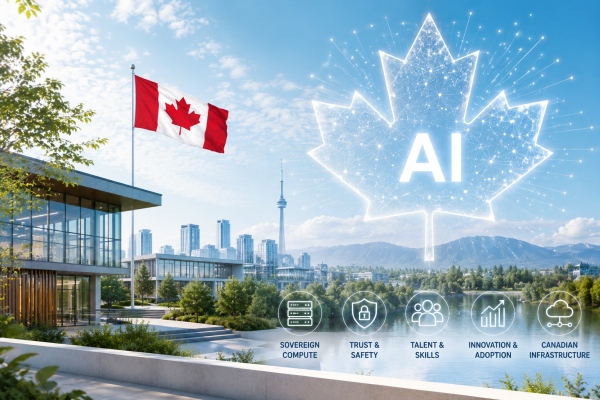
On June 4, 2026, Prime Minister Mark Carney launched AI for All, Canada’s new national artificial intelligence strategy. It targets $200 billion in additional economic growth, 250,000 new AI related jobs over five years, and a rise in AI adoption from just over 12% today to 60% by 2034.
The strategy also aims to create up to 90,000 AI related jobs and work placements for young Canadians. It supports AI skills, trust and safety, sovereign compute and cloud infrastructure, and Canadian company scale up. Canada’s AI challenge is no longer research. It is deployment.
Canada helped build the modern AI era. The country has three National AI Institutes, Vector Institute in Toronto, Mila in Montréal, and Amii in Edmonton. It also has a long record of public investment in AI research and talent.
Yet the harder problem is in the AI economy. The federal government says Canada remains among the slowest countries to adopt AI at scale. Only slightly more than 12% of Canadian businesses use AI today. AI for All sets a target of 60% adoption by 2034.
Canada has AI credibility, but it lacks broad deployment. Research output can attract talent and capital. Still, productivity gains only show up when companies redesign workflows, train workers, improve operations, and build commercial products around the technology.
This connects directly to Canada’s AI adoption gap. The next phase depends less on model breakthroughs and more on whether firms can put AI to work across finance, healthcare, manufacturing, energy, agriculture, transportation, and public services.
AI for All is a strategy with announced investments, but it’s not positioned as one simple funding package. It sets out an implementation plan built around trust, opportunity, and sovereignty.
The plan includes stronger privacy and online safety rules, AI transparency measures, expanded AI Safety Institute capabilities, entry level AI training for all Canadians, trusted AI agents for post secondary students, SME adoption support, and an AI Missions Program that starts with health.
Canada needs more firms, workers, and public institutions using AI in ways that raise productivity, improve services, and create Canadian owned economic value.
For fintech leaders, the strategy reads like an implementation roadmap. AI adoption will depend on infrastructure, skills, procurement, privacy rules, data governance, and trust. These are the same issues affecting open finance, digital identity, fraud prevention, payments modernization, and smart data infrastructure.
Financial services may offer one of the clearest adoption tests. Banks, credit unions, insurers, wealth management firms, payment companies, and fintechs already run data heavy businesses. They also rely on repeatable workflows, compliance controls, customer records, and risk systems.
AI can support fintech use cases from fraud detection and credit assessment to investment research and operational risk monitoring. That creates an opening for Canadian regtech firms, AI infrastructure companies, payment providers, lending platforms, and wealthtechs that can help institutions move from pilots to production.
The same issue appears in AI and non traditional data in financial services. Financial institutions can use AI to improve decisions, but they need governance that protects consumers and supports regulatory trust.
The strategy pushes AI into national competitiveness policy. It names compute, cloud, connectivity, data, and talent as foundations of sovereign Canadian AI.
Canada’s national AI strategy also says the federal government will continue delivering more than $2 billion in existing investments in Canadian AI compute capacity, including through the AI Compute Challenge. This isn't a single new $2 billion package in the Prime Minister’s release. It's an existing compute investment stream tied to Canada’s wider sovereignty strategy.
It also connects directly to Canada’s recent debate over cloud concentration and AI sovereignty. Compute capacity and cloud control can determine whether domestic firms can scale without deeper platform dependence.
Countries don’t capture AI value only by producing researchers. They capture value when companies scale, retain key talent, own intellectual property, and sell into global markets from a domestic base.
For Canadian fintechs and investors, sovereign AI infrastructure affects who controls data, how firms access compute, how procurement supports domestic companies, and whether Canadian AI companies can scale before larger foreign markets pull them away.
AI for All sets ambitious targets. The proof will come from adoption, scale, productivity, and trust.
Can Canadian business adoption rise from just over 12% to 60% by 2034? Can Canadian AI firms scale while keeping meaningful operations, talent, and intellectual property in Canada? Can regulated sectors deploy AI with enough transparency and accountability to earn public trust?
Canada already proved that it can build AI research strength. Yet it hasn’t proved that it can turn that strength into widespread productivity gains and globally scaled companies at the same pace as larger markets.
For NCFA members, the opportunity lies in execution. Founders can build AI tools that solve costly financial sector problems. Investors can look for firms with real workflow adoption, not only technical claims. Policymakers can reduce friction where regulation, procurement, data access, and capital formation slow responsible deployment.
AI for All is a clear shift in Canada’s AI policy. Ottawa now looks at AI as an adoption, productivity, sovereignty, and scale up challenge, not just a research agenda. Canada’s AI advantage will come from helping more Canadian firms use AI, sell AI, govern AI, and keep more of the value created by AI in Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
June 2, 2026 | NCFA Feature | Capital Markets And Funding, Open Banking Open Finance And Data Sharing, Digital Assets Blockchain And Tokenization

On May 28, 2026, Wealthsimple announced IPO Access for Canadian retail investors, giving eligible clients a way to request shares in select Canadian and US initial public offerings at the offering price before public trading begins. Four days later, Robinhood completed its WonderFi acquisition and entered Canada with a regulated crypto base.
Canada’s retail finance market is turning into a contest over access, loyalty, status, and who owns the customer relationship.
Wealthsimple says IPO Access lets eligible clients review available IPOs inside the platform, submit a conditional offer to buy before public trading begins, and receive shares at the offering price if an allocation is available. Canadian IPOs and US IPOs marketed in Canada by prospectus are open to eligible clients, while US only IPOs require accredited investor status.
Clients don't automatically receive shares. Wealthsimple can only distribute the IPO shares it receives through participating investment banks, so investors may receive all, some, or none of the shares requested. IPO Access opens the door to a process long dominated by institutions and high net worth investors. Allocation size, issuer quality, investor suitability, disclosure, and demand will decide whether it becomes meaningful market access or a loyalty feature with thin supply.
If Wealthsimple ever pursued its own public listing, IPO Access would face its most visible credibility check. Can retail investors receive meaningful allocation in a high demand Canadian IPO, or only permission to submit a request?
Robinhood’s WonderFi acquisition gives it Canadian market entry through regulated crypto infrastructure. WonderFi operates Bitbuy and Coinsquare, two long running Canadian crypto platforms. When Robinhood announced the WonderFi deal in May 2025, WonderFi reported more than C$2.1B in assets under custody. The all cash transaction valued WonderFi at about C$250M, with shareholders receiving C$0.36 per share.
Robinhood is entering Canada with a larger consumer finance model (not just crypto trading). Its US strategy already reaches beyond trading into managed portfolios, premium membership, family accounts, credit products, AI tools, and lifestyle finance. Robinhood’s wealthtech and lifestyle finance push lays out the direction clearly. The company wants a larger share of the customer relationship, extending beyond trading into crypto, cash, credit, rewards, and everyday financial activity.
Wealthsimple already owns the local bank challenger position. Robinhood now has regulated crypto distribution and global brand recognition. Banks have the widest financial relationships. The competitive question is who can turn access, trust, price, rewards, and habit into the primary customer relationship.
Canadian banks still dominate deposits, lending, mortgages, advice, card relationships, business banking, and full service wealth management. Their brokerage arms have responded with lower cost trading offers, ETF promotions, digital tools, and stronger wealth integration.
Wealthsimple’s three year Billy Bishop airport partnership puts a fintech brand inside a premium travel moment that banks and card issuers have historically owned through lounges, rewards, and status. The June 1 to August 31 pop up is brand marketing. The broader agreement is more strategic, linking financial products to membership, identity, and lifestyle.
Banks can match prices, bundle accounts, and improve digital apps. Cultural relevance is harder to buy. Wealthsimple and Robinhood sell access, control, status, simplicity, and participation. Banks sell security, breadth, advice, and balance sheet strength. The winner will combine both without making the customer feel trapped.
IPO Access now has to prove allocation quality, not only product demand.
Robinhood has to show whether WonderFi becomes a crypto foothold or the base for a broader Canadian wealth and money platform.
Banks have to decide whether to respond with better access and pricing or mainly protect existing margins. They now have to defend the relationship, not just the account.
Regulators have to keep investor protection strong without blocking access models that could improve capital formation.
For NCFA's community, the capital markets innovation angle is interesting. Canada needs more public market participation, deeper retail access, stronger fintech competition, and clearer rules for digital investing. Wealthsimple’s IPO Access launch puts a practical test in the market. Robinhood’s Canada entry raises the competitive stakes.
If fintechs can give Canadians better access to IPOs, crypto, investing, rewards, and everyday money tools, will banks respond by opening up the customer relationship or by making their existing bundles harder to leave?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 1, 2026 | NCFA Fintech Market Activity | Risk Compliance And Regtech, Artificial Intelligence And Data
On May 27, 2026, Fredericton based cybersecurity scaleup Lastwall raised $16 million in a round led by BDC Capital’s StrongNorth Fund, See Isabelle Hudon, President and CEO BDC's LinkedIn announcement. The round also included the New Brunswick Innovation Foundation, Frostbite Capital, Blue Bear Capital, BlueWing Ventures, and 18West.
It's a Canadian cybersecurity story, not a military procurement story. Lastwall works in defence, government, and critical infrastructure environments, but the announcement is about growth capital for identity first security, zero trust access, and quantum resilient protection. For NBIF, it's the largest single investment in its history through the round.
Karl Holmqvist, Founder and CEO, Lastwall:
“We proved our model in the world’s most demanding federal market. We earned FedRAMP Moderate Authorization, secured U.S. government systems, and built a platform for the realities of modern cyber warfare. Now, we’re bringing those trusted capabilities home to help strengthen Canada’s cyber resilience at a defining moment for national security.”
Lastwall secures access across cloud, hybrid, disconnected, and low bandwidth environments. It's important for energy, telecom, transportation, defence, government, and public sector systems where a failed login layer can become an operational risk.
The product focus is identity, authentication, credential protection, privileged access, and zero trust controls. Lastwall also says quantum resilient protection is built into the platform, which is key for systems that need to stay secure beyond the current threat cycle.
For fintechs and financial institutions, digital identity and access control are now resilience infrastructure. Fraud, account takeover, insider risk, cloud access, vendor access, and critical system protection all depend on knowing who is connecting, from where, and under what conditions.
Peter Dawe, BDC’s Vice President of Defence Strategy and a recently retired Major General, joined Lastwall’s board as part of the financing. That gives the company closer defence and sovereign capability expertise as Canada looks for more domestic cyber capacity.
Canada’s cyber resilience gap isn't only about monitoring threats. It's also about securing access to the systems that run public services, financial infrastructure, energy, communications, and national security. Canada’s new cyber law and PSP oversight are already raising the bar for security, resilience, and vendor accountability. Lastwall’s funding shows Canadian capital is starting to treat identity security as a sovereign capability, not just another software category.
Can Canadian cybersecurity firms turn U.S. federal proof into domestic critical infrastructure adoption before cyber resilience becomes a procurement emergency?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 1, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing
On May 28, 2026, Saris announced a $28.8M USD Series A to scale its agentic workflow platform for banks and credit unions. 8VC led the round, with participation from Audacious Ventures, Homebrew, Btech Consortium, and Service Ventures. Saris builds AI agents for lending, compliance, and operations, where financial institutions still spend staff time on document review, data validation, exception handling, and repetitive back office work.
Saris is a Canadian and US based AI fintech, not a Canada only vendor. The company’s hiring page describes a Canada and US hiring footprint, with hybrid workspace options in Montréal, Toronto, and San Francisco. This affects the business model. Saris can draw from Canadian AI and fintech talent while selling into the larger US banking market, where 8VC and enterprise partners can help open doors.
The Canadian link also sits in the founder story. Danial Jameel, Alice Dinu, and James Dang previously built Oohlala Mobile, later Ready Education, which Y Combinator lists in its Summer 2016 batch with a Montréal location. That history gives Saris a stronger base than a typical first time AI startup. Selling workflow software into regulated institutions takes trust, implementation discipline, and patience.
Saris now has more capital to compete in the US banking market, deepen integrations with Fiserv, Encompass, and MeridianLink, and grow the team that trains and deploys its AI agents. The strategic question for Canada is how much of that growth, talent, and customer expansion stays connected to the domestic fintech ecosystem.
Saris trains agents on each institution’s workflows and systems, then applies them to repeatable tasks across lending and operations under human supervision. Based on company reported figures, Saris’ agentic workflows automate up to 70% of consumer, mortgage, and commercial lending tasks and reduce costs by up to 35%. The platform also more than doubles output without adding headcount.
MeridianLink’s partner page says Saris works directly inside MeridianLink to automate document review, field validation, discrepancy remediation, post closing QA, and fraud alert resolution across consumer lending, DL4, and quality control workflows. MeridianLink also reports 99.8% field accuracy, 10x faster file review, and 3x underwriter and loan officer capacity, with one customer clearing a 600 loan backlog in four days.
So how does Saris stack up to competitors. Its target market extends beyond Canadian financial institutions, and its product fits banks and credit unions that already use systems such as Fiserv, Encompass, and MeridianLink.
US founded nCino brings global platform scale. More than 2,700 customers globally use nCino’s platform, including enterprise banks, regional banks, community banks, credit unions, challenger banks, building societies, and independent mortgage banks. That scale gives nCino a distribution advantage with institutions that want a broad cloud banking platform across lending, account opening, portfolio workflows, and customer engagement.
Saris does not need to replace the full operating platform. Its opening is file review, document checks, exception handling, and throughput inside systems institutions already use. That gives Saris a more focused sale where banks and credit unions already run core platforms or loan origination systems but still rely on staff to clear repetitive work.
Canadian based thirdstream is more domestic and onboarding focused. More than 50 financial institutions use thirdstream’s onboarding platform, including banks, credit unions, brokerages, and trust companies. Its strength is in Canadian account origination, identity verification, automated decisioning, real time account funding, and document management.
Toronto based Boss Insights sits closer to lending data infrastructure. Its platform gives financial institutions business lending data infrastructure across accounting, sales, banking, payroll, tax, analytics, monitoring, and customer portal capabilities. Boss Insights lists 1 API and 1,000 plus integrations, which places it closer to open finance, borrower data, and commercial lending intelligence than Saris’ document and workflow automation layer.
Saris looks strongest where banks and credit unions want targeted AI automation without a full platform replacement. Saris can draw from Canadian talent and a Montréal founder history while selling into larger US banking budgets. The question is whether customer relationships, implementation teams, and product leadership stay connected to Canada as the company grows.
Danial Jameel, cofounder and CEO of Saris:
“Our vision is a future where humans and AI work side by side in financial services.”
Saris’ raise shows financial AI moving into the parts of banking where cost, controls, and customer turnaround times get measured. AI can lower operating costs, but financial firms still need evidence that models remain fair, secure, monitored, and accountable. That operating pressure also runs through AI compliance and governance costs.
Should Canadian AI funding and fintech policy focus more on regulated proof points inside banks, credit unions, payments, lending, compliance, and capital markets rather than broad AI adoption metrics?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
