




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


November 4, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy, Capital Markets Infrastructure And Funding
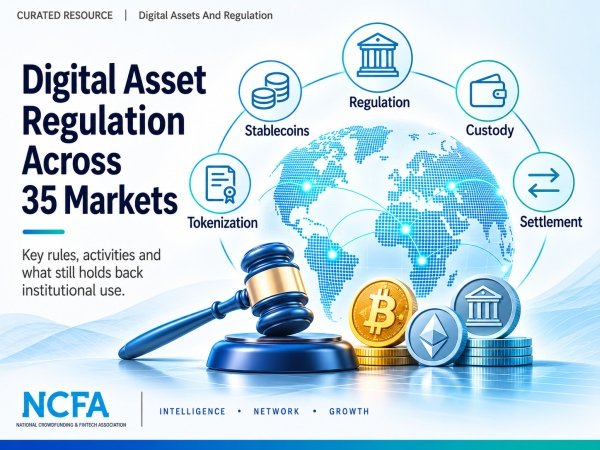
On October 28, 2026, the World Economic Forum and Boston Consulting Group published Regulation of Digital Assets in a Shifting Global Landscape, based on regulatory developments across 35 jurisdictions and more than 25 digital asset activities. The research includes interviews with 50 public and private sector experts, workshops and input from more than 100 participants. Digital assets can be legal and regulated while still being difficult for banks, asset managers and other institutions to use at scale.
More than 70% of the jurisdictions studied regulate the activity being performed rather than relying only on the form of the asset. Trading venues, custodians and payment providers are supervised in more than 75% of the sample. Progress still varies widely within individual countries. A market can have clear rules for tokenized securities while its stablecoin, custody or settlement rules are still incomplete. For a company deciding where to operate, the rules for its actual business matter far more than a country's overall reputation for digital assets.
The 38 page resource compares rules for token issuance, exchanges, wallets, custody, payments, lending, staking and the infrastructure behind digital assets. It also looks at whether institutions can legally own the assets, protect clients, settle transactions, use digital money and meet capital requirements. The activity matrix shows where each part of the market is regulated, partly regulated, unregulated or prohibited.
Cryptoassets account for roughly $3 trillion in market value, stablecoins about $300 billion in circulation and tokenized real world assets about $30 billion. One scenario cited in the research puts tokenized real world assets at approximately $88 trillion by 2035, equal to around 16% of global investable assets. BlackRock's BUIDL fund had reached about $2.6 billion by July 2026, while Euroclear and Banque de France are working on moving a €310 billion commercial paper market onto distributed ledger infrastructure.
Tokenization is already moving into financial infrastructure because issuing the asset is only the beginning. Ownership records, custody, settlement, collateral and servicing all have to work after that. Faster settlement can cut counterparty exposure but may require more cash at the time of settlement. Easier collateral movement doesn't help much if institutions cannot price the asset, pledge it or enforce their claim.
Five barriers can stop institutional adoption even after regulators permit the activity. Leaving one unresolved can keep a legal market small.
Digital assets won't make every middleman disappear, but they can make some existing fees harder to defend. Faster settlement and shared records mean less reconciliation, fewer manual steps and lower servicing costs. Businesses that depend on slow transactions, fragmented records or closed distribution may feel that pressure first. Liquidity, trusted custody, access to customers, risk capacity and market access are harder to replace.
For example, putting a fund onchain doesn't solve pricing, investor records, compliance, redemption, distribution or settlement. Tokenized fund operations after issuance still need all of those functions to work before investors get much benefit from the technology.
There is also money to be made connecting systems that don't yet work well together. Digital money needs places where it can be spent or settled. Tokenized assets need custody and financing. Banks and asset managers need reliable access to both. A company that solves one of those connections may have a better business than one issuing another token or building another closed network.
For founders and investors, a company can have excellent tokenization software and still struggle if customers cannot settle, finance or distribute the asset efficiently. Firms with control over liquidity, distribution, custody or an important connection between systems may have much stronger economics.
Not every part of a country's digital asset market develops at the same speed. Switzerland has established legal treatment for tokenized securities and distributed ledger market infrastructure while still developing its stablecoin rules. WEF and BCG state that “The relevant comparison is therefore by activity, not by jurisdiction overall.” A company choosing where to launch needs to examine the rules for its product and business model rather than rely on a broad label such as crypto friendly.
A country with heavy retail trading may need stronger platform supervision and customer protection first. Heavy use of foreign stablecoins can make reserves, redemption and currency risk more urgent. A financial centre trying to build tokenized capital markets may need clear custody, settlement and collateral rules sooner. Copying another country's approach can leave the biggest local problem untouched.
Cross border business doesn't require every country to have identical rules. Institutions need to trust the legal rights, customer protections and settlement outcomes in the other market. Countries can recognize each other's rules where those protections are comparable and avoid repeating the same work. That becomes much harder when supervision, enforcement, data or infrastructure cannot be trusted across borders.
Even the same rule can produce different results. Two firms may follow the same financial crime requirement but use different transaction histories, risk thresholds or blockchain analytics. One may accept a wallet that another rejects. Similar differences can affect collateral values, transaction data and controls. When that happens often enough, legitimate business gets slower and liquidity can break into smaller pools.
Canada now has several parts on the go at once. Proposed federal stablecoin rules cover reserves, redemption, custody and Bank of Canada supervision, while Canada's six largest banks are exploring Canadian dollar tokenized deposits. Tokenization is also expanding across funds, securities and settlement. All of these products eventually run into many of the same payment, custody, capital and infrastructure questions.
Canada's stablecoin rules won't create an institutional market on their own. Banks still need practical ways to hold and settle the assets. Custody has to be clear. Collateral has to work inside financing markets. Financial crime controls have to work across different networks. A stablecoin can meet its reserve requirements and still see limited institutional use if the rest of the transaction is difficult or expensive.
Tokenized securities and deposits face the same reality. Faster settlement can force treasury teams to keep more cash available during the day. Tokenized collateral only helps when lenders can recognize it, value it and enforce the claim. Systems can connect technically while ownership, privacy or compliance problems remain unresolved. A digital asset becomes commercially useful when the whole transaction works, not simply when one part has moved onchain.
The 35 country comparison is useful because it covers more than 25 activities and nine areas of regulation, making it easier to see exactly where a market is ready and where something is still missing. It also connects regulation to funding, collateral, settlement, custody, payments and business economics rather than treating compliance as a separate exercise.
The regulatory matrix mainly reflects conditions as of February 2026, and rules are changing quickly.
Digital Assets Regulation Insights from Jurisdictional Approaches (WEF comparison of nine jurisdictions published in 2024)
Stablecoin Regulations In Canada (current NCFA reference for Canada's federal stablecoin rules and implementation)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
October 30, 2026 | NCFA Story Intelligence | Digital Assets Blockchain And Tokenization, Cybersecurity And Fraud, Competition And Market Structure

On October 29, 2026, Binance suffered unauthorized withdrawals with an estimated US$6.3 billion impact, while Polymarket suffered a separate third party breach that forced its international prediction market to halt trading. Binance says the attack may have started with a compromised DevOps engineer’s laptop. Polymarket says one of its third party providers was compromised. The Binance hack and Polymarket breach aren’t known to be connected, but both exposed a similar weakness. Neither required the underlying blockchain to fail.
At Binance, the attacker reached systems capable of submitting withdrawal transactions. The exchange says it has found “no evidence of any wallet private key leak.” About US$3 billion has been frozen onchain, and Binance says customers won’t absorb the loss. Deposits are operating normally. Withdrawals remain paused while the exchange rebuilds parts of the withdrawal service.
Polymarket faced a different failure. Its international exchange entered cancel only mode at 2:05 p.m. ET, identified the compromised provider at 2:37 p.m., prepared to resume trading at 2:55 p.m. and marked the incident resolved at 3:05 p.m. Polymarket says “Anyone who has been impacted will be made whole.” The platform is operating again, but full reimbursement of every affected user hadn’t been independently confirmed at the latest verification cutoff.
Binance shows what can happen when attackers reach the systems that authorize money movement. Polymarket shows how hostile code can reach customers through software sitting between them and the market. In both cases, the financial rails could keep processing instructions after the instructions themselves had been compromised.
TRM estimates approximately US$6.36 billion moved from Binance wallets across ten blockchains. Elliptic independently calculates about US$6.43 billion.
Binance’s official estimate remains approximately US$6.3 billion. Different pricing times produce small differences, but all three calculations land around the same extraordinary number.
A compromised employee device can sit several steps away from a private key and still reach systems that decide which transactions get signed.
For an exchange, authorization controls become part of custody whether the private key leaks or not.
Tether, Circle and other issuers could immobilize supported balances while stolen assets were still moving.
Bitcoin and ether stayed visible but movable. Tracing the money and controlling the money were two different powers.
Polymarket hasn’t confirmed a final loss figure or victim count. Outside estimates range from about US$2.2 million to US$2.7 million.
Polymarket says affected users will be made whole. Full reimbursement hadn’t been independently verified at the latest cutoff.
Binance hasn’t finished proving the recovery works just because deposits are back. Withdrawals still have to resume without reopening the weakness that forced them to stop. The exchange also needs to show that replacement assets fully support customer liabilities after billions moved out. Its promised postmortem needs to explain how unauthorized withdrawals passed internal controls and what changed before the system reopened.
The updated Proof of Reserves will put numbers behind the customer protection promise. Binance says customers won’t absorb the loss. Reserve data can show whether the assets behind customer balances have actually been restored.
Polymarket isn’t finished once trading comes back either. Affected users still need to be fully reimbursed. Two third party compromises in four months also leave a harder question over the business. **How much outside software should be able to touch an authenticated customer session before the market itself becomes exposed?**
The Binance hack showed that a platform can lose billions without evidence that its private keys were stolen. Polymarket showed that a market can remain technically intact while hostile code reaches customers through a supplier. Stablecoin issuers then froze billions of dollars that native bitcoin and ether issuers couldn’t freeze because no such issuer exists. Binance’s own balance sheet became the backstop after those controls ran out.
That is where the competitive line in digital finance is moving.
The strongest platforms won’t be the ones that simply claim secure infrastructure. They’ll be the ones that can **limit what a compromised employee, supplier or software component can do, stop bad instructions before settlement, isolate losses quickly and carry the financial weight when prevention fails**.
Binance and Polymarket are now being measured on exactly that.
The blockchain may settle the transaction. Trust won’t come from the blockchain alone. It will depend on everything that happens before an instruction reaches the chain and everything a company can still do after something goes wrong.
How 4,000 BTC Left Liquid Network Without A Stolen Key
How nearly an entire reported Bitcoin reserve left through an apparently valid process even though the obvious authorization key remained intact.
Binance Left Canada but the Fight Reached Supreme Court
How Binance’s Canadian exit became a wider test of regulatory reach, company records and access to digital asset markets.
Polymarket Earns Approval to Relaunch in the U.S.
How Polymarket moved back toward regulated US market access after acquiring a licensed derivatives exchange.
Canada Proposes Stablecoin Market Entry Rules
Canada’s proposed rules put reserves, custody, redemption, data security and recovery directly into the stablecoin operating model.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 28, 2026 | NCFA Story Intelligence | Regulation And Policy, Digital Assets Blockchain And Tokenization, Competition And Market Structure, Capital Markets Infrastructure And Funding
Binance thought it was leaving Canada in 2023. The regulatory fight stayed behind.
Binance never entered Canada the way a bank or securities dealer would. It didn’t open a Canadian branch, build a local exchange or wait for a Canadian licence. Changpeng Zhao was a Canadian entrepreneur who had studied computer science at McGill, but Binance launched in Shanghai in July 2017 and grew into the world’s largest crypto exchange by trading volume within about six months. The product was global from the start. Borders came later.
By 2021, Canadian regulators were catching up with what that model meant on the ground. Ontario pushed Binance out. Binance hired former regulators, incorporated in Alberta and tried to build its way back in. Then Canada tightened the rules again. On May 2, 2023, Binance told securities regulators it planned to withdraw nationally.
Eight days later, the OSC opened an investigation. The next day came a sweeping demand for company records. On May 12, Binance told the public it was leaving Canada.
The exit and the investigation crossed in real time. Binance was trying to close one Canadian chapter while the regulator was opening another.
Three years later, that unfinished business has reached the Supreme Court of Canada. Ontario’s Court of Appeal has already ruled that part of the OSC summons went too far. The OSC wants that ruling overturned. Nine interveners now include civil liberties groups, securities regulators and four governments.
What follows is a story of a borderless crypto company meeting national regulators, leaving some markets, adapting in others, and discovering that a market exit doesn’t make the regulatory past disappear.
Ontario treats access as local activity. The OSC’s position is that platforms offering securities or derivatives to Ontario users can’t avoid provincial rules simply because the company or servers sit somewhere else. For internet based finance, the customer’s location can pull a global platform into a local regulatory system.
Binance starts planning a return. By early 2022, Binance is doing something that would have looked unlikely months earlier. It hires former Canadian regulators, incorporates in Alberta and starts building toward full registration. Binance hires ex-regulators and incorporates in Alberta to charter compliance course in Canada catches the pivot. A few months later, Alberta-based Binance Canada expects to return to Ontario by 2024 shows how far the strategy has moved. The company isn’t talking about abandoning Canada. It is talking about coming back to Ontario through the front door.
The OSC gets enforceable controls. The undertaking turns account restrictions, product wind downs and monitoring into commitments the regulator can supervise. Binance is no longer only deciding what Ontario access should look like on its own.
Binance still sees a Canadian future. The company pursues registration outside Ontario and talks publicly about returning. That makes the national exit in 2023 more than a market withdrawal. It ends an attempted compliance strategy.
Binance blames the rule set, not Canada itself. The company says it delayed the decision while looking for another route and hopes to return someday. Canada is a relatively small market for Binance, but the evidence doesn’t establish that size alone drove the exit. The company’s own explanation focused on the rule set and the product limits that came with it.
Other platforms make a different calculation. Some exchanges also leave, while others pursue Canadian registration and accept narrower product menus. Every platform has to decide whether the local opportunity justifies the controls, product limits and ongoing supervision required to stay.
Regulators need records to reconstruct the past. Cross border platforms can spread staff, systems and legal entities across several countries. Without compulsory powers, investigators may struggle to establish who made a decision, which controls existed and what customers were told.
Broad demands carry real operating costs. A request covering years of email, chat, files and other communications can trigger preservation, data collection, legal review, privilege screening and cross border privacy work. A global exchange can spend heavily on that process. A smaller fintech may feel the same demand much more sharply.
The ruling protects relevance, not secrecy. The Court accepts that regulators have strong production powers and that privacy expectations for regulated business records can be low. It still requires a reasonable basis to believe compelled records may matter to the investigation.
The OSC sees a wider enforcement problem. The regulator argues that the Court of Appeal’s approach could make investigations slower and more difficult, particularly before investigators know exactly where useful evidence sits. Binance answers that regulators have had relevance limits for decades and can draft demands around the conduct they are actually investigating.
Investor protection still needs effective investigations. Regulators can’t police complex markets without access to records. Cross border digital businesses make that harder because relevant evidence may sit across entities, employees and systems that don’t line up neatly with one province.
Constitutional limits still matter inside regulated markets. Laura Paglia of the Canadian Forum for Financial Markets told Advisor.ca that securities regulators need broad powers, but argued that demands should remain proportionate and consider compliance costs. CFFiM was denied intervener status, so its view is industry commentary rather than a submission the Supreme Court will hear.14
Binance has already tried several endings in Canada.
First it left Ontario. Then it hired regulators and built an Alberta operation that was supposed to bring it back. Then it accepted an Ontario undertaking. Then it decided the national rules were no longer worth the trade and left Canada altogether.
The legal history kept going.
FINTRAC imposed a penalty tied to the years Binance operated here. Investors pursued a separate class action. Ontario courts rejected Binance’s attempt to force those investors into costly Hong Kong arbitration, a dispute later followed by Ontario Court Orders Binance To Pay Investor Legal Costs. The OSC kept investigating. The company that left Canada in 2023 is still litigating here in 2026.
Binance changed too. Zhao stepped down. A board arrived. Local licences and compliance teams became part of the growth strategy. Japan went from warning Binance to hosting a locally registered Binance business. Abu Dhabi became a regulated global base.
The Supreme Court case is now much bigger than Binance.
The Court is being asked to decide where constitutional limits sit when a regulator with legitimate investigative powers demands a very large volume of company records. A ruling that gives regulators wider latitude could make it easier to investigate complex businesses whose people, systems and data span multiple entities and countries. A ruling that requires a tighter connection between requested records and suspected conduct could force regulators to narrow summonses earlier and give companies stronger grounds to challenge sweeping demands.
Either way, the decision could shape how securities regulators design investigations, how regulated firms preserve and produce records, and how much compliance cost companies may face when regulators come looking for evidence. Depending on how broadly the Court reasons, its impact could also reach beyond capital markets into other regulated sectors that rely on statutory production powers.
That helps explain why governments, another securities regulator and civil liberties organizations have joined a dispute that began with one crypto exchange. The precedent could influence the balance between effective supervision and protection against regulatory overreach across Canadian business.
Binance spent years learning that global reach doesn’t erase national borders. Canada’s highest court is now deciding where one of those borders sits for regulators themselves.
Once a regulator has authority to investigate, how much of a company can it force open?
Binance left Canada. The company moved on. The answer could matter to regulated businesses long after this case is over.
INVESTOR GUIDE
7 Questions to Ask Before Choosing a Crypto Exchange in Canada
A current guide to registration, custody, transfers, funding, fees and operational risks Canadian investors should check before sending money to a crypto platform.
FINTECH INTELLIGENCE
Are Regulators Opening Markets While Raising Costs?
Market access can improve while evidence, records and supervision requirements get tougher, changing the economics for both incumbents and smaller entrants.
REGULATORY INSIGHT
Canada Proposes Stablecoin Market Entry Rules
Canada’s new stablecoin proposal shows how market access can depend on local custody, supervision and operating requirements, even when the underlying product is global.
REGULATION AND POLICY
National Security Is Now Part of Financial Supervision
Financial supervision is expanding beyond traditional capital and conduct questions into sanctions, cyber threats, ownership and state linked risk.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 26, 2026 | NCFA Market Activity | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization, SME Finance And Business Banking
On October 26, 2026, Atlanta based trade finance company PrimeRevenue announced plans to tokenize trade finance assets on Solana, bringing its Electronic Time Drafts (ETDs) to blockchain capital markets. These instruments represent corporate buyers' obligations to pay suppliers on agreed future dates and can be financed to provide suppliers with earlier cash. PrimeRevenue aims to expand beyond its established bank funding network by connecting these obligations with additional institutional and eligible blockchain investors.
PrimeRevenue reports 50,000 companies using its platform, more than 100 funding partners and over US$300 billion in annual payment transactions. That established network gives the company a strong starting point for bringing corporate payment obligations to new investors. Rather than building a financing market from scratch, PrimeRevenue can extend its existing relationships, financial instruments and distribution capabilities into blockchain capital markets.
When a corporate buyer owes a supplier money, the supplier may have to wait 30, 60 or 90 days for payment. PrimeRevenue's Electronic Time Draft allows the buyer's payment obligation to be transferred to a financing bank at a discount. The supplier receives cash early, while the bank collects the full amount from the buyer when payment comes due. Financing terms reflect factors including the buyer's credit rating and the remaining payment period.
For example, a supplier owed US$100,000 in 90 days could exchange the draft for an earlier discounted payment. A smaller supplier working with a financially stronger corporate customer may secure more attractive financing than borrowing against its own credit. The buyer retains the agreed payment date, the supplier receives working capital and the bank earns a return for providing the funding and assuming the buyer's payment risk.
ETDs aren't ordinary digital invoices. PrimeRevenue's patented process creates and signs a time draft electronically, supports its transfer to the financing bank and arranges collection at maturity. The company says the structure also removes certain lien search and release requirements that can complicate conventional receivables financing.
Over time, tokenized ETDs could support a continuously replenishing working capital market. Corporate buyers generate new payment obligations, suppliers receive early financing, and investors recover capital as drafts mature. That money could finance the next round of transactions, potentially giving suppliers more flexible access to funding without relying on a single lender. Each draft would still carry its own credit risk, but the financing network could operate more like a revolving pool of capital.
In 2018, PrimeRevenue reported US$1.78 billion in ETD financing, helping nearly 1,000 suppliers across 13 countries get paid early. The program involved 14 banks and more than 100 corporate buyer programs, showing that ETDs were already being used internationally well before the Solana initiative.
PrimeRevenue currently connects corporate payment obligations with established funding institutions. Tokenization could allow other eligible investors to finance or acquire interests in those obligations, depending on how the legal structure is implemented. Solana would provide a shared record of issuance, transfers and settlements, while PrimeRevenue continues supplying the corporate relationships and transaction activity.
PJ Bain PrimeRevenue CEO described the intended expansion in the company's announcement:
"It creates new pathways to unlock working capital and liquidity for our customers and funding partners."
A bank might gain another way to distribute its exposure instead of holding every draft until maturity. New investors could gain access to corporate credit with defined payment dates. Suppliers could benefit if competition among funding providers improves pricing or financing availability. None of these benefits is established until investors commit capital and completed transactions demonstrate the economics.
PrimeRevenue still needs to clarify what investors would actually own, how they would receive payments and what happens if a corporate buyer fails to pay. Holding a token on Solana doesn't automatically give an investor the legal right to collect the underlying debt. Investors would also need to consider whether they could sell their holdings before payment is due.
The bigger opportunity is bringing more investors into trade finance, not simply processing transactions faster. PrimeRevenue already connects corporate buyers, suppliers and banks. Tokenization could open that network to additional investors, giving suppliers access to more funding options and potentially better rates.
Unlike Fission's tokenized fund liquidity model, which helps investors access cash from existing fund holdings, PrimeRevenue is bringing corporate payment obligations to new funding markets. Both use tokenization to connect financial assets with capital, but they serve different financing needs.
Canadian businesses face similar working capital pressures. Payments Canada's 2026 research found that 37% of surveyed small and medium businesses consider payment delays a significant problem. Recent Canadian SME financing initiatives are expanding access to smaller loans and more flexible supplier payments. Tokenized ETDs could offer another option, especially for suppliers selling to large, creditworthy corporate customers.
Canadian banks, commercial lenders and financing platforms could eventually use similar models to connect corporate payment obligations with a wider pool of investors. This could give suppliers more financing choices while opening new opportunities for lenders and financial technology providers.
PrimeRevenue describes the Solana initiative as its first step toward decentralized finance (DeFi), connecting traditional trade finance with new blockchain funding markets.
PrimeRevenue already has the corporate customers, financing network and bank relationships to bring trade finance assets to new investors. Solana could help attract more capital and give suppliers better financing options. Can PrimeRevenue turn tokenized trade finance into a larger, more competitive funding market that delivers real value to businesses?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 15, 2026 | Market Activity | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization, Wealthtech Investing And Trading
On October 15, 2026, New York fintech Fission announced a US$10 million Series A financing led by Pantera Capital to help investors sell tokenized fund holdings before their normal withdrawal dates. Circle Ventures, Borderless Capital, New Form, gumi Cryptos Capital and GTS CEO Ari Rubenstein also participated. Fission is building a business around buying investments from people who don't want to wait months to get their money back.
The round closed in September and follows a US$1.6 million pre-seed financing in Oct 2024. Fission plans to add more supported funds and increase the capital available for investor purchases. Its valuation and committed buying capacity haven't been disclosed.
Private investment funds often limit when investors can withdraw money. Some offer quarterly redemption dates, while others require approval before an investor can sell to someone else. Representing fund shares as digital tokens can make transfers easier, but investors still need an eligible buyer willing to pay for them.
Fission provides that buyer for supported investments. An eligible investor connects a digital wallet and requests a sale. Fission arranges the purchase and handles the required transaction steps. The investor receives cash before the fund's normal withdrawal date, while the buyer takes on the wait and the investment risk. The fund doesn't have to sell its underlying assets to complete that investor's early exit.
Founder and CEO Jonathan Shaffer told Fortune that an exit which might normally take about 200 days could settle through Fission in 90 seconds or less, for a fee. In August, Centrifuge introduced Fission liquidity for four tokenized funds linked to investment strategies from New York Life Investment Management, Apollo and Janus Henderson. The products include high yield corporate bonds, diversified credit, highly rated collateralized loan obligations and short term U.S. Treasuries.
Eligible holders can receive USDC, a stablecoin linked to the U.S. dollar, while the funds continue their usual settlement and withdrawal schedules. Those schedules range from the next business day to quarterly. For investors holding the Apollo diversified credit product, that could mean receiving money through Fission rather than waiting for the next quarterly redemption.
Shaffer described Fission's role in Centrifuge's announcement as providing "an independent liquidity layer" across different investment strategies. The company says it has processed millions of dollars in transactions, but hasn't published an exact total, transaction count or average price paid to investors. The four fund integrations show a working commercial application. They don't establish how much liquidity Fission can provide at scale.
Getting money out early has a price, and it varies considerably by fund. Research published in September 2026 estimated Fission's fees at 5.70% for Apollo's ACRDX diversified credit fund, 0.34% for New York Life's HYB high yield bond fund and just 0.02% for Janus Henderson's JTRSY Treasury fund. On a $10,000 holding, that means an estimated cost ranging from $570 to $2. These were estimates as of September 17, not fixed or guaranteed prices. The difference reflects the cost and risk of providing cash before the underlying investments settle.
That trade could appeal to an investor facing an unexpected cash need. For someone who can afford to wait until the next redemption date, paying for an earlier exit may make less sense. The service has to offer a price investors will accept while leaving enough return to compensate whoever supplies the cash.
There is also risk between the sale and the buyer's eventual exit. A fund's investments could fall in value. Withdrawals could be delayed during difficult markets. Some fund interests may require approval before being transferred. The buyer needs to understand those restrictions and price them correctly before committing capital.
Fund managers have a different concern. An outside buyer can provide liquidity without forcing the fund to sell assets early, which could make the investment more attractive to customers. But repeated sales at steep discounts could undermine confidence in the fund's reported value. Managers will want to know how Fission prices transactions and whether those prices reflect the need for quick cash or problems with the investments themselves.
Fission's growth will also depend on how much capital it can put to work. A fast sale of a small holding is one thing. Handling many large investor exits during a market downturn is a different test.
Fission's founders bring experience from institutional investing and digital securities. CEO Jonathan Shaffer previously worked at Point72, while cofounder Steve Bendit worked at Securitize. They know that making an investment easier to buy doesn't necessarily make it easier to sell. Fission's business depends on finding buyers, securing enough capital and offering prices investors will accept.
Existing tokenized fund operations already need to handle ownership records, investor eligibility and transfer restrictions. Fission must work within those rules while financing earlier exits. For Canadian private credit funds and alternative investment platforms, that could help attract investors who are reluctant to lock up their money. Any Canadian offering would still need to comply with securities laws and fund transfer requirements. Fission hasn't confirmed that its service is available in Canada.
Fission's opportunity isn't making private funds digital. It's making them easier to exit. If the company can consistently find buyers, offer fair prices and manage the risk of holding investments until redemption, it could remove an important barrier to private market investing.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 20, 2026
Following crypto live news today starts with knowing what changed, then checking the prices and discussion around it. This edition brings together two recent developments, a timestamped Bitcoin, Ether and Solana price snapshot, and practical ways to read charts and choose coverage. The figures are observations from October 22, 2026; the linked resources let you continue checking as the story develops.
The news check below was completed on October 22, 2026, at 03:12 UTC. It covers two selected developments, rather than claiming to summarize every event in the market. For readers in Toronto, that cutoff falls on the evening of October 21. Dates should travel with a headline when it crosses time zones.
The Solana Foundation's Alpenglow update reports that the new consensus protocol is live on mainnet, following activation in epoch 1064 on October 21. Consensus is how validators agree on transaction order and finality: when a transaction is treated as irreversible. The Foundation describes roughly 150 milliseconds as the target finality, not a guarantee for every user's transaction.
The rollout also has a boundary worth retaining in a short summary. The voting component, Votor, is live; the separate block-distribution component, Rotor, is planned for a later release. Describing the entire roadmap as completed would overstate the update. For market readers, a technical milestone gives SOL a specific development to investigate, but does not establish what its price should be.
CME's listing notice identifies October 19, 2026, as the trade date for Bitcoin Cash and Uniswap futures, including Micro versions. Its current product page marks the contracts as live. This is a derivatives development, distinct from buying BCH or UNI outright on a spot exchange.
The distinction changes how a headline should be read. More instruments can give participants additional ways to express or hedge exposure; they do not demonstrate fresh net buying of the underlying token. Canadian readers should also distinguish a U.S. product listing from permission to access a particular service in their province.
For further reporting, browse crypto live news today on OnCoin, then follow each consequential claim to its announcement or filing. A story about a network upgrade needs different evidence from a story about an exchange listing. Keep those sources separate when several headlines arrive together.
Here is a saved snapshot from Coinbase Exchange's public ticker endpoints, collected between 03:05:42 and 03:05:47 UTC on October 22, 2026. Each row is a last trade on that exchange in U.S. dollars. The rows were collected sequentially, not at one perfectly synchronized instant.
| Spot pair | Last trade, USD | Trade time, UTC |
|---|---|---|
| BTC-USD | $82,812.25 | 03:05:40.943 |
| ETH-USD | $2,438.96 | 03:05:43.889 |
| SOL-USD | $105.52 | 03:05:42.839 |
These are historical observations once printed, not executable offers or an automatically refreshing feed. The ticker endpoints return newer observations when queried again. A single quote cannot establish the day's trend or show whether either news item above moved the market.
The same data illustrates why price labels matter. In the ETH response, the last trade was $2,438.96, while the best bid was $2,439.06 and the best ask $2,439.11. The last trade records a completed transaction. Bid and ask describe the best displayed buying and selling prices at the snapshot, which can move before another trade occurs.
The displayed spread was therefore $0.05. That is not the full cost of an order: fees and available quantities still matter. A larger purchase may reach higher offers, while a larger sale may reach lower bids. Coinbase's ticker documentation identifies these fields separately, making it possible to check what a quoted number represents.
Do not mix USD, CAD and USDT figures when comparing screens. USDT is a dollar-linked token, not the same instrument as U.S. dollar cash. Even when two figures look close, the venue, trading pair and observation time must match before their difference means much.
A chart is useful when it helps answer a specific question: did the move begin before the announcement, continue afterward, or fade? Start with an asset you can identify and an event time you can support. Opening a chart without that question makes it easy to find a pattern that fits whichever explanation you already prefer.
If you need a live cryptocurrency graph, start with OnCoin's market overview and open the relevant asset detail page. Check the available interval and price series. If that view cannot show the historical window you need, use a chart that can; a present quote cannot reconstruct yesterday's trading.
Work through the comparison in this order:
Candlesticks summarize the opening, highest, lowest and closing prices within a selected interval, as described in Coinbase's chart overview. A candle still forming has not reached its final close. Avoid comparing that unfinished observation with a completed candle as though both were settled results.
Consider a hypothetical token trading at $2.00 before a headline reaches your feed, then $2.10 when you open the report and $2.12 five minutes later. The move from $2.00 is 6%; the move from $2.10 is about 0.95%. Choosing the earlier baseline makes the apparent reaction much larger. Without the original announcement time, neither calculation identifies the event's effect.
Volume can help show whether activity increased during the interval. It does not reveal traders' motives. Keep its units and venue coverage consistent, particularly when comparing a spot chart with derivatives activity.
Choose coverage according to the question you need answered. Community discussion is useful for asking a host to explain a term or show a source. An issuer's technical presentation is better suited to understanding its own release. Newsroom video can provide interviews and editorial context, though a recorded segment is not current simply because its topic remains in the headlines.
OnCoin's crypto category is one place to watch crypto live, with navigation for live, upcoming and replay content. Check the session date and status before relying on a statement about what is happening now. This is a route to discussion, not an endorsement of every host or a promise that a relevant session is always broadcasting.
For newsroom coverage, CoinDesk's video hub lists formats including CoinDesk Daily and Markets Outlook. Read each segment's date and subject. For the network story above, the Solana Foundation's upgrade page also links to its own Alpenglow explainer. That material can clarify the design, while remaining an interested party's account rather than independent investment analysis.
During a stream, ask a concrete question: “Which document confirms that this part has launched?” or “Which pair and interval are on screen?” Answers that lead back to something you can inspect are more useful than a confident price prediction. Holdings, sponsorship and affiliate arrangements belong in your assessment of a speaker's recommendations.
A genuine account can also distribute a false claim. The SEC's January 12, 2024 incident statement documents an unauthorized approval post on its X account three days earlier. For consequential regulatory news, check the formal record rather than stopping at account identity or a screenshot shown on air.
Read the announcement before explaining the price move. Keep the same pair and interval when comparing charts, and choose coverage that helps answer the questions the document leaves open. That gives you a clearer account of an event without requiring an instant market prediction. Accurate news can still be followed by losses, illiquid trading or implementation problems. Keep its sources and dates attached when sharing an update, and revise your account if the evidence changes.
Public announcements, many market pages and some streams can be read without placing a trade. Access and account requirements vary by service. Use the publisher's known website, and avoid signing a wallet message or sending funds merely to read a report. There is no need to create financial exposure to investigate a headline.
Check the displayed observation time, the venue's service-status page and a second independent source. A frozen number does not mean the market has stopped moving. Avoid treating a stale quote as an opportunity until you understand whether the problem is your connection, the data display or the trading venue.
Post the correction where the original audience can see it, identify what changed and link to the supporting record. Remove malicious links when necessary. Quiet deletion may leave earlier readers unaware of the error, especially if they copied the claim into another conversation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 15, 2026 | Cryptocurrency, Digital Assets, Crypto Exchanges, Market Analysis
Searching for top crypto exchanges by volume is a sensible way to find active venues, but it is a poor way to finish an exchange comparison. A volume number describes recorded turnover during a chosen interval. It does not tell a reader whether the pair they need is deep, whether the displayed price is executable, or whether the venue's terms fit their country and use case. This article looks at the gap between a busy platform and a usable market. It is not a platform ranking or a recommendation to deposit funds.
Volume counts transactions over a specified period, commonly in a quote currency. Activity can improve price discovery and provide more observations, but the number is affected by pair mix, spot or derivatives coverage, fee incentives, and the data provider's method. Two valid rankings can disagree simply because they count different things.
The top crypto exchanges by volume page is useful for making a shortlist. Before reading an order as a recommendation, check the interval, products included, quote currency, and venue coverage. A venue's total may include markets that a reader cannot access, or a product that is irrelevant to the intended task.
Execution lives at the pair level. A venue can be busy overall while a smaller asset has a wide spread and a thin book. The reverse is possible too: a modest venue may be the active place for a particular local-currency pair. Daily turnover is a record of past activity; depth and spread describe what is available near a price now.
The timing gap matters. A 24-hour volume figure and a spread observed this minute are different snapshots. A listing, service interruption, or regional session change can alter the relevant market between them. Record access times, and treat the lack of pair-level timestamps as a real limitation rather than filling it with an assumption.
A city analogy is useful here. A crowded city does not mean every street is open or easy to reach. Aggregate volume describes the city. The route that matters is the actual pair, product, order size, and time of day.
Consider a reader who wants to exchange a less widely traded asset for a local currency. A venue can sit near the top of an aggregate table because its major pairs and derivatives markets are active, yet the relevant local pair may have only occasional trades. The displayed total has not become false; it simply answers a different question. The reader needs to see the current bid and ask, the amount available close to each, the fee schedule, and any transfer or account restrictions that apply before treating the ranking as useful evidence.
This is where a small test order is sometimes discussed, but it is not a universal answer. Fees, withdrawal conditions, eligibility rules, and asset-transfer risks may make a test impractical or expensive. The broader point holds without one: a platform-wide figure should lead to pair-level research, and the details that determine execution should be current when the decision is made.
When a market moves, one venue may print a new trade before an aggregate page catches up. Market makers and arbitrage can narrow the gap, but they do not remove delays, fees, transfer constraints, or regional frictions. Differences can become more visible during fast conditions.
Comparing crypto market prices with a venue quote starts with matching the asset and quote currency. Then identify each number: last trade, bid, ask, midpoint, index, or derivatives mark. A $100 last trade beside a $99.60 bid and a $100.40 ask is not the same observation as a $100 midpoint.
Consider an illustrative snapshot. An aggregate index reads $99.80, while a venue's last trade is $100.30. The venue currently bids $99.90 and asks $100.40. That gap may simply be a trade near the upper edge of a spread. It deserves more scrutiny when it persists across several liquid venues, widens as the market moves, or prevents execution near the displayed quote. Even then, the observation is stronger than any untested accusation about its cause.
Price differences also change how a volume figure should be read. A large total in a pair that repeatedly trades away from other references may call for questions about methodology, concentration, and extraordinary-condition handling. It does not justify declaring that a venue is manipulating prices.
Trading communities influence attention long before an analyst writes a conclusion. A useful discussion may locate an outage notice, explain a technical change, or point to a user report that can be checked. The same social momentum can turn a ranking into proof by repetition: people choose a venue because it appears popular, and the popularity then becomes part of the story.
The phrase web3 social networks covers posts, group chats, live conversations, and creator-led communities. Their strongest use is often discovery and debate. A good contribution names its source, separates fact from opinion, and makes room for correction. A repeated referral code, screenshot, or confident price target does not become independent evidence simply because more accounts repeat it.
Online chatter can improve research when it leads to a service notice, a documentation update, or a detailed report with reproducible steps. It becomes harder to assess when incentives are hidden. Affiliates, project teams, market makers, and ordinary users can all emphasize a venue for different reasons. The answer is not to dismiss every comment; it is to make the incentive part of the reading.
Use sentiment to find questions. If many users mention withdrawal problems, check the venue's status page, terms, incident notices, and whether the disruption is regional or platform-wide. If a community celebrates volume, ask which pairs produced it and whether those pairs are relevant to the reader's task.
Crowd activity can be especially misleading when people share the same screenshot. A volume badge, a single trade print, or a price chart can spread quickly through a group, making one observation look like many independent reports. Look for different kinds of evidence instead: a timestamped status notice, a pair-level order book, a record from another venue, or documentation that explains a product change. Agreement becomes more meaningful when the sources are not all repeating the same original image.
For preliminary research, work through the following order. It keeps a single market metric from doing the work of an entire due-diligence process.
The highest total may be useful for observing a busy market. Another venue may offer the relevant pair, local access, or clearer operating terms. The right conclusion depends on the use case and evidence, not on the position of a row in a table.
For comparison writing, it also helps to keep an awkward result in the note rather than smoothing it away. A high-ranked venue may have the pair but a spread that is wider than a reader expected. A lower-ranked venue may show better visible depth at the moment, yet have conditions that require additional verification. Reporting both observations is more useful than forcing them into a single winner. Markets change by the minute; an honest comparison identifies the measured conditions and leaves room for them to change.
Volume says little about custody, account security, legal protections, tax treatment, or operational continuity. A venue can report substantial activity while its policies change, a product becomes unavailable, or access differs by region. Public rankings also update on their own schedule.
Liquidity is conditional. A tight spread in calm conditions may widen during news, and an order book that looks deep can thin as a larger order consumes visible levels. Compare the depth near the relevant price with the intended order size and urgency. Visible orders can also be cancelled, so a screen is not a promise of execution.
The careful takeaway is modest: use volume to locate research targets, then inspect the pair, the price definition, the operating terms, and the applicable rules. An aggregate ranking cannot establish that a venue is appropriate for a particular person or transaction.
No. The relevant price depends on the pair, quote currency, side of the market, order size, fees, and execution time. A high-volume venue can be competitive in one market and less useful in another.
No. It describes market activity, not custody arrangements, cybersecurity, legal compliance, solvency, or customer protections. Those questions need separate evidence and can vary across entities and jurisdictions.
They may use different venues, intervals, currency conversions, and price definitions. A last trade can also sit away from a current bid or ask. Compare methodology before calling the difference an error.
Treat it as a lead. Check the venue's official status page, timestamps, independent reports, and which product or region is affected. Do not share credentials, keys, or urgent instructions based on an unverified post.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016