

Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 28, 2026 | NCFA Insight | Regulation And Policy, Capital Markets And Market Infrastructure, Wealthtech Investing And Trading, Risk Compliance And Regtech
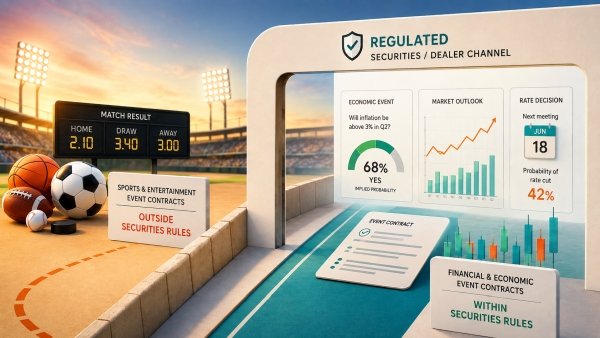
On August 27, 2026, the Canadian Securities Administrators (CSA) and Canadian Investment Regulatory Organization (CIRO) issued new guidance on sports and entertainment event contracts. The CSA says those contracts belong outside securities and derivatives regulation, and CIRO will not approve dealer members to trade them.
The decision closes the securities-dealer route without banning every sports prediction market category under every Canadian law. Gaming and other applicable rules can still determine what is permitted elsewhere, but Canadian investment dealers now know sports and entertainment will not join the event contracts they can distribute through CIRO.
CIRO currently allows two investment dealers, Wealthsimple Investments Inc. and Interactive Brokers Canada Inc., to facilitate a limited set of contracts tied to economic forecasts, environmental outcomes and financial indicators. Permitted contracts generally need at least 30 days to maturity, clients cannot use leverage, and elections, referendums, political nominations and other political events remain prohibited.
In the U.S., sports category helped prediction markets reach a much larger audience. Prediction Markets Tighten As Wealthsimple Enters noted in March that a March Madness winner contract had already exceeded US$100 million in volume and 2026 Super Bowl contracts topped US$1 billion. Canada is now explicitly removing that demand interest from the securities-dealer channel.
That leaves economic, environmental and financial contracts to prove they can generate repeat participation and enough liquidity to remain useful. Rates, inflation, housing and climate outcomes can carry real forecasting value, but they don't naturally produce the same frequency, fan interest or habitual trading as professional sports.
Platforms are also experimenting with how prediction markets are presented. CRSHMARKET's livestream prediction-market model combines live video, creators and event contracts to make participation more immediate. That doesn't change Canada's regulatory limits, but it highlights why product format is important to growth if permitted contracts have to compete for attention without sports.
A contract within CIRO's permitted categories can potentially reach Canadian clients through an authorized investment dealer, while sports and entertainment contracts cannot use that route. Product teams therefore need to understand the event being priced, the applicable regulator and the distribution rules before estimating the addressable market.
As a result, the need for regulated event contract infrastructure is more valuable. Platforms need compliance controls, market surveillance, outcome verification, settlement and dealer integration, but they also need to know which contracts can be offered through which channel.
Infrastructure providers that help firms classify products, apply the right controls, integrate regulated distribution and settle outcomes can serve multiple markets even when the permitted contract set differs by jurisdiction.
CSA and CIRO say they are still assessing other types of event contracts. They haven't said which additional categories may eventually fit inside securities and derivatives regulation or which will remain outside it.
Those decisions will help determine the size of Canada's regulated prediction-market business. If CIRO dealers remain concentrated on economic, environmental and financial indicators, the sector may develop mainly as a forecasting and investment product. Additional permitted categories could create more reasons to trade and more opportunities for liquidity to build.
Regulators still need to consider market manipulation, insider information, outcome integrity and whether a particular event belongs inside financial regulation at all.
Can Canadian prediction markets build enough liquidity around economic, environmental and financial events without the sports contracts that helped drive U.S. adoption?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |

August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
Leave a Reply