





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Sep 2, 2026
India is increasingly relevant to fintech companies for more than market access. It is also a significant source of technology, product, finance, risk, data, and operational talent that global scaleups can integrate into international teams.
India's wider startup ecosystem had more than 2.23 lakh government-recognised startups by March 31, 2026, while the country's digital financial infrastructure continues to expand rapidly. UPI alone processed more than 24,000 crore transactions during FY26, illustrating the scale at which digital financial services now operate in the country.
For a Canadian or international fintech, however, deciding to recruit in India creates a strategic question:
Should the company establish an Indian entity before building a team, or can it begin hiring first and make the larger corporate investment later?
For many scaleups, these decisions do not need to happen simultaneously.
A phased talent strategy can allow a fintech to test access to Indian talent, build an initial team, understand operating costs, and validate its long-term requirements before committing to a full local entity.
India combines a large technology workforce with an established ecosystem across financial services, digital payments, software development, data, and startup innovation.
This creates hiring opportunities across functions that fintech companies frequently need as they scale, including:
India's digital payments ecosystem also gives fintech professionals exposure to financial products operating at substantial scale. UPI accounted for 85.5% of India's digital payment transaction volume in the second half of 2025, according to RBI data reported by IBEF.
But the business case for building a team should not begin with the question, "How many people can we hire?"
It should begin with:
Which capabilities should the company own internally, and which of those capabilities can be built effectively in India?
That changes hiring from a cost exercise into a talent strategy.
A fintech talent strategy defines which capabilities a company needs, where those capabilities should be located, and how employees will be hired, managed, and integrated into the organisation.
For an India expansion, a useful talent strategy should address five areas:
This is particularly important for fintech companies because many roles interact with sensitive financial data, regulated products, security systems, or customer operations.
Hiring should therefore be considered together with data access, information security, governance, internal controls, and business continuity.
The first India hires should solve clearly defined business problems rather than simply expand headcount.
A practical approach is to prioritise functions where the company already understands the workflows and can manage outcomes remotely.
| Function | Why a Fintech May Build It in India |
| Engineering | Product development, integrations, platform infrastructure |
| Data | Analytics, reporting, data engineering and modelling |
| QA | Product testing, automation and release support |
| Cybersecurity | Security operations and technical monitoring |
| Finance operations | Reporting, reconciliation and operational support |
| Customer operations | User support and service delivery |
| Risk operations | Process-driven risk and verification support |
| Product operations | Coordination between technology, product and commercial teams |
Leadership should also identify whether the function is supporting the global business or conducting activity directly in the Indian market.
That distinction can affect entity, regulatory, tax, and Permanent Establishment considerations later.
Yes, depending on the type of relationship and business activity.
A foreign fintech typically has several potential models available.
Contractors may be appropriate for genuinely independent, project-based work.
For example, a fintech might engage a specialist for:
Contractors should not simply be used as substitutes for employees where the actual working arrangement functions like regular employment.
A fintech can outsource a complete function or defined process to another company.
In this model, the external provider typically manages its own employees and delivers an agreed service or outcome.
That is different from building a dedicated internal team.
Where a fintech wants dedicated employees in India but does not yet have a local employing entity, an Employer of Record India model can provide another option.
The EOR becomes the legal employer in India, while the fintech continues to manage employees' daily responsibilities, goals, projects, and performance.
A fintech can establish its own Indian company and employ staff directly.
This generally provides greater long-term control but also introduces ongoing corporate, accounting, payroll, HR, tax, and administrative responsibilities.
The best structure depends on the company's stage and objectives.
| Factor | Contractor | Outsourcing | EOR | Own Entity |
| Dedicated employee relationship | No | Usually no | Yes | Yes |
| Local entity required | No | No | No for EOR employment | Yes |
| Client controls daily work | Limited by independent relationship | Usually outcome-focused | Yes | Yes |
| Local payroll | Not employee payroll | Provider handles employees | EOR handles | Company handles |
| Initial setup burden | Low | Low | Lower than entity | Highest |
| Suitable for testing India | Yes, for genuine projects | Yes | Yes | Possible but larger commitment |
| Long-term large workforce | Limited | Depends on model | Depends on scale | Strongest fit |
For a fintech building an internal product or operations team, the main comparison is often between EOR employment now and direct employment through an entity later.
Entity establishment is a strategic corporate decision.
Hiring can be an operational decision.
Those decisions may move at different speeds.
Suppose a Canadian fintech has funding to build a six-person engineering and data team in India. It already knows the roles it needs, but management is not yet certain whether India will eventually support 10 employees, 50 employees, or a much larger operation.
Immediately building a company around an uncertain headcount assumption can create unnecessary fixed infrastructure.
A staged approach allows the fintech to answer questions such as:
The business can then make its entity decision using operating evidence rather than projections alone.
Salary is only one component of India workforce costs.
Finance teams should compare the total cost of different structures.
Relevant categories can include:
An EOR may involve a per-employee service fee, while an owned entity introduces more fixed organisational costs.
The economics can therefore change as the team becomes larger.
Companies comparing these structures can also review State of India EOR 2026 when assessing employment costs, entity considerations, compliance responsibilities, and potential tax exposure.
Fintech teams often work within more sensitive operating environments than ordinary remote teams.
The question is not simply whether a developer or analyst can work remotely.
Companies may also need controls around:
Employees may interact with customer data, financial information, transaction records, or internal risk systems.
Access should be based on role requirements.
Devices, authentication, credentials, source code, and internal platforms require appropriate security controls regardless of where employees are located.
Certain finance or payment workflows may require multiple layers of approval rather than giving one employee end-to-end control.
Teams should understand who owns decisions, where approvals are recorded, and how processes are audited.
Hiring someone in India does not itself determine whether the fintech is permitted to offer regulated financial services in India.
Employment structure and financial-services licensing are separate questions.
A company building an India team to support overseas operations should therefore distinguish workforce expansion from market entry.
India's four consolidated Labour Codes came into effect on November 21, 2025, covering wages, industrial relations, social security, and occupational safety and working conditions.
Companies employing workers directly need processes covering relevant employment requirements, including areas such as:
Under an EOR structure, many agreed employer-side administrative responsibilities are handled by the EOR.
However, using an EOR does not remove the fintech's responsibility for how employees access systems, handle information, perform regulated activities, or represent the business.
Potentially, depending on what the employees do.
An EOR or contractor arrangement does not automatically eliminate Permanent Establishment or wider business-connection considerations.
India's Income Tax Department states that business income of a non-resident can be taxable in India where the enterprise has a Permanent Establishment or business connection, subject to applicable tax treaties.
Indian tax rules also identify activities such as habitually concluding contracts or playing a principal role leading to the conclusion of contracts as potentially relevant to business-connection analysis.
A fintech should therefore obtain appropriate tax advice where India-based personnel:
A developer supporting a global product and a senior commercial executive entering contracts on behalf of the foreign company may present very different risk profiles.
An entity can become increasingly attractive as India moves from an experimental talent location to a strategic operating hub.
Common indicators include:
There is no universal employee number at which every fintech should incorporate.
The decision should consider scale, cost, tax, regulation, employment requirements, business activity, and long-term strategy together.
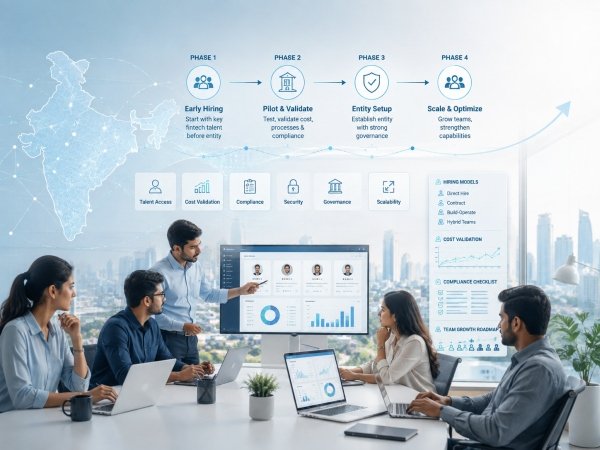
A practical expansion sequence can look like this:
Identify the roles that India can support and the business problem each role solves.
Recruit a small number of clearly defined roles using an appropriate employment structure.
Implement security, communication, management, documentation, payroll, and performance systems.
Compare productivity and total employment costs against the original business case.
Estimate whether the India operation is likely to remain a small global team or grow into a major operating centre.
Once the scale and commercial requirements are clearer, evaluate establishing a local entity.
This approach allows a fintech to treat entity setup as a consequence of proven scale rather than a prerequisite for exploring Indian talent.
For fintech companies that want employees in India before establishing their own entity, Asanify provides an India-focused Employer of Record model.
Asanify operates through its own Indian entity and can act as the legal employer while the client fintech retains control over employees' daily work, responsibilities, and performance.
Its EOR support can include:
This structure can be useful for scaleups testing the Indian talent market or building an initial team while their long-term entity strategy remains under evaluation.
Tax, regulatory, financial-services licensing, PE, data, and other business-specific risks should still be assessed separately.
For fintech scaleups, India expansion should start with the capabilities the business needs, not with entity setup.
Companies can first define the right roles, choose a suitable employment model, and validate costs, compliance, and team performance. This gives leadership a clearer view of how India fits into the wider operating strategy.
As the team grows, the business can then decide whether a larger local infrastructure or entity is justified. A phased approach helps keep early expansion flexible while supporting more informed long-term decisions.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply