
Global fintech and funding innovation ecosystem

Learn About Fintech and Funding in Canada

Interested in learning about financial innovation and the future of financial services?

Curated News, Insights, Regulation: Fintech, Blockchain, Peer to Peer, AI, Alternative Finance

Fintech and Funding Industry Advocacy

FINTECH FRIDAY$ Podcast (weekly)

Canadian Fintech Director and Networking Platform

Industry Reports and Research

Entrepreneurship

Innovation

Raising Equity and Funding Your Startup

Social and Community Impact

Video Library

Alternative Finance in Canada report

Conferences and Services Marketplace


The National Crowdfunding & Fintech Association of Canada (NCFA Canada) is a cross-Canada non-profit actively engaged with fintech, alternative finance, blockchain, cryptocurrency, crowdfunding and online investing stakeholders globally. NCFA Canada provides education, research, industry stewardship, services, and networking opportunities to thousands of members and subscribers and works closely with industry, government, academia, community and eco-system partners and affiliates to create a strong and vibrant crowdfunding and fintech industry. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights

Aug 29, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Competition And Market Structure, Regulation And Policy, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Cross Border Payments And FX, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Payments Infrastructure And Money Movement This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors.  This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis.  (Missed prior week's Fintech Whisperer?  (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May ...
Image Freepik, Data visualization signals
September 4, 2026 | NCFA Insight | Digital Identity And Trust, Digital Assets Blockchain And Tokenization, Regulation And Policy Alternative Naming Systems, DNS Control and a September 21 Deadline On August 10, 2026, ICANN opened a consultation on alternative naming systems that could affect how blockchain based and other naming systems work alongside the global Domain Name System. Comments are open until September 21, 2026 at 23:59 UTC. ICANN is the nonprofit organization that coordinates the global Domain Name System, including the rules for top level domains such as .com, .org and newer gTLDs. The consultation matters most to domain registries, Web3 naming providers, digital identity firms, wallet and payment companies, cybersecurity specialists and brands that could be affected if the same name appears across multiple naming systems. ICANN is dealing with a problem that did not exist when the DNS was designed. Alternative naming systems can create names outside the global DNS, while registry operators and potential applicants in the 2026 New gTLD Program are now interested in using some of the same top level strings in both systems. If that happens, users need confidence that the same name is controlled by the same party wherever they encounter it ...
AI Image – DNS and blockchain naming systems separated by an interoperability gap
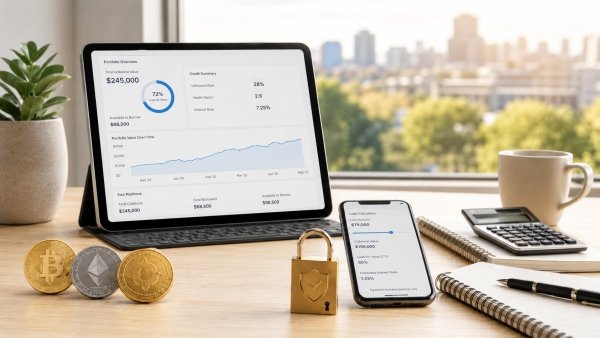
September 4, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Digital Assets, Embedded Finance Revolving Crypto Credit With 60% LTV and Partial Liquidation On September 3, 2026, Toronto-based APX Lending launched a five-year crypto-backed line of credit that lets eligible borrowers pledge Bitcoin, Ethereum or both, draw funds, repay them and borrow again. APX says the facility supports borrowing up to 60% loan to value, with annual rates from 10.49% to 11.99% depending on the outstanding balance. Interest applies only to money actually borrowed, with no charge on unused capacity. APX also says there are no origination, prepayment or liquidation fees. The biggest change from APX's existing fixed-term loans is that borrowers can use the credit line more than once. They can keep approved collateral in place, draw funds when needed, repay them and borrow again. Three Takeaways 1. Bitcoin and Ethereum Can Support Repeat Borrowing APX gives the example of C$200,000 of Bitcoin and C$100,000 of Ethereum supporting up to C$180,000 of borrowing at the maximum 60% LTV. Available credit changes with the value of the collateral, so a falling crypto market can reduce borrowing capacity quickly. The basic idea will be familiar to anyone who ...
AI Image – Crypto-backed line of credit dashboard with Bitcoin and Ethereum collateral
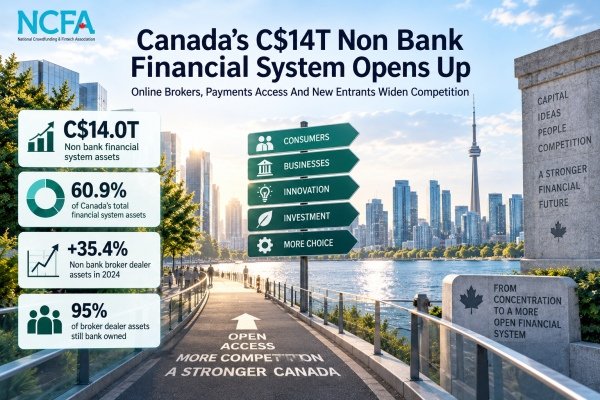
September 3, 2026 | NCFA Story Intelligence | Competition And Market Structure, Banking And Lending, Capital Markets And Market Infrastructure, Open Banking Open Finance And Data Sharing A Huge Non Bank Base Meets Faster Challenger Growth And Wider Market Access On September 3, 2026, Bank of Canada staff released new non bank finance data showing that Canada’s non bank financial sector held C$14.0 trillion in assets at the end of 2024, equal to 60.9% of the financial system. The Bank's broad definition includes pension funds, insurers, investment funds, financial auxiliaries and other intermediaries. Much of the 2024 increase also came from stronger market valuations. The headline number is only part of the story. Faster growth is appearing in narrower bank like activities, online brokerage and specialty finance, while commercial banks still retain enormous asset and distribution advantages. Canada already had a huge financial system outside deposit taking banks. What's changing is how customers reach it, where credit can originate and how many firms can compete for data, payments, investing and banking services. C$14.0T Non bank assets 60.9% Share of financial system assets 34.5% Commercial bank share +12.1% Narrow NBFI assets +35.4% Non bank broker dealers 95% Broker dealer assets still ...
NCFA Story – Canada C$14T non bank financial system with online broker growth and wider financial access
September 3, 2026 | NCFA Story Intelligence | Artificial Intelligence And Data, Competition And Market Structure, Fintech And Innovation Nvidia Buys Hugging Face As Open Source AI Faces A New Owner On September 3, 2026, Nvidia announced a definitive agreement to acquire Hugging Face for US$12.9303 billion. The deal would put one of the biggest platforms for open source and open weight AI alongside the company that already dominates much of the market for AI computing. The price includes about US$11.9 billion for Hugging Face stockholders and up to US$1 billion in equity awards for employees joining Nvidia. The transaction hasn't closed. Nvidia says it expects completion in the first half of 2027, subject to regulatory approvals and other closing conditions. Nvidia is making a very public promise with the deal. Hugging Face will remain open. Developers will still be able to choose their models, clouds, inference providers and computing platforms. Nvidia hardware will not be required. That promise goes directly to the tension. Hugging Face became valuable because developers, startups, researchers and rival chip companies could all build there. Nvidia can make that ecosystem stronger. Ownership can also make some of those same users wonder whether an open source ...
AI Image – Nvidia buys Hugging Face as open source AI faces new ownership and competition
Sep 3, 2026 Some buy now, pay later activity reaches Canadian credit files. Most routine instalment plans currently do not. That is the short answer, and the qualifications matter more than the answer does. Whether a buy now, pay later arrangement appears on a credit file in Canada depends on the provider, on which credit bureau is involved, on whether a payment was missed, and on the month in which the question is asked. Payments made on time and payments missed follow different routes. Two people financing identical purchases through different providers may find entirely different records. What follows sets out what is reported, by whom, to which bureau, and with what effect on a score, then explains why the answer is this unsatisfying. The position described reflects Canadian reporting as of September 2026, and it is moving. What buy now, pay later actually is The Financial Consumer Agency of Canada describes buy now, pay later plans as arrangements that finance a purchase with credit. Its research characterises the category as covering a wide range of credit arrangements and as generally a type of consumer credit, comparable to instalment lending. That framing is the reason the credit-file question arises at ...
AI Image – Buy now pay later credit report review in Canada with woman shopping online
September 3, 2026 | NCFA Market Activity | Digital Banking And BaaS, Regulation And Policy, Payments Infrastructure And Money Movement Revolut Bank US, 2027 Launch Plans and U.S. Banking Products On September 3, 2026, Revolut received conditional U.S. bank approval from the Office of the Comptroller of the Currency form Revolut Bank US, N.A., a federally chartered national bank headquartered in Stamford, Connecticut. Revolut says it is still working through FDIC, Federal Reserve and final OCC approvals and remains on track for a 2027 launch. U.S. customers cannot open accounts with Revolut Bank US yet. Revolut already serves U.S. customers, but the regulated banking are with other institutions. Lead Bank supports Revolut's prepaid card accounts and banking services, while Savings Vault funds are held at Cross River Bank. Revolut controls the app and customer experience, but those partner banks hold deposits and perform key regulated functions. Revolut says the proposed bank would offer loans, credit cards and FDIC insured deposits, alongside access to stablecoins and cryptocurrencies. Its charter application also describes deposits, savings, business credit, payments, remittances and foreign exchange. Some investment and digital asset services could still sit with affiliates or outside providers rather than inside the bank itself. Revolut ...
AI Image – Digital banking app dashboard with U.S. bank office view
Sep 3, 2026 Anyone who has onboarded a client at a fintech startup knows the bottleneck. The product works, the API integration is done, and then someone emails a photo of a passport taken at an angle in bad light, with half the machine-readable zone cut off. Multiply that by fifty applicants a week and your compliance queue turns into a photo-editing job. Small lenders, brokerages and crypto exchanges all hit the same wall. Identity verification and record-keeping are document-heavy by law, and the documents arrive in whatever format the customer's phone produced. That is the gap a mobile scanner fills. OKEN, listed on the Play Store under the longer name OKEN - camscanner, pdf scanner and published under the name CAMBYTE Pte. Ltd., is a Productivity app that turns a phone camera into a document scanner with edge detection, OCR text recognition, and export to PDF, JPG, Word or TXT. It also reads QR codes, which matters more than it sounds in a payments context. What OKEN Does With a Photographed Document The core loop is straightforward. Point the camera at a page, let the app find the borders, and it flattens the perspective into something that looks like ...
AI Image – Smartphone scanning an invoice to a Windows laptop with OCR text extraction and digital compliance document management
September 3, 2026 | NCFA Market Interest | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Wealth Investing And Trading Payward Revenue Growth, IPO Delay and Its US$20B Valuation Kraken parent Payward has reportedly delayed its U.S. IPO again, this time to the second quarter of 2027 at the earliest. The company confidentially filed a draft registration statement in November 2025, then put the listing on hold in March as crypto prices, trading volumes and valuations weakened. Payward hasn't confirmed the new 2027 timing, so it remains a reported window rather than a scheduled IPO date. The delay comes at an interesting point for the business. Payward reported US$508 million in Q2 adjusted revenue, up 17% year over year. Funded accounts rose 42% to 6.6 million, while assets on the platform were US$40 billion. Adjusted EBITDA was much thinner at US$23 million, and total platform transaction volume fell 18% to US$310 billion as crypto spot trading cooled. Those numbers give Payward a pretty clear reason to wait. Revenue and customers are growing, but the company is still proving how much earnings it can generate when trading activity softens. Going public now would put that question in front of ...
AI Imag – Crypto trading screens with hourglass and 2027 IPO timeline
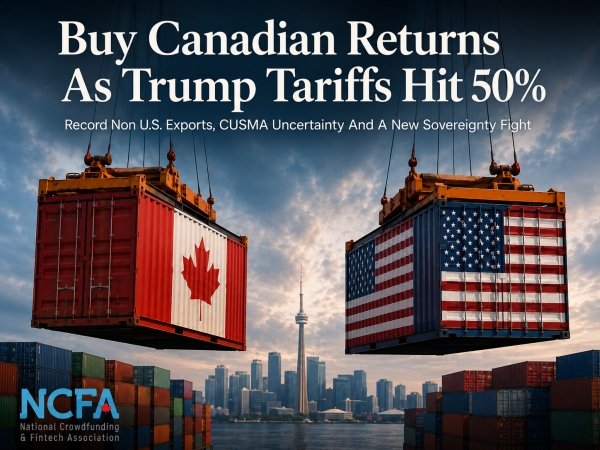
September 3, 2026 | NCFA Story Intelligence | Trade And Tariffs, Canadian Economy, Cross Border Finance, Public Policy Record Non U.S. Exports Meet Retaliation, Stalled Talks And A New Sovereignty Fight On September 3, 2026, Canada's July trade report put two stories beside each other. Exports to the United States fell 6.6%, while exports to countries outside the U.S. rose 7.4% to a record C$25.6 billion. Canada's merchandise trade surplus with the world narrowed from C$4.2 billion in June to C$769 million. Its surplus with the United States fell from C$10.3 billion to C$5.9 billion. Those numbers now sit inside a much rougher political relationship. On August 22, the United States imposed a 50% tariff on roughly US$20 billion of Canadian exports, while the Government of Canada values the affected goods at C$27.6 billion. Canada has rejected the terms on offer and announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8. Canada is still deeply tied to the U.S. economy, but the reaction is no longer confined to government. Buy Canadian sentiment has returned. Companies are reviewing suppliers and customers. Travel choices have changed. More Canadian businesses are looking beyond the U.S ...
AI Image – Buy Canadian Returns as Trump Tariffs Hit 50% showing Canada U.S. trade tensions over shipping containers at Toronto port