





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Fintech | June 18, 2025
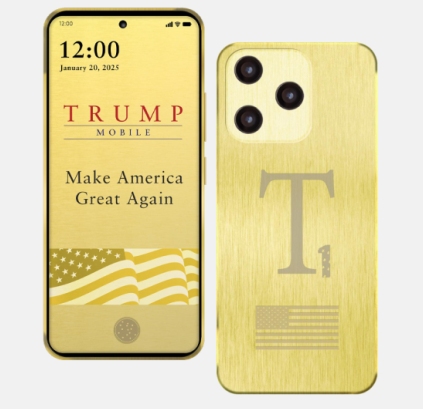
Image courtesy of Trump Mobile website
On June 18, 2025, Fortune reported that Trump Mobile is entering the U.S. wireless market with a $47.45 per month prepaid plan and a smartphone built by Chinese device maker Unihertz. Beyond the political optics, the announcement is interesting from a fintech perspective since Trump Mobile plans to use a telecom backbone to bundle lifestyle services in a way that mirrors embedded finance strategies seen in a variety of global fintech ecosystems.
The T1 smartphone is priced at $499 with a $100 down payment, and is scheduled to ship in late summer 2025. Trump Mobile is powered by Patriot Mobile, an MVNO that leases infrastructure from existing carriers. The business model relies on branding and licensing rather than owning physical networks. This setup closely resembles the way fintechs white label financial infrastructure through APIs and software platforms.
Eric Trump, EVP Trump Organization on Trump Media:
“I'm incredibly excited to step into this new digital space, hard-working Americans deserve a wireless service that's affordable, reflects their values, and delivers reliable quality they can count on. We're especially proud to offer free long-distance calling to our military members and their families — because those serving overseas should always be able to stay connected to the people they love back home. ”
The flagship product is the “47 Plan” offered at $47.45 per month. According to Trump Mobile’s website, it includes unlimited talk, text, and data, plus international calling. The bundled services also include 24/7 telehealth access and roadside assistance, which are traditionally sold separately or through insurance providers. Packaging them into a single mobile bill is a similar approach of fintech super apps.
The T1 phone has midrange specs: a 6.8-inch AMOLED 120 Hz screen, 12 GB RAM, 256 GB storage, a 50 MP triple camera setup, Android 15, a 5,000 mAh battery with 20 W fast charging, USB-C, a headphone jack, and biometric unlocking. The phone is manufactured by Unihertz in China, despite political framing that implied U.S. manufacturing. It unveils global hardware supplier realities that fintechs face when bringing physical devices to market.
According to The Wall Street Journal, the Trump family licenses its name to Patriot Mobile, which operates the network. This approach is similar to how fintech startups offer debit cards, wallets, and investment tools without becoming licensed financial institutions. The infrastructure is external, but the customer relationship is owned by the brand.
There is also a digital asset component. Reuters reported that Trump Media is applying for a cryptocurrency ETF made up of 75% Bitcoin and 25% Ethereum. Even though the potential crypto ETF isn't directly tied to the phone plan just yet, it highlights the Trump brand's ambition to combine lifestyle, media, and financial products.
Ironic as you get that earlier in 2025, the Trump administration slapped a raft of reciprocal tariffs, including a baseline 20% tariff on Chinese-made consumer electronics. According to Al Jazeera, the administration later exempted certain chips and phones but it's unknown which specific products currently qualify. If the T1 is subject to tariffs, the cost could be absorbed by Unihertz, passed to Patriot Mobile, or used to justify higher retail pricing.
Trump Mobile offers a live case study in how embedded services can be sold through telecom. For Canadian fintechs, it opens a conversation about how telcos and startups might partner to deliver subscription-based insurance, health care, or financial tools to underserved communities. Packaging multiple services into a mobile plan can improve customer stickiness, adding to predictable revenue, as also seen in bundled offerings by Koho, Neo, and other Canadian fintechs.
There should be policy concerns however, with potential conflicts of interest involving Trump's family ties to regulatory agencies. Also combining telco infrastructure with consumer finance triggers questions around cross-sector regulation, as regulators will need to consider the risks of a converging telco-fintech model as it grows.
For NCFA members, this launch offers insight into how bundled, cross-platform models can scale quickly with the right partnerships. As Canada expands open banking and explores new models of service delivery in underserved markets, this example shows how telecom-fintech convergence could work, assuming regulators allow it.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply