





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 11, 2026 | NCFA Resource | Open Banking And Consumer Driven Finance, Artificial Intelligence And Data, Competition And Market Structure
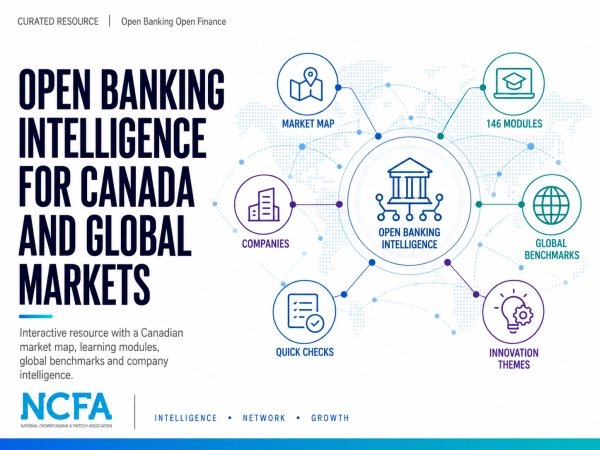
Understanding Open Banking and Consumer Driven Finance means keeping several things in view at once. Canada has proposed regulations and an implementation program underway, other markets already have years of operating experience, and fintechs are testing products around financial data, identity, credit, payments and decisioning.
The NCFA Open Banking & Consumer-Driven Finance Interactive Intelligence resource brings that material into one interactive environment. It is Canada-led, with international examples and global benchmarks where they help explain market structure, implementation choices and commercial activity.
Readers can learn through a Canadian Open Banking Market Map, 146 learning modules, company intelligence, discussions, innovation themes, global benchmarks or Quick Checks (there's even an NCFA arcade perk for completing modules). There is no required starting point.
The Canadian Open Banking Market Map shows who is participating and where different capabilities fit, helping readers identify competitors, infrastructure providers, potential partners and areas of market activity.
The 146 learning modules break Open Banking and Consumer Driven Finance into smaller topics that can be explored individually or in sequence. Quick Checks let readers test what they understand before continuing, making it easier to get current on a specific issue without working through a long report.
Company intelligence connects firms to market categories, technologies and use cases, while discussions and innovation themes explore where new capabilities are developing and where parts of the ecosystem may already be crowded.
Global benchmarks put Canadian developments in perspective. Australia, the UK, Europe and other jurisdictions have tested different approaches to data access, consumer consent, accreditation, payments and competition. Their experience cannot be copied directly into Canada, but it gives Canadian teams evidence to compare against emerging policy and market choices.
Canada’s detailed operating requirements are still being finalized. Worth nothing that NCFA also offers a separate Open Banking Regulatory Intelligence Guide, a dedicated resource for proposed regulations, implementation requirements and regulatory readiness.
Founders and product teams can see where a product fits before committing time and capital, while banks and credit unions can use the same market view across strategy, product and innovation teams. Investors can trace a market theme into the companies working on it and compare the opportunity with evidence from operating jurisdictions.
Policymakers, advisers and industry organizations can examine what happened after policy choices reached the market without assuming another country’s model belongs in Canada. The practical question is what worked, what did not and which lessons are relevant here.
NCFA’s separate Open Banking In Canada Opportunity Brief goes deeper on commercialization, evidence and product opportunities. Interactive Intelligence is broader, giving readers the market and international context before they narrow in on a specific commercial thesis.
The main strength is a one stop destination to research and learn about Open Banking. They can start with a company, market category, learning topic, international example or innovation question and follow the connections that are relevant to their work. Further, the page will be refreshed periodically to capture key updates and changes.
Data-sharing requirements affect product design, new technical capabilities can create commercial opportunities, and evidence from other markets can challenge assumptions about adoption or competition.
Open Banking Decision Intelligence analysis takes that thinking further by examining what firms can do with permissioned financial data, including credit, fraud detection and financial guidance.
There are limits. Canada’s proposed Consumer Driven Banking Regulations may still change, international examples operate under different legal and competitive conditions, and company intelligence dates quickly in an active market. The resource is designed to be revisited as the market develops and should not replace legal advice, due diligence or primary regulatory sources.
Canada Open Banking And Consumer Driven Banking Rules (proposed Canadian requirements, implementation and regulatory intelligence)
How Canada Started Opening Its Financial Infrastructure (payments, data access and financial infrastructure context)
Canada’s Open Banking Strategy Starts With Trust (consent, fraud, liability and consumer protection)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply