[Report] A New North Star: Canadian Competitiveness in an Intangibles Economy

Public Policy Forum | Robert Asselin and Sean Speer | April 4, 2019

Rise of the intangibles

When New England Patriots quarterback Tom Brady played in his first Super Bowl in 2002, there was no iTunes store, no Facebook, no Instagram, no Airbnb, no Gmail and no Skype. Today the companies who own these intangible assets are worth more than $4 trillion. The rise of the intangibles economy will have sweeping policy implications that will become clearer over time. Nobody knows for sure where this is heading.

Our overriding objective in this paper is to help catalyze a bi-partisan policy discussion about a new “north star” for Canada’s economic competitiveness and the types of policy reforms needed to start us on this path. As part of this process, we set out a series of policy recommendations that cover the classic drivers of competitiveness such as taxation and regulation and drivers for the intangibles economy such as data governance, intellectual property retention, and the race for talent. But as important as these prescriptions are, the main takeaway for policymakers and the Canadian public is that the rise of the intangibles economy requires that we test old assumptions and are open to new thinking. Canada’s economy cannot afford complacency in this new economic era.

We need a new competitiveness consensus

In the world of policy and politics, short-termism and complacency are difficult to resist. They trump partisanship. They trump best intentions. Pressure mounts on any government or political party to respond to immediate issues and keep an eye fixed on the four-year election cycle. Both of us observed these demands in our respective positions as economic advisers to national governments.

See: 

Advancing Competition in a Changing Marketplace

Competition Bureau weighs in on fintech: urgent action required

Canada’s Regulatory System for Fintech is Complex, Costly and Chaotic. It is Stifling Fintech Innovation

NCFA Letter to Ontario Economic Development on Burden (Jan 2019)

The problem is that reactive governance is inconsistent with the mix of long-term policies required to promote broad economic participation and growth. For a competitiveness agenda to maintain and raise Canadians’ quality of life, it demands discipline, focus and a vision that extends beyond the election cycle. It thus requires a multi-partisan commitment. A change in government may naturally result in new preferences and priorities, but it should not cause us to lose collective sight of the common bases of competitiveness, productivity and jobs, and the greater opportunities and outcomes they produce for successive generations.


The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

November 9, 2026 | Market Activity | Wealthtech, Investing And Trading, Fundraising And Capital Markets Competing for Canada’s $98.6 Billion RESP Market On November 6, 2026, National Bank of Canada agreed to acquire Embark Student Corp. for an estimated $226 million, adding more than $6 billion in RESP assets under management and approximately 436,000 beneficiaries. The deal gives National Bank immediate scale in Canada’s $98.6 billion RESP market and strengthens its digital competition with Wealthsimple, Questrade and other investment platforms. The transaction is expected to close by mid fiscal 2027, subject to court, regulatory and other customary approvals. National Bank already competes in Registered Education Savings Plan (RESP) accounts. It offers advisor supported RESPs and its direct brokerage lets customers manage RESP investments themselves. Embark brings a national digital business focused specifically on managed education savings, grant administration and RESP servicing. The acquisition gives National Bank a third way to compete for families without building that specialist operation one customer at a time. What National Bank Gets That It Doesn't Already Have Embark is one of Canada's largest direct to consumer RESP providers and operates as a Scholarship Plan Dealer across Canada. Its platform handles account administration, investment management, government ...
AI illustration of a graduation cap on stacked books beside a piggy bank and savings jar, illustrating education savings and competition in Canada’s RESP market
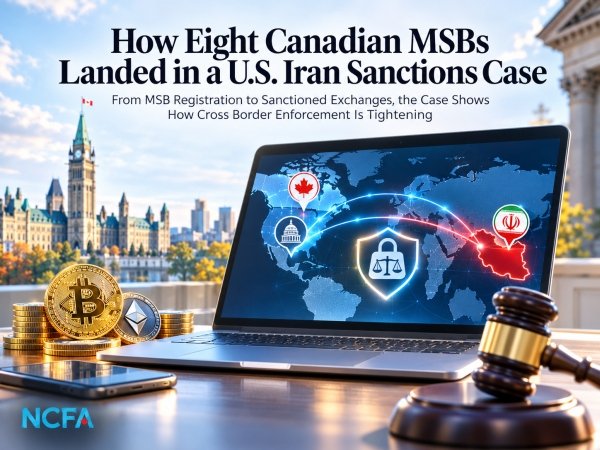
November 9, 2026 | NCFA Story Intelligence | Risk Compliance And Regtech, Cross Border Payments And FX, Digital Assets Blockchain And Tokenization When Canadian MSB Registration Meets Sanctions, Crypto and Financial Crime On November 6, 2026, eight Canadian money services businesses appeared on a U.S. sanctions list. Every one of them had a Canadian MSB registration number. That number meant the business had entered Canada's federal registration system. It didn't mean FINTRAC had approved the firm, cleared its customers or vouched for every transaction passing through it. Until November 6, that distinction could sound technical. Then the U.S. Treasury allegations arrived. Treasury says several of the eight firms converted cash or conventional currency into digital assets that reached sanctioned Iranian exchanges, addresses associated with the Islamic Revolutionary Guard Corps and, in some cases, wallets tied by U.S. authorities to Canadian drug trafficker Ryan Wedding. The firms had Canadian addresses, Canadian corporations and Canadian registration numbers. Now they also had OFAC designations. The same day, FINTRAC coordination with OFAC and FinCEN became public. Then Canada's financial intelligence agency disclosed what had been happening inside its own MSB regime during 2026: 161 registrations revoked, more than $198 million in penalties against nine ...
AI illustration of Eight Canadian MSBs linked to U.S. Iran sanctions with FINTRAC, crypto transactions and cross border enforcement imagery
Nov 9, 2026 Work can be stressful, especially in our busy world. Many people feel pressured to meet deadlines and juggle multiple tasks, which can leave them feeling overwhelmed. Work stress and fatigue can hurt both your job performance and your personal life. Recognize these feelings and look for ways to reduce them for better overall well-being. Many believe that working long hours is unavoidable. However, you can find simple ways to manage stress and boost your energy for a more balanced and satisfying work life. Here are some strategies to help you reduce work stress and fatigue. Set Healthy Boundaries Setting boundaries is the first step in managing stress. In a world that expects you to always be available, define your work hours. Let your colleagues know when you are available, and stick to that schedule. When you decide when to stop working, make sure you follow through. This may mean turning off notifications or avoiding emails after work hours. Taking breaks throughout the day is also crucial. Short breaks can increase your productivity and clear your mind. Use these moments to move away from your desk, go for a walk, or take deep breaths. These small pauses can ...
AI illustration of a professional woman taking a relaxing stretch break at her desk to reduce work stress and fatigue in a bright office.
November 9, 2026 | Insight | Payments Infrastructure And Money Movement, Competition And Market Structure, Cybersecurity Fraud And Financial Crime A New 24/7 Settlement Layer for Canadian Payments On November 9, 2026, Payments Canada launched Canada’s Real Time Rail, giving banks, credit unions and eligible payment firms a national system that can exchange, clear and settle payments in real time, 24 hours a day. Eight organizations are active at launch. RTR uses ISO 20022 messaging, makes settled funds available immediately and starts with centralized fraud controls built into the rail. Canadians won't suddenly see a new payment button. Interac e Transfer starts migrating onto RTR in 2027, major banks are still onboarding and participants need to build services customers can actually use. What changes today is the infrastructure underneath Canadian payments. Qualified firms can now build on a domestic rail that settles continuously instead of waiting for traditional processing windows. That opens more room for faster payouts, better treasury tools, real time account transfers and new payment products, but the commercial value now depends on who turns access into something useful. Who Can Use the Real Time Rail Now? The first active participants are Wealthsimple, Questbank, Peoples Trust Company, Paramount ...
AI illustration of a Digital map of Canada showing connected payment networks and real time financial infrastructure across the country
Nov 9, 2026 Financial services has spent years making the decision to approve a loan faster and more informed. AI is part of that progress. As NCFA’s coverage of AI loan decisioning shows, lenders are finding new ways to verify information and assess risk at origination. But approval is one decision on one day. Collections deals with what happens on all the other days. A customer’s circumstances can change many times before the debt is repaid. What happens when income drops, a payment is missed or a customer stops responding? Those decisions belong to debt collections, and they deserve just as much intelligence. After more than twenty years working in collections, this is where I think AI gets interesting. Not because it can automate more for the sake of it, but because it can help teams choose a better next action while giving collectors the time and context to handle situations that need human judgement. A risk score should lead somewhere Collections teams have always had to prioritise. The difficulty is that a delinquency bucket is not a person. Two accounts in the same bucket can belong to people in very different circumstances. One customer may have forgotten a payment ...
By Chris Maranis, Deputy CEO, EXUS
Nov 6, 2026 Planning for retirement often takes a backseat, especially when life gets busy. Many people find themselves thinking about retirement later than expected. This can happen for financial reasons, personal choices, or unexpected events. If you are approaching retirement later in life, you need careful planning. The good news is that with thoughtful preparation and informed choices, you can still enjoy a fulfilling retirement. Here are some ways to prepare for a secure financial future. Resources and Tools Start by understanding your resources. Evaluate your current assets, savings, and other income sources. Check your savings accounts, retirement accounts, and any investments. Financial tools or software can help you track your finances. A financial advisor can give you specific insights to help you stretch your resources effectively. Also, think about potential income you can earn after retirement. This could come from part-time work, freelance jobs, or even hobbies. The key is to recognize what resources you have and how to use them to support your retirement plans. Budgeting Wisely Creating a realistic budget is crucial as you near retirement. Review your current expenses and consider how they might change when you retire. Think about costs like healthcare, housing, daily ...
AI illustration of a Couple approaching retirement reviewing financial documents, savings, investments and retirement planning strategies together at home.
Oct 31, 2026 | Last Updated: Nov 6, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Digital Identity And Trust, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading NCFA Fintech Whisperer tracks weekly fintech market intelligence that changes how financial markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins. Missed a prior week's Fintech Whisperer? Browse December 6 to 12, 2025, December 13 to 19, 2025, January 1 to 9, ...
Fintech market intelligence visualization
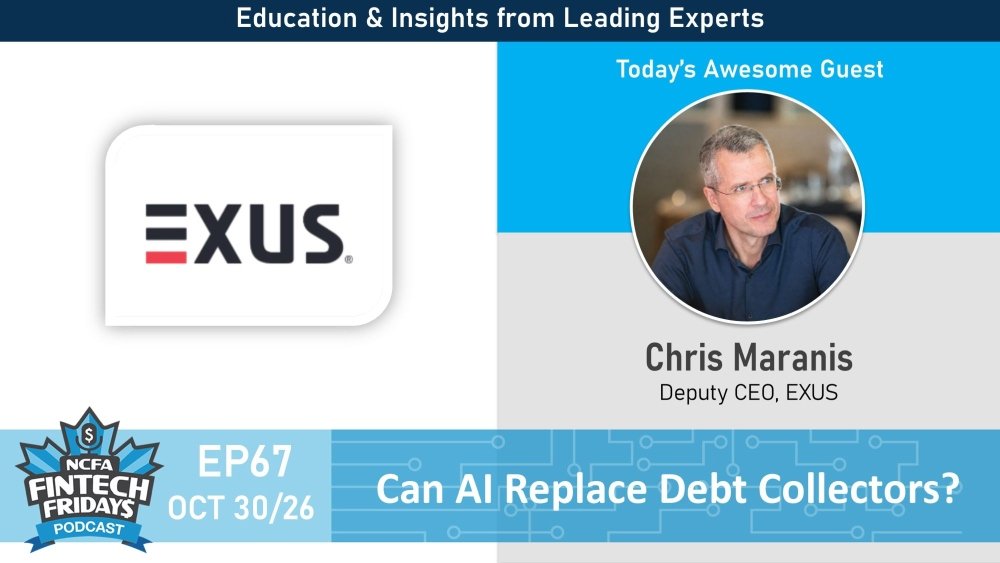
About NCFA Canada | Craig Asano | November 6, 2026 Featured Guest: CHRIS MARANIS, Deputy CEO, EXUS (LinkedIn) Chris Maranis is Deputy CEO at EXUS and a long-standing leader in the global debt collection technology space. Since joining EXUS in 2004, he has worked with financial institutions across more than 30 countries, helping them transform collections operations across the full lifecycle from pre-collection to recoveries. His experience spans diverse markets and operating models, including in-house teams, outsourced networks, and highly regulated environments, with a strong focus on improving performance while strengthening customer relationships. Today, he helps shape EXUS’ strategic direction by connecting market needs with product vision, commercial growth, and operating execution. His current mandate combines internal leadership with a strong external market role, working closely with customers, partners, and industry stakeholders to advance a more intelligent, ethical, and customer-centric approach to collections. Drawing on two decades of international experience, he now focuses on how AI data-driven decisioning and modern engagement strategies can help organizations build future-ready collections models that deliver better outcomes for both lenders and customers. About EXUS EXUS is a global technology company specialising in debt collection and credit risk software. Founded in 1989, its EXUS Financial Suite ...
Fintech Fridays S4EP67 Chris Maranis, Deputy CEO EXUS_1000
November 6, 2026 | Insight | Competition And Market Structure, Payments Infrastructure And Money Movement, Capital Markets Infrastructure And Funding More Competition in Canadian Finance With Tougher Consumer Rules On November 5, 2026, Finance Minister François Philippe Champagne tabled Budget 2026 with a financial sector package aimed at making it easier for credible new competitors to enter, raise capital and grow. The Budget 2026 financial sector measures cover bank approvals, ownership, deposit funding, payments, stablecoins, investment capital and commercialization. Separate measures tighten fraud, financial crime and consumer protection. Many of the digital finance building blocks started in Budget 2025's fintech and capital agenda. A year later, some are reaching implementation while Budget 2026 goes further on bank entry, ownership, funding and competition. Canada's six largest banks still hold about 93% of banking assets, leaving new entrants to compete against institutions with major advantages in deposits, distribution, capital and customer relationships. Outside banking, Canada also has a large C$14 trillion non bank financial system spanning investment funds, pensions, insurers and other financial firms. Canada has plenty of financial activity, but needs stronger competition in core banking and payments. Will Budget 2026 Make It Easier to Start and Grow a Bank? Ottawa ...
AI illustration of Canadian financial competition and fintech growth represented by digital payments, Canadian currency and Parliament Hill in Ottawa
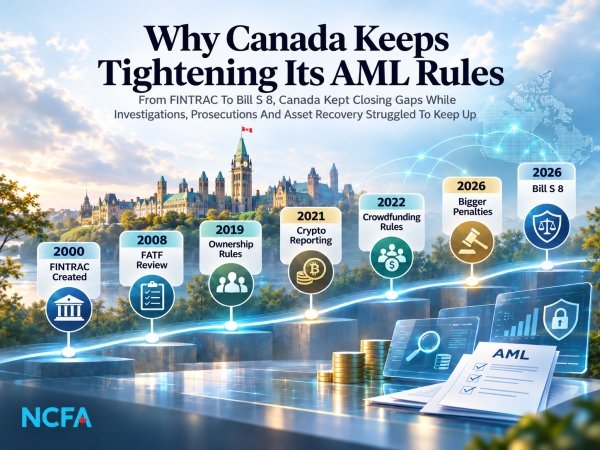
November 5, 2026 | NCFA Story Intelligence | Risk Compliance And Regtech, Regulation And Policy, Digital Assets Blockchain And Tokenization Canada keeps closing financial crime gaps, but investigations, prosecutions and asset recovery still have to catch up with the much larger system Canada added another layer to its anti money laundering system on November 3, 2026. Bill S-8 would tighten registration for money services businesses, give FINTRAC more grounds to refuse or revoke registrations, add controls for crypto ATMs, restrict some large cash transactions and third party cash deposits, and let regulated firms receive more financial crime information from government and law enforcement. Five days earlier, the Auditor General had delivered a very different AML announcement. FINTRAC was taking nearly 4 months on average to provide requested financial intelligence. Half of the recipients surveyed said information sometimes arrived too late to help an active investigation. A month before that, FATF had praised parts of Canada's system while still calling for stronger supervision, more complex money laundering prosecutions and better asset recovery. Canada isn't short of rules. It has spent more than 25 years adding them. This is a story of Canada closing one financial crime gap after another, only to ...
AI illustration of NCFA Story about Canada AML rules timeline showing FINTRAC, FATF reviews, beneficial ownership, crypto reporting, crowdfunding rules, penalties and Bill S-8.


Leave a Reply

Your email address will not be published. Required fields are marked *