





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 22, 2026 | NCFA Insight | Artificial Intelligence And Data, Risk Compliance And Regtech
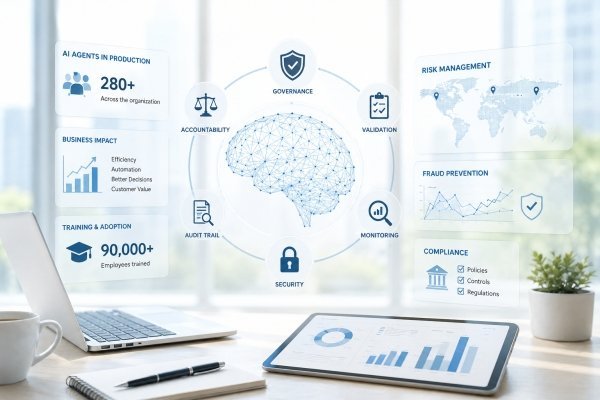
On June 22, 2026, Banco Santander reported that its AI first strategy generated €35 million in business value in Q1 2026, with expected value of more than €200 million by year end and a target of more than €1 billion between 2026 and 2028. That's a regulated bank putting numbers around AI execution.
The more interesting part is how Santander is trying to get there. The bank has extended AI access to all 185,000 employees, reported more than 280 AI automation agents in production, and previously described its ambition to become an AI native bank.
Ricardo Martín Manjón, Chief Data & AI Officer at Banco Santander, put the strategy plainly:
“For me, being AI-first means applying AI where it can have tangible impact.”
For Canada, the timing of this announcement is important because Santander recently received approval to operate as a federally regulated bank in Canada. So its AI operating model more than a global case study. It's a preview of how new banking competitors may bring AI, governance, fraud controls, and measurable operating discipline into regulated Canadian markets.
The first AI cycle rewarded access. Banks tested foundation models, launched copilots, built internal assistants, and looked for productivity wins. That phase is maturing fast. Models are easier to access. Cloud tools are easier to use. Building a convincing demo is no longer the hardest part.
The harder test is operating AI inside a regulated financial institution without losing control of risk, data, decisions, accountability, or customer trust.
That's where Santander’s publicly released data become strategically useful. Specifically, the update points to measurable business value, enterprise wide access, employee adoption, automation agents, and governance controls across ethical, legal, cybersecurity, and risk requirements. This is what AI moving from lab work into operating infrastructure looks like.
One underappreciated piece of the story is Santander AI Lab’s open source work. Its Gen Fraud Graph project is described as an Apache 2.0 open source initiative for generating synthetic fraud graphs and advancing fraud detection capabilities. The technical repository is also available on SantanderAI’s GitHub.
Fraud detection is one of the fastest ways to expose whether financial AI can be trusted. It touches financial crime, AML controls, identity checks, transaction monitoring, customer friction, model risk, and auditability. A model that performs well in a slide deck but cannot be tested, explained, monitored, or reviewed isn't ready for regulated scale.
Synthetic fraud graphs help solve a practical problem. Banks need realistic fraud scenarios to test detection systems, but they cannot freely share customer data or investigative information. Synthetic environments provide a safer way to benchmark performance, validate models, and document results.
The choice of fraud is revealing. Santander didn't launch its open source thread with a marketing assistant or a generic productivity tool. It highlighted infrastructure connected to risk.
Fraud teams need speed, but they also need evidence. Compliance teams need explainability. Risk teams need controls. Boards need accountability. Regulators need confidence that systems can be monitored and challenged.
For fintechs, this move by Santander is both a warning and an opportunity. AI claims won't be enough in fraud, AML, onboarding, underwriting, customer service, complaints, trading, surveillance, or compliance workflows. Buyers will increasingly ask for testing evidence, audit trails, human review, data controls, drift monitoring, and proof that the system works under pressure.
Recent work from IOSCO, OSFI, the European Union, the FCA, and other supervisory bodies points in the same direction. Institutions want measurable results. Customers expect accountability. The result is a growing focus on how AI systems are tested, monitored, explained, and challenged. That's why AI is creating a new compliance burden at the same time it creates productivity gains.
Santander reports more than 280 AI agents operating across the organization alongside enterprise wide training, governance controls, and measurable business outcomes. The same operating question now appears across AI agents entering financial workflows, customer onboarding, fraud detection, transaction monitoring, and compliance operations. The challenge is proving that it can operate safely inside regulated environments, and fraud amplifies the challenge immediately.
AI clones, biometric breaches, faster payments, and cyberattacks are weakening older trust signals, which raises the value of new verification controls for financial trust. Synthetic fraud graphs fit into that bigger problem because they give teams a safer way to test detection systems without exposing customer data or live investigations.
For banks, fintechs, payments firms, and infrastructure providers, that changes the economics of competition. Access to advanced models is becoming easier. Building a prototype is becoming easier. Producing evidence that a system can be trusted under real operating conditions remains difficult.
The first AI race was about capability. The next one is quickly focusing on proof.
If access to advanced AI becomes commonplace, will governance infrastructure and proof of control become more valuable than proprietary models in regulated financial services?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply