





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


BNPL | June 17, 2025
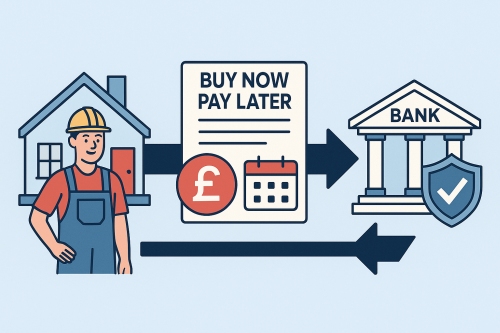
On June 16, 2025, the UK HM Treasury published a policy update that says 'domestic premises suppliers' (aka door to door vendors or companies that provide goods or services in a customer's home) no longer need to be licensed as credit brokers to offer Buy Now Pay Later (BNPL) services. The change to BNPL regulation is aimed at supporting smaller businesses without weakening consumer protections. This exemption includes services like home improvement consultations, kitchen installations, in-home services like cleaning or fitness, or any other sale that takes place during a visit to the customer's home.
Many industry stakeholders warned that requiring a credit broker license for these types of businesses isn't necessary and overly burdensome. The government agreed because these in-home suppliers do not offer financial services as their primary business activity. Instead, the typically introduce customers to a single BNPL lender as part of a product or service sale. Additionally, regulators realized that the risk of consumer harm in these cases is relatively low since the financial exposure sits with the BNPL lender who is regulated, not the seller, and felt that requiring small businesses to apply and maintain broker requirements is disproportionate to their role.
While the sellers are now exempt, BNPL lenders will still be fully regulated under the new rules, and must perform creditworthiness and affordability checks and comply with FCA Consumer Duty requirements. They must also ensure that purchases made using BNPL are protected under Section 75 of the Consumer Credit Act 1974, and that customers have access to the UK’s Financial Ombudsman Service to address complaints.
The full BNPL regulatory framework in the UK is expected to come into force by mid-2026, including secondary legislation to implement the exemption for in-home sellers.
Canada doesn't currently have a dedicated national BNPL regulatory framework. It also doesn't require BNPL sellers to have a credit-brokering license. The Financial Consumer Agency of Canada (FCAC) continues to monitor the sector but doesn't directly regulate BNPL lending. Oversight is through a mix of provincial consumer protection laws and federal rules related to money laundering and data privacy.
In Ontario as an example, BNPL offerings must comply with the Consumer Protection Act, which requires clear disclosures and restricts misleading marketing. If a provider handles payments, they may also need to register as a money services business under federal law.
As BNPL continues to grow, pressure is building for regulators to provide clearer guidance. The UK’s model may offer a useful reference for policymakers looking to balance access to BNPL services while protecting Canada's evolving credit sector.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply