





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 15, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Embedded Finance, Artificial Intelligence And Data
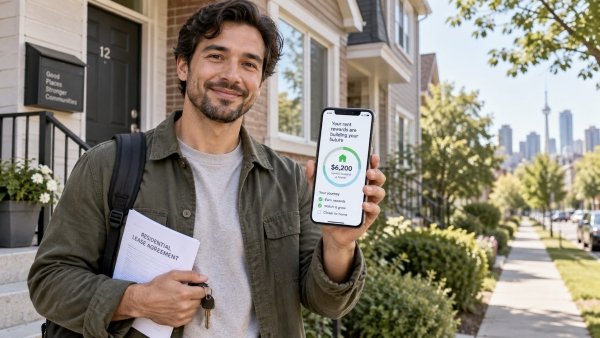
On September 15, 2026, Toronto-based Canadian proptech Zown updated its homebuying app with Rent Rewards alongside AI property search, affordability estimates, mortgage pre-approval and transaction services. Zown advertises up to 8% back on rent, giving it a reason to start working with consumers years before many will be ready to buy a home.
The 8% combines two potential rewards. Zown Money says Zown currently provides up to 4% cashback directly on rent, while an eligible credit card can add up to another 4% depending on the card's terms. At C$2,500 in monthly rent, Zown's 4% portion would equal C$100 a month or C$1,200 a year. If a renter also earned the full additional 4% through their card, the total could reach C$200 a month or C$2,400 a year before any card or payment-related costs.
The Canadian iPhone app, developed by Zown Realty Inc., also lets users upload a lease and proof of rent, search properties through an AI assistant called Zoro, view estimated affordability, request showings with licensed agents, seek mortgage pre-approval, submit offers and coordinate parts of closing. Zown Realty is an Ontario-registered real-estate brokerage. Mortgage rates, terms and qualification are provided through Vine Mortgage Group, and Zown says it isn't a direct mortgage lender.
Zown's model starts with a difficult Canadian problem. CMHC's 2026 Mortgage Consumer Survey found that recent buyers needed an average 4.4 years to save a down payment, while first-time buyers needed 4.7 years. Savings supplied the largest share of the down payment for 51% of first-time buyers. Another 23% of homebuyers received a financial gift, with a median gift of C$30,000. Rent Rewards give Zown a recurring reason to stay connected during those years.
Zown already has a more established incentive for buyers. Its Down Payment Boost returns up to 1.25% of a home's purchase price, capped at C$25,000, using part of the brokerage economics generated when a customer buys through Zown. On a C$1 million home, 1.25% equals C$12,500. Despite the product name, Zown's current guidance says the money arrives at closing and isn't counted as part of the mortgage down payment itself. Buyers can use it for closing and post-closing expenses.
Zown isn't alone in treating rent as financially useful activity. KOHO introduced rent cashback and credit reporting in Canada, while FrontLobby reports verified rent history to credit bureaus. Zown takes a different approach by connecting rent rewards with a later property purchase and the services surrounding it.
1. Rent is becoming a financial product. Canadian fintechs are attaching payments, rewards and credit reporting to one of the largest monthly household expenses. Toronto-based Chexy shows how quickly the category can scale. In March, the company raised C$14 million after starting with rent payments and said it had reached more than C$1 billion in annual payment volume and C$20 million in rewards value. Zown is pursuing a different end market, but rent serves the same commercial purpose of establishing a recurring financial interaction before other higher-value services are needed.
2. Housing costs are attracting more fintech models. Rent reporting, payment routing, rewards and short-term financing are competing for the same household expense. NCFA has tracked how fintech is entering rent and housing payments through companies including KOHO, Borrowell, Zenbase and Chexy. Zown adds another model by using rent rewards to encourage future homeownership and then connecting the renter to brokerage and mortgage services.
3. AI is getting closer to the financial decision. CMHC found that 16% of mortgage consumers who searched online used AI for mortgage information in 2026. HouseSigma says its Canadian platform has more than two million registered users and over five million monthly web visits, with AI used for valuation and market analysis. Zown's Zoro is competing in the same environment, focused on helping someone make a better property or financing decision. NCFA has identified the same commercial issue in decision intelligence across financial services.
It's a competitive field already. Wahi competes on digital brokerage and buyer cashback, Perch on digital mortgage readiness, FrontLobby on rent reporting, and HouseSigma on property search, valuation and market data. Zown's difference is the attempt to connect those stages much earlier, while the customer is still renting.
The economics improve if Rent Rewards keep customers engaged rather than simply subsidizing renters who eventually buy elsewhere. A traditional brokerage usually starts competing once someone begins seriously looking for a home. Zown can enter much earlier, stay connected through monthly rent, introduce affordability and mortgage tools, and eventually earn brokerage revenue if that renter buys through the platform.
That could lower the cost of finding future buyers and generate more revenue from each customer relationship. It can also become expensive if Zown funds rewards for several years without converting enough renters into completed transactions. The operating number worth watching should therefore be how many Rent Rewards users eventually become profitable Zown homebuyers?
Canadian mortgage companies, brokerages and property apps usually compete once someone is already thinking seriously about buying. If Zown can give renters enough financial value to earn their attention four or five years earlier, how much of the future homebuyer relationship can it own before the mortgage application even begins?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply