Global fintech and funding innovation ecosystem

Portable Business Identity

NCFA Opportunity Brief - Portable Business Identity
Innovation Map → Digital Identity And Trust → Portable Business Identity → Opportunity
Last Updated Jun 24, 2026
FINANCIAL INNOVATION OPPORTUNITY BRIEF This page tracks evidence, risks, validation signals and venture opportunities emerging as business identity, KYB, beneficial ownership data and compliance credentials become more portable across financial platforms.
Innovation OpportunityDigital Identity, KYB And Data Portability

Portable Business Identity

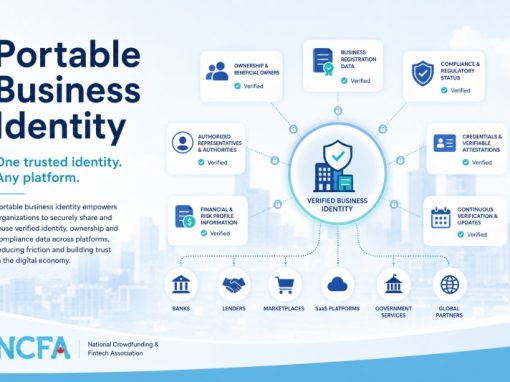
Businesses still repeat identity, ownership, onboarding and compliance checks across banks, PSPs, lenders, marketplaces and software platforms. The opportunity is to let verified business identity, KYB records, authority, ownership and trust credentials move securely across institutions with consent and controls.

16 Evidence4 Questions4 Related Opps4 Resources

Opportunity Intelligence

Market Potential

US$51B+Digital identity solutions, 2026 estimate
US$30B+KYC and KYB spend by 2030
HighGrowth signals
4Source count

Portable business identity sits between digital identity, KYB, beneficial ownership, data portability and compliance automation. Market estimates vary by scope, but the direction is consistent: regulated firms need more reliable business identity data, while businesses need less repetitive onboarding across platforms.

View market sizing sources

Top Opportunity

The strongest opening is portable KYB and business identity profiles that reduce repeated onboarding while preserving control, consent, verification quality and auditability. The buyer may be a bank, PSP, marketplace, lender, regtech provider or business platform that wants lower onboarding friction without weaker compliance.

Top Risks

  • Regulated firms may hesitate to rely on portable business credentials unless liability and assurance standards are clear.
  • Government registries, LEI issuers, identity providers and existing KYB vendors may compete for control of the trust layer.
  • Portability can increase fraud or data leakage risk if consent, revocation, freshness and governance are weak.

What To Watch

Consumer driven banking rollout, CSA data portability testing, GLEIF vLEI adoption, beneficial ownership rules, KYB automation, open finance standards and evidence that SMEs or platforms will pay for reusable business identity tools.

Product Opportunities

Strongest current path: Portable KYB Profiles

Evidence points to three venture paths. Each one addresses a different constraint that prevents business identity and compliance data from moving safely across financial ecosystems.

1. Portable KYB Profiles

Reusable business onboarding and ownership records

7 evidence signals
3 related questions
high readiness

Businesses repeatedly submit incorporation documents, ownership records, director information, tax data, licenses and compliance evidence to every new financial provider. Portable KYB profiles could reduce this duplication while keeping institutions in control of risk decisions.

The venture opportunity is not to eliminate due diligence. It is to make verified business information easier to reuse, refresh, audit and share under clear permission rules. Potential buyers include banks, PSPs, lenders, marketplaces, wealth platforms and compliance service providers.

What could break the thesis

Regulated firms may decide that relying on third party KYB records creates more liability than efficiency unless assurance standards mature.

Market WindowOpen
Buyer ClarityHigh
Competitive PressureMedium High
Evidence StrengthHigh
What to validate first

Will banks, PSPs or platforms rely on portable KYB outputs, or only use them to accelerate internal review?

2. Business Identity Wallets

Verified entity, authority and credential control

5 evidence signals
2 related questions
growing readiness

Business identity wallets would let companies hold and present verified entity information, authority credentials, licenses, beneficial ownership attestations and role based permissions. The vLEI model shows how legal entity identity can become cryptographically verifiable in digital interactions.

This path may be most valuable where businesses need to prove who they are, who can act for them and what authority has been granted across payments, procurement, lending, filings and platform onboarding.

What could break the thesis

Wallet adoption may remain fragmented if issuers, registries, platforms and regulators do not converge around interoperable standards.

Market WindowOpening
Buyer ClarityMedium High
Competitive PressureMedium
Evidence StrengthMedium High
What to validate first

Which credential creates enough value to drive wallet adoption: entity identity, authority to act, beneficial ownership, tax status or licensing?

3. Trust Passport Networks

Platform trust, compliance status and risk portability

4 evidence signals
2 related questions
early readiness

Many businesses build trust repeatedly across marketplaces, lenders, PSPs, procurement networks and software ecosystems. A trust passport network would let selected trust attributes travel with the business, including verification status, permissions, payment history, platform standing and risk signals.

This path is broader than compliance. It may support B2B marketplaces, SME finance, embedded finance, cross border trade and agent commerce. It is earlier because governance and liability questions are harder than the technology.

What could break the thesis

Platforms may refuse to share trust data if they view it as proprietary, competitively sensitive or too risky to rely on elsewhere.

Market WindowEarly
Buyer ClarityMedium
Competitive PressureMedium
Evidence StrengthEarly
What to validate first

Which trust attributes are portable enough to matter and safe enough for another platform to rely on?

Evidence Trail

16 verified and early evidence items. Evidence type classifies the signal, not the publisher.

Filter by signal type to review source records, market signals and thought leadership supporting this opportunity. Evidence is sorted newest to oldest.

2026-06-18
Primary
Bank Of Canada Consumer Driven Banking
Framework allows Canadians and businesses to securely share financial data
Regulatory
2026-06-18
Primary
GLEIF Verifiable LEI
User controlled legal entity identity for digital transactions and filings
Infrastructure
2026-06-18
Primary
GLEIF Legal Entity Identifier
Unique global legal entity identification and reference data
Infrastructure
2026-06-18
Primary
FINTRAC Beneficial Ownership Requirements
Entity verification, beneficial ownership accuracy and business relationship controls
Regulatory
2026-05-11
Thought Leadership
Digital Identity As Trust Layer For Data Sharing
Portable digital credentials as data sharing expands
Adoption
2026-04-14
Analysis
Consumer Driven Banking In Canada
Consumers and small businesses can direct secure financial data sharing
Regulatory
2026-04-14
Market Activity
KYC And KYB Spending To Surpass US$30B
KYB system spend growth validates buyer pain
Adoption
2026-02-24
Analysis
Canada's Open Banking Infrastructure Advances Before Policy
Direct APIs and secure data portability environment
Infrastructure
2026-01-15
Primary
Your Data, Your Control
Competition Bureau frames consumer driven banking as data control and portability
Regulatory
2025-11-05
Analysis
Budget 2025 Accelerates Fintech, AI, And Capital Growth
Consumer driven banking rollout and data portability policy signal
Trust
2025-02-19
Thought Leadership
CSA Seeks Industry Input On Data Portability Consultation
eKYC, investor data portability and switching friction
Trust
2025-01-23
Research
Data Portability In Financial Services
Canadian open banking debate and portability implications
Trust
2024-10-22
Analysis
CFPB Finalizes Open Banking Rule
Data sharing, switching costs and portability lessons for Canada
Trust
2023-02-16
Research
OECD Data Portability In Open Banking
Consent based financial data portability and policy challenges
Infrastructure
2022-06-30
Explainer
vLEI 101
LEI as verifiable credential and control proof for organizations
Adoption
2018-09-21
Story
Commercial Passport And Digital Business Identity
Historical Canadian KYC portability and business identity signal
Trust

Participate In This Opportunity

Share your perspective, research, case study or video response. You can also express interest in future discussions, collaboration opportunities and innovation activities related to this topic.

Learn how NCFA identifies, validates and tracks innovation opportunities →
Participate

About NCFA Opportunity Intelligence

NCFA Opportunity Intelligence tracks emerging venture opportunities using evidence, market developments and validation signals. Opportunity briefs are updated as new information, evidence and stakeholder perspectives become available. This content is provided for information purposes only and does not constitute legal, investment, financial, tax or professional advice.


NCFA Jan 2018 resizeThe National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights

NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter


Leave a Reply

Your email address will not be published. Required fields are marked *




