NCFA Letter to Ontario Economic Development on Burden (Jan 2019)

NCFA | Regulatory Burden Reduction, Steering Committee | Jan 31, 2019

27 Jan 2019

Minister of Economic Development, Job Creation and Trade

College Park 18th Flr, 777 Bay St, Toronto, ON M7A 1S5


Dear Minister

Regulatory Burden on Innovation and Start-ups

The Ontario Premier the Hon Doug Ford has invited submissions on regulatory burden. We wholeheartedly support this initiative. The National Crowdfunding & Fintech Association of Canada appreciates the opportunity essentially to summarize submissions it has already made to the Ontario Securities Commission and the Ontario Ministry of Finance in 2017.

As the lead Minister on reducing regulatory burden, we understand that we should send these submissions to you – https://news.ontario.ca/medg/en/2018/12/ontarios-government-for-the-people-cutting-red-tape-to-help-create-jobs.html.

We are aware of the OSC’s recent request for input on regulatory burden; we are preparing a detailed submission for them that updates and adds to our earlier submissions. We will copy your office.

The NCFA submissions to the OSC (Aug 2017) and the Minister of Finance (Oct 2017) are attached. So far as we know, none of our recommendations has been accepted.

Our key takeaways continue to be:

  1. Compared to Canada’s global competitors, equity and debt crowdfunding is being stifled by a combination of regulatory burden (not just in the capital markets sector) and lack of coordinated government support (financial and otherwise). Our 2000 members tell us that many start-ups are leaving Ontario and Canada and seeking capital elsewhere, while many fail even to get off the ground. Alternatively, to scale up, innovators are often (in effect) forced to sell to larger companies usually established elsewhere. In the result, Canada continues to be a branch plant economy, and we are falling further behind.
  2. The crowdfunding and fintech sectors urgently need:
  • Harmonized offering memorandum exemptions across provincial and territorial jurisdictions;
  • Harmonized start up exemptions with higher caps – the OSC exemption has not been used;
  • Proportionate, risk based, outcomes focused regulation (and supervision) with an end to prescriptive regulatory requirements that are not justified by ongoing cost benefit analyses;
  • More education for stakeholders, and the research/data needed by regulators, governments, and the industry: to keep up-to-date with very quickly changing markets, to make better decisions, and to more quickly correct roadblocks to success;
  • Government support equivalent to that provided in jurisdictions like the UK and Singapore.


You will be well aware that SMEs and their entrepreneurial spirit are the backbone of the economy, employing millions of Canadians. But there is a well-documented funding gap, especially for innovators, and female, First Nations and rural founders.

We know that small business is struggling in Ontario. We know that very little use is being made of the crowdfunding exemption. We know that companies are generally short of capital, especially when compared to their US counterparts. And we need more data than are presently available.

See:

Ontario needs to make it easier for SMEs to start up, grow and flourish by making it easier for them to access finance and support. Innovative capital raising options for early stage ventures (in many cases not suitable for an IPO) are more important than ever.  And it should be easier for small investors to invest in the higher risk small businesses that matter to them.

There are significant economic and social benefits to be won.

We would welcome a meeting to discuss this and other issues and opportunities in the alternative finance and fintech sectors in Ontario.


Sincerely


NCFA

Regulatory Burden Reduction, Steering Committee


Cc:      Premier of Ontario [Legislative Building, Queen's Park, Toronto ON M7A 1A1]

Minister of Finance [Frost Bldg S 7th Flr, 7 Queen's Park Cres, Toronto, ON M7A 1Y7]

Cabinet Office (Att: Steve Orsini)

Ontario Securities Commission


Download the PDF version --> here


The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

Oct 31, 2026 | Last Updated: Nov 6, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Digital Identity And Trust, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading NCFA Fintech Whisperer tracks weekly fintech market intelligence that changes how financial markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins. Missed a prior week's Fintech Whisperer? Browse December 6 to 12, 2025, December 13 to 19, 2025, January 1 to 9, ...
Fintech market intelligence visualization
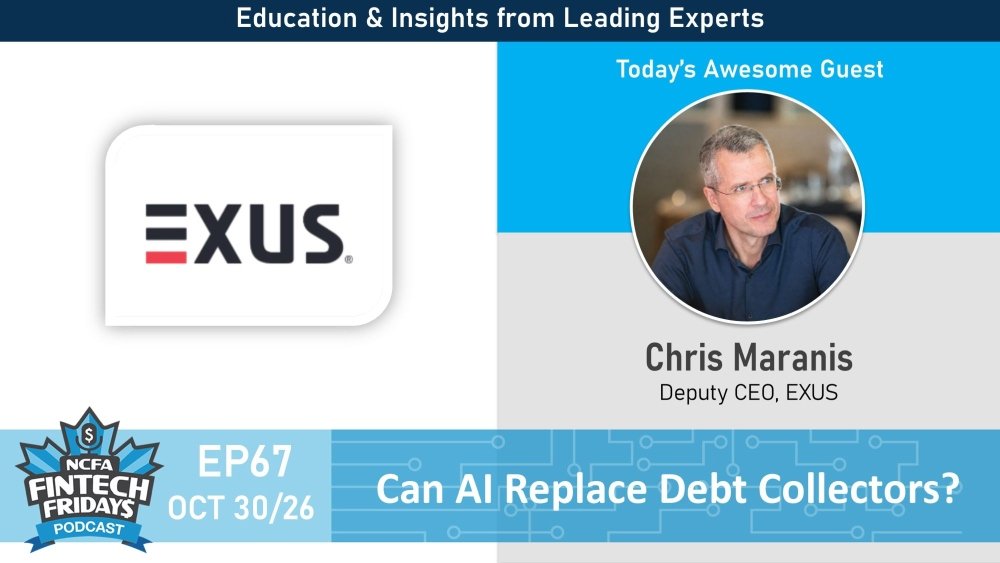
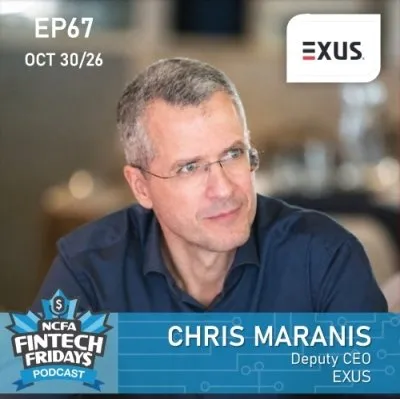
About NCFA Canada | Craig Asano | November 6, 2026 Featured Guest: CHRIS MARANIS, Deputy CEO, EXUS (LinkedIn) Chris Maranis is Deputy CEO at EXUS and a long-standing leader in the global debt collection technology space. Since joining EXUS in 2004, he has worked with financial institutions across more than 30 countries, helping them transform collections operations across the full lifecycle from pre-collection to recoveries. His experience spans diverse markets and operating models, including in-house teams, outsourced networks, and highly regulated environments, with a strong focus on improving performance while strengthening customer relationships. Today, he helps shape EXUS’ strategic direction by connecting market needs with product vision, commercial growth, and operating execution. His current mandate combines internal leadership with a strong external market role, working closely with customers, partners, and industry stakeholders to advance a more intelligent, ethical, and customer-centric approach to collections. Drawing on two decades of international experience, he now focuses on how AI data-driven decisioning and modern engagement strategies can help organizations build future-ready collections models that deliver better outcomes for both lenders and customers. About EXUS EXUS is a global technology company specialising in debt collection and credit risk software. Founded in 1989, its EXUS Financial Suite ...
Fintech Fridays S4EP67 Chris Maranis, Deputy CEO EXUS_1000
November 6, 2026 | Insight | Competition And Market Structure, Payments Infrastructure And Money Movement, Capital Markets Infrastructure And Funding More Competition in Canadian Finance With Tougher Consumer Rules On November 5, 2026, Finance Minister François Philippe Champagne tabled Budget 2026 with a financial sector package aimed at making it easier for credible new competitors to enter, raise capital and grow. The Budget 2026 financial sector measures cover bank approvals, ownership, deposit funding, payments, stablecoins, investment capital and commercialization. Separate measures tighten fraud, financial crime and consumer protection. Many of the digital finance building blocks started in Budget 2025's fintech and capital agenda. A year later, some are reaching implementation while Budget 2026 goes further on bank entry, ownership, funding and competition. Canada's six largest banks still hold about 93% of banking assets, leaving new entrants to compete against institutions with major advantages in deposits, distribution, capital and customer relationships. Outside banking, Canada also has a large C$14 trillion non bank financial system spanning investment funds, pensions, insurers and other financial firms. Canada has plenty of financial activity, but needs stronger competition in core banking and payments. Will Budget 2026 Make It Easier to Start and Grow a Bank? Ottawa ...
AI illustration of Canadian financial competition and fintech growth represented by digital payments, Canadian currency and Parliament Hill in Ottawa
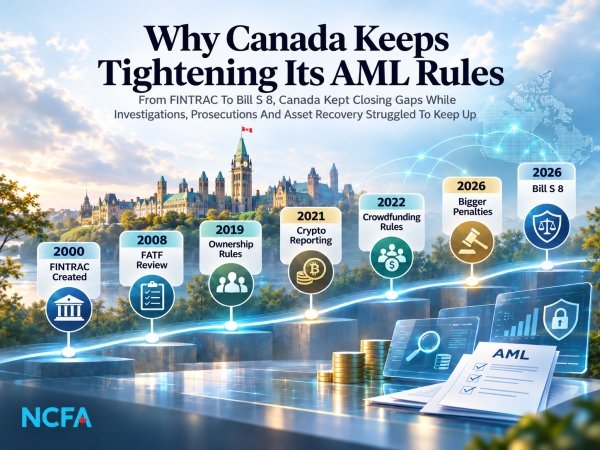
November 5, 2026 | NCFA Story Intelligence | Risk Compliance And Regtech, Regulation And Policy, Digital Assets Blockchain And Tokenization Canada keeps closing financial crime gaps, but investigations, prosecutions and asset recovery still have to catch up with the much larger system Canada added another layer to its anti money laundering system on November 3, 2026. Bill S-8 would tighten registration for money services businesses, give FINTRAC more grounds to refuse or revoke registrations, add controls for crypto ATMs, restrict some large cash transactions and third party cash deposits, and let regulated firms receive more financial crime information from government and law enforcement. Five days earlier, the Auditor General had delivered a very different AML announcement. FINTRAC was taking nearly 4 months on average to provide requested financial intelligence. Half of the recipients surveyed said information sometimes arrived too late to help an active investigation. A month before that, FATF had praised parts of Canada's system while still calling for stronger supervision, more complex money laundering prosecutions and better asset recovery. Canada isn't short of rules. It has spent more than 25 years adding them. This is a story of Canada closing one financial crime gap after another, only to ...
AI illustration of NCFA Story about Canada AML rules timeline showing FINTRAC, FATF reviews, beneficial ownership, crypto reporting, crowdfunding rules, penalties and Bill S-8.
November 5, 2026 | Market Activity | Wealthtech Investing And Trading, Artificial Intelligence And Data, Risk Compliance And Regtech Odlum Brown Connects Client Onboarding Directly to Dataphile On November 3, 2026, Odlum Brown and Montreal based Mako Financial Technologies launched a digital client onboarding system integrated with Odlum Brown’s Dataphile book of record. The custom workflow supports Odlum Brown’s self clearing model and carries client information from account applications into the system used to maintain its accounts. Clients can complete an application themselves, work through it with an advisor or have the advisory team enter information with them. Odlum Brown has operated as an independent Canadian investment firm since 1923 and now manages more than $25 billion in client assets across six British Columbia locations. Mako was founded in Montreal in 2018 and builds digital workflows for wealth firms, including client onboarding, account opening, KYC and ongoing account administration. The Odlum Brown deployment connects client onboarding directly with the systems used to maintain accounts, instead of treating onboarding as a separate digital form. How Does Mako’s Odlum Brown Onboarding Work? The workflow changes what a client or advisor sees based on answers already provided. If an earlier response changes what information, ...
AI illustration of a digital investment account onboarding on a laptop representing Mako’s client onboarding system for Odlum Brown
Nov 5, 2026 A crypto price feed is fresh when it delivers the latest relevant observations for the market it claims to show. A flashing number or a “live” badge cannot establish that. Check what the price represents, when the underlying event occurred, and whether newer events are reaching the display. An unchanged quote can be correct in a quiet market; an animated dashboard can still be behind. You can investigate these differences using visible records, although locating the precise fault may require access to the provider's systems. Find out which clock the page is showing Several events happen between a trade and your screen. The exchange records the trade, a data service receives it, an application processes the update, and your browser displays it. Each stage can have a timestamp. A page refreshed at 14:00 may still be displaying a trade from 13:55. The refresh time describes the page, while the trade time describes the observation. Start with the definition beside the number. A last-traded price is the price of a completed transaction. A best bid or ask describes an available order at a moment. An index combines selected observations according to a method. A derivatives mark serves the ...
AI illustration of a Crypto price feed network device with Ethernet cables representing live market data delivery and connection latency
November 5, 2026 | Market Activity | Cross Border Payments And FX, Payments Infrastructure And Money Movement, Regulation And Policy Whish Uses Its Lebanon Network to Build a Canadian Payments Base On November 4, 2026, Whish Money announced its first Canadian operating location in Montreal, starting with money transfers between Canada and Lebanon. The branch had already been reported open in late October. Whish says more Canadian financial services are planned and enters Canada with an established international payments business. The company reports more than 2.5 million app users, operations across 160+ countries, more than $40 billion in historical gross payment value and more than one million cards issued. Jad Koussa CEO called Montreal “a defining step in Whish Money’s global expansion.” Whish already has more than 1,000 locations in Lebanon, including 40 main branches, plus international transfer connections through Ria, Mastercard, TerraPay, Visa, Taptap Send and Sendwave. That gives the company established distribution and payout reach on the Lebanon side while Montreal adds direct access to Canadian senders. What Can Whish Money Customers Use in Canada? The confirmed Canadian service today is remittance, with Canadian bank accounts being connected to Whish for wallet funding and transfers. Whish’s Canada and ...
Illustration of Montreal and Beirut skylines connected by a mobile money transfer, showing Whish Money's Canada to Lebanon remittance corridor
Nov 5, 2026 A comparison of Canadian review-removal services, pricing and practical fit for small businesses. A single suspicious review can cause real concern for a small business. For a restaurant, clinic, contractor or local retailer, online feedback is often one of the first things a prospective customer reads. Yet a negative review is not automatically a policy violation, and a third-party agency cannot simply delete it. The useful question is whether a review breaks Google’s rules and what support a business needs to present its case. For Canadian entrepreneurs evaluating paid assistance, ReviewsBoost and ReviewRemoval offer per-review services, while Reputation.ca provides a broader, ongoing reputation-management approach. These models have different costs and serve different needs. 1. ReviewsBoost: a lower-cost specialist option ReviewsBoost is aimed at Canadian businesses seeking assistance with potentially policy-violating Google reviews. Its service model emphasizes a review assessment, managed reporting support and updates on progress. For owners facing an isolated questionable review, its simpler per-review pricing may be appealing. Pricing: CAD $45 upfront per review, plus CAD $95 upon successful removal, for a total of CAD $140 per removed review before applicable taxes. Best fit: cost-conscious small businesses seeking specialist help with a specific review and ...
AI illustration of a Canadian small business owner reviewing a suspicious one-star Google review on a laptop and preparing to report a potential policy violation.
Nov 5, 2026 Long weekends and public holidays are pure gold for every licensed casino platform in Australia.Thursday evenings often mark the start of a busy promotional period for online casinos, with operators introducing new bonuses to attract weekend traffic. Players exploring offers such as https://free-spins-professor.com/200-free-spins/ may notice that these promotions receive particular attention as the weekend approaches. How Casinos and Bookies Gear Up for Long Weekends Casinos don’t wait until Friday arvo to start throwing money around. From Wednesday they triple the budget on free spins no deposit Australia and cash drops. Reloads jump from the usual 50–75 % to straight 150–200 % matches with half the normal wagering. Weekend-only tournaments with $50k–$150k prize pools go live at 6 p.m. Thursday and run until Tuesday midnight. Why Engagement Skyrockets on Public Holidays Nobody’s stuck at work, the barbie is fired up by lunch, and the footy never stops. Average session length jumps from 28 minutes on a normal Tuesday to two and a half hours across Easter or the King’s Birthday weekend. Phones stay glued to hands while the races, AFL, NRL and cricket overlap on every screen in the country. Long Weekends Completely Flip Which Bonus Pays Best ...
https://free-spins-professor.com/200-free-spins/
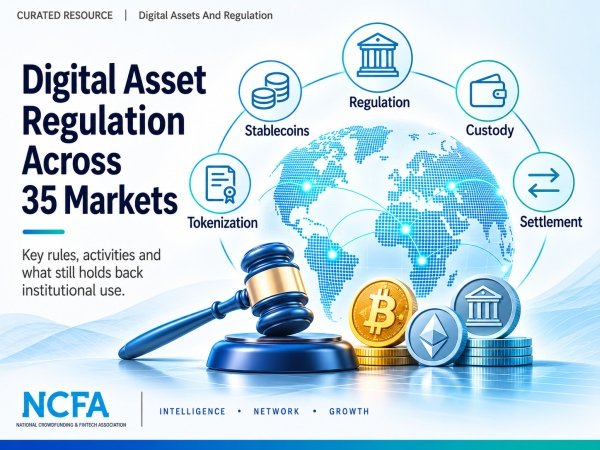
November 4, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy, Capital Markets Infrastructure And Funding Regulation Is Not the Same as a Working Market On October 28, 2026, the World Economic Forum and Boston Consulting Group published Regulation of Digital Assets in a Shifting Global Landscape, based on regulatory developments across 35 jurisdictions and more than 25 digital asset activities. The research includes interviews with 50 public and private sector experts, workshops and input from more than 100 participants. Digital assets can be legal and regulated while still being difficult for banks, asset managers and other institutions to use at scale. More than 70% of the jurisdictions studied regulate the activity being performed rather than relying only on the form of the asset. Trading venues, custodians and payment providers are supervised in more than 75% of the sample. Progress still varies widely within individual countries. A market can have clear rules for tokenized securities while its stablecoin, custody or settlement rules are still incomplete. For a company deciding where to operate, the rules for its actual business matter far more than a country's overall reputation for digital assets. What It Does In Practice The 38 ...
NCFA Resource on digital asset regulation across 35 markets covering stablecoins, custody, settlement and tokenization


Leave a Reply

Your email address will not be published. Required fields are marked *