






Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


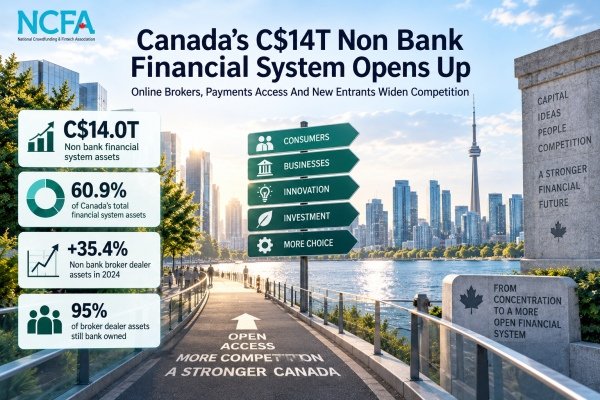
On September 3, 2026, Bank of Canada staff released new non bank finance data showing that Canada’s non bank financial sector held C$14.0 trillion in assets at the end of 2024, equal to 60.9% of the financial system. The Bank's broad definition includes pension funds, insurers, investment funds, financial auxiliaries and other intermediaries. Much of the 2024 increase also came from stronger market valuations.
The headline number is only part of the story. Faster growth is appearing in narrower bank like activities, online brokerage and specialty finance, while commercial banks still retain enormous asset and distribution advantages.
Canada already had a huge financial system outside deposit taking banks. What's changing is how customers reach it, where credit can originate and how many firms can compete for data, payments, investing and banking services.
Canada already had a vast financial system outside banks before fintech took off. Pension funds, insurers and investment funds have held enormous pools of financial assets for decades. The Bank says non bank assets have grown at an average annual rate of 6.9% since 2010.
The C$14 trillion also grew faster in 2024 because markets rose. Other investment funds increased 18.8%, pension assets rose 9.6% and insurance assets rose 9.8%. The Bank attributes much of that growth to stronger valuations.
Fintech arrived inside a financial system that was already enormous. Since then, investing has become easier to distribute online, more credit products have appeared outside traditional bank lending, payment firms have gained access to national infrastructure and financial data is being opened to approved competitors. Customers now have more ways to reach financial products without starting at a bank branch.
Online brokerage is one of the clearest changes in the Bank's data. Non bank broker dealer assets grew 35.4% in 2024, and the Bank says online brokers drove the increase.
Digital investing can win customers quickly because opening an account, moving cash and buying securities no longer requires the same physical distribution network.
The incumbents are nowhere close to disappearing. Non bank firms account for only about 5% of Canada's broker dealer assets. Bank owned broker dealers hold the other 95% of those assets.
The contrast is striking. Challenger activity is changing customer behaviour much faster than it is changing institutional asset share.
A Canadian can now invest through a digital broker, buy an ETF, hold cash inside an investing app and compare financial products without spending much time inside a traditional branch. The banks still own enormous distribution and balance sheet capacity. They no longer own every customer entry point.
Specialty finance has grown quietly beside the banks. Finance companies represent 11.8% of the narrow non bank measure and grew 7.1% in 2024. Statistics Canada includes consumer lending, corporate lending, leasing, mortgage investment corporations and mortgage finance corporations in its non bank credit work.
The official statistics have also expanded over time to capture newer models such as buy now pay later financing.
A mortgage can start outside a bank and still end up inside one. Mortgage finance corporations can originate loans through brokers and then sell them to regulated financial institutions. A borrower may meet a non bank lender first while a bank later funds or owns the mortgage.
Competition and cooperation can exist in the same transaction.
Canadian finance is becoming more distributed without becoming neatly divided into banks on one side and challengers on the other. Origination, funding, servicing, securitization and ownership can happen at different institutions. That makes the system more competitive in places and more interconnected at the same time.
Private credit shows the same Canadian pattern. Non bank loans have supplied about 15% of external funding for Canadian non financial businesses for roughly a decade. Private credit has not rapidly replaced domestic bank lending.
Canadian institutions are still heavily involved. The Bank estimates that private lending by Canadian investors plus Canadian bank lending to private credit funds totalled about C$500 billion around the beginning of 2026, with most of the activity in the United States.
Canadian pensions, insurers and banks know the asset class well. Much of the capital is simply being deployed elsewhere.
That divide is already visible in Canada's C$500 billion private credit exposure. Canadian institutions have substantial capacity to invest in private lending, while Canadian businesses still depend much more heavily on banks and public debt markets.
Payments access is opening to firms that historically could not participate directly. Payments Canada says registered payment service providers can now apply for membership and Real Time Rail participation. Wise, KOHO, Float, Paramount Commerce and Brim were among the first PSP members admitted in 2026.
The Real Time Rail is scheduled to launch in the fourth quarter of 2026 with instant clearing and settlement and support for direct PSP participation.
Financial data is opening too. Canada's consumer driven banking framework makes competition an explicit objective and creates accreditation routes for regulated financial institutions and registered payment firms.
Approved providers will be able to request customer permissioned financial data instead of relying on screen scraping or proprietary bank connections.
The opening of Canada's payments system now extends into consumer driven banking. A challenger with payment access and customer approved data has more room to build a financial relationship without depending on an incumbent for every connection.
In June, OSFI launched a streamlined approvals framework for targeted new entrants. It covers eligible credit unions and firms with technologically innovative or emerging banking models.
OSFI is aiming for a clearer three phase process and a targeted 12 month review after a complete formal application is accepted.
Foreign banks already have a formal route into Canada. OSFI assesses applications for full service and lending branches and recommends eligible applications to the Minister of Finance.
Entry is still tightly supervised. Capital, liquidity, governance, business plans, home country supervision, security and risk management remain part of the approval process.
A firm that qualifies for federal entry can pursue much more than a better financial app. Regulated banking capacity, payment access and customer approved data can put more of the customer relationship inside the challenger itself. The requirements remain demanding, but the route is clearer.
Securities rules are changing at the same time. The Canadian Securities Administrators has expanded the Listed Issuer Financing Exemption, allowed eligible venture issuers to adopt semi annual reporting and introduced other measures intended to reduce financing and disclosure friction.
In July, the CSA said more than 10% of eligible companies had already opted into semi annual reporting and that significant capital had been raised under the expanded exemption.
More financial assets do not automatically create more productivity. A pension portfolio can rise because markets rise. A fund can buy existing securities. Canadian institutions can invest abroad. None of those outcomes guarantees more financing for a Canadian company trying to commercialize technology, buy equipment or scale internationally.
That allocation question runs directly into whether Canada can turn financial access into productive participation.
The C$14 trillion headline makes the productivity problem harder to dismiss. Canada is not short of financial assets. The harder question is whether more of the system can connect viable Canadian businesses with capital on terms that let them invest, grow and compete.
The Bank itself recognizes the upside. Its paper says these non bank firms can foster innovation, increase competition, serve underserved markets and improve financial system efficiency.
The same activities can also carry leverage and transform credit or liquidity in ways that spread stress through funds, dealers and financing markets. More activity outside bank balance sheets can distribute risk while making some connections harder to see.
The Bank's 2026 work on private credit and market based finance reflects that concern without treating every non bank institution as a threat.
As activity spreads across funds, dealers, lenders and platforms, risk travels with it. Credit, liquidity, customer data and operating dependencies become harder to follow when they are shared across more institutions. Regulators have to preserve the benefits of wider competition while keeping those connections visible.
Banks still anchor the system. Their share of total financial system assets barely changed in 2024. They still dominate broker dealer assets, business lending, deposits and many of the funding relationships behind non bank finance.
The starting points are multiplying. Online brokers compete for investors. Specialty lenders compete for borrowers. PSPs can gain direct payment access. Approved providers can compete around financial data. Eligible new entrants can pursue federal regulation through a clearer process.
Canada's banks remain deeply entrenched, but more of the financial activity around them is open to competition. Incumbents keep the scale while challengers gain more ways to reach customers, move money, originate credit, raise capital and, in some cases, become regulated institutions themselves.
Talking Point
Canada already has C$14 trillion of finance outside traditional banks. More firms are now gaining ways to compete for customers, payments, data, credit and regulated entry while the banks remain dominant.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 3, 2026 | NCFA Market Activity | Digital Banking And BaaS, Regulation And Policy, Payments Infrastructure And Money Movement
On September 3, 2026, Revolut received conditional U.S. bank approval from the Office of the Comptroller of the Currency form Revolut Bank US, N.A., a federally chartered national bank headquartered in Stamford, Connecticut. Revolut says it is still working through FDIC, Federal Reserve and final OCC approvals and remains on track for a 2027 launch. U.S. customers cannot open accounts with Revolut Bank US yet.
Revolut already serves U.S. customers, but the regulated banking are with other institutions. Lead Bank supports Revolut's prepaid card accounts and banking services, while Savings Vault funds are held at Cross River Bank. Revolut controls the app and customer experience, but those partner banks hold deposits and perform key regulated functions.
Revolut says the proposed bank would offer loans, credit cards and FDIC insured deposits, alongside access to stablecoins and cryptocurrencies. Its charter application also describes deposits, savings, business credit, payments, remittances and foreign exchange. Some investment and digital asset services could still sit with affiliates or outside providers rather than inside the bank itself.
Revolut has been working toward this for months. It dropped plans to buy a U.S. bank earlier this year and chose to apply for a new national bank instead. The OCC received the Revolut Bank US application on March 4. Conditional approval six months later gets the company much closer to owning the bank behind its U.S. app.
Today, Revolut can build the app, price subscriptions and design much of the customer experience, but it still depends on banks such as Lead Bank and Cross River Bank for core banking functions. That arrangement helped Revolut enter the U.S. without taking on the full cost of becoming a bank, but it also means product changes, deposit economics and parts of the customer relationship depend on outside institutions.
With its own bank, Revolut could keep more of that customer relationship inside the company. Deposits could sit at Revolut Bank US, lending income could stay within the group and the company could build products without asking a partner bank to support every change. Revolut also says direct access to payment networks such as Fedwire and ACH could make transfers faster and cheaper.
The economics become more interesting at Revolut's current size. Its 2025 financial results included US$6.0 billion in revenue, US$1.7 billion in net profit, US$67.5 billion in customer balances and a US$2.9 billion lending portfolio. Revolut now serves more than 80 million customers worldwide and is adding roughly one million customers every 17 days.
The U.S. opportunity is still much less developed than Revolut's business in Europe and some other markets. A bank charter gives the company a chance to compete for deposits, credit and primary banking relationships rather than mainly offering an app connected to somebody else's bank. Revolut has also committed to invest US$500 million in the U.S. over the next few years as it builds the products and operations around that effort.
Conditional OCC approval is a major regulatory step, but it is not permission to open the bank tomorrow. Revolut still needs FDIC approval for deposit insurance, Federal Reserve approvals for its U.S. holding structure and final OCC clearance. The company also has to finish staffing, capitalization, technology, compliance and operational testing before customers can be moved onto the new bank.
Owning a bank also changes the risk Revolut takes on. A partner bank carries much of the regulated balance sheet today. Revolut Bank US would have to manage its own capital, liquidity, credit losses, consumer compliance, BSA and AML controls, cybersecurity, governance and federal examinations.
Lending makes that especially real. A payments app can process money without taking the same credit risk as a bank making personal or business loans. Once Revolut starts lending from its own balance sheet, growth has to be backed by sound underwriting, reserves, collections and enough capital to absorb losses when borrowers struggle.
The company is already building that structure though. Its application calls for a separate U.S. bank board and senior executives responsible for finance, risk, compliance, legal, lending and operations. Revolut says it remains on track for 2027, but the launch date still depends on regulators being satisfied that the bank is ready to operate safely.
Revolut's first Canadian attempt ended very differently. The company launched a limited beta in 2019 and left Canada in 2021 without establishing a domestic bank. The earlier product was much narrower than the banking business Revolut now operates in several markets.
Jan Pilbauer now leads Revolut Canada, and Revolut has described the market as attractive, but there is still no announced launch date or public Canadian bank licence application. A U.S. national bank charter certainly doesn't give Revolut permission to take deposits or operate a bank in Canada.
If Revolut does return, it would arrive as a much larger and more regulated company than the one that left five years ago. It now operates licensed banks in multiple countries, carries a growing lending book and is building local banking operations rather than relying only on cards and foreign exchange. Canada has also changed, with OSFI's streamlined approvals framework giving eligible new entrants a clearer federal application process.
None of that means a Canadian relaunch is close. It does mean the next attempt, if it happens, could look much more like a full digital bank than the limited product Revolut tested here before.
Revolut is now trying to do something large fintechs often avoid for as long as they can it seems. That is to own a regulated bank, the deposits, the lending and more of the customer economics. That can produce more revenue and more control, but it also means the compliance failures, credit losses and funding mistakes belong to Revolut too.
How much more can Revolut earn when it owns the bank behind the app?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
On September 3, 2026, Canada's July trade report put two stories beside each other. Exports to the United States fell 6.6%, while exports to countries outside the U.S. rose 7.4% to a record C$25.6 billion. Canada's merchandise trade surplus with the world narrowed from C$4.2 billion in June to C$769 million. Its surplus with the United States fell from C$10.3 billion to C$5.9 billion.
Those numbers now sit inside a much rougher political relationship. On August 22, the United States imposed a 50% tariff on roughly US$20 billion of Canadian exports, while the Government of Canada values the affected goods at C$27.6 billion. Canada has rejected the terms on offer and announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
Canada is still deeply tied to the U.S. economy, but the reaction is no longer confined to government. Buy Canadian sentiment has returned. Companies are reviewing suppliers and customers. Travel choices have changed. More Canadian businesses are looking beyond the U.S. at the same time that Ottawa is asking them to absorb the cost of doing it.
The question running through this story is whether the tariff fight is merely disrupting Canada U.S. trade or helping create commercial relationships that remain different even after the politics cool.
The evolving trade war began with a border argument. Washington said Canada was not doing enough on fentanyl and border security. Ottawa said the scale of the problem did not justify an economy wide tariff and answered with retaliation rather than concession.
Ottawa disputed the premise while tightening the border anyway. Canada argued that the U.S. was imposing an economic penalty far larger than the border problem it cited. At the same time, Ottawa strengthened enforcement, giving the fight an early contradiction that never really disappeared.
North America already has a trade agreement designed to make cross border commerce predictable. The surprise is not that Canada and the U.S. disagree. It is that the disagreement can still produce sweeping tariffs while CUSMA remains in force.
CUSMA then became the shield Canadian companies hoped it would be. A large share of continental trade kept moving under the agreement, offering businesses a degree of protection from the broad tariff threat.
The most politically sensitive sectors did not get the same protection. Steel, aluminum and autos became proof that a trade agreement could survive while the industries most tied to jobs, factories and regional politics still took direct hits.
CUSMA remains in place, but businesses now know that compliance with the agreement does not eliminate every tariff risk. A company can remain inside the North American trade framework and still be exposed to a separate sector fight.
Canada entered the 2026 CUSMA review looking for certainty and left without it. Ottawa wanted companies to know the North American rules would hold for another generation of investment. The review did not deliver that reassurance.
The United States did not give Canada the long runway it wanted. The agreement stayed alive, but companies making plant, supplier and capital decisions measured in years were left with a shorter political horizon.
The agreement remains in force. But the failed long term extension means companies can no longer assume the relationship will simply return to the old operating model after one review.
Then the tariff ceiling moved again. After bilateral talks failed, Washington raised the pressure to levels that made another Canadian response almost unavoidable. The dispute was no longer about whether tariffs would remain. It was about how much economic pain each side was willing to absorb.
Canada chose retaliation over the deal on the table. Ottawa said the U.S. terms would leave Canadian workers and businesses worse off. Canada announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
This is where the fight stops looking like a temporary tariff negotiation and starts looking like a choice about economic autonomy. Canada is accepting the risk of another round of costs rather than take terms Ottawa says would leave important industries worse off.
Trump then turned Lake Ontario into part of the dispute. The Lake America order gave Canadians something more visceral than a tariff table to react to. A fight over market access suddenly had a symbol that touched geography, identity and sovereignty.
The symbolism hit a country already primed to push back. The tariff fight had been accompanied by statehood rhetoric and repeated claims that Canada depended too heavily on the United States. The lake renaming made the argument feel less like a dispute over customs schedules and more like a challenge to Canadian identity.
A tariff can feel remote until it affects a price, a contract or a job. Renaming a shared Canadian lake for U.S. federal purposes created a cultural symbol that was easier to understand and harder to separate from the wider sovereignty argument.
Canadian resistance is showing up in everyday choices. Buy Canadian sentiment has strengthened as consumers reconsider groceries, travel, technology, vehicles and other purchases. Businesses are also reviewing where they source products and whether U.S. dependence still looks commercially sensible.
American opinion is much less supportive of the escalation. A Reuters Ipsos poll found 57% of Americans opposed the latest tariffs on Canada and only 20% supported them. The same poll found 63% opposed Lake America and 14% supported it.
Canadian patriotism has many sources, so the tariffs should not be treated as the sole cause. But the observable response to repeated tariff threats, statehood rhetoric and Lake America includes stronger Buy Canadian behaviour, support for retaliation and a more explicit case for economic self reliance.
Some companies are acting on the anger instead of waiting it out. Reuters reported that Chapman's Ice Cream plans to cut U.S. imports by 70% by mid 2027. Other firms are reviewing suppliers, sourcing more at home and looking for customers outside the United States.
Once a supplier is replaced, politics may not put the old relationship back together. New contracts, certifications, logistics routes and internal processes create switching costs. A future agreement could remove a tariff quickly while leaving behind commercial relationships built during the dispute.
This is where a patriotic reaction can become structural economic change. The first purchase may be emotional. The lasting effect depends on whether Canadian and non U.S. alternatives become good enough to keep the customer or supplier relationship after the anger fades.
The July numbers show Canada really is looking elsewhere. Exports outside the United States rose 7.4% to a record C$25.6 billion. Non U.S. destinations accounted for roughly one third of Canadian merchandise exports in July.
America is still too large to replace quickly. Canada's trade surplus with the U.S. fell to C$5.9 billion in July, while Canada ran a C$5.1 billion deficit with countries outside the U.S. More trade elsewhere reduces concentration before it replaces the commercial value of the American market.
The record non U.S. export figure shows diversification was already underway before the August 22 escalation. It does not prove the newest tariffs caused the change. It does show Canada was already finding more business outside the U.S., even while the American market remained too large to replace quickly.
Every new route creates another bill before it creates resilience. New buyers can require longer shipping, different payment terms, more foreign exchange and more working capital. New suppliers can require deposits, inventory changes and fresh credit checks. The cost arrives before the exporter knows whether the new relationship can match the economics of the old one.
Canada can become less exposed to one market while making individual companies more complicated to finance. Diversification works only if firms have enough liquidity to survive the period between leaving an old relationship and making a new one profitable.
Lenders now have to see tariff risk before the financial statements do. U.S. customer concentration, tariff sensitive inputs, margin exposure and the time needed to replace a buyer can change a borrower's risk within weeks. Historical revenue can therefore look healthy while the economics underneath it are already deteriorating.
Payments, foreign exchange and treasury providers face the opposite problem. More destinations create more currencies, settlement routes, counterparties and cash timing issues. The same diversification that reduces geographic concentration can increase demand for cross border payments, hedging, trade finance, receivables tools and working capital.
Trade policy becomes financial services work once companies start changing customers and suppliers. Credit has to recognize new exposure sooner. Payments have to reach more markets. Treasury teams have to manage more currencies. Working capital has to cover the period before new trade relationships mature.
Markets still assume some of this confrontation eventually fades. Currency forecasts are already looking past the current hostility and pricing a calmer relationship later. Businesses have less freedom to wait for that version of the future.
Businesses cannot wait for that forecast to come true. Carney said on September 1 that the United States must start being serious before talks can resume. At that point no new bilateral negotiations were scheduled. A company choosing a supplier, market or plant location has to make the decision under today's rules.
That is the deeper consequence of the dispute. Governments can reverse tariffs quickly. Companies that have spent months replacing suppliers, winning customers and building payment routes may have less reason to go back. The tariff war could therefore leave a commercial footprint that lasts longer than the tariffs themselves.
Talking Point
Trump's tariff campaign has done more than raise the cost of Canada U.S. trade. It has turned economic dependence into a Canadian political issue, revived Buy Canadian behaviour and pushed companies to look harder for customers and suppliers elsewhere. The unresolved question is whether that response leaves Canada with stronger companies and more durable trade relationships or simply a more expensive way to do business.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 27, 2026 | NCFA Resource | Open Banking And Consumer Driven Finance, Risk Compliance And Regtech, Artificial Intelligence And Data
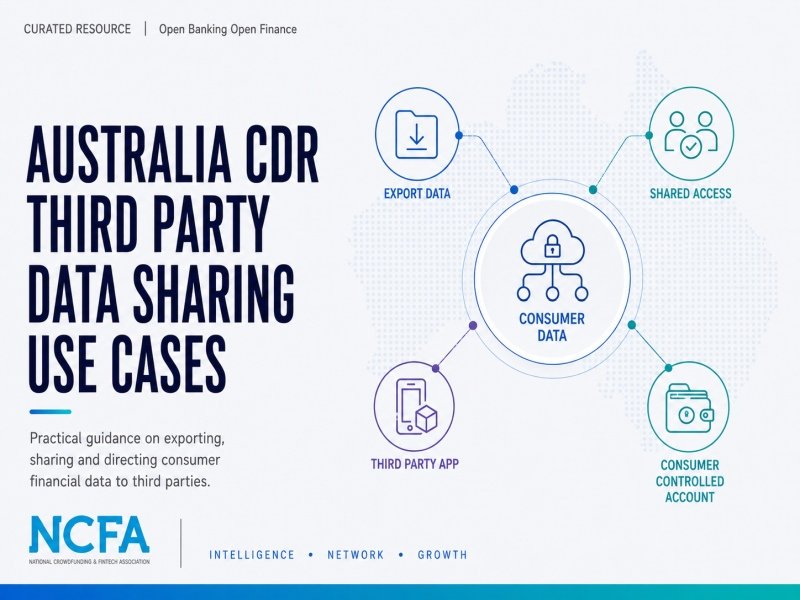
On January 27, 2026, Australia’s Consumer Data Right updated its Third Party Data Sharing Use Cases with practical examples showing how consumers can export financial data, give another person access, send data to another application or direct it into an account they control.
The Australian Competition and Consumer Commission developed the guidance with input from Treasury. It tackles a straightforward product question. After an accredited provider receives a consumer’s financial data, what can the consumer do with it next?
The answer depends on who initiates the sharing, where the information goes and who controls the destination. Those details affect consent, privacy and the provider’s responsibilities.
The guidance organizes third party sharing into four situations:
Who initiates the sharing is the key distinction. The ACCC says these consumer directed scenarios are unlikely to raise compliance concerns when the consumer makes a clear and informed choice. Downloading data, configuring access or instructing the provider to send information helps establish that the consumer chose the disclosure.
If the provider is making the disclosure itself, the permitted use and disclosure rules apply. The provider needs the authority and consent required under Australia’s Consumer Data Right rules.
That difference becomes concrete in product design. Letting someone download transaction history for personal analysis carries different responsibilities from automatically sending customer information to another company. Giving an accountant controlled access inside an SME finance platform is also different from transmitting the data outside that service.
Where the financial data remains inside the accredited provider’s service, the provider continues to carry the relevant Consumer Data Right obligations. These include privacy safeguards covering data security and the destruction or de-identification of information that is no longer required.
When consumers send their data outside that environment, they need to know how the recipient will handle it. The ACCC says providers should explain that other privacy laws may apply and encourage consumers to review the recipient’s data handling policies.
The same framework can support a single disclosure or recurring sharing for a defined period. The provider must hold the collection and use consents required for the service. Consumer Data Right consent generally lasts for up to 12 months, while some business consumer consents can extend for up to seven years.
Fintech product teams can use these examples when building financial data portability into real services. A personal finance app could let customers export transaction data for their own analysis. An SME platform could give an accountant controlled access to business records. A lending or cash flow application could let customers send selected information into another service they already use.
Compliance and legal teams can review the same features by asking a few direct questions. Who initiated the disclosure? Who controls the destination? Does the information stay inside the accredited service? What consent supports the sharing? Which obligations continue once the data leaves?
Banks and other financial institutions can use the examples to anticipate how customers may expect data portability to work. Consumers are unlikely to organize their behaviour around regulatory terminology. They will want financial information to work with budgeting software, accounting systems, lending applications, analytics tools and other services they choose.
Canada will face similar product questions as Consumer Driven Banking reaches implementation. Canada Open Banking And Consumer Driven Banking Rules tracks accreditation, authentication, consent, data sharing, security and liability requirements. Australia’s examples show what product teams have to consider after the first regulated transfer, when a customer wants to reuse the information somewhere else.
Standardized financial data can support credit assessment, fraud detection, cash flow analysis and financial guidance as well. NCFA’s Open Banking Decision Intelligence looks at how firms can turn permissioned financial data into better decisions. Third party sharing gives consumers and businesses more control over which tools can participate in those workflows.
The four examples are specific enough to use in product and compliance discussions. Teams can look at an export button, an accountant access feature, an application-to-application transfer or recurring sharing arrangement and ask exactly who controls the data at each point.
The guidance also shows why interface design and compliance cannot be separated. A button that lets the consumer choose where information goes can create a different regulatory position from a service that sends the same information on its own. Consent, control of the destination and whether the provider continues to hold the data all affect the answer.
That's useful context for Canadian teams working through consent and downstream data use. Canada can define who participates in regulated sharing and how financial institutions transfer data to accredited recipients. Customers will still want to download that information, share it with professionals, use it in another application or authorize access over time.
Australia’s rules do not determine what Canadian firms can do. The two countries have different legislation, privacy requirements, accreditation models and regulatory terminology. The Australian examples are useful because they expose practical questions Canadian product, compliance and policy teams will also have to answer.
The ACCC also makes clear that the article is general guidance. Whether a particular implementation complies with Australia’s Consumer Data Right depends on the circumstances, and providers remain responsible for assessing their legal obligations.
Consumer Data Right (Australian framework, participants and consumer information)
Legal Obligations For Data Recipients (collection, consent, use and disclosure requirements)
CDR Privacy Safeguard Guidelines (privacy requirements for handling consumer financial data)
Canada’s Open Banking Strategy Starts With Trust (consent, fraud, liability and consumer protection in Canada)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 28, 2026 | NCFA Market Activity + Insight | Capital Markets And Market Infrastructure, Risk Compliance And Regtech, Regulation And Policy, Wealthtech Investing And Trading
On August 28, 2026, the Commodity Futures Trading Commission penalized Gabriel Perez for prediction market insider trading after finding that he used confidential presidential speeches to trade event contracts for his own benefit. Perez worked as a White House technical adviser and teleprompter operator, which gave him access to prepared remarks before President Donald Trump delivered them.
Perez generated US$107,539.02 in profits by trading contracts on words and phrases the President would mention. He must return those profits, pay a US$65,000 civil penalty, stop violating the Commodity Exchange Act and stay out of CFTC regulated trading for three years. Perez consented to the settlement without admitting the CFTC's findings or legal conclusions, and the Commission says his cooperation justified a substantial reduction in the civil penalty. The CFTC also thanked KalshiEX for assisting the investigation.
As event contracts attract more volume, products and mainstream distribution, exchanges need to do more than price outcomes and settle trades. They need credible ways to identify when someone may know the answer before everyone else.
A mention market lets traders take a Yes or No position on whether a word, phrase or term will appear during a defined event. Perez opened his Kalshi account on December 8, 2025 and traded markets tied to presidential speeches, including addresses, rallies, policy remarks and the State of the Union.
The CFTC order says Perez generally saw prepared remarks about an hour before the President spoke. He bought Yes contracts when the target word appeared in the speech and No contracts when it did not. On one occasion, he changed his position after watching the President skip part of the prepared text.
Perez traded across 14 presidential mention markets and made money on 39 of 43 contracts. He was not making a better forecast than other traders. He had already seen the prepared remarks and knew whether many of the words being traded were present.
Traditional financial markets already deal with executives, advisers and employees who may hold valuable information before investors receive it. Event contracts can create a much wider group of people with direct knowledge of an outcome. A political speech can involve writers, production staff, government employees and technical crews, while sports, entertainment and corporate events can involve players, coaches, producers, employees, advisers or others close to the result.
That risk was visible before federal enforcement arrived. Kalshi's earlier insider trading cases included a MrBeast editor and a California political candidate, and the exchange said it had opened roughly 200 investigations or probes. Those cases showed that integrity work was already becoming part of running an event market. The Perez action is more consequential because the CFTC is now applying federal commodities law directly to misuse of confidential information in prediction market contracts.
The integrity problem can also extend beyond advance knowledge. Some traders may know an outcome early, others may be able to influence it, and some may hold information through a public duty or private relationship. That makes the source of the information as important as the trade itself.
The CFTC order and what the public record shows is that investigators could connect Perez's account, government role, speech access, trading times and profits. For prediction markets, knowing who is behind an account matters as much as spotting an unusual trade.
Traditional surveillance remains important. Exchanges can look for unusual profits, concentrated positions, repeated success, trading immediately before an event and activity that doesn't fit a customer's normal behaviour. Prediction markets add another requirement because suspicious trading may only make sense once the account is connected to a job, relationship or source of access outside financial markets.
A trader repeatedly winning presidential speech contracts becomes far more interesting if the exchange or regulator also knows that person works on presidential events. The same logic applies to sports personnel trading injury or lineup contracts, employees trading corporate outcomes or production staff trading entertainment events.
Exchanges need to know who is trading, what access they may have to the event and whether their trading pattern fits that access. Reliable customer identity, account history and information about relevant jobs or relationships can help investigators decide whether an unusual trade deserves a closer look. Surveillance teams need tools that can connect trading patterns with occupations, relationships and event access. Case management, alert review and auditable investigation records become more important as the number of contracts and traders grows.
This boosts the commercial case for regulated event contract infrastructure. Market surveillance, identity controls, outcome verification, compliance workflows, investigation tools and regulator reporting are becoming part of what platforms need to operate credible markets, alongside matching, pricing and settlement.
Different contracts also require different surveillance assumptions. An inflation contract settles on a formal public release. A presidential mention contract may depend on a speech seen by staff shortly before delivery. A sports contract can depend on injury or lineup information known to a relatively large group before the public learns it. Exchanges need to understand how each event is produced, who may know the answer early and who can influence the result before they can decide what suspicious trading looks like.
Prediction markets are reaching customers through larger financial platforms, which brings more liquidity but also more accounts and more activity to monitor. Recent CSA and CIRO guidance on prediction markets keeps sports and entertainment event contracts outside Canada's securities dealer channel, while Wealthsimple Investments and Interactive Brokers Canada can offer a narrower set of economic, environmental and financial contracts under CIRO conditions.
The CFTC case also shows that regulators are prepared to use existing commodities rules when confidential information is abused. Exchanges and distributors therefore need to spot suspicious activity early, connect it to useful account information, investigate it and keep records that can support enforcement.
That creates a practical market for surveillance, identity, behavioural analytics and case management tools. Prediction markets have already proved they can attract products, liquidity and mainstream distribution, but can market integrity keep up.
Can prediction markets scale faster than their ability to detect who knows the outcome before everyone else?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 28, 2026 | NCFA Insight | Regulation And Policy, Capital Markets And Market Infrastructure, Wealthtech Investing And Trading, Risk Compliance And Regtech
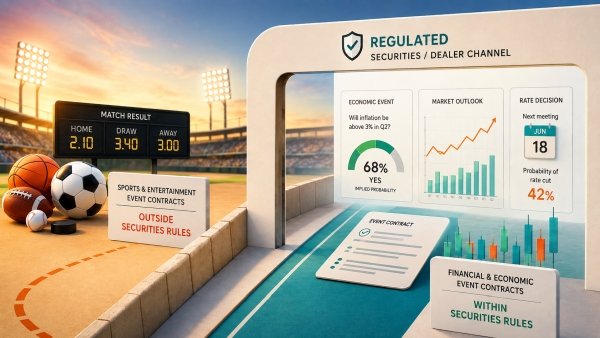
On August 27, 2026, the Canadian Securities Administrators (CSA) and Canadian Investment Regulatory Organization (CIRO) issued new guidance on sports and entertainment event contracts. The CSA says those contracts belong outside securities and derivatives regulation, and CIRO will not approve dealer members to trade them.
The decision closes the securities-dealer route without banning every sports prediction market category under every Canadian law. Gaming and other applicable rules can still determine what is permitted elsewhere, but Canadian investment dealers now know sports and entertainment will not join the event contracts they can distribute through CIRO.
CIRO currently allows two investment dealers, Wealthsimple Investments Inc. and Interactive Brokers Canada Inc., to facilitate a limited set of contracts tied to economic forecasts, environmental outcomes and financial indicators. Permitted contracts generally need at least 30 days to maturity, clients cannot use leverage, and elections, referendums, political nominations and other political events remain prohibited.
In the U.S., sports category helped prediction markets reach a much larger audience. Prediction Markets Tighten As Wealthsimple Enters noted in March that a March Madness winner contract had already exceeded US$100 million in volume and 2026 Super Bowl contracts topped US$1 billion. Canada is now explicitly removing that demand interest from the securities-dealer channel.
That leaves economic, environmental and financial contracts to prove they can generate repeat participation and enough liquidity to remain useful. Rates, inflation, housing and climate outcomes can carry real forecasting value, but they don't naturally produce the same frequency, fan interest or habitual trading as professional sports.
Platforms are also experimenting with how prediction markets are presented. CRSHMARKET's livestream prediction-market model combines live video, creators and event contracts to make participation more immediate. That doesn't change Canada's regulatory limits, but it highlights why product format is important to growth if permitted contracts have to compete for attention without sports.
A contract within CIRO's permitted categories can potentially reach Canadian clients through an authorized investment dealer, while sports and entertainment contracts cannot use that route. Product teams therefore need to understand the event being priced, the applicable regulator and the distribution rules before estimating the addressable market.
As a result, the need for regulated event contract infrastructure is more valuable. Platforms need compliance controls, market surveillance, outcome verification, settlement and dealer integration, but they also need to know which contracts can be offered through which channel.
Infrastructure providers that help firms classify products, apply the right controls, integrate regulated distribution and settle outcomes can serve multiple markets even when the permitted contract set differs by jurisdiction.
CSA and CIRO say they are still assessing other types of event contracts. They haven't said which additional categories may eventually fit inside securities and derivatives regulation or which will remain outside it.
Those decisions will help determine the size of Canada's regulated prediction-market business. If CIRO dealers remain concentrated on economic, environmental and financial indicators, the sector may develop mainly as a forecasting and investment product. Additional permitted categories could create more reasons to trade and more opportunities for liquidity to build.
Regulators still need to consider market manipulation, insider information, outcome integrity and whether a particular event belongs inside financial regulation at all.
Can Canadian prediction markets build enough liquidity around economic, environmental and financial events without the sports contracts that helped drive U.S. adoption?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 28, 2026 | NCFA Insight | Open Banking Open Finance And Data Sharing, Digital Identity And Trust, Risk Compliance And Regtech, Cybersecurity And Fraud
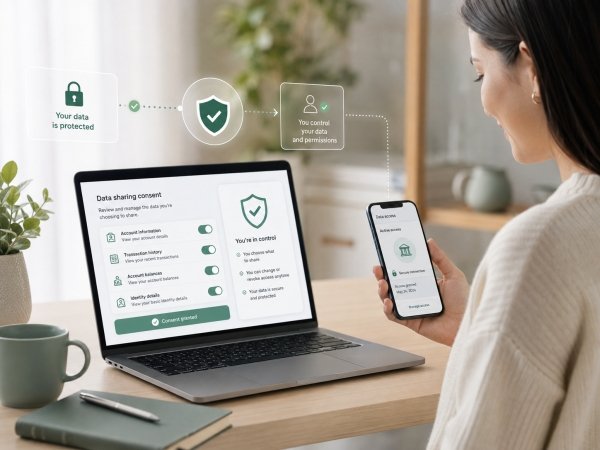
On August 26, 2026, Canada’s Office of the Privacy Commissioner (OPC) called for five changes to Canada’s proposed Consumer-Driven Banking Regulations including what financial data can be shared, what firms must prove before accreditation, when public data can be reused without consent, how security keeps pace with new threats, and how the Bank of Canada and Privacy Commissioner coordinate oversight.
The submission arrived on the last day of the government's 60-day consultation, which closed August 26. Finance Canada now has to decide which recommendations make it into the final regulations before Canada's open banking system starts moving from rulemaking into accreditation and implementation.
The Commissioner supports consumer-directed data sharing, multi-factor authentication and mandatory breach reporting to the Bank of Canada. The five requested changes go further and could affect compliance costs, product design, consumer trust and which fintechs can afford to participate.
The proposed regulations cover identity information, account identifiers, fees and terms, balances, transactions and information about financial products. The OPC says those categories aren't detailed enough for consumers to know exactly what information they are agreeing to share and points to Australia’s Consumer Data Right as a more precise model.
It's important when someone is looking at a consent screen. "Identity data" doesn't tell a customer whether a provider will receive a name, address, email, phone number or other information.
The issue becomes more important as firms combine bank data with other sources and use it for credit, fraud, pricing or financial recommendations. Open banking decision intelligence becomes more valuable as firms infer more from permissioned financial data, which makes precision about what was actually shared even more important.
If Canada wants meaningful consent, people need to know what is leaving their bank before they approve it.
The proposed rules offer four accreditation routes under Bank of Canada oversight, including streamlined treatment for payment service providers already registered under the Retail Payment Activities Act. The OPC wants stronger proof from some applicants, including evidence that security controls are working, technical standards are being met and authentication and complaint processes are ready.
It also wants certain financial institutions to show that people responsible for consumer-driven banking have been assessed for good character and integrity, and that insurance or other guarantees are available to manage data-related risks.
That raises the accreditation bar for good reason. Accredited firms may receive account identifiers, balances, transaction histories and other highly sensitive information. The commercial question now is how much proof Canada requires and what it costs credible firms to provide it.
Finance Canada estimates the proposed regulations will generate C$13.2 billion in benefits over ten years while adding about C$457.7 million in regulatory costs. Under the government's central scenario, roughly 680 businesses participate initially, including 578 small businesses, with an estimated average annualized regulatory cost of C$89,133 for each small business.
Large financial institutions can spread fixed security, legal and reporting costs across millions of customers. Smaller fintechs can't. Canada needs to keep poorly prepared firms away from consumer financial data without making the cost of proving readiness another advantage for incumbents.
The OPC also wants Finance Canada to narrow an exception that allows some publicly available information to be used without consent. Its recommendation is that public data should not include information where a consumer still has a reasonable expectation of privacy.
Information can technically be public without someone expecting it to be collected, combined with financial records and reused inside a commercial service. Open banking makes those combinations easier and potentially more valuable.
The final rules therefore need to protect against a consent loophole where one piece of public information becomes a reason to use financial information in ways the customer didn't reasonably expect.
The proposed regulations already require vulnerability management, authentication, encryption, network protection, employee training and tested incident-response plans, with those controls applied in proportion to the sensitivity of the data. The OPC wants an additional obligation requiring firms to keep those safeguards appropriate as technology and cyber risks evolve.
That's certainly more demanding than completing a checklist once. After a breach, a firm could still have to show that its security was appropriate for the data it held and the risks it should reasonably have been managing.
For banks and fintechs, security readiness therefore becomes an ongoing operating requirement. Canada's proposed open banking requirements already span accreditation, authentication, security, technical standards, liability, complaints and Bank of Canada supervision. Companies preparing to participate need proof that those controls actually work, not just policies saying they exist.
The Bank of Canada will supervise consumer-driven banking participants while the Privacy Commissioner continues to oversee federal private-sector privacy obligations. A serious data breach can involve both, so the OPC wants explicit authority for the regulators to coordinate their work and share information where necessary.
Without that, companies can face overlapping requests and investigations while an important issue still falls between mandates. When customer data is exposed, management needs to know who must be notified, what each regulator expects and how the two authorities will divide the work.
Clear coordination is especially important because Canada is trying to replace a system millions of people already use. Finance Canada estimates roughly nine million Canadians currently rely on financial-data services using credential-based screen scraping. Regulated API access should reduce important security and liability risks, but only if supervision works cleanly when something goes wrong.
The OPC is asking Finance Canada to be more precise about what data moves, who can receive it and what firms must prove before they get access. Those protections however cost money. Independent security work, technical compliance, authentication, insurance, reporting and complaint processes all consume capital that a younger company could otherwise spend on product development, hiring or customer acquisition.
The answer isn't weaker safeguards. Financial transaction data is too sensitive for that. The challenge is to determine whether each requirement addresses a real risk and whether the cost is proportionate to the firm, activity and data involved.
Canada's C$13.2 billion benefit estimate assumes firms enter the market and build services people want to use. Open banking opportunities in Canada already span verification, cash-flow tools, SME services, financial management and future payment initiation, but APIs alone won't create competition.
Consumers need providers they trust, and credible challengers need a realistic way to qualify. The final rules will help decide both.
How high can Canada raise the privacy and security bar for open banking before the cost of clearing it starts protecting incumbents from the competition the system is supposed to create?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
The Privacy Commissioner wants clearer rules in five areas: exactly what financial data can be shared, what firms must prove before accreditation, when publicly available data can be used without consent, how security safeguards should keep pace with changing threats, and how the Bank of Canada and Privacy Commissioner coordinate oversight.
No. The 60-day consultation on the proposed Consumer-Driven Banking Regulations closed on August 26, 2026. Finance Canada now has to decide what changes to make before the regulations are finalized.
Yes. Stronger accreditation, security, insurance and compliance requirements can improve consumer trust and keep poorly prepared firms out, but they also raise the cost of participation. The challenge is setting a high enough bar to protect financial data without making open banking too expensive for credible smaller fintechs to enter.
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
