





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 15, 2026 | NCFA Market Activity | Digital Banking And BaaS, Cross Border Payments And FX, Competition And Market Structure

On September 14, 2026, UK-based global payments company Wise launched a Chequing Account in Canada with no monthly fee, Interac e-Transfer support, Canadian account details, pre-authorized debits, debit-card access and multi-currency features. The launch takes Wise further into everyday Canadian financial activity while keeping the cross-border tools that built its original customer base.
The account is available to personal and business customers in Canada. Customers can hold more than 40 currencies, receive money using account details available across 22 currencies and send money to more than 70 countries. Wise converts currencies at the mid-market rate and charges a separate conversion fee that currently starts from 0.19%, depending on the currency and transaction.
Canadian customers can send up to C$25,000 to a supported Interac email address and receive up to C$25,000 per day through Interac Autodeposit. Wise doesn't charge its own fee to receive Autodeposit payments, and the September launch removed the Wise fee for sending CAD to an Interac alias and adding CAD through Interac. Incoming transfers that require a security question and manual acceptance aren't currently supported, and an email registered for Wise Autodeposit can't remain registered for Autodeposit at another financial institution.
Wise also provides Canadian institution, transit and account numbers for electronic deposits and withdrawals. Customers can receive pay, set up pre-authorized debits for recurring bills, spend through a physical or digital debit card and withdraw cash at ATMs. Wise currently charges no withdrawal fee on the first C$100 each month, then C$2.69 plus 2.69% on the amount above C$100, while an ATM operator can charge its own fee.
Group Spend lets customers create a shared balance for expenses such as household bills or trips. Wise's international features are still a key difference. Customers can hold CAD and dozens of other currencies in one account, convert between them and receive money using account details available in 22 currencies.
Wise Payments Canada Inc. is not a Canadian bank. It is registered with the Financial Transactions and Reports Analysis Centre of Canada as a Money Services Business under registration M15193392 and with the Bank of Canada as a payment service provider under the Retail Payment Activities Act. It also holds a Quebec money services business licence.
Wise keeps customer funds separate from its operating money under Canada's payment-safeguarding rules. For its Chequing Account, Wise says eligible deposits are held in trust at a Canada Deposit Insurance Corporation member institution with customers identified as beneficiaries. Eligible deposits can receive CDIC protection of up to the equivalent of C$100,000 per beneficiary if the member institution fails and the trust-disclosure requirements are satisfied; Wise itself is not a CDIC member.
Foreign-currency balances aren't automatically excluded because CDIC can cover eligible deposits in Canadian or foreign currency. Coverage still depends on the deposit meeting CDIC rules, and balances held for the same customer at the same member institution can be combined when insurance limits are calculated.
Wise also became a Payments Canada member in January 2026 after federal rule changes opened membership to regulated payment service providers. That gives Wise a formal role inside Canada's payments system and makes eligible PSP members able to seek participation in payment systems under the applicable rules. Membership doesn't automatically give Wise direct access to every Canadian payment rail.
Canadian consumers can already choose among traditional banks, digital banks and fintech accounts that cover much of the same daily activity. Wise competes with domestic payment functions and a deep multi-currency product, while using a regulated non-bank structure for the account itself.
Big Six banks: Traditional banks still combine chequing with lending, credit, branches, drafts and direct deposit-taking. RBC Day to Day Banking, for example, has a standard C$4 monthly fee and includes 12 debit transactions plus unlimited Interac e-Transfers. Wise removes the monthly fee and adds much deeper multi-currency functionality, but it doesn't replace the full range of services available through a bank.
Wealthsimple: Wealthsimple has expanded deeper into everyday banking with chequing, payments, direct deposit, cards and other daily money tools. Customer cash is held in trust with CDIC member institutions rather than by Wealthsimple as a bank. Wise has the stronger cross-border proposition through currency holding, foreign account details and international transfers.
KOHO: KOHO combines prepaid-card spending, Interac transfers, Autodeposit and bill payments, with customer funds held through a trust structure designed to qualify for CDIC protection. Its product is centred more heavily on Canadian spending, credit building, rewards and budgeting, while Wise puts international money management at the centre of the account.
EQ Bank: EQ Bank's Personal Account also has no monthly fee and includes unlimited Interac e-Transfers, bill payments, direct deposit and card access. The legal model is different because EQ Bank is a trade name of Equitable Bank, a federally regulated bank and CDIC member that accepts deposits directly. EQ already uses Wise for international transfers, making it both a competitor in everyday banking and a distribution partner for Wise's cross-border capability.
Neo Financial: Neo gained direct Interac e-Transfer access in April 2026 and offers digital chequing functions including Interac transfers, bill payments, pre-authorized debits and card spending. Its focus is more Canadian spending, credit and rewards, while Wise brings a much deeper international money layer.
Wise now covers many of the tasks that keep a chequing account central to a customer's financial life, while adding something most Canadian chequing products don't offer at the same depth: one account built around both domestic use and frequent cross-border money movement.
Canada's regulatory changes give non-bank providers more room to compete for that relationship. RPAA supervision applies operational-risk and safeguarding requirements to payment service providers, while Payments Canada membership brings qualifying fintechs closer to national payment systems. Consumer-driven banking could extend that competition further if customers gain easier ways to connect financial data and services across institutions.
Wise is also giving the launch a physical presence through a temporary pop-up at Toronto Eaton Centre on Level 1 from September 14 through October 11. Customers can register, get product help and participate in launch promotions there, but the location is a Wise promotional and service activation rather than a Canadian bank branch.
Wise can now handle many of the transactions Canadians associate with a primary chequing account while remaining a regulated non-bank provider. How much of the everyday banking relationship can fintechs win before customers care less about whether their main account comes from a bank?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Sep 15, 2026

Image credit: Pexels
Market volatility remains a persistent factor in wealth management, driving investors to seek strategies that balance capital stability with strategic diversification. While physical property has traditionally served as a tangible asset class, direct ownership often carries operational friction and localized concentration risk. Real estate funds present a structured alternative, pooling capital to access larger-scale assets under professional administration. However, evaluating these vehicles requires a realistic understanding of their risk profiles, liquidity terms, fee structures, and underlying statutory frameworks.
Managed real estate portfolios offer distinct operational benefits while introducing clear structural constraints:
While European Union institutions have increasingly pressured member states to restrict residency-by-investment programs, specific national jurisdictions maintain defined statutory pathways. Hungary’s Guest Investor Program offers a structured framework for international investors seeking European mobility alongside capital allocation.
Unlike former European programs that encouraged direct residential purchases—often driving up local housing prices—the Hungarian framework emphasizes institutional, regulated fund vehicles. Under this legal framework, securing a Hungary Golden Visa through real estate fund investment requires strict adherence to statutory criteria:
Long-term portfolio resilience requires evaluating operational realities beyond the initial statutory holding period:
Regulated real estate funds operate under strict prudential oversight, with the MNB supervising legal compliance, market solvency, and reporting standards. While professional management aims to optimize operational performance and generate targeted income distributions, yields are never guaranteed and remain subject to market conditions, management fee drag, and occupancy rates.
When integrated into a broader wealth strategy, managed real estate funds offer a transparent method for participating in property markets and achieving long-term mobility goals—provided investors align their liquidity expectations with the regulatory realities of the underlying vehicle.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 14, 2026 | NCFA Insight | Cross Border Payments And FX, Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization, Competition And Market Structure

On September 12, 2026, BRICS leaders met in New Delhi for the 18th BRICS Summit and backed further work connecting national payment and financial messaging systems. The New Delhi Declaration confirms that the BRICS Payment Task Force has been studying cross border interoperability and the use of local currencies for trade settlement and investment.
BRICS hasn't yet created a common payment network or digital currency. However, payment interoperability has moved into an official technical workstream rather than remaining a series of proposals from individual members.
The progression has been fairly quick. India proposed stronger payment and central bank digital currency connectivity in January. In August, Reserve Bank of India Governor Sanjay Malhotra confirmed that members were discussing links between fast payment systems and central bank digital currencies. The September declaration gives the Payment Task Force a formal basis to continue that work across the bloc.
The commercial backdrop has also changed significantly since we last covered the 2023 BRICS summit. The group has expanded, supply chains have been rerouted, trade relationships have become more politically charged and tariffs are again influencing where companies manufacture and sell. BRICS now accounts for nearly one quarter of global trade, while intra BRICS merchandise trade reached US$1.17 trillion in 2024.
For banks, payment companies and fintechs, that scale changes the economics of interoperability. Existing domestic payment systems already process enormous volumes. Connecting more of those systems across borders could affect routing, settlement costs and access to large emerging markets without waiting for a new monetary system to be built.
The declaration focuses on systems that members already operate. The Payment Task Force has studied interoperability between payment and messaging channels and discussed using BRICS currencies for trade and investment. Leaders want further work on cross border payments that are faster, cheaper and easier to access while remaining secure.
India brings considerable operating scale to that discussion. Its Unified Payments Interface processes more than 250 billion transactions annually and is accepted in 11 countries. Other BRICS members have their own domestic payment rails. Connecting those systems can be faster than designing a single BRICS network from scratch.
A merchant payment could still require foreign exchange and liquidity between two currencies. Banks would still need compliance controls, and somebody has to settle the transaction. Interoperability can reduce some of the handoffs between institutions without making those functions disappear.
Local currency settlement can develop alongside those links. A company trading between India and another BRICS economy may eventually have more ways to invoice or settle without routing every transaction through a third currency. That can remove a conversion in some transactions, although the underlying currencies still carry exchange rate risk.
Russia has pushed back against describing every BRICS payment initiative as an attempt to abandon the U.S. dollar. More payment choices and greater use of domestic currencies don't require members to stop using dollars where the economics favour them.
The New Development Bank is pursuing a related approach through financing. BRICS leaders want it to expand lending in local currencies and diversify its funding. Borrowers that can raise money in the same currency as their revenues may face less foreign exchange exposure.
Payments can't be separated from what is happening to trade. The New Delhi Declaration warns that rising tariffs and other unilateral trade measures can reduce global trade, disrupt supply chains and add uncertainty for businesses. BRICS finance ministers made the same point before the summit, criticizing unilateral trade and financial measures and calling for more coordination among member economies.
The pressure is visible in 2026. The United States imposed a new 25% tariff on selected Brazilian exports in July, covering billions of dollars in goods. Brazil said it would pursue alternative markets if access to the U.S. became more difficult. India has also taken a harder line in U.S. trade negotiations while expanding commercial ties with Europe and other markets.
China offers another lesson. Companies spent years moving manufacturing into Southeast Asia and India to reduce exposure to U.S. tariffs, yet some are now returning production to China because supplier networks, skilled labour and operating efficiency remain difficult to reproduce elsewhere. Tariffs can redirect investment, but they don't erase the economics of established supply chains.
BRICS members are responding by trying to strengthen trade within the bloc. India has called for more open markets, simpler customs procedures and deeper supply chain links. Intra BRICS merchandise trade has grown thirteenfold since 2003, reaching US$1.17 trillion in 2024.
Payment connectivity becomes more valuable as those trade relationships deepen. A Brazilian exporter selling into India, or an Indian company sourcing from China, benefits more from direct payment links when the underlying commercial relationship is large enough to support liquidity and repeat transactions.
For Canada and other economies heavily exposed to the U.S. market, the development is worth watching. Tariffs are pushing governments and companies to diversify customers, suppliers and financing relationships. BRICS is building payment and trade links across many of the markets companies may increasingly look to as alternatives.
Central bank digital currencies remain much less developed as a BRICS payment option. Members operate at different stages of CBDC research, testing and deployment, making a common technical model harder than connecting established fast payment systems.
Sanjay Malhotra, Governor, Reserve Bank of India:
"Various options are on the table, but it is still at discussion stage, including CBDCs and linkages of fast payment systems."
The September declaration didn't announce a CBDC pilot or identify central banks that will participate in one. There is no shared rulebook for settlement, liquidity or foreign exchange conversion and no governance structure for a BRICS CBDC network.
Fast payment links can progress without solving all of those problems at once. A connection between two existing national systems can use currencies and regulated institutions that already operate in each market. Additional bilateral links could later connect into a larger network if members agree on common technical and regulatory rules.
BRICS may therefore develop as a collection of connected domestic systems rather than one centralized network. Fintechs could compete in routing, FX, merchant payments and technical connectivity without waiting for a common BRICS currency.
NCFA has seen a similar commercial principle in other markets as direct access to payment rails expands. More direct access can give fintechs greater control over costs and service delivery, provided the regulatory and operating requirements still support a sustainable business.
Traditional correspondent banking often sends a cross border payment through several institutions before it reaches the recipient. Each participant can add time, cost and another reconciliation step. Direct connections between national payment systems could shorten some routes, particularly where participating banks already have liquidity in both currencies.
Payment companies could help merchants reach new markets, while fintechs build routing and FX services around connected domestic rails. Banks would still provide settlement and liquidity. Wider access also brings more responsibility around operating controls, fraud and compliance, an issue we reviewed in payment network access and control.
BRICS is also examining connections between securities settlement and depositary systems. Technical discussions have looked at differences between member markets, while the proposed New Investment Platform remains under development. Compatible payment and securities systems could eventually reduce friction in both trade and investment flows.
Established global payment networks and correspondent banks aren't disappearing. They have deep liquidity, global reach and mature compliance systems. BRICS members are trying to create additional routes alongside them, which can increase bargaining power and give businesses more choices when tariffs, sanctions or geopolitical disputes interrupt established channels.
The commercial impact will become visible once transactions go live. A direct connection between two major systems can be measured through settlement time, FX cost and merchant adoption. Several working links could eventually create a meaningful network across BRICS economies.
BRICS doesn't need a common currency to change cross border finance. The bloc already represents nearly a quarter of global trade, and tariffs are giving members another reason to diversify payment and trading relationships. If national rails begin connecting at scale, fintechs, banks and merchants gain more ways to transact outside traditional correspondent routes. The proof will be lower costs, faster settlement and sustained transaction volume once those links go live.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 14, 2026 | NCFA Market Activity | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data

On September 14, 2026, Paris-baesed digital asset firm Kaiko raised US$110 million in a Series B extension led by S&P Global. RBC joined BNP Paribas, Nasdaq Ventures, Bpifrance, Broadridge, Coinbase Ventures, DRW Venture Capital, Canton Foundation, Stellar and Susquehanna Private Equity Investments. Existing shareholders Anthemis, Point Nine and Revaia also participated.
Kaiko plans to invest the capital in its market data business and services for onchain capital markets. Its coverage spans more than 150 exchanges and protocols, with data used for pricing, trading, valuation, risk, surveillance and benchmarks.
S&P Global, RBC, Nasdaq, BNP Paribas and Broadridge bring something beyond capital. They operate businesses that depend on reliable prices, benchmarks, market data and institutional distribution. Their investment gives Kaiko deeper relationships with firms that could also become customers, partners or distribution channels as tokenized securities and digital assets enter more institutional products.
S&P Global was already working with Kaiko before leading the round. On September 1, S&P Dow Jones Indices and Kaiko launched the S&P Kaiko Digital Asset Indices, bringing more than 4,000 rates and indices into one suite. Kaiko provides digital asset data, calculation and connectivity across more than 150 exchanges, while S&P DJI brings benchmark administration, licensing and global distribution.
The relationship also reaches tokenized traditional assets. Earlier work brought the iBoxx U.S. Treasuries Index onto the Canton Network, giving onchain applications access to an established fixed income benchmark. S&P is therefore investing in a company it already uses across digital asset pricing, benchmark production and onchain data delivery.
RBC's participation puts a major Canadian bank alongside global exchanges, banks, data firms and digital asset investors backing Kaiko's expansion.
A tokenized bond or fund still needs a defensible price. Banks and asset managers also need reference rates, liquidity data and valuations that can flow into trading, collateral, risk, reporting and settlement systems across digital asset markets. Those requirements become harder when assets trade across multiple exchanges, blockchains and around the clock.
Institutional adoption is already growing in tokenized collateral and cash markets, where pricing, valuation and settlement quality directly affect whether products can scale.
Kaiko provides market data feeds, analytics, indices, pricing and monitoring tools. Its onchain services can also deliver licensed data directly into blockchain applications. That gives the company exposure to several parts of the market without depending entirely on crypto trading volumes.
The investors will participate in a Strategic Industry Working Group chaired by Kaiko and focused on data for tokenized capital markets. Nothing formal has been disclosed yet but there will be lots at the table including banks, exchanges, financial data firms, blockchain networks and market technology providers with different requirements for pricing and using tokenized assets.
So what does this mean for traditional data companies? Building digital asset expertise internally takes time, specialist market knowledge and direct connections to fragmented venues. Investing in firms such as Kaiko can give established providers access to those capabilities while they contribute distribution, benchmark credibility and institutional clients.
Coin Metrics competes for institutional market, network and reference data. Lukka is strong in valuation, accounting and audit data. CoinDesk Data competes in digital asset benchmarks and market information. Bloomberg and LSEG have much larger enterprise distribution and can add digital asset products to platforms already embedded inside banks and investment firms.
Kaiko brings deep digital asset expertise in pricing, benchmarks and institutional data. S&P's investment can help Kaiko reach more financial institutions, but it also highlights the competition. Large data companies already have the customers, distribution and capital to partner with specialists, buy them or build similar capabilities themselves.
Kaiko will need more revenue from indices, tokenized assets and enterprise data if it wants to rely less on crypto trading activity. The working group only becomes strategically beneficial if it leads to products, common data practices or stronger links into existing financial systems.
S&P Global isn't just buying exposure to crypto growth. It is backing specialist data capability it already uses. If tokenized markets scale, reliable pricing and benchmarks may be one of the harder and more valuable pieces for financial institutions to recreate themselves.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 5, 2026 | Last Updated Sep 14, 2026 | NCFA Fintech Whisperer | Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization, Digital Identity And Trust, Cybersecurity Fraud And Financial Crime, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Artificial Intelligence And Data, Cross Border Payments And FX, Wealthtech Investing And Trading, Embedded Finance, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Risk Compliance And Regtech, Treasury Liquidity And Cash Management, Regulation And Policy, Data Privacy And Governance

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026).
Connecting an AI assistant to dozens of live systems gives it more operational authority than a standard support bot. Similar payment operations agents are already appearing elsewhere in India, making permissions, authentication and audit records increasingly important as AI reaches deeper into merchant finance.
Agentic commerce needs more than an AI model and a payment button. As agentic commerce expands, merchants need controlled ways to expose products, pricing and payment permissions across many agents without building a separate connection for each one.
AI is moving into the work that happens before a small business credit decision, including financial review, borrower interviews and due diligence. The growing use of agentic AI under regulatory scrutiny makes traceability and human responsibility increasingly important as lenders automate more of the assessment process.
Advisor AI is moving beyond notes and summaries into work that touches client records, KYC and planning systems. The deeper Focal AI analysis looks at where productivity gains meet consent, recordkeeping and advisor accountability as agents begin acting across regulated workflows.
Core providers are becoming a more explicit supervisory control point for community banks. Technology vendors need implementation quality, contract terms, operational controls and regulatory cooperation to withstand scrutiny because provider conduct can now feed directly into supervisory and enforcement decisions.
Chime is trying to own the regulated banking capacity behind a relationship it has spent years building through a partner. Its recent expansion into investing and workplace distribution shows why owning more of the banking economics underneath the account could become increasingly valuable if the acquisition closes.
The licence gives Unlimit another regulated access point for cross border payment distribution in Asia Pacific. For merchants and fintechs expanding regionally, the operating value comes from combining local payment channels with one provider rather than building separate regulated connections in each market.
Stablecoins still need banks and local payout rails at the edges of the transaction. The Tazapay deal shows Circle buying those connections rather than building each market one at a time, bringing more of the route between USDC and domestic payment systems inside the company.
Capital treatment determines how expensive it is for banks to hold or support crypto exposures. The final rules now become part of Canada's wider stablecoin and digital asset regulatory regime, giving institutions a firmer basis for deciding which activities are economically viable inside prudential capital and liquidity controls.
Switzerland is testing one digital franc instrument across banks, payments and capital markets rather than keeping each use case separate. It is still a sandbox, but bringing SIX and TWINT into the same test gives the work more weight. Commercial use will depend on what survives the tests and how participating institutions agree to use it.
Fuze now has a supervised operating position in another major financial centre. The Swiss entry gives institutional clients another provider for regulated crypto and stablecoin services while keeping settlement connected to established banking systems. The approval is financial intermediary status, not a Swiss banking licence.
AI agents cannot transact widely if every payment network identifies them differently. The work directly connects to the emerging questions around consent and liability in AI payments, where identity, authorization and responsibility need to travel with the agent across payment systems.
Digital identity now has a clearer route into everyday U.S. bank onboarding. Banks can use government issued mobile credentials without waiting for a new KYC rule, giving identity providers and financial institutions more room to replace document checks with verifiable digital credentials while keeping existing compliance responsibility intact.
The implementation shows what open banking looks like when standards become operating infrastructure inside bank technology. It also provides a useful comparator for Canada's Open Banking intelligence, where secure API access, consent controls and interoperability remain central implementation questions.
Digital wallets are becoming more useful when customers can take them beyond their home market. Mastercard is giving independent wallet providers common ways to reach contactless, QR and online acceptance without each provider building those connections alone. With multiple wallet operators already participating, Wallet Pay adds another route for local wallets to compete across borders.
Swift's ledger is gaining practical use across more banks, currencies and payment windows. Bringing Singapore's three domestic banks into live SGD transactions adds a local interbank use case to the cross border and weekend payments already completed. For banks and treasury teams, the value will depend on how routinely that shared capability can be used outside conventional processing hours.
A large regulated bank has connected a proprietary stablecoin to the control systems it already uses for real money movement. The important test now is whether USBDC progresses from an internal live transaction into recurring treasury, liquidity or client payment activity where 24/7 settlement changes how the bank manages value across borders.
PhonePe is pulling more card functions into the wallet interface, from contactless acceptance to international QR payments. That fits a wider pattern of payment networks opening access while retaining control over the rules, credentials and infrastructure underneath each transaction.
A regulated local stablecoin is now being tested through payment terminals merchants already use. That is the type of transition behind the question of whether stablecoins are becoming payment infrastructure: digital money entering ordinary merchant acceptance rather than remaining inside crypto trading venues.
Settlement requirements can keep smaller or lower rated institutions out of global card networks even when customer demand exists. IFC is using guarantees to absorb part of that risk, giving more banks and fintechs a practical route into international payment infrastructure without requiring the networks to carry the full exposure themselves.
Jaywan already had merchant acceptance in the UAE. The new evidence is distribution through Mastercard Gateway, which gives the domestic scheme a larger e-commerce route and makes it easier for merchants to support Jaywan alongside international cards through one setup.
UPI is extending beyond India by connecting familiar consumer payment apps directly into foreign merchant acceptance. The first Singapore deployment is already live, while the larger opportunity is distribution through FOMO Pay's merchant network without asking Indian users to change how they pay.
A wallet that works locally becomes much more useful when it can travel. TerraPay is connecting existing African wallet networks to a global merchant network without requiring each wallet provider to build separate acceptance relationships market by market. That gives local wallets a larger role in cross border commerce.
Stablecoin cards still need working capital behind the payment. Visa is using live settlement data to help lenders finance that gap and automate repayment from settlement flows. If the model spreads, onchain credit could become part of the everyday funding machinery behind card programs rather than a separate crypto lending market.
NymCard is assembling more of the regulated payments stack under one platform. Final approval would give banks and enterprises another infrastructure provider able to combine issuing, money movement, open finance and stored value services without splitting those functions across as many vendors.
Direct scheme access gives Viva.com more control over local payment acceptance than a standard processor integration. It also shows how a cross border bank can expand across Europe by connecting directly to domestic payment rails instead of treating the region as one uniform payments market.
Weekend settlement makes 24/7 tokenised deposits more useful for treasury, not just payments. Companies can move cash across entities and markets when they need it instead of waiting for banks in another time zone to reopen. The next test is whether this becomes a routine treasury service across more banks and currencies.
Mortgage lenders now have a firm implementation date for multiple credit scoring models inside FHA underwriting. That creates a delivery deadline for credit data, automated underwriting, lender workflows and model governance while reducing reliance on a single legacy scoring model.
Credit score competition is moving into mainstream mortgage origination rather than remaining a controlled rollout. Lenders can now choose VantageScore 4.0 across eligible Fannie and Freddie loans, putting more pressure on scoring providers, credit bureaus and underwriting systems to support multiple models at production scale.
Pye gives borrowers a way to compare lender access from one application while lenders compete inside the same digital distribution point. If adoption grows, the model could change who controls customer acquisition in retail credit, especially where merchants and software platforms embed borrowing directly into the purchase or service experience.
The fund connects tokenization with an existing financing problem rather than creating a digital asset in isolation. NCFA's tokenization analysis tracks the same transition from issuance experiments toward measurable financial products and operating infrastructure.
This is a material follow on to the Nasdaq and Payward relationship announced in March. NCFA’s xStocks analysis tracks how Payward has been building distribution, brokerage connections and tokenized equity infrastructure. Nasdaq is now adding capital and surveillance technology to that relationship.
Stablecoin capital is entering private credit at institutional scale. StableFund also connects two markets NCFA has been tracking separately: private credit and digital money. The practical test is whether stablecoin settlement changes funding speed, administration or access once the capital is deployed.
Canada's scaleup financing gap is attracting direct balance sheet attention from its largest financial institutions. RBC is pairing growth capital with banking, market access and commercial relationships, which could give later stage Canadian companies another option when large domestic lead investors are difficult to find.
India has now put tokenized securities and central bank digital money into the same corporate bond process. Same day issuance and settlement gives regulators and market operators concrete evidence to compare against conventional workflows, including whether tokenization can cut settlement risk and operating work without weakening existing investor protections.
Underwriting AI is moving into the point of sale rather than operating only behind insurer workflows. Faster preliminary guidance can help advisors set expectations before submitting a case, while final underwriting authority remains with the insurer. That makes accuracy, explainability and escalation controls central to whether the service improves conversion without adding risk.
This is production adoption rather than an AI demonstration. The design follows the control pattern NCFA examined when AI agents entered governed workflows: defined policies, traceable recommendations, approval gates and human accountability around financial actions.
Wealth AI is starting to operate between systems and meetings rather than waiting inside a chat window. Canada's OneVest AI platform shows a similar direction as wealth technology moves from analysis toward continuous workflow automation.
The transaction combines two large technology layers used behind advisor and wealth firms. It also builds on Envestnet's Canadian wealthtech expansion, adding more trading, tax and portfolio infrastructure underneath advisor workflows.
Zero commission trading has reached a major Canadian bank owned brokerage. Wealthsimple had already put pressure on brokerage pricing, and BMO's response now tests how quickly the country's other large bank brokerages follow.
Savvy is pairing a large financing round with measurable advisor and revenue growth, giving investors another data point on how quickly technology led wealth platforms can scale. The capital also raises competitive pressure on traditional advisor firms as independent teams gain more software, operations and growth support from integrated platforms.
Institutional portfolio technology is moving directly into private banking advice. Danske is giving advisors and clients more continuous analysis rather than relying only on periodic portfolio reviews, raising the competitive bar for digital advice, portfolio monitoring and the technology behind affluent wealth relationships.
Embedded finance becomes more useful when a software company can add regulated money functions without building each component itself. Potje gives Quantoz a live reference customer for that model, connecting accounts, payments and compliance behind one product while the regulated provider handles the financial infrastructure.
Canada’s instant-payment build is now reaching the fraud layer inside financial institutions that support fintech distribution. This RTR intelligence guide tracks the fraud, access and operating requirements firms face as settlement becomes continuous and final. Peoples Group is putting those controls into production before launch.
The size of the activity gives banks and fintech fraud teams a useful view of where financial crime controls are being tested. Health care fraud can pass through ordinary deposit accounts and payment flows, putting more pressure on transaction monitoring, entity screening and the kind of counterparty checks that become critical when formal registration alone does not tell the full story.
A reserve system can fail even when the obvious signing key is still intact. NCFA's technical review of the Liquid incident examines why bridge software, federation controls and reserve monitoring matter when the backing asset can leave without the expected key being stolen.
Bank fintech relationships could face a more risk based supervisory model instead of uniform vendor controls. Fintechs selling into regulated institutions should expect due diligence, contracts, monitoring and evidence requirements to track more closely with the financial, compliance and operational risks of the service they provide.
The bulletin adds another source of intelligence to sanctions and AML enforcement beyond bank reporting alone. For financial institutions and fintechs, it increases the value of defensible ownership, counterparty and transaction records when activity crosses jurisdictions or involves higher risk intermediaries.
Compliance AI becomes more useful when it can reconstruct an entire customer experience rather than score individual conversations in isolation. NCFA's question on whether AI creates new compliance burden is directly relevant as firms automate more monitoring while remaining responsible for evidence, review and escalation.
The rule reduces routine examination frequency for a larger group of qualifying community and smaller banks without changing their underlying supervisory obligations. For fintech partners, the practical effect may appear in bank compliance capacity, vendor reviews and the amount of supervisory work institutions need to manage between examinations.
Bank capital rules affect how much balance sheet capacity is available for lending, investment and new financial products. The 2027 changes could make some business lending more economical at a time when Canada's business funding mix remains heavily dependent on banks and public markets.
This raises the operating bar for vendor due diligence in Canada. Privacy compliance is no longer just about a company’s own controls. It also turns on how well the business assesses processors, cloud providers, AI vendors and other external partners before data is shared. That has direct implications for fintech partnerships, outsourcing and open banking style data flows, where third party access and accountability remain central issues. See OPC's five open banking fixes.
Another week of market proof that financial infrastructure is becoming more programmable, automated and tightly controlled at the same time. Banks, fintechs and market operators are putting AI, tokenized assets, real time payments and digital identity into production while regulators tighten expectations around access, capital, fraud and accountability. Which leading firms can connect new capabilities to regulated infrastructure without losing control of risk, economics or the customer relationship?
Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 11, 2026 | NCFA Resource | Open Banking And Consumer Driven Finance, Artificial Intelligence And Data, Competition And Market Structure
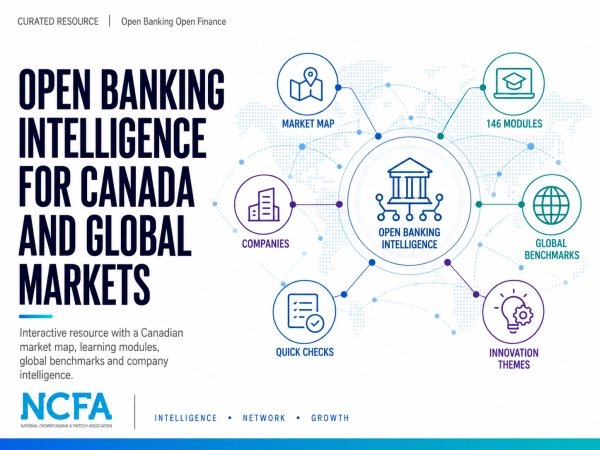
Understanding Open Banking and Consumer Driven Finance means keeping several things in view at once. Canada has proposed regulations and an implementation program underway, other markets already have years of operating experience, and fintechs are testing products around financial data, identity, credit, payments and decisioning.
The NCFA Open Banking & Consumer-Driven Finance Interactive Intelligence resource brings that material into one interactive environment. It is Canada-led, with international examples and global benchmarks where they help explain market structure, implementation choices and commercial activity.
Readers can learn through a Canadian Open Banking Market Map, 146 learning modules, company intelligence, discussions, innovation themes, global benchmarks or Quick Checks (there's even an NCFA arcade perk for completing modules). There is no required starting point.
The Canadian Open Banking Market Map shows who is participating and where different capabilities fit, helping readers identify competitors, infrastructure providers, potential partners and areas of market activity.
The 146 learning modules break Open Banking and Consumer Driven Finance into smaller topics that can be explored individually or in sequence. Quick Checks let readers test what they understand before continuing, making it easier to get current on a specific issue without working through a long report.
Company intelligence connects firms to market categories, technologies and use cases, while discussions and innovation themes explore where new capabilities are developing and where parts of the ecosystem may already be crowded.
Global benchmarks put Canadian developments in perspective. Australia, the UK, Europe and other jurisdictions have tested different approaches to data access, consumer consent, accreditation, payments and competition. Their experience cannot be copied directly into Canada, but it gives Canadian teams evidence to compare against emerging policy and market choices.
Canada’s detailed operating requirements are still being finalized. Worth nothing that NCFA also offers a separate Open Banking Regulatory Intelligence Guide, a dedicated resource for proposed regulations, implementation requirements and regulatory readiness.
Founders and product teams can see where a product fits before committing time and capital, while banks and credit unions can use the same market view across strategy, product and innovation teams. Investors can trace a market theme into the companies working on it and compare the opportunity with evidence from operating jurisdictions.
Policymakers, advisers and industry organizations can examine what happened after policy choices reached the market without assuming another country’s model belongs in Canada. The practical question is what worked, what did not and which lessons are relevant here.
NCFA’s separate Open Banking In Canada Opportunity Brief goes deeper on commercialization, evidence and product opportunities. Interactive Intelligence is broader, giving readers the market and international context before they narrow in on a specific commercial thesis.
The main strength is a one stop destination to research and learn about Open Banking. They can start with a company, market category, learning topic, international example or innovation question and follow the connections that are relevant to their work. Further, the page will be refreshed periodically to capture key updates and changes.
Data-sharing requirements affect product design, new technical capabilities can create commercial opportunities, and evidence from other markets can challenge assumptions about adoption or competition.
Open Banking Decision Intelligence analysis takes that thinking further by examining what firms can do with permissioned financial data, including credit, fraud detection and financial guidance.
There are limits. Canada’s proposed Consumer Driven Banking Regulations may still change, international examples operate under different legal and competitive conditions, and company intelligence dates quickly in an active market. The resource is designed to be revisited as the market develops and should not replace legal advice, due diligence or primary regulatory sources.
Canada Open Banking And Consumer Driven Banking Rules (proposed Canadian requirements, implementation and regulatory intelligence)
How Canada Started Opening Its Financial Infrastructure (payments, data access and financial infrastructure context)
Canada’s Open Banking Strategy Starts With Trust (consent, fraud, liability and consumer protection)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 11, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Wealthtech Investing And Trading, Risk Compliance And Regtech
On September 10, 2026, OpenAI launched ChatGPT for Financial Services, a version of ChatGPT Work built for finance around GPT-6 Astra, premium financial data, connected firm information and tools for research, modelling and client materials. OpenAI developed the product with Morgan Stanley and Evercore as design partners, starting with investment banking and equity research.
A financial institution no longer has to start with a general AI model and then separately connect every data source, build research workflows and figure out how the output gets into a valuation model, research note or pitchbook. Some of that assembly work now comes inside the product.
That positions ChatGPT closer to the type of work bankers and analysts produce every day. It also puts OpenAI into more direct competition with fintech copilots, research platforms and financial software vendors building similar workflows around third party AI models.
ChatGPT for Financial Services includes premium datasets from providers such as Daloopa, PitchBook and LSEG News. OpenAI says the available data covers areas including earnings transcripts, financial statements, company fundamentals and private companies. Teams can start using supported datasets that are included without negotiating separate contracts or configuring their own connectors.
The scope still depends on the provider and dataset. PitchBook says users get access to its expanded Essential dataset, including firmographic information on companies, investors and funds. OpenAI's terms also set rules for each provider around timing, storage, copying and reuse.
OpenAI indexes and hosts supported partner data on its own infrastructure so the system can retrieve it faster and attach citations to figures and claims. In finance, analysts need to know where their numbers came from, which period it covers and whether the source supports the conclusion.
There are real limits. OpenAI's Financial Services Terms say data and outputs may be inaccurate, incomplete, delayed or outdated. Daloopa data listed in the terms is delayed by 24 hours, while Nasdaq pricing supplied through Financial Modeling Prep is delayed by at least 15 minutes. Those details become important when the same system is used for research, valuation work and client materials.
For financial data companies, ChatGPT can become another route to institutional users. OpenAI gets licensed data closer to the research workflow, while the provider keeps control over how its underlying information can be copied, exported or reused.
OpenAI is also going after the work produced after the research. Administrators can publish approved Excel, Word and PowerPoint templates so teams can turn analysis into valuation models, research notes, pitchbooks and other documents in the firm's own format and style.
Investment banking and research teams spend a lot of time getting numbers, commentary and analysis into the right spreadsheet, memo or presentation. If AI can produce that work using approved templates, companies can cut production time without rebuilding the workflow around a separate tool. Morgan Stanley and Evercore helped OpenAI identify those pain points. OpenAI says reliable data access and high quality artifact creation were among the biggest problems raised through the design work. The announcement doesn't say either firm has deployed ChatGPT for Financial Services across its entire organization at this point.
Fintech copilot models that mainly wrap a large language model around research or document creation now face tougher competition. Specialists still have room where they own proprietary data, regulated workflows, execution capability, integrations built for individual institutions or financial expertise that a general platform can't easily reproduce. NCFA recently looked at decision intelligence in financial services which highlights a similar competitive issue. Access to data matters, but the firms creating the most value will be the ones that turn it into better research, decisions and client outcomes.
ChatGPT for Financial Services includes enterprise controls such as SAML SSO, SCIM provisioning and access controls by role. OpenAI says business data is not used to train its models by default, data is encrypted at rest and in transit, administrators can configure workspace retention, and supported workspace logs can be exported through its Compliance Platform.
Those controls help firms manage who gets access and what information can be used. They don't make a bank, dealer, investment firm or advisor compliant by themselves. Each institution still has its own obligations around privacy, records, supervision, model risk, client information and material information that isn't public.
Its Financial Services Terms say the service provides information and tools for financial research and analysis and that OpenAI does not provide financial or investment advice. Users are told to apply independent professional judgment and check important sources, dates and calculations before relying on the output.
That keeps responsibility with the institution. Citations can make research easier to check and firm templates can make the output easier to use, but someone still has to stand behind the analysis, recommendation or client communication.
OpenAI is making general finance copilots easier to copy and harder to defend. Fintechs will need an edge in proprietary data, regulated execution, deep workflow integration or trusted financial expertise to compete.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
