





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 18, 2026 | NCFA Insight | Digital Assets And Tokenization
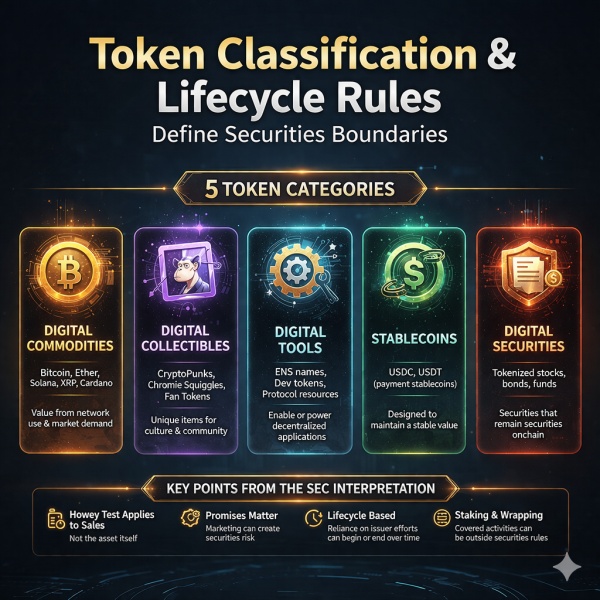
On Mar 17, 2026, the U.S. Securities and Exchange Commission issued a formal interpretation on how federal securities laws apply to certain crypto assets and certain crypto asset transactions with aligned support from the CFTC read the SEC’s March 17 press release on the joint crypto interpretation (and Fact Sheet).
This is a significant U.S. digital asset policy interpretation because it gives the market something it's lacked for a long time: a public classification system, a public lifecycle test, and public treatment of core activities such as staking, wrapping, and airdrops.
The old question of 'is it a security?' no longer sits only at the token level.
The SEC now says the answer can depend on the category of asset, the way it is sold, the promises around it, and whether those promises still matter later in the market.
The release classifies crypto assets into five categories based on characteristics, uses, and functions: (1) digital commodities, (2) digital collectibles, (3) digital tools, (4) stablecoins, and (5) digital securities. It's a framework that crypto firms can actually use in product design, listing review, and compliance planning.
Some of the examples are worth noting. In the published interpretation, the SEC lists Aptos, Avalanche, Bitcoin, Bitcoin Cash, Cardano, Chainlink, Dogecoin, Ether, Hedera, Litecoin, Polkadot, Shiba Inu, Solana, Stellar, Tezos, and XRP as examples of digital commodities. It says these assets gain value from how the network operates and from market supply and demand, not from a team whose efforts drive profit expectations.
On collectibles, it points to CryptoPunks, Chromie Squiggles, Fan Tokens, WIF, and VCOIN.
On tools, it cites Ethereum Name Service domain names and CoinDesk’s Microcosms NFT Consensus Ticket.
The point is not that every asset that looks similar gets a free pass, and the SEC is now saying publicly that many crypto assets are not securities in themselves.
The SEC separates the token from how it is sold. It applies the Howey test to the transaction, not just the asset. A token that is not a security can still be sold as part of an investment contract if a team’s promises create an expectation of profit.
The interpretation then separates the asset from the contract and explains how that link can end. A non security token is no longer subject to an investment contract once buyers no longer rely on the issuer’s promises.
This can happen in two ways. The issuer fulfills what it said it would build, such as delivering functionality or completing roadmap milestones. Or the issuer abandons those efforts, making it unreasonable for the market to keep relying on them. In both cases, the investment contract can fall away, even though the issuer may still face anti fraud liability for earlier statements.
This directly addresses the secondary market problem. A token’s status in later trading does not depend only on how it was launched. It also depends on whether buyers still rely on the issuer’s promises at that point in time.
The SEC ties securities treatment directly to what issuers say. Statements in agreements, websites, whitepapers, and social media can create a reasonable expectation of profit.
That risk increases when issuers make explicit promises tied to roadmaps, milestones, funding plans, and how their work will drive value.
Token design and marketing cannot be separated. If the sales narrative links price appreciation to team execution, the offering can be treated as an investment contract.
For founders and counsel, that is the message. Product design, legal design, and communications design now need to be built together from day one.
The SEC says covered protocol staking activities don't involve securities transactions when structured as described. It covers self staking, custodial and non custodial staking, delegated and nominated staking, and liquid staking.
The interpretation is that rewards and penalties come from protocol rules, not from a team managing profits. That includes liquid staking models where users receive tokens tied to their staked position. If returns come from how the network operates, not from a promoter’s decisions, the activity is less likely to be treated as a securities transaction. That gives exchanges, custodians, and staking providers clearer ground for product design.
The SEC also says wrapping a non security crypto asset doesn't create a security when the wrapped token is redeemable one for one, the underlying asset stays locked for the holder, and value comes from that underlying asset. This supports cross chain use, custody design, and token mobility.
It also confirms that certain airdrops do not involve an investment of money under the Howey Test when recipients do not give anything in return. Common uses include rewarding early users, supporting governance, and building network participation. This does not make all airdrops safe, but it gives builders a clearer framework to separate distribution from securities risk.
The SEC aligns its position on stablecoins with the GENIUS Act. It says qualifying payment stablecoins issued by permitted issuers will not be securities once the law is in force. It also states that some covered stablecoins already fall outside securities treatment under its interpretation. This gives issuers and institutions clearer direction on how stablecoins are treated at the federal level.
Tokenized securities get a clear boundary. A security remains a security whether it is issued offchain or onchain. The SEC describes both issuer led tokenization and third party tokenization of existing assets. In both cases, moving an asset onchain may improve issuance and settlement, but it does not change its legal status.
This interpretation affects different parts of the market in different ways.
This interpretation shows what a more usable framework looks like in practice. While it doesn't solve every unanswered question, it's helpful and moves the debate from slogans to structure. Markets develop faster when participants can classify assets, model lifecycle risk, and design products in lie with public rules instead of trying to read the regulator’s mind from old enforcement cases.
The SEC doesn't replace the Howey Test but it makes Howey more operational for crypto markets. That's the real change. The release gives the industry a public map for classification, a public test for when securities treatment begins and ends, and public treatment of activities that sit at the center of token network design. If you're looking for more of a legal analysis here.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply