





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 15, 2026 | NCFA Market Activity | Digital Banking And BaaS, Cross Border Payments And FX, Competition And Market Structure
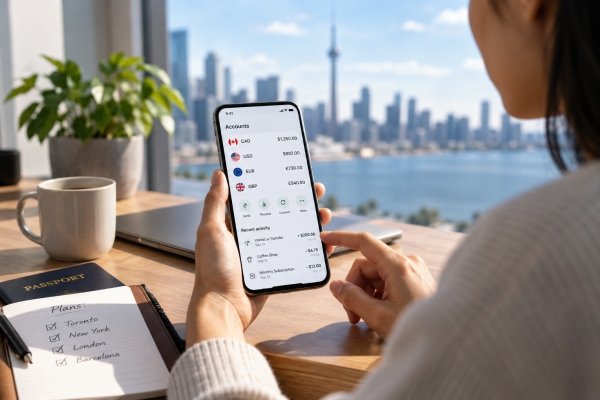
On September 14, 2026, UK-based global payments company Wise launched a Chequing Account in Canada with no monthly fee, Interac e-Transfer support, Canadian account details, pre-authorized debits, debit-card access and multi-currency features. The launch takes Wise further into everyday Canadian financial activity while keeping the cross-border tools that built its original customer base.
The account is available to personal and business customers in Canada. Customers can hold more than 40 currencies, receive money using account details available across 22 currencies and send money to more than 70 countries. Wise converts currencies at the mid-market rate and charges a separate conversion fee that currently starts from 0.19%, depending on the currency and transaction.
Canadian customers can send up to C$25,000 to a supported Interac email address and receive up to C$25,000 per day through Interac Autodeposit. Wise doesn't charge its own fee to receive Autodeposit payments, and the September launch removed the Wise fee for sending CAD to an Interac alias and adding CAD through Interac. Incoming transfers that require a security question and manual acceptance aren't currently supported, and an email registered for Wise Autodeposit can't remain registered for Autodeposit at another financial institution.
Wise also provides Canadian institution, transit and account numbers for electronic deposits and withdrawals. Customers can receive pay, set up pre-authorized debits for recurring bills, spend through a physical or digital debit card and withdraw cash at ATMs. Wise currently charges no withdrawal fee on the first C$100 each month, then C$2.69 plus 2.69% on the amount above C$100, while an ATM operator can charge its own fee.
Group Spend lets customers create a shared balance for expenses such as household bills or trips. Wise's international features are still a key difference. Customers can hold CAD and dozens of other currencies in one account, convert between them and receive money using account details available in 22 currencies.
Wise Payments Canada Inc. is not a Canadian bank. It is registered with the Financial Transactions and Reports Analysis Centre of Canada as a Money Services Business under registration M15193392 and with the Bank of Canada as a payment service provider under the Retail Payment Activities Act. It also holds a Quebec money services business licence.
Wise keeps customer funds separate from its operating money under Canada's payment-safeguarding rules. For its Chequing Account, Wise says eligible deposits are held in trust at a Canada Deposit Insurance Corporation member institution with customers identified as beneficiaries. Eligible deposits can receive CDIC protection of up to the equivalent of C$100,000 per beneficiary if the member institution fails and the trust-disclosure requirements are satisfied; Wise itself is not a CDIC member.
Foreign-currency balances aren't automatically excluded because CDIC can cover eligible deposits in Canadian or foreign currency. Coverage still depends on the deposit meeting CDIC rules, and balances held for the same customer at the same member institution can be combined when insurance limits are calculated.
Wise also became a Payments Canada member in January 2026 after federal rule changes opened membership to regulated payment service providers. That gives Wise a formal role inside Canada's payments system and makes eligible PSP members able to seek participation in payment systems under the applicable rules. Membership doesn't automatically give Wise direct access to every Canadian payment rail.
Canadian consumers can already choose among traditional banks, digital banks and fintech accounts that cover much of the same daily activity. Wise competes with domestic payment functions and a deep multi-currency product, while using a regulated non-bank structure for the account itself.
Big Six banks: Traditional banks still combine chequing with lending, credit, branches, drafts and direct deposit-taking. RBC Day to Day Banking, for example, has a standard C$4 monthly fee and includes 12 debit transactions plus unlimited Interac e-Transfers. Wise removes the monthly fee and adds much deeper multi-currency functionality, but it doesn't replace the full range of services available through a bank.
Wealthsimple: Wealthsimple has expanded deeper into everyday banking with chequing, payments, direct deposit, cards and other daily money tools. Customer cash is held in trust with CDIC member institutions rather than by Wealthsimple as a bank. Wise has the stronger cross-border proposition through currency holding, foreign account details and international transfers.
KOHO: KOHO combines prepaid-card spending, Interac transfers, Autodeposit and bill payments, with customer funds held through a trust structure designed to qualify for CDIC protection. Its product is centred more heavily on Canadian spending, credit building, rewards and budgeting, while Wise puts international money management at the centre of the account.
EQ Bank: EQ Bank's Personal Account also has no monthly fee and includes unlimited Interac e-Transfers, bill payments, direct deposit and card access. The legal model is different because EQ Bank is a trade name of Equitable Bank, a federally regulated bank and CDIC member that accepts deposits directly. EQ already uses Wise for international transfers, making it both a competitor in everyday banking and a distribution partner for Wise's cross-border capability.
Neo Financial: Neo gained direct Interac e-Transfer access in April 2026 and offers digital chequing functions including Interac transfers, bill payments, pre-authorized debits and card spending. Its focus is more Canadian spending, credit and rewards, while Wise brings a much deeper international money layer.
Wise now covers many of the tasks that keep a chequing account central to a customer's financial life, while adding something most Canadian chequing products don't offer at the same depth: one account built around both domestic use and frequent cross-border money movement.
Canada's regulatory changes give non-bank providers more room to compete for that relationship. RPAA supervision applies operational-risk and safeguarding requirements to payment service providers, while Payments Canada membership brings qualifying fintechs closer to national payment systems. Consumer-driven banking could extend that competition further if customers gain easier ways to connect financial data and services across institutions.
Wise is also giving the launch a physical presence through a temporary pop-up at Toronto Eaton Centre on Level 1 from September 14 through October 11. Customers can register, get product help and participate in launch promotions there, but the location is a Wise promotional and service activation rather than a Canadian bank branch.
Wise can now handle many of the transactions Canadians associate with a primary chequing account while remaining a regulated non-bank provider. How much of the everyday banking relationship can fintechs win before customers care less about whether their main account comes from a bank?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply