

Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Oct 31, 2026 | Last Updated: Nov 6, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Digital Identity And Trust, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading

Image: Freepik
NCFA Fintech Whisperer tracks weekly fintech market intelligence that changes how financial markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins.
Missed a prior week's Fintech Whisperer? Browse December 6 to 12, 2025, December 13 to 19, 2025, January 1 to 9, 2026, January 10 to 16, 2026, January 17 to 23, 2026, January 24 to 30, 2026, January 31 to February 6, 2026, February 7 to 13, 2026, February 14 to 20, 2026, February 21 to 27, 2026, February 28 to March 6, 2026, March 7 to March 13, 2026, March 14 to March 20, 2026, March 21 to March 27, 2026, March 28 to April 3, 2026, April 4 to 10, 2026, April 11 to 17, 2026, April 18 to 24, 2026, April 25 to May 1, 2026, May 2 to 8, 2026, May 9 to 15, 2026, May 16 to 22, 2026, May 23 to 29, 2026, May 30 to June 5, 2026, June 6 to June 12, 2026, June 13 to June 19, 2026, June 20 to June 26, 2026, June 27 to July 3, 2026, July 4 to July 10, 2026, July 11 to July 17, 2026, July 18 to July 24, 2026, July 25 to July 31, 2026, August 1 to August 7, 2026, August 8 to August 14, 2026, August 15 to August 21, 2026, August 22 to August 28, 2026, August 29 to September 4, 2026, September 5 to September 11, 2026, September 12 to September 18, 2026, September 19 to September 25, 2026, September 26 to October 2, 2026, October 3 to October 9, 2026, October 10 to October 16, 2026, October 17 to October 23, 2026, October 24-October 30, 2026.
Penny brings the practical test of financial AI into everyday accounts. Can a client see exactly what an agent plans to do before approving it? Wealthsimple is keeping confirmation in the transaction path, a useful response to AI agent authorization risks. Banks and fintechs competing here will need reliable permissions and clear records, not just a better chat interface.
Singapore wants financial firms to solve common AI deployment problems together instead of rebuilding every control separately. Vendors should watch the tools that emerge from BuildFin.ai and SafeFin.ai. Shared practices can make procurement easier, but they can also raise the minimum standard for selling AI into banks.
Project SAGE moves the agentic finance debate toward the control layer that determines whether financial agents can be trusted to act. Identity alone is not enough. Firms need to prove who delegated authority, what the agent can do and how that authority is revoked. Those questions sit at the centre of AI agent financial authorization and security.
Firms building AI tools for customer decisions will get a direct route to test designs with the regulator. That matters more than another broad statement on responsible AI. Applicants should arrive with specific decision flows, customer safeguards and evidence they can evaluate during the program.
For Canadian founders and early investors, exit taxation affects where companies are built and where proceeds get invested next. The proposed relief could make staying in Canada more attractive when a venture succeeds. But the eligibility rules will decide who actually benefits, especially founders, employees with equity and angels backing smaller deals. Until enacted, founders shouldn't price the proposed exemption into a transaction.
BitGo can now sell custody and financing together rather than leave institutions to connect several providers. That makes collateral eligibility, liquidation terms and counterparty exposure central buying decisions. Clients comparing BitGo's institutional custody services with its new trading desk should press for actual funding costs and settlement performance. The launch alone doesn't establish market share.
US exchanges now have a route to list equity perpetual futures within registered markets. Brokers can assess a product category many traders currently find offshore. But the business case depends on actual contracts, margins, clearing arrangements and liquidity. No exchange volume was announced, so this is a permission milestone rather than evidence of trading demand.
Tokenized public equities need more than trading and settlement. They also need reliable ownership records, corporate actions and voting rights. Broadridge is building those functions into the NYSE model before launch, extending the tokenized securities infrastructure layer already forming around regulated markets. Regulatory approval and issuer participation are the next proof points.
Financial institutions increasingly face a cost for every separate ledger connection. Consensys is selling a way to coordinate transactions while institutions keep control of their own networks. Buyers will need to test settlement finality, exception handling and integration cost before treating interoperability as solved.
The approved connection could let investors reach the digital gilt through two depositories instead of one. That gives banks and custodians a real interoperability problem to solve before issuance. They’ll need to test ownership records, settlement finality and investor access. A successful pilot could establish a useful model for digital government bond distribution, but no gilt has been issued yet.
A shared clearing house could give tokenized instruments access to familiar margin and default processes. That may be cheaper than running separate clearing arrangements. Members should test legal finality, collateral treatment and what happens when a digital transaction fails. Eurex has announced the design; live eligible products and actual clearing volumes remain the proof.
The proposed listing could give tZERO capital and a public market valuation for its regulated tokenization business. But the amount available depends on redemptions, financing and closing conditions. Investors should track cash actually delivered and trading activity across its platforms. **A signed SPAC deal is not a completed funding round.**
For active traders, a small fee change can matter across millions of shares. Dealers should model the cap alongside spreads and rebates, then confirm which provincial relief orders apply before changing routing. The November implementation brings the fee cap into actual execution costs for affected markets.
This expands BMO’s ability to connect Australian mining issuers with global institutional capital and advisory services. For smaller market participants, it raises the competitive standard for research, placement reach and cross border execution. The integration matters more than the acquisition headline.
Banks using Aquila could add currency coverage without building a separate payment connection for every corridor. That's commercially useful only if rates, compliance checks and failed payment handling work inside normal operations. Firms evaluating bank and cross border payment connections should compare actual execution costs and settlement times rather than count currencies on a slide.
A gift card seller has to keep suppliers funded even when customers pay in crypto and its suppliers expect local cash. Bitrefill is using stablecoins behind the scenes, not asking suppliers to change what they accept. That puts live evidence behind the cross border stablecoin supplier payments opportunity. The financial test is conversion cost, available liquidity and reliable delivery across more corridors.
Payment providers often need one bank for currency accounts and another provider for digital assets. RTGS.global is reducing that integration burden for eligible firms, although bank onboarding and market coverage still apply. Its value will depend on account approval, funding speed and costs across the banking and digital asset payment connections customers actually use.
The licence gives Razorpay a regulated route for cross border payment products and a clearer sales pitch to global platforms. Firms evaluating the service should check permitted flows, payout corridors, bank coverage and actual onboarding time rather than treating the licence as proof that every corridor is live.
The higher ceiling moves this rail beyond smaller remittance tickets and gives payment providers more room to serve larger consumer transfers without splitting them across transactions. The competitive question is whether instant card payouts can win volume from bank based cross border flows on cost, reliability and reach as cross border payment infrastructure becomes faster and more programmable.
Cross border QR acceptance could give Hong Kong bank and wallet users more ways to pay abroad without using a separate travel wallet. Providers should watch fees, currency conversion and participating banks. Merchant reach alone does not establish how much of that network a customer can actually use.
Texas adds another state where Navro can offer regulated payment services directly under its own permission. That makes licensing a sales advantage for firms managing payroll and international disbursements. Clients still need to check other state permissions, supported payout routes and bank arrangements. **One API does not mean one licence covers the entire US.**
The FCA is offering firms a route to test whether quantum systems outperform established financial crime tools before committing to expensive infrastructure. Interested compliance vendors need measurable detection questions and credible comparison data. This complements the earlier financial sector quantum readiness work, but the immediate opportunity is experimentation, not a production procurement mandate.
This is a bank payment authorization problem with a third party entry point. Payment firms can't judge resilience only by whether customer accounts were compromised. They also need controls over vendor permissions, treasury transactions and emergency transfer suspension. The cost becomes immediate when legitimate customer payments stop while the bank investigates. Arkéa's precise financial loss remains unconfirmed.
The business case for fraud AI is investigator time and better decisions, not simply faster generated explanations. Mashreq’s deployment puts those claims inside a bank control environment. Buyers should ask for measured investigation throughput, detection quality and evidence trails before extending automation.
This is a procurement and migration issue for banks long before quantum attacks become routine. Firms need to identify where vulnerable cryptography protects customer data, transactions and long lived records. Vendor contracts and implementation roadmaps are where the work becomes expensive.
A fraud report is more useful when it leads to a blocked account, disabled number or removed website. Maple Disruption brings the organizations controlling those channels into the same operation. Banks and fintechs should examine how quickly shared fraud intelligence reaches the team that can act. The real test is disruption achieved, not the number of participants.
BVNK gives payment providers a working route from dollars to stablecoin balances and back. It's useful for firms that need treasury and customer payouts without building four blockchain integrations themselves. The buying decision still comes down to liquidity, redemption and compliance costs. Those are the same operating constraints in NCFA's programmable stablecoin payments research.
Banks could still distribute digital money, but issuing it would require a different legal structure. That matters for licensing, reserves and who carries redemption obligations. Canadian wallets and PSPs also need clear treatment of foreign issuers, not just domestic products. NCFA's stablecoin regulatory guide tracks the existing framework while Ottawa works through the proposed amendments.
Institutional traders want exchange liquidity without giving one exchange control of their entire asset pool. Bitget is separating those functions, but clients still need to review collateral rights, liquidation instructions and settlement responsibility. The distinction matters alongside NCFA's crypto custody and exchange trust research. Keeping assets elsewhere is useful only when the legal and operational controls hold under stress.
The important step is that a major bank can send assets into custody and retrieve them through an operating connection. That is more useful than another memorandum of understanding. Institutions assessing regulated digital asset custody infrastructure will still want evidence of withdrawal reliability, segregation and collateral enforceability before expanding lending against these assets.
Restoring the reserve closes one immediate solvency gap, but it does not restore every withdrawal route. Users and trading firms still need to check liquidity, redemption channels and governance controls. The unresolved commercial issue is how a federated bitcoin product earns back confidence after a reserve failure.
Always available tokenized assets need an equally available cash leg. Hong Kong has connected both sides inside a regulated pilot, which makes settlement hours less of a constraint on treasury and tokenized fund activity. The commercial test is volume, participant growth and movement from pilot access toward production use in tokenized collateral and cash settlement.
Ireland is giving tokenization firms a more direct route into regulatory engagement while the supporting settlement and legal framework is still being built. That can surface custody, asset servicing and interoperability issues before firms scale them. The opportunity is shifting from issuance toward the regulated infrastructure around tokenized real world assets.
Tokenization firms need ways to reach regulated bank partners before they can prove demand. tConnect creates another entry point to test that fit. The useful measure will be projects that progress from collaboration into funded deployments, not how many firms attend.
The pause is a direct operating interruption for traders and liquidity providers relying on cross chain swaps. Those users need current chain status, outbound queue visibility and clear incident reports. An unexplained refund error also raises questions about how the protocol handles exceptional transactions under load.
Higher deposit protection could make customers more comfortable keeping larger balances at smaller federally insured banks. That affects a bank's funding cost and its ability to compete for savings. The proposed changes could help challengers, but firms must explain the current coverage accurately until Parliament changes the law. Smaller banks may benefit most if stronger insurance coverage helps them compete for deposits.
Getting a banking licence is expensive before the first account opens. A clearer decision period could make financing a challenger bank more realistic, while the ownership changes may let growing banks retain strategic investors longer. The details matter. Canada's Budget 2026 financial competition analysis sets out the wider context, but applicants still need to meet prudential standards.
Revolut can now compete on deposits rather than relying only on its existing account and payment products. For incumbent banks, the pressure is immediate on savings pricing and mobile acquisition. For digital challengers, the licence shows how costly and valuable direct deposit capacity can be.
Thailand’s virtual bank contest is turning into a distribution and core technology test. CLICX brings banking, mobile and physical retail reach together, but readiness alone does not establish account growth. The first customer offers and their economics will tell competitors whether that combination works.
Buying a bank can give a lending platform more direct control of funding and products, but the approval process can disrupt the whole plan. OppFi’s withdrawal puts a price on regulatory uncertainty. Other fintech acquirers need credible alternatives while approval remains unresolved.
Banks now face a larger identity vendor combining onboarding, biometrics and fraud controls. That may reduce integration work, but a bigger provider can also command more pricing power. Buyers should compare approval accuracy, portability and contract terms before consolidating suppliers. The projected 200 million checks are useful scale context, not proof that the merger has improved results.
Amdocs has bought its way into the systems insurers use to administer policies, bill customers and settle claims. For EIS clients, the first questions are service continuity and integration cost. For competing vendors, the threat is a supplier that can combine core software with enterprise AI services. Actual insurer deployments will determine whether that combination pays off.
Data centre builders need insurance that spans power, construction, equipment and cyber exposures rather than isolated policies. Pooling underwriting capacity could make larger projects easier to finance, especially as AI raises infrastructure demand. The test is whether the facility offers useful terms and capacity once it opens.
Motor finance lenders can settle some claims before the wider redress process ends, but an early offer has to stand up to scrutiny. A poorly explained calculation can create another dispute. Firms should keep a clear record of the amount offered, the customer’s options and the effect on any open complaint. Faster resolution only helps when customers can understand the terms.
Accreditation is moving from legislation toward the application work firms must actually complete. Fintech applicants should test the proposed evidence requirements against their operating models now. The deadline is a chance to resolve costly ambiguity before onboarding and compliance processes become fixed.
The date finally gives payment teams a launch milestone they can plan around. For merchants and treasury operators, the value comes when their providers actually enable funds to arrive in seconds. Access still depends on testing, settlement arrangements and participant readiness. NCFA's RTR access rules guide shows why a system launch does not give every provider immediate access.
Pliant is making corporate payment infrastructure accessible to software agents, not just staff clicking through expense screens. That creates demand for clear limits, approvals and records of who authorized each instruction. Canadian firms already face these AI agent payment authority questions. The $80 million round funds expansion, while transaction controls and customer adoption will determine the product's value.
A recipient name that differs slightly from the bank's record can interrupt a legitimate payment or confuse a sender. Consistent matching gives banks a better chance to handle those cases without weakening fraud checks. PSPs should test character handling and near matches against real customer records, then measure false warnings and stopped payments. The rules work only when the customer experience is clear.
Ebury is preparing to sell instant Canadian payments through infrastructure it already uses abroad. That may shorten integration work, but customers cannot use an announcement to settle funds. The next milestones are access and testing under Canada’s RTR rules, followed by actual payment availability. Corporate clients should watch those dates before changing treasury processes.
The shift is from an AI assistant recommending a payment to software executing one under delegated authority. That turns spending limits, identity, revocation and transaction logs into core payment infrastructure. The same control questions are emerging across AI agent financial authorization and security.
Peak demand is where payment infrastructure becomes visible to a merchant. A provider that keeps checkout working during short bursts of traffic can directly influence completed sales, but the useful benchmark is measured performance rather than the integration itself. Transaction success, latency, conversion and processing economics will show whether the deployment strengthens Unlimit's position in India's competitive payments market.
OKX has given eligible US stablecoin holders a spending option without a separate manual cashout. The question is how the product handles conversion costs, availability and rewards once customers use it regularly. For payment firms, this adds another live case to the stablecoin card settlement market. It is not a Canadian card launch.
Bill S-8 would make registration harder for risky money services businesses and change how financial crime intelligence reaches regulated firms. Crypto ATM operators should review the proposed restrictions against their current licences and locations. Payment firms should examine what new information FINTRAC could demand. NCFA’s crypto ATM money laundering guidance offers background, but the bill is not yet law.
Crypto issuers and counsel now have more specific staff language to test against token design and disclosures. The guidance can narrow unanswered questions, but it is not legal immunity. Businesses should track which interpretations affect their product structures without presenting staff FAQs as binding law.
Singapore is attacking two barriers to insurance capital reaching infrastructure deals, expertise and capital cost. Insurers can assess the grant immediately, while asset managers should examine whether the proposed risk criteria fit the deals they can originate. The consultation could alter financing demand across infrastructure and securitized assets.
The implementation date turns the September rulebook into a balance sheet decision for affected banks. Clearing, custody, trading and financing teams can now price eligible activity against the final treatment. The distinction between tokenized deposits and crypto exposures remains important under Canada's OSFI 2027 crypto rules.
Banks don’t have a new AI rule to implement here. They do have a clearer view of the questions examiners may ask about consequential automated decisions. Can staff stop an agent? Who approved its authority? Can the bank explain a failure? Those are practical tests of AI agent authorization controls, even though the OCC guide imposes no new standards.
Moving fraud logic from engineering queues into the risk function can shorten the time between a new attack pattern and a production control. It also makes governance more important because rule changes can affect onboarding, approvals and declines immediately. The product will be more valuable if customers can show faster response without increasing false positives, exceptions or unexplained automated decisions.
The FCA is giving firms failure patterns they can test against now. Data lineage, change testing, AI inventories, conditional approvals and kill switch ownership all become concrete control questions rather than abstract governance principles. Similar issues are emerging across AI, programmable finance and financial crime regulation.
The merger puts regulated bank funding and embedded business lending under one owner. Liberis gains another way to fund offers delivered through its partners. Qred gains wider merchant distribution. Small businesses will judge the combination on approval times, price and repayment flexibility. Reach across 17 countries is valuable only if the lending economics hold up.
ESG ratings providers now have deadlines, not just broad calls for better disclosure. Firms selling ratings in the UK should review their conflicts controls, methodologies and customer explanations ahead of the June 2027 application window. Asset managers have work too. They need to know whether the ratings suppliers embedded in their products can meet the new standards before June 2028.
Tokenized deposits are becoming a treasury product for actual institutional customers, not just a bank demonstration. The commercial value rests on when money can move, how much liquidity must sit idle and what treasury systems can connect. Measured customer flows are the next test.
Clearing members can now use certain RMB bonds as margin instead of tying up as much cash. **More than RMB 400 million posted on day one** gives this a stronger operating basis than a policy proposal. The saving will depend on haircuts, custody charges and funding costs. Banks should measure the cash released, not just the amount of collateral accepted.
Wealthsimple could bring Canadian dollar digital assets to customers who would never open a crypto wallet themselves. CADD already exists, so this is a new distribution and reward announcement, not the launch of the stablecoin itself. NCFA covered CADD's original regulated issuance in May. The next test is how many clients use it for payments or cash management rather than simply collecting rewards.
Zero commission Canadian options put more pressure on trading fees, while faster order entry makes a difference for active clients. Direct indexing adds a tax planning product within accounts investors already use. The bigger competitive test is whether Wealthsimple can serve frequent traders without higher spreads or weaker execution. Its planned perpetual futures also bring suitability and leverage questions that matter as much as headline pricing.
Capital.com has permission to enter Singapore, but it still needs customers. The company plans to begin onboarding in 2027, so local brokers have time to prepare. Investors should compare the instruments, trading costs and safeguards actually offered at launch. Regulatory approval opens the market; it does not establish customer traction.
Canada’s RTR launch, proposed banking reforms and new digital asset rules make this a consequential week for financial innovation. Globally, firms are putting AI, tokenization and new payment infrastructure into practical use. For Canadian fintechs, the opportunity is in execution. Clearer rules, better access and products that solve real customer problems will determine who can compete and grow.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech news and insights, industry research, or launch into emerging financial innovation opportunities.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
November 6, 2026 | Insight | Competition And Market Structure, Payments Infrastructure And Money Movement, Capital Markets Infrastructure And Funding
On November 5, 2026, Finance Minister François Philippe Champagne tabled Budget 2026 with a financial sector package aimed at making it easier for credible new competitors to enter, raise capital and grow. The Budget 2026 financial sector measures cover bank approvals, ownership, deposit funding, payments, stablecoins, investment capital and commercialization. Separate measures tighten fraud, financial crime and consumer protection. Many of the digital finance building blocks started in Budget 2025's fintech and capital agenda. A year later, some are reaching implementation while Budget 2026 goes further on bank entry, ownership, funding and competition.
Canada's six largest banks still hold about 93% of banking assets, leaving new entrants to compete against institutions with major advantages in deposits, distribution, capital and customer relationships. Outside banking, Canada also has a large C$14 trillion non bank financial system spanning investment funds, pensions, insurers and other financial firms. Canada has plenty of financial activity, but needs stronger competition in core banking and payments.
Ottawa wants to add competition as a secondary statutory objective for OSFI while keeping financial stability first. Proportionality, compliance burden and market impact would become explicit considerations when OSFI regulates and supervises financial institutions. Smaller institutions often carry many of the same fixed regulatory costs as much larger competitors, so the way those rules are applied can affect whether a new entrant can build a viable business.
Peter Routledge, Superintendent of Financial Institutions
“Our role is to ensure the prudential framework does not create unnecessary barriers to responsible competition.”
OSFI's streamlined approval rules for targeted new entrants already use a 12 month target for formal review after OSFI accepts a complete application. That clock doesn't include all the work required before filing or everything needed before a new institution can begin operating.
Budget 2026 proposes a maximum one year statutory decision timeline for new banks, trust and loan companies and insurers. It would also remove some self dealing restrictions that can limit how a new institution organizes itself while waiting for approval. A ministerial policy statement would give applicants more guidance on entry, transitional relief and proportional regulation. Applicants still need capital, governance, systems, risk controls and a credible business plan, and the legislation still has to define exactly when the statutory clock starts and stops.
Santander first published notice of its Canadian bank application in July 2019. Santander's Canadian banking licence followed years later, with an amended structure involving its Canadian finance businesses receiving an order to commence business in March 2025. The application changed along the way, so that full timeline can't be compared directly with Budget 2026's proposed one year decision period. It does show how long the full path into Canadian banking can take.
A challenger still needs enough capital to grow. Budget 2026 would raise the equity threshold at which a bank must become widely held from $12 billion to $25 billion. Certain foreign bank subsidiaries with less than $8 billion in equity would get more ownership flexibility, while federal credit unions could bring in a wider range of qualifying cooperative shareholders.
Those rules leave successful challengers with more room to raise capital before ownership restrictions tighten. Canada has already added new entrants such as Questbank. New banks still have to attract enough deposits and customers to take meaningful share once they're licensed.
Budget 2026 also proposes raising CDIC protection from $100,000 to $250,000, adding temporary protection for high balances after events such as a home sale and removing the limit for eligible deposits in registered and tax free accounts. Finance says stronger coverage can improve smaller banks' access to lower cost funding. Customers holding larger deposits would also have less reason to favour a large bank simply because of its balance sheet. The existing $100,000 limit remains in force until legislation changes it.
Ottawa also plans to improve funding access for small and medium deposit taking institutions, expand voluntary exit options and keep making prudential requirements more proportionate to size and risk. That continues the direction already visible in OSFI's competition and growth approach. Easier entry won't mean much if firms can't afford to stay and compete.
Canada's Real Time Rail is scheduled to launch on November 9, 2026. Budget 2026 didn't create RTR, so the launch shouldn't be treated as a new budget initiative. The budget starts the next policy phase with an early 2027 payments consultation, a review of the Canadian Payments Act and proposed changes to the Retail Payment Activities Act.
Canada had already started opening core payment infrastructure before this budget. Federal changes made regulated PSPs, qualifying local credit unions and designated clearing houses eligible to join Payments Canada. By October 2026, 22 new members had joined Payments Canada after the access reform, with 20 becoming eligible because of the new rules. The group includes Wise, Float, KOHO, Neo Financial, Adyen, Remitly and several credit unions.
Membership changes who can get into the system, but it doesn't provide automatic access to every rail. Canada's Real Time Rail access rules still require settlement arrangements, technical integration, testing and certification. Wider access can reduce dependence on incumbent intermediaries, but fintechs still have to turn that access into better products, pricing or service.
The RPAA amendments would strengthen Bank of Canada supervision as the regulated PSP market matures. Ottawa also wants provinces and territories to work toward more consistent consumer protection for payment firms. Different provincial requirements can add cost to a fintech serving customers nationally even when the service itself runs through one platform.
A voluntary digital credentials pilot is also planned for financial services. Reusable credentials could reduce repeated document checks and strengthen onboarding, but the budget hasn't defined the technical model or participants. Banks and fintechs only gain if the credentials work across organizations rather than create another closed identity system.
Consumer driven banking gets a smaller update because most of the framework was already underway. Budget 2026 proposes clearer annual banking fee information supported by data sharing, while Canada's broader consumer driven banking market continues toward regulated data access and payment initiation. The budget doesn't announce another accreditation model or a new timetable for write access.
Budget 2026 changes how banks could issue stablecoins. Canada has enacted the Stablecoin Act and published proposed operating regulations, but the regime isn't fully in force. Federally regulated financial institutions would be prevented from issuing stablecoins directly and would instead have to use a non financial institution subsidiary regulated under the Act.
A bank would still bring capital, distribution and customer relationships, but its issuing entity would sit inside the same Canadian stablecoin regulatory framework as other covered issuers. Final reserve, redemption, custody, capital and insolvency rules will determine how close the competitive treatment really becomes.
Budget 2026 would also extend the Stablecoin Act to foreign financial institutions that aren't already prudentially regulated in Canada. Canadian PSPs, wallets and exchanges will want access to credible global stablecoins their customers already use. Foreign issuer rules therefore affect product choice, liquidity and integration costs even for Canadian companies that never plan to issue a stablecoin themselves.
Canada and the EU are also exploring connections between their instant payment systems and wider access to each other's banking, insurance and fintech markets. There is no new market access yet. If the work produces operating rights, Canadian fintechs could gain a larger payments corridor without building every international connection separately.
A qualifying individual could exempt up to $15 million in capital gains for each qualifying business under the proposed Canada Growth Incentive. The headline is large, but the eligibility tests narrow the pool considerably.
The person must be at least 18 and resident in Canada in the year of the claim. The company generally needs to be a Canadian controlled private corporation when the shares are issued, with combined related corporate assets of no more than $100 million. The shares normally need to be newly issued on or after November 5, 2026 and held for at least 36 months. Canadian business and asset tests also apply for much of that period.
Financial and insurance businesses are excluded. A software company selling technology to banks may qualify depending on what business it actually carries on. A bank, lender, insurer or other company operating as a financial business shouldn't assume it does.
Existing founders also shouldn't assume shares they already own suddenly qualify. The new rules generally apply to shares issued on or after Budget Day. Finance estimates about $715 million in fiscal cost over four years but doesn't publish a reliable count of qualifying individuals or companies. Its impact analysis expects nearly 84% of beneficiaries to have adjusted gross income above $200,000 and more than 75% to be men.
The incentive leaves more capital with qualifying founders and investors after a successful exit. The enhanced small business rollover also gives investors more time to reinvest qualifying proceeds, including additional flexibility for some future equity agreements such as SAFEs.
SR&ED may reach a wider group of fintech and regtech companies. Budget 2026 proposes adding certain commercialization costs tied to eligible R&D, including necessary regulatory approvals, certifications and intellectual property protection. Ottawa estimates $930 million over five years and $235 million annually after that. Marketing, distribution and ordinary sales costs don't suddenly become eligible.
The $750 million Early and Growth Stage Investment Strategy remains part of the startup capital picture, but it isn't new Budget 2026 money. Budget 2025 announced the BDC managed program, with $75 million for pre seed and seed investment and $675 million for later and growth stage capital.
The $25 billion Canada Strong Fund adds another route for private capital into Canadian projects and high growth companies. The Fund launched earlier in 2026, while Budget 2026 adds more detail on minority co investments, strategic investments and a new retail product planned for 2027. Canada Strong Notes would let individuals invest alongside the Fund through participating financial institutions, with principal protection, a coupon and some participation in Fund returns. Final terms will determine whether the Notes become a meaningful new retail investment channel.
Ontario's decision to join Canada's securities passport system could reduce duplicated work for companies raising capital across provinces. Ontario is the country's largest capital market and has historically sat outside the passport. Joining won't create more investors, but fewer duplicate filings and reviews can make national financings easier to execute.
Budget 2026 leaves NI 45-110, accredited investor rules and retail exempt market access largely untouched. Canada's C$1.5 million crowdfunding issuer cap remains in place, despite NCFA's longstanding position that the limit should rise to at least C$5 million to give smaller issuers a more practical path to growth capital.
Life insurers get more investment flexibility as well. Ottawa plans to broaden the infrastructure investments permitted under the Insurance Companies Act. Canadian life insurers manage large pools of long duration capital, so wider investment powers could direct more institutional money into domestic infrastructure without creating another government funding program.
Budget 2026 combines stronger competition with more accountability for firms serving consumers. Fraud losses, banking fees, mortgage costs and account switching all affect whether consumers can benefit from having more providers in the market. Several measures therefore target the cost and risk of everyday financial services rather than market entry itself.
Fraud prevention becomes more commercially important when firms carry more of the loss. Banks and fintechs have stronger reasons to improve authentication, identity verification, transaction monitoring and intervention before money leaves an account. Wider access to non public beneficial ownership information and stronger powers to dissolve corporations used for fraud add another layer to those controls.
Several other measures deal with financial system resilience rather than fintech competition. The Bank of Canada would gain authority to hold foreign currency for emergency lending to banks under severe stress. Ottawa also plans a Canadian Earthquake Insurance Facility, while federal pension rules would allow more electronic communication and reduce some administrative requirements.
The Minister of Finance would also gain authority to order banks and related institutions to sell investments in Canadian businesses when national security concerns arise. Financial institutions buying technology companies or other strategic assets would therefore face another potential review consideration.
Canada has spent years talking about more financial competition. Budget 2026 puts more of the plumbing behind it. The opportunity is real, but access and competitive gains only appear if new entrants can turn it into better products, lower costs and meaningful customer choice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 5, 2026 | NCFA Story Intelligence | Risk Compliance And Regtech, Regulation And Policy, Digital Assets Blockchain And Tokenization
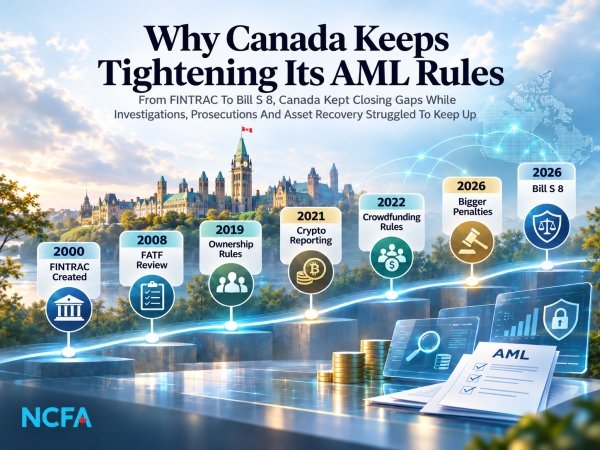
Canada added another layer to its anti money laundering system on November 3, 2026.
Bill S-8 would tighten registration for money services businesses, give FINTRAC more grounds to refuse or revoke registrations, add controls for crypto ATMs, restrict some large cash transactions and third party cash deposits, and let regulated firms receive more financial crime information from government and law enforcement.
Five days earlier, the Auditor General had delivered a very different AML announcement.
FINTRAC was taking nearly 4 months on average to provide requested financial intelligence. Half of the recipients surveyed said information sometimes arrived too late to help an active investigation.
A month before that, FATF had praised parts of Canada's system while still calling for stronger supervision, more complex money laundering prosecutions and better asset recovery.
Canada isn't short of rules.
It has spent more than 25 years adding them.
This is a story of Canada closing one financial crime gap after another, only to find that more reports and tougher rules don't automatically produce faster investigations, prosecutions or recovered money.
The 2022 truck convoy became one of the most visible turns in that story.
It wasn't the beginning.
Banks and other reporting firms now have to tell FINTRAC when money looks suspicious. Investigators gain a national source of financial intelligence that didn't exist before, and regulated firms can no longer treat unusual transactions as someone else's problem.
But criminals aren't limited to bank accounts. Money can pass through companies, intermediaries, cash businesses, real estate and foreign accounts. The first rulebook catches more activity, and the routes around it become easier to see.
Customer checks get stronger. MSBs register. FINTRAC gains penalties and more supervisory reach. A regulated firm has fewer excuses for not knowing who opened the account or sent the money.
Then investigators reach the company behind the transaction and can hit another wall. The account holder may be visible while the person controlling the corporation isn't. The search moves from the customer to the owner.
A shell company becomes less useful when investigators can identify the people with significant control. The ownership trail gets shorter, and legitimate companies get clearer record keeping duties.
The trail can still cross provincial registries, trusts and foreign entities. And while Canada is looking deeper into ownership, another way of moving value is growing outside the familiar bank payment path. The next gap starts with the money itself.
Crypto exchanges and payment firms now have to build registration, identity checks, records and reporting into products designed to move value quickly. Legitimate operators gain a clearer path into the Canadian market, but compliance becomes part of the product itself.
Bringing crypto inside FINTRAC doesn't cover every new way Canadians can collect or move money. A year later, crowdfunding and payment platforms show where the boundary still ends. The next expansion arrives in the middle of a national crisis.
Ottawa closes the gap quickly. Crowdfunding and payment firms that had built businesses outside traditional banking inherit FINTRAC registration, identity checks and reporting. The line around the regulated market moves again.
Legitimate platforms pay for the same controls. Staff, systems, records and audits become part of the cost of staying in business. The government closes one blind spot and pushes compliance deeper into smaller financial firms.
A suspicious account at one institution can become more useful when another firm recognizes the same owner, wallet or transfer pattern. Activity that once ended inside separate compliance teams can start connecting across institutions.
That gives firms another job. They need controls around what can be shared, why it can be shared and who gets access. Canada gains more intelligence, while compliance becomes a bigger part of running the business.
A strong operator can benefit when firms that ignore reporting duties or regulator requests lose market access. Banks and partners have more reason to trust an MSB that stays registered and responds when FINTRAC calls.
But the price of proving that compliance is uneven. Large institutions spread legal, data and monitoring costs across millions of customers. A startup can't. The regulator starts removing weaker operators just as the cost of being a strong one keeps rising.
FINTRAC no longer has to wait for a criminal case to hit a company hard. It can order fixes, impose much larger penalties and put compliance failures into public view. For regulated firms, the cost of weak controls can arrive long before police lay a charge.
But the money laundering case still has to be built somewhere else. Police need evidence, prosecutors need a case they can prove and assets have to be found before they disappear. Canada has made it faster to punish weak compliance. Catching and recovering the criminal money is still the slower job.
FINTRAC can connect reports across institutions and point investigators toward suspicious money. It can tell police where accounts connect and which transactions deserve another look.
Police still have to identify the people, gather admissible evidence and find the assets before they move again. Ottawa is creating another institution because financial intelligence doesn't arrest anyone or recover a dollar by itself.
Canada now has more reporting entities, ownership data, penalties, registration controls and financial intelligence than at any earlier point in FINTRAC's history. The reporting side of the system is bigger and harder to ignore.
Investigators still need the information before assets move. Prosecutors still need complex cases they can prove. Governments still need to recover more of the money. Canada has become better at spotting suspicious activity than finishing the journey from report to recovered proceeds.
Stronger registration can remove operators that lie about their business, ignore regulator requests or raise serious integrity concerns. Legitimate MSBs, payment companies and remittance firms may benefit when weak operators lose access.
Every added check still needs people, systems and legal work. Small firms spread those costs across fewer customers than banks do. Canada can shut bad operators out and still make the door heavier for good ones to open.
Bill S-8 may close more holes around MSB registration, crypto ATMs, cash deposits and financial crime information sharing.
But Canada is reaching the point where adding another reporting obligation produces less value if the rest of the chain can't keep up.
FINTRAC can collect more information.
Banks, fintechs and MSBs can build better controls.
Law enforcement can receive more leads.
None of that helps much if investigators get the intelligence too late, prosecutors can't build enough complex cases or criminal assets are gone before authorities can reach them.
That is where Canada's next AML chapter is heading.
The proposed Financial Crimes Agency could give Ottawa more capacity to investigate serious financial crime and recover proceeds. Bill C-12 gives FINTRAC much stronger leverage over regulated firms. Bill S-8 would tighten who gets into parts of the market and how certain transactions are handled.
Those tools now have to work together.
For fintechs, that creates a different kind of pressure.
The firms that survive stricter registration and supervision may become easier for banks, investors and customers to trust. But every new control also costs money, and smaller operators don't have the same compliance scale as the country's largest financial institutions.
Canada can keep tightening the perimeter.
The bigger question now is whether the system inside that perimeter can move fast enough to catch the money, recover it and still leave room for legitimate firms to compete.
That answer won't come from the next amendment.
It will come from the cases Canada is actually able to finish.
Will Canada's next AML gains come from tougher rules, or from finally turning more financial intelligence into completed cases and recovered assets?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 5, 2026
A crypto price feed is fresh when it delivers the latest relevant observations for the market it claims to show. A flashing number or a “live” badge cannot establish that. Check what the price represents, when the underlying event occurred, and whether newer events are reaching the display. An unchanged quote can be correct in a quiet market; an animated dashboard can still be behind. You can investigate these differences using visible records, although locating the precise fault may require access to the provider's systems.
Several events happen between a trade and your screen. The exchange records the trade, a data service receives it, an application processes the update, and your browser displays it. Each stage can have a timestamp. A page refreshed at 14:00 may still be displaying a trade from 13:55. The refresh time describes the page, while the trade time describes the observation.
Start with the definition beside the number. A last-traded price is the price of a completed transaction. A best bid or ask describes an available order at a moment. An index combines selected observations according to a method. A derivatives mark serves the contract's valuation rules. These numbers may update differently even when the systems are functioning normally.
When comparing cryptocurrency prices live, align the asset, quote currency, venue or aggregation method, and market type before interpreting a difference. Two tickers with the same asset name may refer to different pairs. A dollar-denominated aggregate and a stablecoin pair are also distinct observations. A mismatch is a reason to investigate the definition before diagnosing a delay.
Look for an event timestamp and its timezone. If the page provides only “last updated,” read its explanation rather than assuming this means the latest exchange trade. The label might refer to a scheduled database update. Where the meaning is undisclosed, record freshness as uncertain; the absence of an explanation does not establish either a fault or a current feed.
Your own clock can complicate comparisons. A device with an incorrect time setting can make a valid event look delayed or even appear to come from the future. Before calculating apparent latency, check automatic time synchronization and timezone settings. A screenshot should preserve the displayed timezone so another reader can understand what the observation means.
An inactive last-trade price is often unsurprising. If nobody has traded the pair recently, the latest completed trade remains the same even while orders change. Check whether the market is open and whether the feed reports trades, orders, or a scheduled reference value. Looking only for a moving last price confuses activity with delivery.
Connection indicators need interpretation too. Coinbase Exchange's WebSocket documentation describes heartbeat messages that include a sequence number and last-trade identifier. These fields can help check continuity. Other services may expose only a connection signal. “Connected” therefore has different evidential value depending on the documented message content; it cannot be treated as a universal freshness certificate.
Here is a compact comparison for a last-trade display:
| What you observe | Possible explanation | Useful next check |
|---|---|---|
| Price unchanged, no newer trades on the same venue | Quiet instrument | Market status and latest trade time |
| Price unchanged, newer trades in the venue's own record | Delayed display or subscription | Event identifiers and app update time |
| Price differs across two venues | Separate order books | Compare matched pairs and timestamps |
| Many old events arrive together | Recovery or buffered delivery | Event time versus arrival time |
These are hypotheses, not diagnoses. A public webpage rarely reveals which stage failed. If a provider offers a status notice, check whether it covers the affected product and time. A general “operational” status can coexist with an isolated problem. Conversely, a notice about one network or service need not describe every market on the platform.
Try a controlled comparison rather than repeatedly refreshing every tab. Keep one instrument visible, note its event time, and compare it with the original venue's corresponding record when accessible. Reopening a page may restore a subscription, but it can also erase the evidence of a recurring interruption. Preserve the observation first if you intend to report the issue.
Check the page's own controls as well. A chart may be paused, displaying a historical cursor, or showing a completed candle while a quote panel updates normally. Resolve those states before blaming the source. If the displayed value changes after returning to the latest candle, the problem was the selected view, rather than necessarily a stale incoming feed. This is a useful first check because it requires no inference about systems you cannot inspect.
Imagine a hypothetical feed that stops reaching a browser at 12:00. The source continues recording trades at 12:01 and 12:02. At 12:03, the browser receives both events close together. The screen may jump through several prices in a second even though the market moved over three minutes. Arrival time compresses the visible story.
That distinction matters for rankings as well as charts. A refreshed biggest crypto gains list shows percentage changes over its stated window. A sudden rearrangement may combine actual market changes with delayed delivery or recalculation. To investigate one row, inspect its underlying price history and update information. The ranking movement alone cannot tell you how quickly the trading occurred.
Missing messages create a related problem. Coinbase's Exchange documentation warns that sequence gaps and out-of-order messages can occur. For a developer, recovery may require the channel's documented synchronization procedure. For a reader, the implication is simpler: a connection that resumes is not proof that the application reconstructed every missed event correctly.
Avoid inferring a tradable opportunity from an old quote. An order placed after the connection recovers is subject to the current market, available liquidity, and order instructions. A stale screen does not reserve the earlier price. Even a market order submitted from a fresh interface can execute at several prices when available depth is limited.
Displayed precision can disguise this uncertainty. Six decimal places may look authoritative, but they tell you how the value is formatted, not how recently it was observed. Likewise, a page that changes color on every update can appear more active than one that refreshes quietly. Freshness depends on the data path and relevant event, not presentation effects.
Use the same sequence each time an important decision depends on a feed:
Video adds another clock. A livestream can include capture, encoding, distribution, and playback delays, while the presenter may display a chart with its own update interval. In crypto market analysis, check the chart's observation time before comparing the host's explanation with your quote page. A clear account of an earlier move remains useful without being a current price reference.
A useful incident report contains the instrument, source, event time, time you observed it, timezone, and a description of the mismatch. Add a screenshot with the relevant labels visible. Exclude account identifiers, access tokens, balances unrelated to the issue, and private browsing details. A reproducible description helps support investigate without turning a public complaint into an account-security risk.
There is no universal number of seconds that makes every crypto feed safe or unsafe. A daily research summary and an order-routing system have different needs. Even a fast feed cannot remove execution risk, source errors, or market volatility. Decide what information your task requires, then assess whether the source actually supplies it.
Freshness is a relationship between an event, its delivery, and your use of the observation. Read the price definition, identify the clock, and compare like with like. When a feed reconnects, check continuity before trusting the apparent jump. If those details are unavailable, uncertainty is the correct finding; extra decimal places cannot repair it.
Yes. It preserves an observation or extraction time rather than a continuing connection. Label the export with its source, time, and relevant window. Reopening the file later does not refresh its contents unless a documented data connection actually runs.
Keep both the original observation and the dated correction when the change affects your analysis. Recalculate dependent results and explain the revision. Replacing one number silently can leave earlier charts or conclusions inconsistent with the corrected data.
No. They may share a data vendor, venue, or cached source. Agreement is more informative when the underlying sources and methods are known. If both reuse the same feed, their matching numbers may reproduce the same delay or error.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 4, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy, Capital Markets Infrastructure And Funding
On October 28, 2026, the World Economic Forum and Boston Consulting Group published Regulation of Digital Assets in a Shifting Global Landscape, based on regulatory developments across 35 jurisdictions and more than 25 digital asset activities. The research includes interviews with 50 public and private sector experts, workshops and input from more than 100 participants. Digital assets can be legal and regulated while still being difficult for banks, asset managers and other institutions to use at scale.
More than 70% of the jurisdictions studied regulate the activity being performed rather than relying only on the form of the asset. Trading venues, custodians and payment providers are supervised in more than 75% of the sample. Progress still varies widely within individual countries. A market can have clear rules for tokenized securities while its stablecoin, custody or settlement rules are still incomplete. For a company deciding where to operate, the rules for its actual business matter far more than a country's overall reputation for digital assets.
The 38 page resource compares rules for token issuance, exchanges, wallets, custody, payments, lending, staking and the infrastructure behind digital assets. It also looks at whether institutions can legally own the assets, protect clients, settle transactions, use digital money and meet capital requirements. The activity matrix shows where each part of the market is regulated, partly regulated, unregulated or prohibited.
Cryptoassets account for roughly $3 trillion in market value, stablecoins about $300 billion in circulation and tokenized real world assets about $30 billion. One scenario cited in the research puts tokenized real world assets at approximately $88 trillion by 2035, equal to around 16% of global investable assets. BlackRock's BUIDL fund had reached about $2.6 billion by July 2026, while Euroclear and Banque de France are working on moving a €310 billion commercial paper market onto distributed ledger infrastructure.
Tokenization is already moving into financial infrastructure because issuing the asset is only the beginning. Ownership records, custody, settlement, collateral and servicing all have to work after that. Faster settlement can cut counterparty exposure but may require more cash at the time of settlement. Easier collateral movement doesn't help much if institutions cannot price the asset, pledge it or enforce their claim.
Five barriers can stop institutional adoption even after regulators permit the activity. Leaving one unresolved can keep a legal market small.
Digital assets won't make every middleman disappear, but they can make some existing fees harder to defend. Faster settlement and shared records mean less reconciliation, fewer manual steps and lower servicing costs. Businesses that depend on slow transactions, fragmented records or closed distribution may feel that pressure first. Liquidity, trusted custody, access to customers, risk capacity and market access are harder to replace.
For example, putting a fund onchain doesn't solve pricing, investor records, compliance, redemption, distribution or settlement. Tokenized fund operations after issuance still need all of those functions to work before investors get much benefit from the technology.
There is also money to be made connecting systems that don't yet work well together. Digital money needs places where it can be spent or settled. Tokenized assets need custody and financing. Banks and asset managers need reliable access to both. A company that solves one of those connections may have a better business than one issuing another token or building another closed network.
For founders and investors, a company can have excellent tokenization software and still struggle if customers cannot settle, finance or distribute the asset efficiently. Firms with control over liquidity, distribution, custody or an important connection between systems may have much stronger economics.
Not every part of a country's digital asset market develops at the same speed. Switzerland has established legal treatment for tokenized securities and distributed ledger market infrastructure while still developing its stablecoin rules. WEF and BCG state that “The relevant comparison is therefore by activity, not by jurisdiction overall.” A company choosing where to launch needs to examine the rules for its product and business model rather than rely on a broad label such as crypto friendly.
A country with heavy retail trading may need stronger platform supervision and customer protection first. Heavy use of foreign stablecoins can make reserves, redemption and currency risk more urgent. A financial centre trying to build tokenized capital markets may need clear custody, settlement and collateral rules sooner. Copying another country's approach can leave the biggest local problem untouched.
Cross border business doesn't require every country to have identical rules. Institutions need to trust the legal rights, customer protections and settlement outcomes in the other market. Countries can recognize each other's rules where those protections are comparable and avoid repeating the same work. That becomes much harder when supervision, enforcement, data or infrastructure cannot be trusted across borders.
Even the same rule can produce different results. Two firms may follow the same financial crime requirement but use different transaction histories, risk thresholds or blockchain analytics. One may accept a wallet that another rejects. Similar differences can affect collateral values, transaction data and controls. When that happens often enough, legitimate business gets slower and liquidity can break into smaller pools.
Canada now has several parts on the go at once. Proposed federal stablecoin rules cover reserves, redemption, custody and Bank of Canada supervision, while Canada's six largest banks are exploring Canadian dollar tokenized deposits. Tokenization is also expanding across funds, securities and settlement. All of these products eventually run into many of the same payment, custody, capital and infrastructure questions.
Canada's stablecoin rules won't create an institutional market on their own. Banks still need practical ways to hold and settle the assets. Custody has to be clear. Collateral has to work inside financing markets. Financial crime controls have to work across different networks. A stablecoin can meet its reserve requirements and still see limited institutional use if the rest of the transaction is difficult or expensive.
Tokenized securities and deposits face the same reality. Faster settlement can force treasury teams to keep more cash available during the day. Tokenized collateral only helps when lenders can recognize it, value it and enforce the claim. Systems can connect technically while ownership, privacy or compliance problems remain unresolved. A digital asset becomes commercially useful when the whole transaction works, not simply when one part has moved onchain.
The 35 country comparison is useful because it covers more than 25 activities and nine areas of regulation, making it easier to see exactly where a market is ready and where something is still missing. It also connects regulation to funding, collateral, settlement, custody, payments and business economics rather than treating compliance as a separate exercise.
The regulatory matrix mainly reflects conditions as of February 2026, and rules are changing quickly.
Digital Assets Regulation Insights from Jurisdictional Approaches (WEF comparison of nine jurisdictions published in 2024)
Stablecoin Regulations In Canada (current NCFA reference for Canada's federal stablecoin rules and implementation)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 4, 2026 | NCFA Regulatory Insight | Regulation and Policy, Digital Assets, Payments, Capital Formation, Artificial Intelligence
On November 3, 2026, Democrats won control of both the U.S. House and Senate, changing who will set the congressional agenda for financial policy when the new Congress begins January 3, 2027. The U.S. midterm election result creates divided government because President Donald Trump remains in office. Congress can change committee leadership, investigations, hearings and which bills move, but it cannot reset laws already passed, court cases underway or agency rules already moving into force.
For fintech, crypto, banking and capital markets, the election creates two different clocks. Congressional oversight can change quickly. Rewriting law is harder because presidential veto power remains, contested Senate legislation can still need 60 votes to advance and regulators continue working under authority Congress has already given them.
| Policy file | Where it stands now | What changes in January | What keeps moving |
|---|---|---|---|
| Crypto market structure | CLARITY stalled after Senate cloture failed 49 to 50 | New committee control and new negotiating terms if the current Congress does not finish the bill | Existing SEC and CFTC authority continues |
| Stablecoins | GENIUS Act is law and implementation is underway | Democratic committees can scrutinize implementation and pursue amendments | OCC rules take effect January 18, 2027 and other regulators continue implementation |
| Open banking | Section 1033 rule exists but compliance dates are stayed by a federal court | Congressional scrutiny of data access, bank costs and fintech competition can change | Court proceedings and CFPB reconsideration continue separately |
| Capital formation | SEC staff is reviewing Regulation Crowdfunding | Congress can change legislative priorities and oversight | SEC work within existing authority can continue |
| Financial AI | AI is already used across lending, fraud, advice and bank operations | Hearings can put more attention on automated decisions, fraud, data and AI agents | Existing financial and consumer rules still apply |
Committee control changes first. Democrats will decide which bills get hearings and votes, which regulators and executives are called to testify and where investigations go. They can demand records, use committee subpoena authority, question regulators and challenge policy through legislation and appropriations. That can change the pressure around a market quickly, but it doesn't give Congress direct control over every financial rule.
The Trump administration still controls the executive branch, while independent agencies retain powers granted under existing statutes. A congressional hearing can expose problems, force explanations and raise the political cost of a policy, but it does not repeal a regulation. Leadership is not fully settled either. Maxine Waters is currently the top Democrat on House Financial Services and Elizabeth Warren is the ranking Democrat on Senate Banking, but the new Congress still has to organize and formally choose committee leadership.
For firms planning around 2027, the first committee agendas will tell us a lot. Hearings, investigations and regulator testimony can change before major legislation does.
Crypto market structure faces the clearest deadline. The House passed the Digital Asset Market Clarity Act in 2025, but the U.S. Senate failed to advance the CLARITY Act 49 to 50 on September 15, 2026. The official Senate roll call confirms it fell short of the 60 votes needed to move ahead.
That vote came after months of negotiation. Republican sponsors said the September draft contained 126 substantive changes requested by Democrats, including changes involving ethics, decentralized finance and stablecoin related bank funding risks. Four Republicans also voted against advancing the House bill, so the disagreement was never simply Democrats versus Republicans.
The CLARITY Act Senate vote leaves the current Congress with one more window before the legislative process resets. If lawmakers cannot reach a deal before January, the new Congress can rewrite, narrow or replace the proposal rather than simply continuing with the same text. Crypto firms therefore face a near term legislative deadline that stablecoin issuers no longer do.
Stablecoins are on a different clock because Congress already passed the GENIUS Act in 2025. On October 21, the Office of the Comptroller of the Currency issued its final GENIUS Act rules for payment stablecoin issuers under its jurisdiction. The OCC rule takes effect January 18, 2027, while the Federal Reserve is taking comments on its own implementation proposal until November 30.
The new U.S. stablecoin issuer rules give companies much more to work with than they had before. Firms now have clearer requirements around reserves, redemptions, capital, governance, custody and approvals. A Democratic Congress can still question regulators, review issues such as foreign stablecoins and rewards, and push for changes later. But it will not be starting from scratch in January.
That puts stablecoins in a different position from crypto market structure. Market structure still depends on another difficult deal in Congress. Stablecoin businesses can already prepare for rules that are taking effect.
U.S. open banking is moving through several channels at once. The Consumer Financial Protection Bureau's Section 1033 Personal Financial Data Rights Rule is still in place, but a federal court stayed its compliance dates on October 29, 2025. The CFPB is also reconsidering parts of the rule. Congress can influence what happens next through hearings, legislation and oversight, but it is not the only force at work. Courts affect timing, the CFPB can revise implementation within its authority, and banks, data aggregators and fintechs continue building commercial connections while the federal framework remains unsettled. See Open Banking and Consumer Driven Finance Interactive Intelligence.
Consumer finance could also attract more congressional scrutiny. Fintech lending, buy now pay later products, fees, credit reporting, privacy and automated underwriting are all areas committees can examine without waiting for a major new law. For operators, the near term signal is not a promised rule change. It is which practices regulators and financial firms are being asked to explain and defend publicly.
Yes, where it already has authority to act. On October 27, SEC Chair Paul Atkins said more than 9,800 Regulation Crowdfunding offerings had taken place over the past decade, raising an average of about US$364,000. He also said:
“I have asked Commission staff to evaluate which aspects of Regulation Crowdfunding can be amended to reduce compliance burdens.”
The SEC is reviewing Reg CF while also examining accredited investor qualification and the public offering process. Congress can hold hearings, legislate or challenge the agency's direction, but the election does not automatically stop work the SEC can conduct under current law.
This is important in Canada because the U.S. Reg CF ceiling is already US$5 million, while Canada's NI 45-110 start up crowdfunding exemption remains capped at C$1.5 million per 12 months. The recent U.S. crowdfunding reform review provides a useful benchmark as the SEC considers further changes.
NCFA continues to recommend raising Canada's NI 45-110 issuer fundraising cap to at least C$5 million. That is NCFA's policy recommendation, not current Canadian law. If U.S. fundraising rules become easier to use while Canada's cap stays fixed, the competitive difference becomes harder for Canadian founders and policymakers to ignore.
AI probably will not move through Congress as one clean financial policy file. Banks and fintechs already use it in underwriting, fraud detection, customer service, advice and operations. AI agents are also beginning to interact directly with financial systems, raising harder questions about consent, authority and responsibility.
Congress can move faster through oversight than through a comprehensive financial AI law. Committees can ask how firms test automated decisions, prevent discrimination, control fraud and decide what an AI agent can do with money or account access. For firms, the early signal will be the questions banks, fintechs and regulators are required to answer, not simply the number of AI bills introduced.
None of the November 3 election results changes Canadian law. Canada’s rules for banking, payments, securities, stablecoins, crowdfunding and consumer driven banking continue on their own timelines. But the business impact can still cross the border because Canadian firms compete for U.S. customers, capital, partners and infrastructure.
Canadian crypto firms need to watch whether CLARITY returns before January or is rewritten under the next Congress. Canadian wallets and payment companies also need to follow U.S. stablecoin rules because they can affect which U.S. dollar products, issuers, custody options and networks are practical to use.
Capital raising creates an even clearer comparison. If the SEC makes Reg CF easier to use while Canada keeps its C$1.5 million issuer cap, Canadian founders face a different fundraising market from U.S. competitors. Canada does not need to copy the U.S., but it does need to understand when U.S. rules make it easier or harder for Canadian firms to compete.
Open banking and AI can also affect Canadian firms even when the laws stay domestic. U.S. decisions on data access, bank connections, third party providers and AI agents can influence product design, partnerships and investor expectations for companies operating in both markets. Canada should set its own rules around Canadian priorities while keeping those cross border effects in view.
The U.S. midterms change who controls the congressional agenda, not the entire financial rulebook. Some files, especially crypto market structure, now face a different political path. Others, including stablecoin implementation, open banking litigation and SEC capital formation work, keep moving. January changes the negotiating table, not the starting point.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 24, 2026 | Last Updated Nov 4, 2026 | NCFA Fintech Whisperer | Regulation And Policy, Capital Markets Infrastructure And Funding, Artificial Intelligence And Data, Cybersecurity Fraud And Financial Crime, Competition And Market Structure, Cross Border Payments And FX, Wealthtech Investing And Trading, Digital Banking And BaaS, Digital Assets Blockchain And Tokenization, Payments Infrastructure And Money Movement, Risk Compliance And Regtech, Sustainable Finance ESG And Financial Inclusion
Image: Freepik
NCFA Fintech Whisperer tracks weekly fintech market intelligence that changes how financial markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins.
Missed a prior week's Fintech Whisperer? Browse December 6 to 12, 2025, December 13 to 19, 2025, January 1 to 9, 2026, January 10 to 16, 2026, January 17 to 23, 2026, January 24 to 30, 2026, January 31 to February 6, 2026, February 7 to 13, 2026, February 14 to 20, 2026, February 21 to 27, 2026, February 28 to March 6, 2026, March 7 to March 13, 2026, March 14 to March 20, 2026, March 21 to March 27, 2026, March 28 to April 3, 2026, April 4 to 10, 2026, April 11 to 17, 2026, April 18 to 24, 2026, April 25 to May 1, 2026, May 2 to 8, 2026, May 9 to 15, 2026, May 16 to 22, 2026, May 23 to 29, 2026, May 30 to June 5, 2026, June 6 to June 12, 2026, June 13 to June 19, 2026, June 20 to June 26, 2026, June 27 to July 3, 2026, July 4 to July 10, 2026, July 11 to July 17, 2026, July 18 to July 24, 2026, July 25 to July 31, 2026, August 1 to August 7, 2026, August 8 to August 14, 2026, August 15 to August 21, 2026, August 22 to August 28, 2026, August 29 to September 4, 2026, September 5 to September 11, 2026, September 12 to September 18, 2026, September 19 to September 25, 2026, September 26 to October 2, 2026, October 3 to October 9, 2026, October 10 to October 16, 2026, October 17 to October 23, 2026.
A shorter national deadline changes staffing, escalation and evidence requirements for dealer complaint teams. Firms that still rely on manual handoffs will have less room for delay. Compliance vendors also get a clearer design target for case routing, document collection and management reporting.
The FCA has converted a promotions case into a practical market exit. Offshore location doesn't protect a crypto platform from UK conduct rules when it still reaches UK customers. Exchanges, affiliates and distribution partners need controls that can prove where promotions land and who can still open or fund an account.
Tokenized collateral now has a defined supervisory route into central clearing. CCPs can design against that route, but approval will still turn on liquidity, custody, legal certainty and access during stress. That connects directly with NCFA’s work on tokenized assets becoming market infrastructure.
The UK equity tape now has a clearer business model and a harder resilience test. Trading venues and prospective tape operators need to price income sharing, service continuity and incident reporting together. Data coverage alone won’t win this market.
Cross border clearing works only when supervisors can rely on each other. This agreement gives Indian clearing corporations a clearer route into UK oversight while preserving the Bank of England’s financial stability role. The next test is whether recognition and access become easier in practice.
The implementation window is effectively over. Fund managers and distributors now need their liquidity controls, derivatives processes and authorization workflows ready for the November 1 rules. The value of the guidance is operational certainty before the new regime goes live.
Canada now has enough detail for firms to start building against the rulebook rather than policy direction. Issuers can model reserve composition, custody, redemption costs, reward structures and Bank of Canada registration now. Payment firms also need to map where stablecoin activity pulls them into RPAA oversight. NCFA's stablecoin regulatory framework tracks those layers together.
Tokenized markets can't run continuously on stale prices. Chainlink is closing that gap with a single pricing reference that stays available when the underlying exchange is shut. The commercial test is whether continuous data supports deeper weekend liquidity and broader use of traditional assets as onchain collateral.
Fund managers can now add a regulated digital issuance layer without replacing the service providers they already use. That lowers the cost of testing tokenized share classes and strengthens the case for tokenized assets as market infrastructure. Live issuance volume and distributor adoption are the next proof points.
Thailand is working to give crypto exchanges a route into regulated derivatives trading without forcing them to build separate businesses. That could lower expansion costs while bringing trading, clearing and risk controls under closer supervision. Combined with Thailand's recently finalized crypto ETF rules, the proposals give exchanges and investment firms more ways to serve investors. The next test is whether the final licensing requirements make commercial entry practical.
A shared ledger becomes more useful as both lenders and large borrowers join it. Goldman adds another major institutional node to 1Source and strengthens the case for replacing bilateral reconciliation with a common record. The next proof point is transaction volume and how quickly more counterparties stop running parallel comparison processes.
Tokenization has moved from DTCC’s roadmap into live depository infrastructure. Banks and asset managers can now test whether tokenized positions improve collateral use, liquidity or settlement while keeping the underlying DTC rights intact. NCFA’s crypto custody intelligence tracks the same shift toward regulated tokenized market infrastructure.
HKEX is pulling more fund distribution work onto shared infrastructure. That can reduce duplicated integrations across managers, distributors and transfer agents. The commercial test is whether the larger network lowers servicing cost and makes new fund distribution easier.
Archax is extending tokenized government debt from issuance into continuous institutional access. The firm has already demonstrated onchain delivery versus payment with tokenized cash. Now the question is whether euro investors use the product for treasury, collateral and liquidity management.
Public blockchain infrastructure is moving into institutional note issuance with regulated distribution attached. Mirae controls the instrument lifecycle while Marketnode provides the investor route. That fits the broader shift NCFA tracks in tokenized capital markets infrastructure.
Private market tokenization needs usable exits, not just digital ownership records. Pontoro is testing that problem with a live pool that combines liquid assets and private fund interests. NCFA has tracked the same liquidity constraint in tokenized asset liquidity infrastructure.
This pushes onchain funds beyond cash and credit into public equities. Janus Henderson already has more than $1 billion in onchain strategies, so distribution and servicing scale now matter more than proof of concept. The larger question is how quickly tokenized funds become normal market infrastructure.
Institutional DeFi has had a custody problem. Institutions often need assets to stay inside qualified custody, while lending protocols expect collateral to interact with onchain contracts. CustodySync creates a bridge between those control models. Usage will show whether that bridge can turn idle custodied assets into repeatable financing activity.
The commercial test for tokenized funds just changed. The question is no longer whether a regulated fund can be put on chain. It's whether investors will use continuous liquidity when the underlying portfolio still operates on conventional market hours. Spreads, market maker depth and off hours price gaps now become the metrics worth watching.
For venue operators, this is an access issue, not a documentation exercise. Firms serving Malaysian institutional flows need to know whether their platform, instruments and client model fall inside the approval perimeter before November 1. Banks and liquidity providers should be checking the venues they rely on at the same time.
This is where digital bond settlement on Pontes starts competing on infrastructure, not demos. The value is interoperability with markets institutions already use. Banks, custodians and issuers can now compare digital issuance with conventional settlement on liquidity, collateral mobility, operating cost and execution time.
This is distribution infrastructure attached to a large existing fund, not a sandbox asset. The Schroders tokenized money market fund approval provides another regulated institutional benchmark. The next proof point is whether tokenized access changes subscriptions, settlement, collateral use or investor reach. Fund managers should watch where wallet based access removes friction and where the conventional fund stack still does the heavy lifting.
AI is now changing the cost structure behind open finance connectivity. Powens is using agents inside production engineering while keeping human approval before release. For operators, the useful benchmark is whether faster connector maintenance improves uptime and coverage without weakening control evidence. NCFA’s open banking intelligence tracks those operating requirements.
The more important signal is operating expansion, not the financing round. Casap is moving agentic automation from one regulated workflow into several functions where decisions affect customers, losses and recovery. Financial institutions adopting similar systems need clear authority boundaries, exception handling and evidence for every automated action as AI agent financial authorization and security becomes an operating control.
Banks are setting the access rules before personal AI agents become a normal financial interface. Canada’s consumer driven banking system is built around permissioned data sharing, while agent access adds delegated authority and transaction control. Authentication, consent and liability now need a workable model for agents as well as people.
The scale makes endpoint access, service permissions and withdrawal authorization a board level control issue for digital asset platforms. The final technical account will matter more than early attack theories. Exchanges, custodians and infrastructure vendors should compare privileged access, transaction approval and emergency freeze controls against the failure path Binance ultimately confirms.
Quantum migration now has federal target dates, which turns a distant security issue into a planning deadline. Financial firms need cryptographic inventories, vendor commitments and replacement schedules before 2030 pressure arrives. NCFA’s post quantum planning analysis explains why the work has to start well before vulnerable systems fail.
App stores are payment gatekeepers, not just software distributors. South Korea's orders challenge the fees and restrictions that make competing payment systems harder to sell. Developers could gain more control over checkout costs and customer payments, while payment providers get a better chance to compete. The commercial test is whether Google and Apple implement the required changes without replacing old restrictions with new ones.
Prediction markets are now a jurisdiction fight over who controls access to federally regulated contracts. The outcome can change where platforms can operate and how state restrictions interact with CFTC registration. Canada is watching the same category develop through firms such as Verdx and its event contract dealer application.
Thai issuers now have firm deadlines to build emissions records, reporting controls and assurance processes that investors can check. That's commercial work for data providers, auditors and compliance software firms. Canada is taking a different approach with its voluntary green and transition taxonomy. Firms serving both markets will need to distinguish mandatory company disclosures from voluntary investment classifications. The immediate priority in Thailand is getting the data and controls ready before the first reporting year.
Connecting RTR and TIPS could give Canadian payment providers a faster, lower cost alternative to traditional international transfers. The commercial opportunity depends on who gets access, how foreign exchange works and what transactions cost. Firms preparing for Canada's Real-Time Rail access requirements should include European connectivity in their planning, but it's not a service they can offer customers yet.
Movantis is adding stablecoin settlement inside an existing payments network rather than launching a separate crypto product. With more than $60 billion in annual flow already on its infrastructure, even a narrow corridor can become meaningful quickly. NCFA’s programmable stablecoin payments opportunity tracks the same commercial shift toward settlement, treasury and payout infrastructure.
This is a live enterprise payment deployment rather than a partnership announcement. Flywire is being embedded inside a marketplace where cross border settlement, foreign exchange and reconciliation are part of the transaction flow. The next proof point is whether the integration lowers payment friction and cost at scale across complex B2B transactions.
Tokenized investing is moving from single assets into packaged portfolio products that can travel across wallets and chains. The early $40 million uptake gives Ondo more evidence than a typical launch. The next test is whether multi asset tokens attract sustained balances and repeat use beyond crypto native investors.
Canadian brokerage competition is moving from AI research tools into account connected workflows. Webull keeps final trade approval with the investor, but the assistant can now reach live balances, positions and order preparation. Questrade introduced a similar Canadian brokerage connection in July, giving the market two live models to compare.
The proposed transfer would consolidate another sponsor bank portfolio inside an institution already operating at material BaaS scale. Fintech partners will be watching program migration, risk appetite and service continuity because banking as a service partnerships depend as much on the regulated bank relationship as on the front end product.
This gives Canada a major test of whether a large incumbent can add a modern core without waiting for a full bank replacement program. Starting with Simplii gives CIBC a digital brand where product speed matters. Watch migration scope, product release cycles and whether the platform eventually expands deeper into CIBC's retail stack.
The charter gives Ripple a federally supervised operating base around reserves and custody, building on the earlier U.S. crypto trust charter approvals. The next test is execution. Institutions will be watching how quickly the bank becomes live capacity and whether Ripple can turn the charter into deeper relationships across payments, custody and capital markets.
The important change is distribution. Existing MetaMask users get Stellar access without installing another wallet, while Stellar gains a direct route into a large self custody user base. Usage will show whether easier access produces more balances, transfers and token activity.
Stablecoins and tokenized assets need deep markets after issuance. Curve gives Stellar a familiar liquidity engine without routing users through another chain. NCFA has tracked the same institutional requirement in tokenized asset liquidity infrastructure. Depth and spreads will determine whether this deployment becomes commercially important.
Banks can add Stellar assets without building another custody stack from scratch. That lowers integration cost and lets network choice depend more on the asset and client use case. NCFA’s crypto custody intelligence tracks why regulated custody and issuance controls are becoming core tokenized market infrastructure.
CADC now has a securities law distribution route that can reach Canada nationally through regulated and exempt participants. That gives wallets, trading platforms and financial institutions another domestic stablecoin model to assess alongside the proposed federal regime. NCFA's Canada stablecoin market entry analysis explains the broader issuer and infrastructure choices opening around these rules.
The live signal is custody access inside BNY's institutional control environment. That removes one practical barrier for firms that can use digital assets only through established custody, governance and operating processes. Adoption now depends less on whether custody exists and more on what institutions are permitted to do with the assets once held.
The operating change is runtime payment choice. An agent can select how money moves instead of following a payment rail fixed earlier in the workflow. That flexibility increases the importance of transaction limits, recipient validation and revocation because AI agent payment authorization now has to hold across several rails, not just one.
The integration reduces how many providers a Solana payments company has to stitch together before it can move money end to end. That makes network choice less important than reach, compliance and payout coverage. The commercial test is whether one orchestration layer can lower integration cost enough to pull more payment volume onto stablecoin rails.
Konek is taking account based payments into merchant distribution rather than waiting for a new national rail to create the use case. PayFacto gives Interac a practical channel into commerce where card economics already matter. NCFA's Canadian online payments analysis tracks how cards, wallets and bank payments are competing for that checkout.
WalletConnect gives Stellar another route into wallets and payment applications at large distribution scale. Merchant rollout in Bermuda still comes later, so adoption should be measured first through wallet connections and payment volume. The direction fits NCFA’s programmable payments opportunity around wallet access, settlement and merchant acceptance.
Authentication is becoming part of payment orchestration rather than another merchant integration. Adyen can now route an eligible shopper into device based authentication from inside its existing stack. Merchants should watch both conversion and fraud because the commercial win requires improvement on both.
This links stablecoin distribution, institutional settlement, treasury and financing inside one large trading group. The important test is usage. Watch settlement volume, treasury adoption and whether RLUSD becomes a working asset across Robinhood's institutional flows rather than another listed stablecoin.
This phase puts migration work into merchant roadmaps. PSPs and payment teams now have to decide when to update integrations, how long to support both rails and which new Wero functions justify moving early. The long overlap gives merchants breathing room, but it also creates a two year distribution contest for the providers handling the transition.
Faster intelligence only matters if it reaches the payment decision before funds move. The integration shortens the gap between a new risk signal and transaction screening while keeping policy configuration with the financial institution. That makes data freshness, alert quality and audit evidence key measures of whether AI and financial crime compliance actually improve in production.
Independent risk analysis is moving into the same environment where onchain capital is allocated. That can make vault selection and governance more comparable for institutions that need third party evidence before deploying funds. The next step is whether protocols and investment committees begin using the assessments as a formal control rather than optional information.
A$260 million turns weak AML controls into a board level cost. Financial firms should read the judgment as an operating warning on customer risk assessment, monitoring and program evidence. The penalty also raises the price of waiting until supervisory concerns become enforcement.
Tokenized assets become easier to scale when compliance rules can travel with the transaction instead of being checked in a separate manual process. Further is testing that model inside a regulated financial center. The critical proof point is whether institutions adopt the controls in live issuance and trading workflows.
OrigenLink changes the handoff between a bank and an alternative lender. Instead of losing a customer when the bank cannot make the loan, the institution can keep the relationship and add another credit path behind its own brand. That gives banks a way to expand SME lending without building every underwriting and servicing capability internally.
Construction finance exposes the working capital problem in unusually clear terms: businesses often have confirmed work but still need liquidity before invoices are paid. Flex Line adds another embedded credit option for that gap and extends the broader shift toward small business working capital and lending being delivered closer to the operating workflow.
Canada's proposed stablecoin rules would require 100% daily reserve backing, redemption within three business days and a maximum 1% redemption fee, with implementation targeted for fall 2027. Meanwhile, Ripple secured final OCC trust bank approval, BNY opened institutional custody for XRP and RLUSD, and Robinhood brought RLUSD into its trading infrastructure, reaching a platform with 28.6 million funded customers. Companies that control custody, distribution and settlement stand to gain.
Canada's challenge is to turn its regulatory framework into commercially viable infrastructure before global networks capture the market.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech news and insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |

August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016