Category Archives: Cyber Security, Quantum, Hacks, Fraud Alerts, Risks, InsurTech

NCFA Weekly Fintech Intelligence Oct 31-Nov 6, 2026

Oct 31, 2026 | Last Updated: Nov 6, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Digital Identity And Trust, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading

Fintech market intelligence visualization

Image: Freepik

NCFA Fintech Whisperer tracks weekly fintech market intelligence that changes how financial markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins.

Missed a prior week's Fintech Whisperer? Browse December 6 to 12, 2025, December 13 to 19, 2025, January 1 to 9, 2026, January 10 to 16, 2026, January 17 to 23, 2026, January 24 to 30, 2026, January 31 to February 6, 2026, February 7 to 13, 2026, February 14 to 20, 2026, February 21 to 27, 2026, February 28 to March 6, 2026, March 7 to March 13, 2026, March 14 to March 20, 2026, March 21 to March 27, 2026, March 28 to April 3, 2026, April 4 to 10, 2026, April 11 to 17, 2026, April 18 to 24, 2026, April 25 to May 1, 2026, May 2 to 8, 2026, May 9 to 15, 2026, May 16 to 22, 2026, May 23 to 29, 2026, May 30 to June 5, 2026, June 6 to June 12, 2026, June 13 to June 19, 2026, June 20 to June 26, 2026, June 27 to July 3, 2026, July 4 to July 10, 2026, July 11 to July 17, 2026, July 18 to July 24, 2026, July 25 to July 31, 2026, August 1 to August 7, 2026, August 8 to August 14, 2026, August 15 to August 21, 2026, August 22 to August 28, 2026, August 29 to September 4, 2026, September 5 to September 11, 2026, September 12 to September 18, 2026, September 19 to September 25, 2026, September 26 to October 2, 2026, October 3 to October 9, 2026, October 10 to October 16, 2026, October 17 to October 23, 2026, October 24-October 30, 2026.

Weekly Fintech Market Intelligence Oct 31 to Nov 6, 2026

Artificial Intelligence And Data

Wealthsimple Penny Will Execute Financial Tasks With Client Approval

November 5, 2026, Canada
  • Wealthsimple introduced Penny on November 5, an AI assistant designed to help clients manage transfers, invoices and investments using their financial information.
  • Penny is designed to prepare actions such as sending e-Transfers or placing securities orders, but each money movement or trade requires client confirmation. The announcement does not establish that Penny is already publicly available.
  • Wealthsimple also plans connections to ChatGPT and Claude in early 2027, with client permission at setup and another check before critical actions.

Penny brings the practical test of financial AI into everyday accounts. Can a client see exactly what an agent plans to do before approving it? Wealthsimple is keeping confirmation in the transaction path, a useful response to AI agent authorization risks. Banks and fintechs competing here will need reliable permissions and clear records, not just a better chat interface.

MAS Opens Finance AI Institute With Three Programs

November 3, 2026, Singapore
  • The Monetary Authority of Singapore confirmed that its Future of Finance Institute began operations on November 3, initially focused on AI in finance.
  • PathFin.ai will share practical adoption work, BuildFin.ai will develop tools and practices for AI agents, and SafeFin.ai will support risk assessment, testing and assurance.
  • The institute plans to expand beyond AI into tokenization. Specific shared tools and additional implementation details are still to follow.

Singapore wants financial firms to solve common AI deployment problems together instead of rebuilding every control separately. Vendors should watch the tools that emerge from BuildFin.ai and SafeFin.ai. Shared practices can make procurement easier, but they can also raise the minimum standard for selling AI into banks.

HKMA Launches Project SAGE for Agentic Finance

November 2, 2026, Hong Kong
  • Hong Kong Monetary Authority launched Project SAGE, short for Securing Agentic Finance with Governance and Enablement, to support practical agentic finance use cases while developing governance around them.
  • The work covers consumer payments, business procurement and treasury, and machine to machine payments, with specific attention to agent identity, delegated authority, authentication and interoperability.
  • HKMA also created an Agentic Finance Expert Group bringing together financial institutions, technology providers, professional services firms and academia to examine implementation, liability and consumer protection.

Project SAGE moves the agentic finance debate toward the control layer that determines whether financial agents can be trusted to act. Identity alone is not enough. Firms need to prove who delegated authority, what the agent can do and how that authority is revoked. Those questions sit at the centre of AI agent financial authorization and security.

Ireland Sets January Date for AI Consumer Sandbox

November 2, 2026, Ireland
  • The Central Bank of Ireland announced that its third Innovation Sandbox Programme will focus on advancing AI for consumer benefit.
  • Applications are scheduled to open in January 2027. Successful participants will receive structured regulatory advice and specialist support.
  • Officials highlighted fairness of automated decisions, consumer vulnerability, fraud resilience and accountability as practical areas for development.

Firms building AI tools for customer decisions will get a direct route to test designs with the regulator. That matters more than another broad statement on responsible AI. Applicants should arrive with specific decision flows, customer safeguards and evidence they can evaluate during the program.

Capital Markets Infrastructure And Funding

Budget Proposes $15M Capital Gains Exemption for Canadian Builders

November 5, 2026, Canada
  • Budget 2026 proposes a Canada Growth Incentive with a new tax exemption on up to $15 million in capital gains from qualifying investments in eligible Canadian companies.
  • The proposal also expands the small business capital gains rollover so investors can defer more tax when proceeds are reinvested in another eligible Canadian small business.
  • The government estimates $715 million in tax relief over four years beginning in 2027 to 2028. Eligibility and legislative implementation still need to be settled.

For Canadian founders and early investors, exit taxation affects where companies are built and where proceeds get invested next. The proposed relief could make staying in Canada more attractive when a venture succeeds. But the eligibility rules will decide who actually benefits, especially founders, employees with equity and angels backing smaller deals. Until enacted, founders shouldn't price the proposed exemption into a transaction.

BitGo Launches Institutional Trading and Crypto Financing Desk

November 4, 2026, United States
  • BitGo launched Global Markets on November 4, combining its institutional execution, prime financing, derivatives and collateral management businesses after acquiring NYDIG's institutional trading operation.
  • Its institutional offering includes spot and block trades, options, swaps and loans against digital asset collateral, with qualified custody supporting collateral management.
  • Pete Janney, formerly of NYDIG, leads the business. BitGo has not disclosed trading volumes or lending balances for the newly combined unit.

BitGo can now sell custody and financing together rather than leave institutions to connect several providers. That makes collateral eligibility, liquidation terms and counterparty exposure central buying decisions. Clients comparing BitGo's institutional custody services with its new trading desk should press for actual funding costs and settlement performance. The launch alone doesn't establish market share.

CFTC Opens Regulated Exchange Route for Equity Perpetual Futures

November 3, 2026, United States
  • CFTC Chairman Michael Selig announced that perpetual futures on individual equities may begin trading on designated contract markets that are also SEC notice registered national securities exchanges for security futures.
  • The announcement addresses a US access route for a product structure more commonly traded offshore, under existing security futures jurisdiction.
  • Permission is not proof of live trading. No specific newly listed equity perpetual contract or exchange trading volume was confirmed in the statement.

US exchanges now have a route to list equity perpetual futures within registered markets. Brokers can assess a product category many traders currently find offshore. But the business case depends on actual contracts, margins, clearing arrangements and liquidity. No exchange volume was announced, so this is a permission milestone rather than evidence of trading demand.

Broadridge Adds Governance Layer to NYSE Tokenized Shares

November 2, 2026, United States
  • Broadridge plans to provide onchain shareholder governance and digital transfer agency services for the New York Stock Exchange's proposed tokenized securities platform, which remains subject to regulatory approval.
  • The integration would connect tokenized ownership with shareholder records, proxy materials, meeting agendas, voting rules and verified voting entitlements across supported wallets, broker interfaces and ProxyVote.
  • Broadridge says its digital and traditional transfer agency services will work together so NYSE listed issuers can support tokenized shares without separating shareholder rights from established issuer servicing.

Tokenized public equities need more than trading and settlement. They also need reliable ownership records, corporate actions and voting rights. Broadridge is building those functions into the NYSE model before launch, extending the tokenized securities infrastructure layer already forming around regulated markets. Regulatory approval and issuer participation are the next proof points.

Consensys Introduces Cross Ledger Settlement Technology

November 2, 2026, Global
  • Consensys introduced Sovereign Network Interoperability on November 2 for institutions running separate ledgers and market infrastructure.
  • The technology is designed to coordinate securities settlement, foreign exchange and collateral movement without moving assets off their native ledgers.
  • The company describes a technology offering for banks, custodians and market operators. The announcement does not establish customer production volumes.

Financial institutions increasingly face a cost for every separate ledger connection. Consensys is selling a way to coordinate transactions while institutions keep control of their own networks. Buyers will need to test settlement finality, exception handling and integration cost before treating interoperability as solved.

UK Assigns Six Banks to Digital Gilt and Approves Depository Link

November 2, 2026, United Kingdom
  • The UK assigned DIGIT pilot roles to Barclays, HSBC, Lloyds, Morgan Stanley, NatWest and RBC Capital Markets.
  • The Bank of England approved a link between HSBC and LSEG digital securities depositories, allowing investors to access the planned issue through either infrastructure.
  • The first digitally native UK government bond remains a planned pilot issuance by the first quarter of 2027. No completed gilt issuance was announced on November 2.

The approved connection could let investors reach the digital gilt through two depositories instead of one. That gives banks and custodians a real interoperability problem to solve before issuance. They’ll need to test ownership records, settlement finality and investor access. A successful pilot could establish a useful model for digital government bond distribution, but no gilt has been issued yet.

Eurex Plans Hybrid Clearing for Digital and Traditional Assets

November 2, 2026, Germany
  • Eurex Clearing announced plans to combine clearing of conventional instruments and digital assets within a single central counterparty structure.
  • The proposed hybrid approach aims to let participants use existing margin, risk management and default processes while connecting new tokenized products.
  • This is an announced infrastructure plan. The release does not establish that all planned digital clearing services are already in production.

A shared clearing house could give tokenized instruments access to familiar margin and default processes. That may be cheaper than running separate clearing arrangements. Members should test legal finality, collateral treatment and what happens when a digital transaction fails. Eurex has announced the design; live eligible products and actual clearing volumes remain the proof.

tZERO Signs $350M SPAC Transaction With FG Imperii

November 2, 2026, United States
  • Tokenized market infrastructure provider tZERO signed a definitive business combination agreement with FG Imperii Acquisition Corp., with a $350 million pre-money valuation including milestone dependent value.
  • The SPAC has up to approximately $231 million held in trust before redemptions. The transaction also references additional financing arrangements and shareholder approvals.
  • Closing is still subject to conditions. The combined company is expected to seek a NYSE American listing under the symbol TZRO after completion.

The proposed listing could give tZERO capital and a public market valuation for its regulated tokenization business. But the amount available depends on redemptions, financing and closing conditions. Investors should track cash actually delivered and trading activity across its platforms. **A signed SPAC deal is not a completed funding round.**

Canadian Marketplace Trading Fee Cap Drops to $0.0017

November 2, 2026, Canada
  • CSA amendments to National Instrument 23-101 set an active trading fee cap of CAD $0.0017 per share for securities priced at CAD $1.00 or more, including applicable US interlisted securities.
  • The adopted amendments were scheduled to come into force November 2, 2026, subject to necessary approvals. Some jurisdictions have issued temporary blanket relief, so participants must check local application.
  • The related CIRO trading increment amendments align certain Canadian quotations for US interlisted stocks with corresponding US increments.

For active traders, a small fee change can matter across millions of shares. Dealers should model the cap alongside spreads and rebates, then confirm which provincial relief orders apply before changing routing. The November implementation brings the fee cap into actual execution costs for affected markets.

BMO Completes Euroz Hartleys Capital Markets Acquisition

November 1, 2026, Canada and Australia
  • BMO completed its acquisition of Euroz Hartleys’ Australian capital markets business on November 1.
  • The transaction adds Perth based equities research, institutional sales, trading, equity capital markets and strategic advisory capabilities.
  • BMO had operated in Australia since 2004 through Melbourne. The new Perth presence expands its local distribution and metals and mining franchise.

This expands BMO’s ability to connect Australian mining issuers with global institutional capital and advisory services. For smaller market participants, it raises the competitive standard for research, placement reach and cross border execution. The integration matters more than the acquisition headline.

Cross Border Payments And FX

Aqua Global Connects Aquila Banks to StoneX FX and 140 Currencies

November 5, 2026, United Kingdom and Global
  • Aqua Global announced a StoneX integration for Aquila, its banking messaging and transaction automation platform, on November 5.
  • The integration is designed to give banks using Aquila API access to StoneX foreign exchange liquidity and cross border payments in more than 140 currencies.
  • The companies announced the connection but did not release live payment volumes, customer counts for the new integration or a full corridor fee schedule.

Banks using Aquila could add currency coverage without building a separate payment connection for every corridor. That's commercially useful only if rates, compliance checks and failed payment handling work inside normal operations. Firms evaluating bank and cross border payment connections should compare actual execution costs and settlement times rather than count currencies on a slide.

Bitrefill Uses Lightspark USDC to Pay Suppliers in Three Markets

November 4, 2026, United States, Mexico and Brazil
  • Bitrefill is using Lightspark's global payout API to pay suppliers from a USDC balance, converting into bank payments in the United States, Mexico and Brazil.
  • Supported instant rails include FedNow and RTP for eligible US accounts, SPEI in Mexico and PIX in Brazil. Bitrefill's suppliers receive local currency rather than cryptocurrency.
  • Bitrefill serves more than one million customers and lists over 8,000 products across more than 180 countries. Its chief executive says supplier payments can now arrive in minutes instead of days; no independent cost savings figure was supplied.

A gift card seller has to keep suppliers funded even when customers pay in crypto and its suppliers expect local cash. Bitrefill is using stablecoins behind the scenes, not asking suppliers to change what they accept. That puts live evidence behind the cross border stablecoin supplier payments opportunity. The financial test is conversion cost, available liquidity and reliable delivery across more corridors.

RTGS.global Adds AMINA Bank Fiat Accounts and Digital Wallet Access

November 3, 2026, United Kingdom and Switzerland
  • RTGS.global added FINMA regulated AMINA Bank to its cross border network, giving eligible clients a route to both commercial bank accounts and digital asset wallets.
  • Initial services include CHF and EUR fiat accounts with local payment rails and digital wallets. USD and GBP accounts are planned but are not part of the initial offering.
  • Eligible payment firms onboard directly with AMINA and hold accounts in their own business names. AMINA is the first network bank offering both fiat and digital asset capabilities under this arrangement.

Payment providers often need one bank for currency accounts and another provider for digital assets. RTGS.global is reducing that integration burden for eligible firms, although bank onboarding and market coverage still apply. Its value will depend on account approval, funding speed and costs across the banking and digital asset payment connections customers actually use.

Razorpay Gets Final GIFT City Payments Licence

November 3, 2026, India
  • Razorpay received its final Payment Service Provider licence from the International Financial Services Centres Authority to operate in GIFT City.
  • The company says the regulated structure brings international collections, investing related flows, settlement and multiple currencies into one offering.
  • Razorpay cites live integrations with RBL Bank and ICICI Bank, and says platform integration can take two to three weeks. Investment platform launches remain forthcoming.

The licence gives Razorpay a regulated route for cross border payment products and a clearer sales pitch to global platforms. Firms evaluating the service should check permitted flows, payout corridors, bank coverage and actual onboarding time rather than treating the licence as proof that every corridor is live.

Thunes Raises China Instant Payout Limit to US$10,000

November 2, 2026, China and Global
  • Thunes expanded its UnionPay connection so financial institutions, payment service providers and money transfer operators can send instant consumer payouts to eligible UnionPay cards across 79 major Chinese banks.
  • The expanded service supports payouts of up to US$10,000 per recipient cardholder per day, increasing the capacity available through the existing Thunes and UnionPay relationship.
  • Thunes identifies Africa, Australia, Indonesia, New Zealand, Thailand and the United States among the expansion corridors feeding payments into mainland China.

The higher ceiling moves this rail beyond smaller remittance tickets and gives payment providers more room to serve larger consumer transfers without splitting them across transactions. The competitive question is whether instant card payouts can win volume from bank based cross border flows on cost, reliability and reach as cross border payment infrastructure becomes faster and more programmable.

Hong Kong FPS Plans UnionPay QR Payments This Year

November 2, 2026, Hong Kong and China
  • HKMA announced plans to connect Hong Kong’s Faster Payment System with UnionPay International by the end of 2026.
  • The planned link will gradually enable QR payments across UnionPay and partner networks spanning more than 100 million merchants in Hong Kong, mainland China and over 40 overseas markets.
  • The connection is planned, not a completed general rollout. Market availability will depend on participating providers and deployment phases.

Cross border QR acceptance could give Hong Kong bank and wallet users more ways to pay abroad without using a separate travel wallet. Providers should watch fees, currency conversion and participating banks. Merchant reach alone does not establish how much of that network a customer can actually use.

Navro Gains Texas Money Transmission Licence

November 2, 2026, United States and United Kingdom
  • Navro obtained a Texas money transmitter licence, expanding its US state permissions for processing payments and remittances.
  • Its service connects business payment routes through a single API and contract, including international payroll, pensions and other cross border flows.
  • Navro says it serves more than 200 corporate workforce payout customers and international payment activity for 1,700 pension schemes. The company also holds a Canadian foreign MSB registration.

Texas adds another state where Navro can offer regulated payment services directly under its own permission. That makes licensing a sales advantage for firms managing payroll and international disbursements. Clients still need to check other state permissions, supported payout routes and bank arrangements. **One API does not mean one licence covers the entire US.**

Cybersecurity Fraud And Financial Crime

FCA Opens Quantum Financial Crime Experiments for 2027

November 5, 2026, United Kingdom
  • The UK Financial Conduct Authority opened expressions of interest for its Quantum Experimentation Group on November 5, inviting financial firms, quantum providers and research laboratories.
  • Its first experiments will focus on financial crime detection and comparing quantum computing with existing approaches, while assessing practical regulatory issues.
  • Registration closes December 31, 2026. The group is expected to launch in the first quarter of 2027; no completed fraud detection deployment is being claimed.

The FCA is offering firms a route to test whether quantum systems outperform established financial crime tools before committing to expensive infrastructure. Interested compliance vendors need measurable detection questions and credible comparison data. This complements the earlier financial sector quantum readiness work, but the immediate opportunity is experimentation, not a production procurement mandate.

Crédit Mutuel Arkéa Cyberattack Disrupts Bank Transfers

November 4, 2026, France
  • Crédit Mutuel Arkéa disclosed an external cyberattack on November 4 that allowed attackers to transfer money from the bank's own account to accounts at other institutions.
  • The bank traced the intrusion through a service provider's platform, not through its Fortuneo subsidiary or customer accounts. It temporarily suspended some transfers while tightening controls.
  • Arkéa said customer deposits were not financially affected and most transfer services resumed the same morning. It did not confirm a final loss amount, although it acknowledged reports were of the right order of magnitude.

This is a bank payment authorization problem with a third party entry point. Payment firms can't judge resilience only by whether customer accounts were compromised. They also need controls over vendor permissions, treasury transactions and emergency transfer suspension. The cost becomes immediate when legitimate customer payments stop while the bank investigates. Arkéa's precise financial loss remains unconfirmed.

Mashreq Adds Generative AI to Fraud Investigations

November 3, 2026, United Arab Emirates
  • Mashreq launched generative AI capabilities with Clari5, part of Perfios, inside its existing fraud management platform.
  • The deployment focuses on fraud detection, investigator productivity and decision support rather than a separate consumer chatbot.
  • The partners describe an operating deployment, but have not supplied verified loss reduction or false positive figures.

The business case for fraud AI is investigator time and better decisions, not simply faster generated explanations. Mashreq’s deployment puts those claims inside a bank control environment. Buyers should ask for measured investigation throughput, detection quality and evidence trails before extending automation.

HKMA Releases Post Quantum Toolkit for Banks

November 2, 2026, Hong Kong
  • The Hong Kong Monetary Authority launched a Post Quantum Cryptography Toolkit for the banking sector during Hong Kong FinTech Week.
  • The toolkit supports banks planning their transition to cryptographic controls designed to withstand future quantum attacks.
  • HKMA expects the materials to develop further as banks apply them and cryptographic standards and practices mature.

This is a procurement and migration issue for banks long before quantum attacks become routine. Firms need to identify where vulnerable cryptography protects customer data, transactions and long lived records. Vendor contracts and implementation roadmaps are where the work becomes expensive.

Canada Launches Maple Disruption 2.0 With Over 50 Fraud Partners

November 2, 2026, Canada
  • The Canadian Anti-Fraud Centre and RCMP’s National Cybercrime Coordination Centre began Maple Disruption 2.0 for November 2 to 6.
  • More than 50 organizations are participating, including banks, telecom companies, crypto exchanges, police, regulators and technology firms.
  • The operation targets infrastructure used by criminals, including fraudulent websites, email addresses, phone numbers, bank accounts and cryptocurrency accounts. Final disruption totals have not been released.

A fraud report is more useful when it leads to a blocked account, disabled number or removed website. Maple Disruption brings the organizations controlling those channels into the same operation. Banks and fintechs should examine how quickly shared fraud intelligence reaches the team that can act. The real test is disruption achieved, not the number of participants.

Digital Assets Blockchain And Tokenization

BVNK Opens Live OUSD Minting and Payments on Four Networks

November 6, 2026, Global
  • BVNK made Open USD available on November 6 for eligible business customers outside the European Economic Area, with minting, redemption, holding and transfers against USD balances.
  • The platform supports OUSD on Ethereum, Solana, Base and Tempo. Customers can use direct treasury access, embedded payment APIs or wholesale mint and burn arrangements.
  • BVNK says customers can open an OUSD wallet and begin using the service now. It has not reported transaction volume or the number of customers using the newly added asset.

BVNK gives payment providers a working route from dollars to stablecoin balances and back. It's useful for firms that need treasury and customer payouts without building four blockchain integrations themselves. The buying decision still comes down to liquidity, redemption and compliance costs. Those are the same operating constraints in NCFA's programmable stablecoin payments research.

Budget Would Require Canadian Banks to Issue Stablecoins Through Subsidiaries

November 5, 2026, Canada
  • Budget 2026 proposes barring federally regulated banks, insurers and trust companies from issuing stablecoins directly. They would instead use eligible nonfinancial subsidiaries regulated under the Stablecoin Act.
  • Ottawa also proposes applying the Stablecoin Act to foreign institutions not already subject to Canadian prudential regulation, bringing more issuers into the proposed federal perimeter.
  • The Stablecoin Act is enacted, but its principal operating requirements remain pending. These Budget 2026 changes are proposals, not new issuer permissions or current prohibitions.

Banks could still distribute digital money, but issuing it would require a different legal structure. That matters for licensing, reserves and who carries redemption obligations. Canadian wallets and PSPs also need clear treatment of foreign issuers, not just domestic products. NCFA's stablecoin regulatory guide tracks the existing framework while Ottawa works through the proposed amendments.

Bitget Lets Traders Keep Crypto With Outside Custodians

November 5, 2026, Global
  • Bitget launched its Open Custody Network on November 5 to connect eligible trading accounts with banks and institutional custodians while assets stay outside Bitget's custody.
  • The network uses asset mirroring to support spot, margin and futures trading against holdings maintained at participating custody providers.
  • Access depends on customer eligibility, custodian support and trading arrangements. Bitget did not disclose how much trading volume currently uses the new network.

Institutional traders want exchange liquidity without giving one exchange control of their entire asset pool. Bitget is separating those functions, but clients still need to review collateral rights, liquidation instructions and settlement responsibility. The distinction matters alongside NCFA's crypto custody and exchange trust research. Keeping assets elsewhere is useful only when the legal and operational controls hold under stress.

First Abu Dhabi Bank Completes Two Way Crypto Custody Transfers

November 3, 2026, United Arab Emirates and Global
  • Komainu completed transfers both into and out of its regulated digital asset custody environment for First Abu Dhabi Bank, announcing the test on November 3.
  • The bank and custodian say the transfers settled instantly and used a framework integrated with FAB Global Markets' institutional operations.
  • The custody arrangement can support future financing backed by digital assets held in regulated custody. No live financing volume was disclosed with the completed transfers.

The important step is that a major bank can send assets into custody and retrieve them through an operating connection. That is more useful than another memorandum of understanding. Institutions assessing regulated digital asset custody infrastructure will still want evidence of withdrawal reliability, segregation and collateral enforceability before expanding lending against these assets.

Liquid Restores Full Bitcoin Backing for LBTC

November 3, 2026, Global
  • Liquid’s bitcoin reserve again matched the outstanding LBTC supply on November 3. SideSwap reported approximately 4,270.54 BTC held against the same amount of LBTC in circulation.
  • The restoration followed the September 6 exploit and reserve contributions that included 300 BTC and 250 BTC on November 2.
  • SideSwap had reopened its own peg out service, but direct Federation peg outs had not fully resumed. Reserve backing and withdrawal availability remain separate issues.

Restoring the reserve closes one immediate solvency gap, but it does not restore every withdrawal route. Users and trading firms still need to check liquidity, redemption channels and governance controls. The unresolved commercial issue is how a federated bitcoin product earns back confidence after a reserve failure.

Hong Kong Moves Tokenized Bank Settlement to 24/7

November 2, 2026, Hong Kong
  • HKMA advanced EnsembleTX to support 24/7 interbank settlement of tokenized deposit transactions using tokenized central bank money, removing the conventional operating hour constraint from the settlement leg.
  • The pilot now includes 12 tokenized deposit banks and 20 other industry participants testing real value transactions across treasury and tokenized asset use cases.
  • EnsembleTX remains a controlled pilot. HKMA has not published transaction volumes or opened the infrastructure as a general market service.

Always available tokenized assets need an equally available cash leg. Hong Kong has connected both sides inside a regulated pilot, which makes settlement hours less of a constraint on treasury and tokenized fund activity. The commercial test is volume, participant growth and movement from pilot access toward production use in tokenized collateral and cash settlement.

Ireland Creates Dedicated Tokenization Access Point

November 2, 2026, Ireland
  • Central Bank of Ireland published its feedback on distributed ledger technology and tokenization and said it will expand its Innovation Hub with a dedicated Tokenisation Access Point.
  • The central bank will also use policy sprints to engage firms on emerging regulatory issues, with tokenization a particular focus over the coming months.
  • Its priorities include central bank money settlement, tokenized collateral, legal and regulatory clarity, common standards and links to Eurosystem initiatives including Pontes and Appia.

Ireland is giving tokenization firms a more direct route into regulatory engagement while the supporting settlement and legal framework is still being built. That can surface custody, asset servicing and interoperability issues before firms scale them. The opportunity is shifting from issuance toward the regulated infrastructure around tokenized real world assets.

HKMA Opens tConnect Launchpad for Tokenization

November 2, 2026, Hong Kong
  • HKMA and Cyberport launched tConnect Launchpad to connect financial institutions, technology providers and digital asset firms around tokenization projects.
  • The initiative aims to develop and test new uses of tokenized financial infrastructure, extending participation beyond the banks already active in HKMA programs.
  • The launchpad is a collaboration and validation route. It is separate from EnsembleTX’s 24/7 tokenized deposit settlement pilot.

Tokenization firms need ways to reach regulated bank partners before they can prove demand. tConnect creates another entry point to test that fit. The useful measure will be projects that progress from collaboration into funded deployments, not how many firms attend.

THORChain Halts Swaps After Reported 10 ETH Error

October 31, 2026, Global
  • THORChain’s official community update described a global network pause following a reported 10 ETH double spend during the October 31 period.
  • The presenter said the cause was not yet known and might relate to a large outbound queue. This was a working theory, not a confirmed root cause.
  • Developers were expected to investigate before normal swaps resumed. The community update did not establish a completed remediation or verified loss total.

The pause is a direct operating interruption for traders and liquidity providers relying on cross chain swaps. Those users need current chain status, outbound queue visibility and clear incident reports. An unexplained refund error also raises questions about how the protocol handles exceptional transactions under load.

Digital Banking And BaaS

Budget Proposes Raising CDIC Deposit Protection to $250,000

November 5, 2026, Canada
  • Budget 2026 proposes increasing eligible Canada Deposit Insurance Corporation coverage from $100,000 to $250,000 per applicable insurance category.
  • Other proposals include temporary extra protection following qualifying life events such as a home sale and removing the cap for eligible deposits held in registered and tax free accounts.
  • The government also proposes periodic framework reviews and changes to CDIC membership conditions. Existing deposit insurance limits still apply until legislation takes effect.

Higher deposit protection could make customers more comfortable keeping larger balances at smaller federally insured banks. That affects a bank's funding cost and its ability to compete for savings. The proposed changes could help challengers, but firms must explain the current coverage accurately until Parliament changes the law. Smaller banks may benefit most if stronger insurance coverage helps them compete for deposits.

Budget Proposes One Year Bank Licence Decisions and Easier Challenger Ownership

November 5, 2026, Canada
  • Budget 2026 proposes a one year statutory decision limit for applications to enter the federal financial institution framework, aimed at giving prospective entrants more predictable review timelines.
  • The government would raise the bank equity threshold triggering widely held ownership requirements from $12 billion to $25 billion and ease specified rules for certain foreign bank subsidiaries below $8 billion in equity.
  • Other proposals would support qualifying federal credit union investment structures and give solvent institutions more options to transfer assets and liabilities. The changes need legislation.

Getting a banking licence is expensive before the first account opens. A clearer decision period could make financing a challenger bank more realistic, while the ownership changes may let growing banks retain strategic investors longer. The details matter. Canada's Budget 2026 financial competition analysis sets out the wider context, but applicants still need to meet prudential standards.

Revolut Begins Banking in New Zealand With NZ$120M Plan

November 3, 2026, New Zealand
  • Revolut registered as a bank in New Zealand and began operating Revolut Bank New Zealand on November 3, supported by a planned NZ$120 million investment over five years.
  • Its initial savings offer includes a 3.50% introductory variable annual rate for eligible new retail customers for four months, with daily interest payments.
  • Eligible deposits are protected up to NZ$100,000 under New Zealand’s Depositor Compensation Scheme. Revolut cites more than 80 million customers globally.

Revolut can now compete on deposits rather than relying only on its existing account and payment products. For incumbent banks, the pressure is immediate on savings pricing and mobile acquisition. For digital challengers, the licence shows how costly and valuable direct deposit capacity can be.

CLICX Selects Vault Core for Thailand Virtual Bank

November 3, 2026, Thailand
  • CLICX selected Thought Machine’s Vault Core as its banking technology platform for its planned virtual bank in Thailand.
  • The venture combines Krungthai Bank, Advanced Info Service and PTT Oil and Retail Business, linking banking with telecom and retail distribution.
  • Thought Machine describes CLICX as the first of Thailand’s new virtual banks to reach operational readiness against the Bank of Thailand’s timetable. Customer launch is a separate milestone.

Thailand’s virtual bank contest is turning into a distribution and core technology test. CLICX brings banking, mobile and physical retail reach together, but readiness alone does not establish account growth. The first customer offers and their economics will tell competitors whether that combination works.

OppFi Withdraws Applications for BNC Bank Acquisition

November 3, 2026, United States
  • OppFi withdrew regulatory applications associated with its proposed acquisition of BNCCORP and BNC National Bank from the OCC, Federal Reserve and FDIC.
  • The company cited limited opportunity to resolve potential regulatory concerns and called for greater clarity around fintech acquisitions of community banks.
  • OppFi maintained its full year 2026 outlook of $600 million to $610 million in revenue and $115 million to $120 million in adjusted net income.

Buying a bank can give a lending platform more direct control of funding and products, but the approval process can disrupt the whole plan. OppFi’s withdrawal puts a price on regulatory uncertainty. Other fintech acquirers need credible alternatives while approval remains unresolved.

Digital Identity And Trust

Fourthline and Veridas Complete Bank Identity Merger

November 3, 2026, Netherlands and Spain
  • Fourthline and Veridas closed their merger on November 3, combining identity verification, biometrics, fraud controls and compliance technology across more than 50 countries.
  • The combined group expects roughly 200 million identity checks in 2026 and more than €50 million in revenue. These are company projections, not confirmed full year results.
  • The financing package includes up to €65 million from equity and debt sources. Existing customer products and integrations remain in operation while the firms integrate.

Banks now face a larger identity vendor combining onboarding, biometrics and fraud controls. That may reduce integration work, but a bigger provider can also command more pricing power. Buyers should compare approval accuracy, portability and contract terms before consolidating suppliers. The projected 200 million checks are useful scale context, not proof that the merger has improved results.

Insurance And Insurtech

Amdocs Acquires EIS Insurance Software for About $340M

November 3, 2026, United States
  • Amdocs completed its acquisition of insurance software provider EIS for approximately $340 million in cash. Additional payments depend on performance.
  • EIS provides core software for policy administration, billing, claims and customer engagement and serves insurers including Allstate, Aflac and Desjardins.
  • Amdocs plans to extend its aOS agentic operating system into insurance, but the announcement does not establish finished customer deployments of the combined offering.

Amdocs has bought its way into the systems insurers use to administer policies, bill customers and settle claims. For EIS clients, the first questions are service continuity and integration cost. For competing vendors, the threat is a supplier that can combine core software with enterprise AI services. Actual insurer deployments will determine whether that combination pays off.

Singapore Plans US$200M Data Centre Insurance Facility

November 2, 2026, Singapore
  • Singapore announced an industry collaboration to develop a specialist data centre insurance facility with US$200 million in initial planned underwriting capacity.
  • MSIG, Gallagher Re, SCOR, Samsung Re and the Cybersecurity Association Singapore are among the participants. A memorandum of understanding was expected during the week.
  • The proposed facility targets construction, operating, supply chain, design and cyber risks. Its operating launch and final coverage terms were not announced.

Data centre builders need insurance that spans power, construction, equipment and cyber exposures rather than isolated policies. Pooling underwriting capacity could make larger projects easier to finance, especially as AI raises infrastructure demand. The test is whether the facility offers useful terms and capacity once it opens.

Lending Consumer Credit And BNPL

FCA Sets Expectations for Early Motor Finance Settlements

November 3, 2026, United Kingdom
  • The FCA published expectations for lenders choosing to make settlement offers on motor finance complaints during the partial suspension of the motor finance redress scheme.
  • The FCA expects clear settlement letters and an offer worth no less than the maximum redress due under the scheme methodology, including applicable adjustments and caps.
  • The guidance addresses voluntary early settlement offers. Firms are not required to make offers, and an accepted full settlement may ordinarily withdraw the related complaint.

Motor finance lenders can settle some claims before the wider redress process ends, but an early offer has to stand up to scrutiny. A poorly explained calculation can create another dispute. Firms should keep a clear record of the amount offered, the customer’s options and the effect on any open complaint. Faster resolution only helps when customers can understand the terms.

Open Banking Open Finance And Data Sharing

Bank of Canada Opens Accreditation Consultation

November 2, 2026, Canada
  • The Bank of Canada opened its first consultation on draft supervisory guidelines for accreditation under Canada’s consumer directed banking program.
  • The draft is the first of a planned series of guidelines and addresses practical expectations for prospective participants under Canada’s consumer directed banking rules.
  • Feedback on clarity, practicality, completeness and implementation is due December 8, 2026.

Accreditation is moving from legislation toward the application work firms must actually complete. Fintech applicants should test the proposed evidence requirements against their operating models now. The deadline is a chance to resolve costly ambiguity before onboarding and compliance processes become fixed.

Payments Infrastructure And Money Movement

Canada Confirms Real Time Rail Launch for November 9

November 5, 2026, Canada
  • Payments Canada confirmed on November 5 that the Real Time Rail is scheduled to launch November 9, 2026, after years of development and testing.
  • The system is designed for instant, data rich payments with clearing and settlement available 24 hours a day, every day among connected participants.
  • The rollout is phased. Initial access and payment volumes depend on participant certification, readiness and migration schedules; the November 9 date does not mean every Canadian bank or fintech can send RTR payments immediately.

The date finally gives payment teams a launch milestone they can plan around. For merchants and treasury operators, the value comes when their providers actually enable funds to arrive in seconds. Access still depends on testing, settlement arrangements and participant readiness. NCFA's RTR access rules guide shows why a system launch does not give every provider immediate access.

Pliant Opens Business Payment Controls to AI Agents

November 4, 2026, Germany, Canada and Global
  • Pliant raised $80 million in Series C funding on November 4 and says authorized third party AI agents can connect to its B2B payment infrastructure through Model Context Protocol (MCP).
  • The company reported exceeding $100 million in annual recurring revenue after three consecutive years of doubling its business. It processes billions of dollars in annual business payment volume.
  • Pliant is expanding in the United States and Canada. Its agent infrastructure can support finance workflows, but the announcement does not report autonomous payment volumes or independently audited agent outcomes.

Pliant is making corporate payment infrastructure accessible to software agents, not just staff clicking through expense screens. That creates demand for clear limits, approvals and records of who authorized each instruction. Canadian firms already face these AI agent payment authority questions. The $80 million round funds expansion, while transaction controls and customer adoption will determine the product's value.

European Payments Council Updates Payee Name Matching Rules

November 3, 2026, European Union
  • The European Payments Council published version 2.0 of its Verification of Payee matching recommendations on November 3 following its 2026 scheme rulebook consultation.
  • The new guidance clarifies the character set used in payee name matching and how responding payment service providers determine match outcomes.
  • The recommendations support implementation of the existing Verification of Payee scheme. They are not a separate new payment system or a new statutory mandate.

A recipient name that differs slightly from the bank's record can interrupt a legitimate payment or confuse a sender. Consistent matching gives banks a better chance to handle those cases without weakening fraud checks. PSPs should test character handling and near matches against real customer records, then measure false warnings and stopped payments. The rules work only when the customer experience is clear.

Ebury and Form3 Plan Canadian Real Time Rail Connectivity

November 3, 2026, Canada and United Kingdom
  • Ebury selected Form3 to support its planned connection to Canada’s Real Time Rail, extending their existing relationship across UK Faster Payments and European SEPA infrastructure.
  • Form3 expects Ebury to join during the 2027 participation stages. Canada’s RTR is undergoing phased deployment, with an initial launch scheduled for the fourth quarter of 2026.
  • Form3 reports processing 5 billion transactions a year for more than 40 customers. The Ebury announcement does not establish that its Canadian RTR payments are already live.

Ebury is preparing to sell instant Canadian payments through infrastructure it already uses abroad. That may shorten integration work, but customers cannot use an announcement to settle funds. The next milestones are access and testing under Canada’s RTR rules, followed by actual payment availability. Corporate clients should watch those dates before changing treasury processes.

Sunrate Gives Authorized AI Agents Commercial Cards

November 2, 2026, Hong Kong and Global
  • Sunrate launched a programmable multicurrency virtual commercial card that lets authorized AI agents create and manage payment instruments, initiate transactions and retrieve payment outcomes.
  • Businesses retain control through predefined authorization rules and spending policies. Sunrate says the card is designed to keep agent initiated payments inside auditable business controls.
  • Sunrate completed Mastercard Agent Pay certification and is connecting the card to a broader set of payment, foreign exchange, compliance, onboarding and conversational agents inside Sunrate.AI.

The shift is from an AI assistant recommending a payment to software executing one under delegated authority. That turns spending limits, identity, revocation and transaction logs into core payment infrastructure. The same control questions are emerging across AI agent financial authorization and security.

Unlimit Goes Live at The Souled Store in India

November 2, 2026, India
  • The Souled Store deployed Unlimit payment acceptance across its website and mobile app, giving the fintech a live retail implementation rather than a future partnership announcement.
  • The integration supports UPI, net banking, credit cards and debit cards and is designed for traffic spikes around limited releases, product drops and seasonal sales.
  • Unlimit says its infrastructure supported payment acceptance during The Souled Store's recent Spider Man collection launch. The companies did not publish transaction volume, conversion uplift or payment success rates.

Peak demand is where payment infrastructure becomes visible to a merchant. A provider that keeps checkout working during short bursts of traffic can directly influence completed sales, but the useful benchmark is measured performance rather than the integration itself. Transaction success, latency, conversion and processing economics will show whether the deployment strengthens Unlimit's position in India's competitive payments market.

OKX Launches US Mastercard Card Backed by Stablecoins

November 2, 2026, United States
  • OKX launched a virtual Mastercard payment card for eligible US customers, issued through WebBank and backed by USDC, USDT and USDG held in OKX Pay.
  • Users can add the card to Apple Pay or Google Pay. OKX advertises zero transaction and foreign exchange fees on purchases, with rewards subject to limits and eligibility.
  • The product is not available in every US state and merchant acceptance does not establish universal account eligibility. The company has not disclosed card payment volume.

OKX has given eligible US stablecoin holders a spending option without a separate manual cashout. The question is how the product handles conversion costs, availability and rewards once customers use it regularly. For payment firms, this adds another live case to the stablecoin card settlement market. It is not a Canadian card launch.

Regulation And Policy

Canada Introduces Bill S-8 With New MSB and Crypto ATM Controls

November 3, 2026, Canada
  • Finance Canada introduced Bill S-8 on November 3. It would strengthen registration checks for money services businesses and expand FINTRAC’s authority to refuse or revoke registrations.
  • The bill would restrict unlawful crypto ATMs, cash transactions of $10,000 or more and certain third party cash deposits. It would also allow regulated businesses to use financial crime information disclosed by law enforcement.
  • These are proposed changes, not current obligations. The government has introduced the bill, but Parliament has not enacted these measures.

Bill S-8 would make registration harder for risky money services businesses and change how financial crime intelligence reaches regulated firms. Crypto ATM operators should review the proposed restrictions against their current licences and locations. Payment firms should examine what new information FINTRAC could demand. NCFA’s crypto ATM money laundering guidance offers background, but the bill is not yet law.

SEC Updates Crypto Guidance on Securities Tests

November 2, 2026, United States
  • The SEC Division of Corporation Finance updated its staff FAQs on crypto assets on November 2, building on the September guidance and the March interpretive release.
  • The FAQs address classification and transactions involving crypto assets, including functional systems, decentralization and securities analysis.
  • The SEC explicitly states that these are staff views, not Commission rules, and that they do not create new legal obligations.

Crypto issuers and counsel now have more specific staff language to test against token design and disclosures. The guidance can narrow unanswered questions, but it is not legal immunity. Businesses should track which interpretations affect their product structures without presenting staff FAQs as binding law.

MAS Offers S$30M Grant and Proposes Insurer Capital Relief

November 2, 2026, Singapore
  • MAS launched a S$30 million grant to help insurers build teams and expertise for infrastructure investing. The grant took effect November 2.
  • MAS also proposed lower capital charges for qualifying infrastructure debt, certain protected infrastructure investments and senior securitization tranches.
  • Comments on the proposed insurance capital changes are due December 18, 2026. The capital treatment is not yet final.

Singapore is attacking two barriers to insurance capital reaching infrastructure deals, expertise and capital cost. Insurers can assess the grant immediately, while asset managers should examine whether the proposed risk criteria fit the deals they can originate. The consultation could alter financing demand across infrastructure and securitized assets.

OSFI Cryptoasset Capital Guideline Takes Effect

November 1, 2026, Canada
  • OSFI's 2027 cryptoasset capital and liquidity guideline took effect November 1 for federally regulated institutions with an October 31 fiscal year end. Institutions with a December 31 year end move to the guideline on January 1, 2027.
  • The final treatment excludes qualifying client clearing exposures from the Group 2 exposure limit, reducing the prudential burden on banks providing eligible clearing services.
  • OSFI also recognizes matching positions in the same Group 2a cryptoasset across regulated exchanges for capital purposes, while existing limits remain for other forms of hedging.

The implementation date turns the September rulebook into a balance sheet decision for affected banks. Clearing, custody, trading and financing teams can now price eligible activity against the final treatment. The distinction between tokenized deposits and crypto exposures remains important under Canada's OSFI 2027 crypto rules.

Risk Compliance And Regtech

OCC Gives Bank Examiners a Super Intelligence Review Guide

November 4, 2026, United States
  • The OCC published an examiner guide on November 4 for reviewing banks’ use of super intelligence and autonomous AI in ordinary operations.
  • The guide covers existing governance, model risk, technology and operational risk practices. It directs examiners to tailor scrutiny to the consequences, autonomy and oversight of each use case.
  • The OCC expressly says the guide creates no new bank requirements, enforceable standards or supervisory expectations. Banks are not required to adopt a separate super intelligence risk category.

Banks don’t have a new AI rule to implement here. They do have a clearer view of the questions examiners may ask about consequential automated decisions. Can staff stop an agent? Who approved its authority? Can the bank explain a failure? Those are practical tests of AI agent authorization controls, even though the OCC guide imposes no new standards.

Honey Badger Puts Live Fraud Workflows in Risk Teams' Hands

November 2, 2026, United States
  • Honey Badger launched Risk Playbooks, a visual builder that lets fraud and risk teams combine signals from more than 150 data feeds, set rules and scoring, and publish the workflow through a single live API.
  • The product is available now and is already being used by fintech, lending and payments businesses. Honey Badger says customers have reduced build and deployment time by about 90%, a company reported figure.
  • Risk teams can update live controls without waiting for engineering releases, while an optional feedback loop can use confirmed outcomes to recommend changes to scorecards.

Moving fraud logic from engineering queues into the risk function can shorten the time between a new attack pattern and a production control. It also makes governance more important because rule changes can affect onboarding, approvals and declines immediately. The product will be more valuable if customers can show faster response without increasing false positives, exceptions or unexplained automated decisions.

FCA Documents AI and Control Failures at Wholesale Banks

November 2, 2026, United Kingdom
  • The FCA found a coding defect that stopped data from reaching a financial crime control for an extended period, with the gap discovered through unrelated activity rather than completeness monitoring.
  • An algorithm change produced an unintended large intraday position after testing failed to model near simultaneous fills in different locations and the order management component reported executed quantity incorrectly.
  • The regulator also cited inaccurate AI generated code that contributed to a service outage, unapproved AI use that exposed sensitive information, incomplete AI inventories and weak controls around approvals and kill switches.

The FCA is giving firms failure patterns they can test against now. Data lineage, change testing, AI inventories, conditional approvals and kill switch ownership all become concrete control questions rather than abstract governance principles. Similar issues are emerging across AI, programmable finance and financial crime regulation.

SME Finance And Business Banking

Liberis and Qred Complete Merger Combining Bank and Embedded SME Lending

November 2, 2026, United Kingdom and Sweden
  • Liberis and Qred completed their merger after approval from Sweden’s financial supervisor, combining Qred’s regulated banking model with Liberis’s lending distribution through platform partners.
  • The group serves more than 60,000 small businesses in 17 countries and reports access to about 11.5 million potential merchant customers.
  • Both brands and existing integrations continue for now. Product integration and expansion plans remain future work.

The merger puts regulated bank funding and embedded business lending under one owner. Liberis gains another way to fund offers delivered through its partners. Qred gains wider merchant distribution. Small businesses will judge the combination on approval times, price and repayment flexibility. Reach across 17 countries is valuable only if the lending economics hold up.

Sustainable Finance ESG And Financial Inclusion

FCA Sets June 2027 ESG Ratings Authorization Window

November 3, 2026, United Kingdom
  • The FCA finalized its first regulatory regime for ESG ratings providers, covering transparency, governance, systems, controls, conflicts of interest and engagement with rating users and rated entities.
  • Providers can begin applying for authorization on June 24, 2027. The regime takes effect on June 29, 2028, subject to applicable exemptions.
  • The FCA regulates how ratings are produced and communicated. It does not prescribe a particular sustainability score or methodology.

ESG ratings providers now have deadlines, not just broad calls for better disclosure. Firms selling ratings in the UK should review their conflicts controls, methodologies and customer explanations ahead of the June 2027 application window. Asset managers have work too. They need to know whether the ratings suppliers embedded in their products can meet the new standards before June 2028.

Treasury Liquidity And Cash Management

HashKey Uses Standard Chartered Tokenized Bank Deposits

November 3, 2026, Hong Kong
  • HashKey adopted Standard Chartered’s institutional tokenized deposit service for treasury management and settlement activity.
  • The service represents commercial bank deposits on Standard Chartered’s blockchain infrastructure, keeping them within an approved banking environment.
  • HashKey identifies faster transfers and extended availability for institutional treasury and liquidity across markets. Transaction volumes have not been disclosed.

Tokenized deposits are becoming a treasury product for actual institutional customers, not just a bank demonstration. The commercial value rests on when money can move, how much liquidity must sit idle and what treasury systems can connect. Measured customer flows are the next test.

HKEX Accepts RMB Government Bonds as Derivatives Margin

November 2, 2026, Hong Kong
  • HKEX clearing houses HKCC and SEOCH began accepting eligible Chinese government and policy bank bonds through Bond Connect, along with offshore Ministry of Finance bonds, as noncash margin collateral.
  • Seven institutions posted more than RMB 400 million of eligible bonds on the first operating day.
  • The new eligibility lets participants meet listed derivatives margin requirements without first selling eligible bonds or converting them to cash.

Clearing members can now use certain RMB bonds as margin instead of tying up as much cash. **More than RMB 400 million posted on day one** gives this a stronger operating basis than a policy proposal. The saving will depend on haircuts, custody charges and funding costs. Banks should measure the cash released, not just the amount of collateral accepted.

Wealthtech Investing And Trading

Wealthsimple Plans CADD Stablecoin Rewards at 3.25%

November 5, 2026, Canada
  • Wealthsimple announced plans to let eligible customers hold CADD, a Canadian dollar stablecoin issued by a regulated financial institution, inside its platform by the end of 2026.
  • It is advertising a 3.25% annual reward on eligible CADD holdings. The announced product was not yet available to Wealthsimple clients on November 5.
  • CADD is designed for 1:1 redemption in Canadian dollars. The product’s reward structure, eligibility and risk disclosures will need scrutiny when Wealthsimple opens access.

Wealthsimple could bring Canadian dollar digital assets to customers who would never open a crypto wallet themselves. CADD already exists, so this is a new distribution and reward announcement, not the launch of the stablecoin itself. NCFA covered CADD's original regulated issuance in May. The next test is how many clients use it for payments or cash management rather than simply collecting rewards.

Wealthsimple Adds Free Canadian Options and Faster Trades

November 5, 2026, Canada
  • Wealthsimple launched commission free options trading on Canadian stocks and direct indexing within existing accounts on November 5.
  • The company says its faster trading experience is available now, reducing a mobile trade from eight steps and 21 seconds to two steps and four seconds. Order execution can be up to six times faster, according to Wealthsimple.
  • Wealthsimple Pro is planned for the end of 2026, while retail perpetual futures on crypto, metals and indices are planned for late November. They were not announced as available on November 5.

Zero commission Canadian options put more pressure on trading fees, while faster order entry makes a difference for active clients. Direct indexing adds a tax planning product within accounts investors already use. The bigger competitive test is whether Wealthsimple can serve frequent traders without higher spreads or weaker execution. Its planned perpetual futures also bring suitability and leverage questions that matter as much as headline pricing.

Capital.com Receives Singapore Licence Ahead of 2027 Launch

November 2, 2026, Singapore
  • Capital Com Securities (Singapore) received a Monetary Authority of Singapore capital markets services licence for securities and over the counter derivatives dealing.
  • This is Capital.com’s first licensed market in Southeast Asia. The company plans to begin onboarding clients in early 2027.
  • The company plans local identity verification through Singpass MyInfo and two factor authentication. A licence does not mean the trading service has already opened to Singapore customers.

Capital.com has permission to enter Singapore, but it still needs customers. The company plans to begin onboarding in 2027, so local brokers have time to prepare. Investors should compare the instruments, trading costs and safeguards actually offered at launch. Regulatory approval opens the market; it does not establish customer traction.

Weekly Close

Canada’s RTR launch, proposed banking reforms and new digital asset rules make this a consequential week for financial innovation. Globally, firms are putting AI, tokenization and new payment infrastructure into practical use. For Canadian fintechs, the opportunity is in execution. Clearer rules, better access and products that solve real customer problems will determine who can compete and grow.

NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech news and insights, industry research, or launch into emerging financial innovation opportunities.


NCFA Canada logoThe National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

Why Canada Keeps Tightening Its AML Rules

November 5, 2026 | NCFA Story Intelligence | Risk Compliance And Regtech, Regulation And Policy, Digital Assets Blockchain And Tokenization
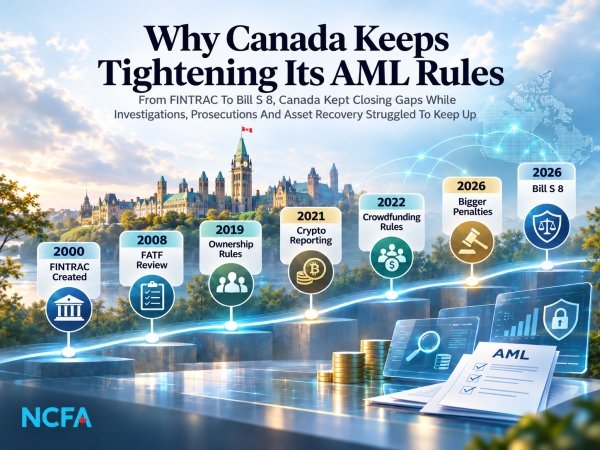
AI illustration of NCFA Story about Canada AML rules timeline showing FINTRAC, FATF reviews, beneficial ownership, crypto reporting, crowdfunding rules, penalties and Bill S-8.

Canada keeps closing financial crime gaps, but investigations, prosecutions and asset recovery still have to catch up with the much larger system

Canada added another layer to its anti money laundering system on November 3, 2026.

Bill S-8 would tighten registration for money services businesses, give FINTRAC more grounds to refuse or revoke registrations, add controls for crypto ATMs, restrict some large cash transactions and third party cash deposits, and let regulated firms receive more financial crime information from government and law enforcement.

Five days earlier, the Auditor General had delivered a very different AML announcement.

FINTRAC was taking nearly 4 months on average to provide requested financial intelligence. Half of the recipients surveyed said information sometimes arrived too late to help an active investigation.

A month before that, FATF had praised parts of Canada's system while still calling for stronger supervision, more complex money laundering prosecutions and better asset recovery.

Canada isn't short of rules.

It has spent more than 25 years adding them.

This is a story of Canada closing one financial crime gap after another, only to find that more reports and tougher rules don't automatically produce faster investigations, prosecutions or recovered money.

The 2022 truck convoy became one of the most visible turns in that story.

It wasn't the beginning.

FINTRAC Is Born and the Boundary Starts Moving 2000 to 2008

Canada's modern AML system begins in 2000. Parliament creates FINTRAC and requires suspicious transaction reporting and reporting of certain large movements of money. After the September 11 attacks, terrorist financing is added to the mandate. By 2006, Ottawa is already widening the system again with MSB registration, administrative penalties and broader compliance duties. FINTRAC is still young, but money is already finding routes the first rulebook didn't fully cover.

How Canada's AML System Started

FINTRAC's institutional history traces the current system to legislation passed in 2000.

FINTRAC began receiving suspicious transaction reports and voluntary information in 2001. Terrorist financing was added after the Anti Terrorism Act.

Changes passed in 2006 introduced the MSB registration regime and gave FINTRAC authority to impose administrative monetary penalties. Registration came into force in 2008.

Canada starts expanding the system almost as soon as it builds it.

Banks and other reporting firms now have to tell FINTRAC when money looks suspicious. Investigators gain a national source of financial intelligence that didn't exist before, and regulated firms can no longer treat unusual transactions as someone else's problem.

But criminals aren't limited to bank accounts. Money can pass through companies, intermediaries, cash businesses, real estate and foreign accounts. The first rulebook catches more activity, and the routes around it become easier to see.

The First FATF Review Finds the Holes 2008 to 2016

FATF's 2008 review gives Canada's young system its first major international stress test. Ottawa gets credit for substantial reforms, but FATF still finds weaknesses in customer checks, supervision, beneficial ownership and FINTRAC's effectiveness. Canada spends the following years tightening many of those areas. By 2014, FATF removes Canada from regular follow up. Two years later, the next full review finds that some of the hardest problems weren't gone. They had moved deeper into the ownership and professional structures around the transaction.

What FATF Kept Finding

The 2008 FATF evaluation called for stronger customer checks, more consistent supervision and better beneficial ownership information.

The 2016 evaluation found substantial progress but continued exposure through legal professionals and opaque companies and legal arrangements.

Lawyers couldn't simply be folded back into the same FINTRAC model either. A 2015 Supreme Court decision found that applying parts of the federal regime to legal counsel violated constitutional protections.

The financial system was becoming easier to monitor. Some of the people behind the money were still difficult to see.

Customer checks get stronger. MSBs register. FINTRAC gains penalties and more supervisory reach. A regulated firm has fewer excuses for not knowing who opened the account or sent the money.

Then investigators reach the company behind the transaction and can hit another wall. The account holder may be visible while the person controlling the corporation isn't. The search moves from the customer to the owner.

Canada Starts Naming the People Behind the Companies 2017 to 2019

Federal, provincial and territorial governments agree to improve beneficial ownership records and eliminate bearer shares. From June 2019, most federal corporations have to keep information on individuals with significant control. A numbered company can still stand between suspicious money and its owner, but investigators now have another record to pull when they start taking the structure apart.

Ownership Records Get Stronger Again

The first federal requirement kept ownership information at the corporation.

That changes again in 2024. Most federal corporations must file information about individuals with significant control with Corporations Canada, and some of that information becomes publicly searchable.

It still isn't a complete Canadian system. Provincial and territorial corporate law means ownership information remains spread across jurisdictions.

FATF is still calling for progress toward a pan Canadian beneficial ownership system in 2026.

A shell company becomes less useful when investigators can identify the people with significant control. The ownership trail gets shorter, and legitimate companies get clearer record keeping duties.

The trail can still cross provincial registries, trusts and foreign entities. And while Canada is looking deeper into ownership, another way of moving value is growing outside the familiar bank payment path. The next gap starts with the money itself.

Crypto Opens Another Route for Value to Move 2020 to 2021

Virtual currency dealers and foreign MSBs serving Canadians come under FINTRAC requirements in 2020. Large virtual currency transaction reporting follows in 2021. Crypto is no longer treated as a separate financial world. If a business exchanges or transfers virtual currency for Canadians, the same questions about identity, source of funds and suspicious activity follow it there.

Crypto exchanges and payment firms now have to build registration, identity checks, records and reporting into products designed to move value quickly. Legitimate operators gain a clearer path into the Canadian market, but compliance becomes part of the product itself.

Bringing crypto inside FINTRAC doesn't cover every new way Canadians can collect or move money. A year later, crowdfunding and payment platforms show where the boundary still ends. The next expansion arrives in the middle of a national crisis.

The Convoy Turns a Gap Into Permanent Rules February to April 2022

The truck convoy makes another gap visible in real time. Ottawa invokes the Emergencies Act in February and temporarily brings crowdfunding platforms and certain payment providers under AML obligations. The emergency ends. The coverage gap doesn't. Two months later, Canada makes the change part of the ordinary system.

What Became Permanent

On April 27, 2022, new regulations permanently brought crowdfunding platforms and certain payment providers under FINTRAC as MSBs or foreign MSBs.

Registration, compliance programs, identity checks, record keeping and transaction reporting followed.

The federal explanation explicitly linked the change to crowdfunding and payment risks highlighted by the blockades.

The permanent rules also drew an immediate industry challenge over their scope, lack of consultation and compliance costs.

The convoy didn't start Canada's AML expansion. It exposed one channel the existing system hadn't fully captured.

Ottawa closes the gap quickly. Crowdfunding and payment firms that had built businesses outside traditional banking inherit FINTRAC registration, identity checks and reporting. The line around the regulated market moves again.

Legitimate platforms pay for the same controls. Staff, systems, records and audits become part of the cost of staying in business. The government closes one blind spot and pushes compliance deeper into smaller financial firms.

The Net Spreads Across More of Finance 2023 to 2025

The next expansion isn't built around one crisis. Mortgage businesses come under FINTRAC in 2024. Armoured car companies follow. In 2025, cheque cashers, factors, financing and leasing firms, title insurers and businesses serving private ATMs join them. Private information sharing between reporting entities also gets a legal route. By 2025, more than 38,000 businesses are inside FINTRAC's supervisory reach.

Why So Many More Businesses Are Now Inside

Canada's 2025 National Risk Assessment identifies vulnerabilities across payment providers, mortgage businesses, crypto assets, crowdfunding, real estate, MSBs and other sectors.

It also says criminals can exploit information gaps between reporting firms. Since March 2025, regulated entities can voluntarily share some personal information under approved codes of practice to detect money laundering, terrorist financing and sanctions evasion.

The system becomes less dependent on one firm spotting one suspicious transaction in isolation.

More businesses are now expected to recognize the same money from different sides.

A suspicious account at one institution can become more useful when another firm recognizes the same owner, wallet or transfer pattern. Activity that once ended inside separate compliance teams can start connecting across institutions.

That gives firms another job. They need controls around what can be shared, why it can be shared and who gets access. Canada gains more intelligence, while compliance becomes a bigger part of running the business.

FINTRAC Starts Throwing Firms Out 2025 to 2026

Then enforcement gets much harder to ignore. FINTRAC issued 6 notices of violation worth about $1 million in 2022 to 2023. In 2025 to 2026, it issued 35 notices worth more than $247 million. It also revoked 82 MSB registrations in one year, up from 12 the year before. A payments, FX, remittance or crypto firm can no longer treat registration as something it secures once and files away.

The Price of Non Compliance Jumps

By May 2026, revocations were cutting across money transfer, FX, virtual currency and PSP businesses, including firms operating across several categories at once.

FINTRAC's 2025 to 2026 annual report confirms 82 MSB revocations and more than $247 million in notices of violation.

The escalation was already visible in Cryptomus's record penalty. FINTRAC imposed about $176 million after finding failures that included suspicious transaction and large virtual currency reporting.

Weak compliance can now threaten the economics of the company itself.

A strong operator can benefit when firms that ignore reporting duties or regulator requests lose market access. Banks and partners have more reason to trust an MSB that stays registered and responds when FINTRAC calls.

But the price of proving that compliance is uneven. Large institutions spread legal, data and monitoring costs across millions of customers. A startup can't. The regulator starts removing weaker operators just as the cost of being a strong one keeps rising.

Bill C-12 Makes Compliance Failures Much More Expensive March 26, 2026

Parliament gives FINTRAC much stronger enforcement tools. Maximum penalties rise sharply. Compliance orders become public. An entity that doesn't comply with an order can face a penalty of up to the greater of $30 million or 3% of global revenue. Ottawa can now hit weak controls much harder without waiting for police to prove a money laundering offence.

How Much Larger the Penalties Became

Bill C-12 received Royal Assent on March 26, 2026.

For prescribed violations, an entity can face a maximum penalty of $20 million. Aggregate maximums can also be tied to 3% of global revenue.

FINTRAC says the legislation increased some penalty limits by as much as 40 times.

A compliance failure can reach the boardroom long before it reaches a criminal courtroom.

FINTRAC no longer has to wait for a criminal case to hit a company hard. It can order fixes, impose much larger penalties and put compliance failures into public view. For regulated firms, the cost of weak controls can arrive long before police lay a charge.

But the money laundering case still has to be built somewhere else. Police need evidence, prosecutors need a case they can prove and assets have to be found before they disappear. Canada has made it faster to punish weak compliance. Catching and recovering the criminal money is still the slower job.

Ottawa Builds a New Agency for the Part FINTRAC Can't Do April 2026

A month later, Ottawa goes after that slower part. Bill C-29 proposes a Financial Crimes Agency to investigate serious and complex financial crime and help recover criminal proceeds. FINTRAC can find patterns and send intelligence. The new agency is meant to pick up the trail from there.

What the New Agency Is Supposed to Do

Bill C-29 was introduced April 27, 2026 and is now being considered by a House committee. The agency isn't operational yet.

The 2026 economic update put $352.7 million over five years and $82.1 million annually thereafter behind the proposed agency, alongside additional funding for specialized prosecutors and Finance Canada.

Its planned workforce includes police and civilian investigators, financial intelligence specialists and asset recovery experts.

Collecting more financial intelligence hasn't produced enough complex cases or recovered money on its own.

FINTRAC can connect reports across institutions and point investigators toward suspicious money. It can tell police where accounts connect and which transactions deserve another look.

Police still have to identify the people, gather admissible evidence and find the assets before they move again. Ottawa is creating another institution because financial intelligence doesn't arrest anyone or recover a dollar by itself.

Two Reviews Show Where the Money Is Still Escaping September to October 2026

By fall, Canada gets two report cards within a month. FATF finds a much stronger system with high quality financial intelligence, but still calls for better supervision, more complex money laundering prosecutions, stronger beneficial ownership coverage and more asset recovery. The Auditor General follows with a problem investigators can feel immediately. Useful intelligence isn't useful enough when it arrives months after police ask for it.

Good Intelligence Can Still Arrive Too Late

The 2026 FATF evaluation says Canada has a mature understanding of financial crime risk and produces high quality intelligence valued by law enforcement.

FINTRAC says FATF found its intelligence was used in 94% of the money laundering and criminal possession investigations reviewed by assessors.

The Auditor General's October 29 audit found that FINTRAC took nearly 4 months on average to provide intelligence when law enforcement flagged a concern.

Half of surveyed recipients said the information sometimes arrived too late to help an ongoing investigation.

The information can be valuable and still lose value while the money keeps moving.

Canada now has more reporting entities, ownership data, penalties, registration controls and financial intelligence than at any earlier point in FINTRAC's history. The reporting side of the system is bigger and harder to ignore.

Investigators still need the information before assets move. Prosecutors still need complex cases they can prove. Governments still need to recover more of the money. Canada has become better at spotting suspicious activity than finishing the journey from report to recovered proceeds.

Bill S-8 Tightens the Perimeter Again November 3, 2026

Five days after the Auditor General's report, Bill S-8 arrives with another set of controls. MSB registration would get tougher. Crypto ATM operators would face more checks and reporting. Some large cash activity would be restricted. Law enforcement could send more information back into regulated firms. Canada is still closing entry points while its newest reviews are pressing the system to do more with the information it already has.

What Bill S-8 Would Change

Bill S-8 is proposed legislation. It isn't law.

The bill would require crypto ATM operators to verify every user's identity, keep transaction records and report each ATM transaction to FINTRAC within 15 days. It would cap a person's transactions at a crypto ATM at $1,000 within 24 hours.

It would prohibit certain third party cash deposits and restrict some cash payments, donations or deposits of $10,000 or more, subject to exemptions and regulations.

It would add new grounds for refusing or revoking MSB registrations, including false or misleading information, and give the Minister of Finance new review and direction powers tied to national security and financial system integrity.

Bill S-8 brings crypto ATM laundering risks back into the centre of the debate after FINTRAC had already documented the use of cash, money mules, private wallets and higher risk exchanges around the machines.

Another gap may close. The pressure on investigators, prosecutors and asset recovery doesn't disappear with it.

Stronger registration can remove operators that lie about their business, ignore regulator requests or raise serious integrity concerns. Legitimate MSBs, payment companies and remittance firms may benefit when weak operators lose access.

Every added check still needs people, systems and legal work. Small firms spread those costs across fewer customers than banks do. Canada can shut bad operators out and still make the door heavier for good ones to open.

The Next Gap Won't Be Fixed by Another Form

Bill S-8 may close more holes around MSB registration, crypto ATMs, cash deposits and financial crime information sharing.

But Canada is reaching the point where adding another reporting obligation produces less value if the rest of the chain can't keep up.

FINTRAC can collect more information.

Banks, fintechs and MSBs can build better controls.

Law enforcement can receive more leads.

None of that helps much if investigators get the intelligence too late, prosecutors can't build enough complex cases or criminal assets are gone before authorities can reach them.

That is where Canada's next AML chapter is heading.

The proposed Financial Crimes Agency could give Ottawa more capacity to investigate serious financial crime and recover proceeds. Bill C-12 gives FINTRAC much stronger leverage over regulated firms. Bill S-8 would tighten who gets into parts of the market and how certain transactions are handled.

Those tools now have to work together.

For fintechs, that creates a different kind of pressure.

The firms that survive stricter registration and supervision may become easier for banks, investors and customers to trust. But every new control also costs money, and smaller operators don't have the same compliance scale as the country's largest financial institutions.

Canada can keep tightening the perimeter.

The bigger question now is whether the system inside that perimeter can move fast enough to catch the money, recover it and still leave room for legitimate firms to compete.

That answer won't come from the next amendment.

It will come from the cases Canada is actually able to finish.

Talking Point

Will Canada's next AML gains come from tougher rules, or from finally turning more financial intelligence into completed cases and recovered assets?

What Happens Next?
  • Will Parliament pass Bill S-8, and which MSB, crypto ATM and cash provisions will survive the legislative process?
  • Can FINTRAC shorten intelligence delays while supervising more than 38,000 reporting businesses?
  • Will the Financial Crimes Agency improve complex investigations, prosecutions and asset recovery once Parliament establishes it?
  • Will larger penalties improve compliance without giving the largest firms an even greater cost advantage?
  • Can federal, provincial and territorial governments close the remaining beneficial ownership gaps?
  • Will wider information sharing help investigators without weakening privacy protections?
What Did You Think?

Has Canada reached the point where better enforcement matters more than another layer of AML rules?

Share this story → Explore related intelligence → Subscribe


NCFA Canada logoThe National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter


NCFA Weekly Fintech Intelligence Oct 24-Oct 30, 2026

Oct 24, 2026 | Last Updated Nov 4, 2026 | NCFA Fintech Whisperer | Regulation And Policy, Capital Markets Infrastructure And Funding, Artificial Intelligence And Data, Cybersecurity Fraud And Financial Crime, Competition And Market Structure, Cross Border Payments And FX, Wealthtech Investing And Trading, Digital Banking And BaaS, Digital Assets Blockchain And Tokenization, Payments Infrastructure And Money Movement, Risk Compliance And Regtech, Sustainable Finance ESG And Financial Inclusion

Fintech market intelligence visualization

Image: Freepik

NCFA Fintech Whisperer tracks weekly fintech market intelligence that changes how financial markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins.

Missed a prior week's Fintech Whisperer? Browse December 6 to 12, 2025, December 13 to 19, 2025, January 1 to 9, 2026, January 10 to 16, 2026, January 17 to 23, 2026, January 24 to 30, 2026, January 31 to February 6, 2026, February 7 to 13, 2026, February 14 to 20, 2026, February 21 to 27, 2026, February 28 to March 6, 2026, March 7 to March 13, 2026, March 14 to March 20, 2026, March 21 to March 27, 2026, March 28 to April 3, 2026, April 4 to 10, 2026, April 11 to 17, 2026, April 18 to 24, 2026, April 25 to May 1, 2026, May 2 to 8, 2026, May 9 to 15, 2026, May 16 to 22, 2026, May 23 to 29, 2026, May 30 to June 5, 2026, June 6 to June 12, 2026, June 13 to June 19, 2026, June 20 to June 26, 2026, June 27 to July 3, 2026, July 4 to July 10, 2026, July 11 to July 17, 2026, July 18 to July 24, 2026, July 25 to July 31, 2026, August 1 to August 7, 2026, August 8 to August 14, 2026, August 15 to August 21, 2026, August 22 to August 28, 2026, August 29 to September 4, 2026, September 5 to September 11, 2026, September 12 to September 18, 2026, September 19 to September 25, 2026, September 26 to October 2, 2026, October 3 to October 9, 2026, October 10 to October 16, 2026, October 17 to October 23, 2026.

Weekly Fintech Market Intelligence Oct 24 to Oct 30, 2026

Regulation And Policy

CIRO Proposes a 60 Day National Complaint Standard

October 29, 2026, Canada
  • CIRO proposed cutting the standard deadline for dealer complaint responses from 90 days to 60 days.
  • Dealers could use up to 30 additional days for complex, exceptional or externally delayed matters, while still completing a fair and documented investigation.
  • The proposal would apply across investment dealers and mutual fund dealers. Comments close January 27, 2027.

A shorter national deadline changes staffing, escalation and evidence requirements for dealer complaint teams. Firms that still rely on manual handoffs will have less room for delay. Compliance vendors also get a clearer design target for case routing, document collection and management reporting.

FCA Forces HTX Out of Active UK Business

October 29, 2026, United Kingdom
  • The FCA secured High Court undertakings that stop HTX from knowingly promoting cryptoasset services unlawfully to UK consumers.
  • HTX is no longer active in the UK. Consumers cannot make new deposits, new UK users cannot register and the exchange cannot target or actively seek UK customers.
  • The settlement follows FCA legal action launched in October 2025 after HTX repeatedly failed to engage over UK financial promotion rules.

The FCA has converted a promotions case into a practical market exit. Offshore location doesn't protect a crypto platform from UK conduct rules when it still reaches UK customers. Exchanges, affiliates and distribution partners need controls that can prove where promotions land and who can still open or fund an account.

Bank of England Opens a Route for Tokenized CCP Collateral

October 29, 2026, United Kingdom
  • The Bank of England opened a consultation on how central counterparties can seek approval to accept tokenized versions of collateral that is already eligible under the proposed UK CCP Rulebook.
  • The draft supervisory statement does not create a separate regime or new collateral requirements. CCPs still have to show that tokenized collateral can be valued, transferred and realized when needed, including during stress.
  • The Bank is also asking whether the same supervisory approach could support future use of tokenized money market fund units, gold and stablecoins. Comments close February 12, 2027.

Tokenized collateral now has a defined supervisory route into central clearing. CCPs can design against that route, but approval will still turn on liquidity, custody, legal certainty and access during stress. That connects directly with NCFA’s work on tokenized assets becoming market infrastructure.

FCA Sets the Economics for UK Consolidated Tape Data

October 29, 2026, United Kingdom
  • The Financial Conduct Authority opened CP26/39 on how the future UK equity consolidated tape provider should share income with firms that contribute market data.
  • The FCA also proposes enhanced operational incident reporting for all consolidated tape providers, extending resilience requirements beyond the commercial terms of the equity tape.
  • The consultation closes December 17, 2026. The FCA plans to confirm the income sharing approach in early 2027 and expects the equity tape to begin operating in 2027 or early 2028.

The UK equity tape now has a clearer business model and a harder resilience test. Trading venues and prospective tape operators need to price income sharing, service continuity and incident reporting together. Data coverage alone won’t win this market.

SEBI and Bank of England Formalize CCP Oversight Cooperation

October 28, 2026, India and United Kingdom
  • SEBI and the Bank of England signed a memorandum covering cooperation and information exchange for clearing corporations recognized by SEBI.
  • The agreement gives the Bank a formal basis to rely on SEBI's regulatory and supervisory work while applying its own responsibility for UK financial stability.
  • The arrangement covers cooperation on central counterparties under each authority's laws and is intended to support international clearing activity across the two jurisdictions.

Cross border clearing works only when supervisors can rely on each other. This agreement gives Indian clearing corporations a clearer route into UK oversight while preserving the Bank of England’s financial stability role. The next test is whether recognition and access become easier in practice.

SFC Publishes Final Guidance for Nov 1 Retail Fund Rules

October 28, 2026, Hong Kong
  • Hong Kong's Securities and Futures Commission published implementation guidance for the revised Code on Unit Trusts and Mutual Funds, which takes effect November 1, 2026.
  • The package includes a supplemental circular on liquidity risk management and updated guidance for the Fund Authorisation Simple Track.
  • The SFC also refreshed frequently asked questions covering the revised retail fund rules and authorization of UCITS funds.

The implementation window is effectively over. Fund managers and distributors now need their liquidity controls, derivatives processes and authorization workflows ready for the November 1 rules. The value of the guidance is operational certainty before the new regime goes live.

Canada Sets Out Stablecoin Issuer Rules

October 24, 2026, Canada
  • Canada published proposed Stablecoin Regulations that would bring the Stablecoin Act into operation and require covered issuers other than banks to register with the Bank of Canada.
  • Reserve assets must equal or exceed outstanding stablecoins at the end of each day. Eligible reserves are limited to high quality liquid assets, must be segregated and bankruptcy remote, and must be held with qualified custodians formed in Canada.
  • Issuers would have to redeem at par within three business days and couldn't charge more than 1%. Interest or yield tied to holding a stablecoin would be prohibited, while transaction based rewards would remain permitted. Comments close December 23, 2026, with implementation targeted for fall 2027.

Canada now has enough detail for firms to start building against the rulebook rather than policy direction. Issuers can model reserve composition, custody, redemption costs, reward structures and Bank of Canada registration now. Payment firms also need to map where stablecoin activity pulls them into RPAA oversight. NCFA's stablecoin regulatory framework tracks those layers together.

Capital Markets Infrastructure And Funding

Chainlink Makes Traditional Asset Pricing Available 24/7

October 29, 2026, Global
  • Chainlink 24/7 is live with continuous market data for equities, commodities and other traditional assets across trading sessions, weekends and holidays.
  • The feeds support tokenized assets, perpetual futures, prediction markets and lending markets that need collateral values after conventional exchanges close.
  • Aave is the launch partner, giving the service immediate distribution inside one of the largest onchain lending platforms.

Tokenized markets can't run continuously on stale prices. Chainlink is closing that gap with a single pricing reference that stays available when the underlying exchange is shut. The commercial test is whether continuous data supports deeper weekend liquidity and broader use of traditional assets as onchain collateral.

Clearstream Wins Control Agent Authorization for Tokenized Funds

October 29, 2026, Luxembourg
  • Luxembourg's CSSF authorized Clearstream to act as a Control Agent under Blockchain Law IV, giving it a regulated role in the issuance and oversight of tokenized fund shares.
  • Asset managers can tokenize selected share classes inside existing UCITS or alternative investment fund structures while keeping established transfer agents, administrators, custodians and depositaries in place.
  • The Control Agent maintains the central issuance account on distributed ledger infrastructure, tracks the holding chain and reconciles issued volume against investor positions. Clearstream says its integrated DLT service remains subject to completion of CSSF regulatory processes.

Fund managers can now add a regulated digital issuance layer without replacing the service providers they already use. That lowers the cost of testing tokenized share classes and strengthens the case for tokenized assets as market infrastructure. Live issuance volume and distributor adoption are the next proof points.

Thailand Proposes Crypto Derivatives Licences for Existing Exchanges

October 29, 2026, Thailand
  • Thailand's Securities and Exchange Commission opened consultation on eight draft regulatory notifications covering crypto derivatives licensing, exchanges, clearing houses and intermediaries under the country's Derivatives Act.
  • Existing licensed digital asset businesses could apply to offer derivatives without establishing separate companies. The proposals also revise financial reporting requirements for derivatives exchanges and clearing houses.
  • The proposals follow an earlier consultation from April to May 2026. Comments close November 28, 2026. The new licensing arrangements are not yet in effect.

Thailand is working to give crypto exchanges a route into regulated derivatives trading without forcing them to build separate businesses. That could lower expansion costs while bringing trading, clearing and risk controls under closer supervision. Combined with Thailand's recently finalized crypto ETF rules, the proposals give exchanges and investment firms more ways to serve investors. The next test is whether the final licensing requirements make commercial entry practical.

Goldman Sachs Joins EquiLend 1Source

October 28, 2026, United States and Canada
  • Goldman Sachs is now using EquiLend 1Source, the distributed ledger platform built to reduce breaks and reconciliation work in securities finance.
  • Goldman joins BNY and National Bank of Canada. BNY and National Bank began transmitting live transactions onto the shared ledger in October 2025.
  • EquiLend says additional counterparties are adopting the platform, which uses one shared transaction record across securities lending and financing workflows.

A shared ledger becomes more useful as both lenders and large borrowers join it. Goldman adds another major institutional node to 1Source and strengthens the case for replacing bilateral reconciliation with a common record. The next proof point is transaction volume and how quickly more counterparties stop running parallel comparison processes.

DTCC Tokenization Service Goes Live With 20 DTC Participants

October 28, 2026, United States and Global
  • DTCC launched the Tokenization Service through The Depository Trust Company, allowing eligible users to create tokenized representations of securities held at DTC and convert between traditional and tokenized forms.
  • DTC holds more than $114 trillion in assets under custody. Twenty DTC participants have signed agreements to access the service, including Bank of America, Barclays, Citi, Fidelity, J.P. Morgan, Morgan Stanley, State Street and UBS.
  • The service currently connects to Canton Network and DTCC's private Besu network. DTCC says additional blockchain networks will be added in 2027 after earlier limited production trades with more than 30 firms.

Tokenization has moved from DTCC’s roadmap into live depository infrastructure. Banks and asset managers can now test whether tokenized positions improve collateral use, liquidity or settlement while keeping the underlying DTC rights intact. NCFA’s crypto custody intelligence tracks the same shift toward regulated tokenized market infrastructure.

HKEX Extends Its Fund Platform Across Distribution and Settlement

October 28, 2026, Hong Kong
  • HKEX launched Platform and Nominee Services on its Integrated Fund Platform, adding master distribution, nominee and administration functions to the existing fund repository and order routing services.
  • The expanded platform supports onboarding, order processing, settlement, payments, reconciliation and reporting across distributors, fund managers and transfer agents.
  • The participant base has grown from 33 firms when order routing launched in July 2025 to more than 60 distributors, fund houses and transfer agents.

HKEX is pulling more fund distribution work onto shared infrastructure. That can reduce duplicated integrations across managers, distributors and transfer agents. The commercial test is whether the larger network lowers servicing cost and makes new fund distribution easier.

Archax Brings 24/7 Euro Government Bill Exposure Onchain

October 28, 2026, European Union
  • Archax launched €GOVY on Stellar, giving eligible institutions continuous tokenized exposure to short dated euro area government debt.
  • The product automatically reinvests proceeds as underlying bills mature, so investors do not have to redeem and reinvest at each maturity.
  • Archax distributes €GOVY to EU clients through Archax Markets Europe, which received Spanish authorization in September to provide execution, placement, custody and related investment services.

Archax is extending tokenized government debt from issuance into continuous institutional access. The firm has already demonstrated onchain delivery versus payment with tokenized cash. Now the question is whether euro investors use the product for treasury, collateral and liquidity management.

Mirae Completes Tokenized Funding Note Issuance on Solana

October 28, 2026, Hong Kong
  • Mirae Asset Securities completed an institutional tokenized funding note issuance on Solana under its US$3 billion Guaranteed Structured Note Programme.
  • The transaction used US dollar six month floating rate notes issued in Hong Kong. Mirae handled token issuance, payments and lifecycle management.
  • Singapore regulated Marketnode acted as an authorized distributor, giving eligible institutional investors a route to hold the notes in tokenized form on public blockchain infrastructure.

Public blockchain infrastructure is moving into institutional note issuance with regulated distribution attached. Mirae controls the instrument lifecycle while Marketnode provides the investor route. That fits the broader shift NCFA tracks in tokenized capital markets infrastructure.

Pontoro Launches Live Liquidity Pool for Private Markets

October 28, 2026, United States and United Kingdom
  • Pontoro launched the first live deployment of its Automated Liquidity Pool on Stellar with Archax and the Stellar Development Foundation.
  • The pool combines liquid money market assets with private market fund interests and uses rules based pricing as liquidity is consumed.
  • Pool interests are issued as permissioned onchain tokens for approved investors, while redemptions draw first from the liquid sleeve and can be constrained when liquidity is exhausted.

Private market tokenization needs usable exits, not just digital ownership records. Pontoro is testing that problem with a live pool that combines liquid assets and private fund interests. NCFA has tracked the same liquidity constraint in tokenized asset liquidity infrastructure.

Janus Henderson Launches Blockchain Native Nasdaq 100 Fund

October 27, 2026, Global
  • Janus Henderson and Centrifuge launched JQQQ, a blockchain native fund designed to track the Nasdaq 100 Index through an issuer sponsored investment strategy.
  • The fund is built for issuance and operation on public blockchain infrastructure and uses Centrifuge technology for onchain fund administration and distribution.
  • Janus Henderson says its onchain platform now includes more than $1 billion in institutional strategies across U.S. Treasuries, structured credit and public equities.

This pushes onchain funds beyond cash and credit into public equities. Janus Henderson already has more than $1 billion in onchain strategies, so distribution and servicing scale now matter more than proof of concept. The larger question is how quickly tokenized funds become normal market infrastructure.

Chainlink Connects Qualified Custody to DeFi Lending

October 26, 2026, United States and Global
  • Chainlink CustodySync lets qualified custodians give institutional clients access to DeFi lending while the underlying assets remain in custody.
  • Anchorage Digital is the launch partner, connecting federally chartered digital asset custody with onchain borrowing workflows.
  • Chainlink estimates roughly $700 billion in digital assets are held in custody, compared with about $250 trillion across traditional custody.

Institutional DeFi has had a custody problem. Institutions often need assets to stay inside qualified custody, while lending protocols expect collateral to interact with onchain contracts. CustodySync creates a bridge between those control models. Usage will show whether that bridge can turn idle custodied assets into repeatable financing activity.

Hong Kong Opens 24/7 Trading for Tokenized Public Funds

October 26, 2026, Hong Kong
  • Hong Kong's Securities and Futures Commission approved secondary trading of two existing SFC authorized ChinaAMC tokenized money market funds on an SFC licensed virtual asset trading platform. Trading began October 26 and runs around the clock.
  • The funds can now trade between investors in a secondary market instead of relying only on conventional subscriptions and redemptions at net asset value.
  • The SFC requires fair pricing controls, liquidity provision, investor disclosures and market making arrangements. Platforms must also show indicative NAV data and warn investors when execution prices materially diverge from it.

The commercial test for tokenized funds just changed. The question is no longer whether a regulated fund can be put on chain. It's whether investors will use continuous liquidity when the underlying portfolio still operates on conventional market hours. Spreads, market maker depth and off hours price gaps now become the metrics worth watching.

Malaysia Tightens the Gate for Electronic Trading Platforms

October 26, 2026, Malaysia
  • Bank Negara Malaysia issued a revised Electronic Trading Platforms Framework covering platform services in wholesale money and foreign exchange markets.
  • Eligible operators must obtain BNM approval before offering electronic trading platform services in Malaysia. Services involving instruments outside the framework still require approvals from the relevant authorities where applicable.
  • The revised rules replace the original 2019 framework and take effect November 1, 2026.

For venue operators, this is an access issue, not a documentation exercise. Firms serving Malaysian institutional flows need to know whether their platform, instruments and client model fall inside the approval perimeter before November 1. Banks and liquidity providers should be checking the venues they rely on at the same time.

Europe Puts a €1 Billion Digital Bond on Live Pontes Rails

October 26, 2026, Euro Area
  • The European Stability Mechanism priced its first digitally native benchmark bond at €1 billion. Deutsche Bundesbank acts as issuing and paying agent, while Clearstream provides the digital market infrastructure.
  • Clearstream creates and manages the bond digitally and runs delivery versus payment settlement on its D7 DLT platform. The cash leg settles through Pontes directly in TARGET using central bank money.
  • The bond is expected to list on the Luxembourg Stock Exchange and qualify for Eurosystem collateral use. Clearstream also expects eligibility at Eurex Clearing and inclusion in general collateral baskets at Eurex Repo.

This is where digital bond settlement on Pontes starts competing on infrastructure, not demos. The value is interoperability with markets institutions already use. Banks, custodians and issuers can now compare digital issuance with conventional settlement on liquidity, collateral mobility, operating cost and execution time.

Aviva Opens Tokenized Access to £22 Billion Sterling Fund

October 26, 2026, United Kingdom
  • Aviva Investors launched a tokenized share class of its Sterling Liquidity Fund on the XRP Ledger. The existing fund has about £22 billion in assets under management.
  • Aviva invested £50 million in the new share class, taking investment across its two tokenized share classes above £86 million. The fund is an Ireland domiciled UCITS money market fund and uses a digital twin model.
  • Eligible investors can access the share class with digital wallets. BNY is the fund custodian, Komainu supports digital asset custody and Licuido provides tokenization infrastructure.

This is distribution infrastructure attached to a large existing fund, not a sandbox asset. The Schroders tokenized money market fund approval provides another regulated institutional benchmark. The next proof point is whether tokenized access changes subscriptions, settlement, collateral use or investor reach. Fund managers should watch where wallet based access removes friction and where the conventional fund stack still does the heavy lifting.

Artificial Intelligence And Data

Powens Uses AI Agents to Build and Repair Open Finance Connections

October 28, 2026, Europe
  • Powens launched an internal AI system that builds new Open Finance connectors and repairs existing connections across an infrastructure estate of more than 1,800 connectors.
  • The system has already delivered 12 new connectors. Powens says typical repairs that could take up to two days now take about 10 to 15 minutes.
  • Every proposed connector or fix still requires engineer approval before it goes live. Powens reports that 50% of proposed fixes are currently approved directly by its engineers.

AI is now changing the cost structure behind open finance connectivity. Powens is using agents inside production engineering while keeping human approval before release. For operators, the useful benchmark is whether faster connector maintenance improves uptime and coverage without weakening control evidence. NCFA’s open banking intelligence tracks those operating requirements.

Casap Expands Agentic AI Across Financial Operations

October 28, 2026, United States
  • Casap raised a US$56 million Series B led by Base10 Partners, bringing total funding to US$90 million, while expanding its agentic AI platform beyond fraud and disputes into collections, claims and other complex financial operations.
  • The company says it now serves more than 100 banks, credit unions, fintechs and processors and grew revenue 10 times since its Series A. Those figures are company reported.
  • Casap says its agents resolve 73% of dispute cases without manual intervention, with human teams handling exceptions and higher risk decisions. The company has not published independently audited performance data.

The more important signal is operating expansion, not the financing round. Casap is moving agentic automation from one regulated workflow into several functions where decisions affect customers, losses and recovery. Financial institutions adopting similar systems need clear authority boundaries, exception handling and evidence for every automated action as AI agent financial authorization and security becomes an operating control.

RBC Blocks Personal AI Agents From Direct Online Banking Access

October 27, 2026, Canada
  • RBC says it has blocked third party personal AI agents from direct access to authenticated RBC digital properties, including online banking.
  • The bank says personal agents may need account credentials or stored passwords to act for users and points to fraud, consumer harm and wider financial system risk as reasons for the restriction.
  • Canadian Press reporting on October 29 says BMO and TD also confirmed they do not permit direct personal AI agent access, while CIBC does not support it and Scotiabank plans to limit access.

Banks are setting the access rules before personal AI agents become a normal financial interface. Canada’s consumer driven banking system is built around permissioned data sharing, while agent access adds delegated authority and transaction control. Authentication, consent and liability now need a workable model for agents as well as people.

Cybersecurity Fraud And Financial Crime

Binance Reports $6.3 Billion Security Incident

October 30, 2026, Global
  • Binance estimates the incident affected approximately $6.3 billion and says blockchain partners have frozen about $3 billion onchain.
  • Its preliminary investigation points to a compromised DevOps engineer laptop that allowed an attacker to reach a service container and submit unauthorized withdrawal transactions. Binance says it has found no evidence that wallet private keys were exposed.
  • Binance temporarily suspended withdrawals during security checks and says the SAFU Fund and company funds will cover losses. A detailed technical review and updated proof of reserves are still pending.

The scale makes endpoint access, service permissions and withdrawal authorization a board level control issue for digital asset platforms. The final technical account will matter more than early attack theories. Exchanges, custodians and infrastructure vendors should compare privileged access, transaction approval and emergency freeze controls against the failure path Binance ultimately confirms.

NIST Sets the Migration Roadmap for Post Quantum Cryptography

October 27, 2026, United States
  • NIST finalized IR 8547, its official roadmap for moving from quantum vulnerable cryptography to post quantum standards.
  • Federal high value and high impact systems must prioritize migration, with key establishment targeted for 2030 and digital signatures for 2031. The broader federal migration target remains 2035.
  • The report identifies vulnerable algorithms, replacement standards and migration work across products, services and the wider cryptographic supply chain.

Quantum migration now has federal target dates, which turns a distant security issue into a planning deadline. Financial firms need cryptographic inventories, vendor commitments and replacement schedules before 2030 pressure arrives. NCFA’s post quantum planning analysis explains why the work has to start well before vulnerable systems fail.

Competition And Market Structure

South Korea Fines Google and Apple KRW 63.71B Over App Payments

October 28, 2026, South Korea
  • South Korea's Korea Media and Communications Commission fined Google KRW 42.9 billion and Apple KRW 20.81 billion for restricting developers' payment choices and other app market violations.
  • Both platforms restricted external payment methods and charged developers a 26% commission when they used permitted third party payment systems. Developers also lost access to certain features available through the platforms' own payment services.
  • The regulator ordered changes to payment policies and app review procedures. This is its first enforcement action under South Korea's 2021 law prohibiting app stores from forcing particular payment methods.

App stores are payment gatekeepers, not just software distributors. South Korea's orders challenge the fees and restrictions that make competing payment systems harder to sell. Developers could gain more control over checkout costs and customer payments, while payment providers get a better chance to compete. The commercial test is whether Google and Apple implement the required changes without replacing old restrictions with new ones.

CFTC Takes Utah to Court Over Prediction Market Control

October 27, 2026, United States
  • The CFTC sued Utah to block the state from using state law to shut down CFTC registered contract markets.
  • The Commission says Congress gave it exclusive federal jurisdiction over registered derivatives exchanges and argues Utah's enforcement obstructs that federal structure.
  • The CFTC says it has also initiated legal proceedings against nine other states and filed briefs in four federal courts of appeal and one state supreme court.

Prediction markets are now a jurisdiction fight over who controls access to federally regulated contracts. The outcome can change where platforms can operate and how state restrictions interact with CFTC registration. Canada is watching the same category develop through firms such as Verdx and its event contract dealer application.

Sustainable Finance ESG And Financial Inclusion

Thailand Mandates ISSB Climate Reporting for Listed Firms From 2027

October 26, 2026, Thailand (announced October 28)
  • Thailand's Securities and Exchange Commission issued nine notifications effective October 26 aligning listed company sustainability disclosures with IFRS S1 and IFRS S2 standards.
  • SET50 companies must report 2027 information in 2028. SET100 companies follow one year later, with wider coverage of listed companies, property funds and infrastructure funds phased in through 2031.
  • The rules require independent assurance of greenhouse gas emissions disclosures and provide five transition relief measures, including initial relief for Scope 3 emissions and comparative reporting.

Thai issuers now have firm deadlines to build emissions records, reporting controls and assurance processes that investors can check. That's commercial work for data providers, auditors and compliance software firms. Canada is taking a different approach with its voluntary green and transition taxonomy. Firms serving both markets will need to distinguish mandatory company disclosures from voluntary investment classifications. The immediate priority in Thailand is getting the data and controls ready before the first reporting year.

Cross Border Payments And FX

Canada and EU Plan to Connect RTR and TIPS Instant Payments

October 30, 2026, Canada and European Union
  • Canada and the EU agreed to support work by the Eurosystem, Bank of Canada and Payments Canada toward connecting their instant payment systems for faster international transfers.
  • The proposed link would connect Canada's planned Real-Time Rail (RTR) with Europe's TARGET Instant Payment Settlement (TIPS) system, creating a potential route for near real time payments between Canadian and European accounts.
  • The commitment does not establish a live payment corridor. No launch date, participating banks, access rules or transaction fees have been announced.

Connecting RTR and TIPS could give Canadian payment providers a faster, lower cost alternative to traditional international transfers. The commercial opportunity depends on who gets access, how foreign exchange works and what transactions cost. Firms preparing for Canada's Real-Time Rail access requirements should include European connectivity in their planning, but it's not a service they can offer customers yet.

Movantis Adds Stellar to Its Cross Border Settlement Rails

October 29, 2026, Americas
  • Movantis integrated Stellar as an additional digital settlement rail inside its existing multi rail cross border payments infrastructure.
  • The first planned use case will settle value from the United States to El Salvador using USDC on Stellar, with regulated local partners handling conversion and final payout.
  • Movantis says its network already processes more than $60 billion a year across more than 200 million transactions, 130 countries and 90,000 payout locations.

Movantis is adding stablecoin settlement inside an existing payments network rather than launching a separate crypto product. With more than $60 billion in annual flow already on its infrastructure, even a narrow corridor can become meaningful quickly. NCFA’s programmable stablecoin payments opportunity tracks the same commercial shift toward settlement, treasury and payout infrastructure.

Flywire Goes Live Across Liquidity Services B2B Marketplace

October 29, 2026, United States and Global
  • Liquidity Services implemented Flywire for domestic and cross border B2B payments across a global ecommerce marketplace serving more than 6 million qualified buyers and 15,000 corporate and government sellers.
  • The deployment supports localized payment methods, currency conversion and compliant payment workflows across more than 100 countries.
  • Liquidity Services says its marketplaces have completed more than US$15 billion in transactions over 25 years. Flywire did not disclose payment volume processed through the new implementation.

This is a live enterprise payment deployment rather than a partnership announcement. Flywire is being embedded inside a marketplace where cross border settlement, foreign exchange and reconciliation are part of the transaction flow. The next proof point is whether the integration lowers payment friction and cost at scale across complex B2B transactions.

Wealthtech Investing And Trading

Ondo Brings Seven Tokenized Portfolios to Solana

October 29, 2026, Global
  • All seven Ondo Intelligent Portfolios are now live on Solana for eligible investors outside the United States through supported wallets and applications.
  • The portfolios passed $40 million in total value locked during their first four weeks on Ethereum and BNB Chain.
  • Ondo already has more than $500 million in tokenized asset value on Solana, giving the portfolio lineup an existing distribution base on the network.

Tokenized investing is moving from single assets into packaged portfolio products that can travel across wallets and chains. The early $40 million uptake gives Ondo more evidence than a typical launch. The next test is whether multi asset tokens attract sustained balances and repeat use beyond crypto native investors.

Webull Canada Connects Brokerage Accounts to Personal AI Assistants

October 27, 2026, Canada
  • Webull Canada lets eligible investors connect their brokerage accounts to AI assistants including ChatGPT, Perplexity, Claude and Grok through Model Context Protocol.
  • Users can access live market data, balances and positions, analyze portfolios and prepare orders through plain language prompts. Trades still require the investor to review and confirm the order on Webull.
  • The integration runs on Webull's global infrastructure, which supports more than 29 million registered users. Rollout to all eligible Canadian accounts is expected by the beginning of November.

Canadian brokerage competition is moving from AI research tools into account connected workflows. Webull keeps final trade approval with the investor, but the assistant can now reach live balances, positions and order preparation. Questrade introduced a similar Canadian brokerage connection in July, giving the market two live models to compare.

Digital Banking And BaaS

nbkc Moves to Assume LSBX Consumer BaaS Portfolio

October 30, 2026, United States
  • nbkc bank filed an application with the FDIC to assume the consumer focused Banking as a Service portfolio operated by LSBX, the BaaS division of Lincoln Savings Bank.
  • nbkc says it currently has about 13 fintech BaaS relationships, approximately 3.6 million BaaS customers and 30 employees dedicated to the business.
  • The transaction is expected to close in early 2027 subject to regulatory approval. nbkc plans to merge the LSBX offering into its existing BaaS business and operate it under the nbkc brand.

The proposed transfer would consolidate another sponsor bank portfolio inside an institution already operating at material BaaS scale. Fintech partners will be watching program migration, risk appetite and service continuity because banking as a service partnerships depend as much on the regulated bank relationship as on the front end product.

CIBC Adopts Vault Core Starting With Simplii

October 29, 2026, Canada
  • CIBC will become the first large Canadian bank to adopt Thought Machine's Vault Core banking platform.
  • The Simplii Account will be the first deployment. CIBC plans to use its own product and engineering teams to build products on the new core.
  • CIBC also completed a £30 million minority strategic investment in Thought Machine earlier in 2026.

This gives Canada a major test of whether a large incumbent can add a modern core without waiting for a full bank replacement program. Starting with Simplii gives CIBC a digital brand where product speed matters. Watch migration scope, product release cycles and whether the platform eventually expands deeper into CIBC's retail stack.

Ripple Announces Final OCC Approval for National Trust Bank

October 26, 2026, United States
  • Ripple announced that the Office of the Comptroller of the Currency granted final approval to charter Ripple National Trust Bank after conditional approval in December 2025.
  • The approved activities include managing segregated reserves for RLUSD, acting as collateral trustee for RLUSD holders and providing fiduciary digital asset custody services.
  • RLUSD will continue to be issued by Standard Custody & Trust Company. Ripple says RLUSD has reached a $2.5 billion market cap, while the new national trust bank will provide its approved custody services after it opens.

The charter gives Ripple a federally supervised operating base around reserves and custody, building on the earlier U.S. crypto trust charter approvals. The next test is execution. Institutions will be watching how quickly the bank becomes live capacity and whether Ripple can turn the charter into deeper relationships across payments, custody and capital markets.

Digital Assets Blockchain And Tokenization

MetaMask Makes Stellar a Default Network for Every Account

October 29, 2026, Global
  • Stellar is now a default network in MetaMask Mobile and Extension. Every existing MetaMask account receives a Stellar address without a separate setup step.
  • Users can hold and manage XLM, Stellar assets and smart contract tokens, send and receive them, and swap between Stellar and other supported networks.
  • Stellar processed $55.6 billion in payment volume in 2025, up 52% year over year, while MetaMask gives the network direct distribution through a major self custody wallet.

The important change is distribution. Existing MetaMask users get Stellar access without installing another wallet, while Stellar gains a direct route into a large self custody user base. Usage will show whether easier access produces more balances, transfers and token activity.

Curve Goes Live on Stellar With Native Stablecoin Liquidity

October 29, 2026, Global
  • Curve Finance launched on Stellar mainnet in its first native deployment outside the EVM ecosystem.
  • The initial release brings Curve's audited StableSwap implementation to Stellar, allowing users to create pools, swap assets and provide liquidity without permission.
  • Curve plans to add FXSwap after its audit is complete, extending the model toward liquidity between assets tied to different currencies.

Stablecoins and tokenized assets need deep markets after issuance. Curve gives Stellar a familiar liquidity engine without routing users through another chain. NCFA has tracked the same institutional requirement in tokenized asset liquidity infrastructure. Depth and spreads will determine whether this deployment becomes commercially important.

Taurus Adds Live Stellar Smart Contract Custody and Issuance

October 29, 2026, Switzerland and Global
  • Taurus added live support for Stellar smart contract assets through its institutional custody and tokenization platforms.
  • Banks and financial institutions can now custody, issue and manage these assets through the same Taurus interfaces and APIs they already use for other networks.
  • The integration supports standardized and custom smart contract structures for securities, funds and other regulated financial instruments.

Banks can add Stellar assets without building another custody stack from scratch. That lowers integration cost and lets network choice depend more on the asset and client use case. NCFA’s crypto custody intelligence tracks why regulated custody and issuance controls are becoming core tokenized market infrastructure.

CADC Reserve Trust Announces Final Prospectus Receipt

October 27, 2026, Canada
  • CADC Reserve Trust announced that the Ontario Securities Commission issued a receipt for its final prospectus dated October 22, covering a continuous offering of CADC tokens at a fixed price of C$1.00.
  • The prospectus qualifies CADC distribution across every Canadian province and territory.
  • Authorized Participants can include registered crypto trading platforms, Canadian financial institutions and platforms with exemptive relief to trade stablecoins on a non custodial basis.

CADC now has a securities law distribution route that can reach Canada nationally through regulated and exempt participants. That gives wallets, trading platforms and financial institutions another domestic stablecoin model to assess alongside the proposed federal regime. NCFA's Canada stablecoin market entry analysis explains the broader issuer and infrastructure choices opening around these rules.

BNY Adds XRP and RLUSD to Institutional Custody

October 27, 2026, United States
  • BNY now supports XRP and RLUSD on its Digital Asset Custody platform for eligible institutional clients.
  • The expansion builds on BNY's role as primary reserve custodian for RLUSD and its existing custody relationship with Ripple Prime.
  • Ripple and BNY are also exploring tokenized trade finance. That work remains exploratory, while the custody support for XRP and RLUSD is live.

The live signal is custody access inside BNY's institutional control environment. That removes one practical barrier for firms that can use digital assets only through established custody, governance and operating processes. Adoption now depends less on whether custody exists and more on what institutions are permitted to do with the assets once held.

Payments Infrastructure And Money Movement

Natural Gives AI Agents Direct Choice of Payment Rails

October 29, 2026, United States
  • Natural moved Direct into general availability, allowing authorized AI agents to choose ACH, wire or real time payments over RTP and FedNow when a transaction is executed.
  • Agents can choose the rail based on the recipient, delivery speed and cost while using the same Natural wallet already used for cards and other payment functions.
  • Existing business controls and limits remain attached to the wallet. Natural says mailed checks, international wires and additional rails are planned but are not part of the current live capability.

The operating change is runtime payment choice. An agent can select how money moves instead of following a payment rail fixed earlier in the workflow. That flexibility increases the importance of transaction limits, recipient validation and revocation because AI agent payment authorization now has to hold across several rails, not just one.

Polygon Opens Its Payment Stack to Solana Businesses

October 29, 2026, Global
  • Polygon Open Money Stack now supports Solana businesses from bank or card funding through stablecoin balances and final payout.
  • The live stack can accept bank transfers, cards, cash or crypto, convert between fiat and crypto, hold funds in wallets and route tokens across Solana, Polygon and other supported chains.
  • Payouts can reach bank accounts, cards, cash locations or wallets, giving Solana businesses one operating layer across funding, orchestration and settlement.

The integration reduces how many providers a Solana payments company has to stitch together before it can move money end to end. That makes network choice less important than reach, compliance and payout coverage. The commercial test is whether one orchestration layer can lower integration cost enough to pull more payment volume onto stablecoin rails.

PayFacto Opens Konek to Its Canadian Merchant Network

October 29, 2026, Canada
  • PayFacto is integrating Konek across its Canadian merchant and partner network, adding account based payments alongside card payments.
  • Konek lets customers pay participating online merchants directly from a chequing or savings account at a participating financial institution through Interac Direct.
  • Interac designed the wallet to lower acceptance cost compared with most traditional cards and to reduce fraud and chargeback disputes for merchants.

Konek is taking account based payments into merchant distribution rather than waiting for a new national rail to create the use case. PayFacto gives Interac a practical channel into commerce where card economics already matter. NCFA's Canadian online payments analysis tracks how cards, wallets and bank payments are competing for that checkout.

WalletConnect Makes Stellar Payments Live Across Its Network

October 29, 2026, Global and Bermuda
  • WalletConnect added Stellar support across a network that reaches 900 million end users, more than 700 wallets and over $400 billion in annual transaction volume.
  • WalletConnect Pay now supports Stellar payments, and LOBSTR is the first Stellar wallet live with the payment service.
  • WalletConnect and Penrose Partners plan to extend the service to Bermuda merchants. Premier Tickets is expected to begin accepting payments in the second quarter of 2027.

WalletConnect gives Stellar another route into wallets and payment applications at large distribution scale. Merchant rollout in Bermuda still comes later, so adoption should be measured first through wallet connections and payment volume. The direction fits NCFA’s programmable payments opportunity around wallet access, settlement and merchant acceptance.

Adyen Adds Visa Passkeys to Its Payment Authentication Layer

October 29, 2026, United Kingdom
  • Adyen rolled out Visa Payment Passkey through Authenticate, the authentication module inside Adyen Uplift.
  • Eligible customers can authenticate online purchases using the device unlock method they already use, including fingerprint or face recognition.
  • Merchants using Authenticate can receive the new method without building another integration. The UK launches first, with broader global expansion planned for 2027.

Authentication is becoming part of payment orchestration rather than another merchant integration. Adyen can now route an eligible shopper into device based authentication from inside its existing stack. Merchants should watch both conversion and fraud because the commercial win requires improvement on both.

Robinhood Makes RLUSD Live Across Chain and Bitstamp

October 27, 2026, United States
  • RLUSD is live on Robinhood Chain and Bitstamp by Robinhood. Ripple says the stablecoin is expected to reach the Robinhood app later this year.
  • Robinhood plans to use RLUSD on the XRP Ledger for institutional settlement and integrate Ripple Treasury into its global cash and liquidity operations.
  • Ripple Prime already provides Bitstamp with lending and margin financing across roughly 20 digital assets. Robinhood reports 28.6 million funded customers globally.

This links stablecoin distribution, institutional settlement, treasury and financing inside one large trading group. The important test is usage. Watch settlement volume, treasury adoption and whether RLUSD becomes a working asset across Robinhood's institutional flows rather than another listed stablecoin.

Dutch Merchants Can Start Moving From iDEAL to Wero

October 26, 2026, Netherlands
  • From October 26, ABN AMRO business customers with iDEAL contracts can begin the technical migration to Wero as the Netherlands moves toward replacing iDEAL.
  • The change requires new API connections, payment page updates and transaction processing changes. Standard payments, refunds and e invoicing are part of the October migration phase.
  • iDEAL is expected to remain available through December 31, 2027. Wero adds functions that extend beyond today's iDEAL model, with subscriptions and pay on delivery capabilities scheduled for later phases.

This phase puts migration work into merchant roadmaps. PSPs and payment teams now have to decide when to update integrations, how long to support both rails and which new Wero functions justify moving early. The long overlap gives merchants breathing room, but it also creates a two year distribution contest for the providers handling the transition.

Risk Compliance And Regtech

Napier AI Brings Real Time LSEG Risk Data Into Payment Screening

October 29, 2026, Global
  • Napier AI completed technology validation for integrating LSEG World Check On Demand into its transaction screening platform.
  • Financial institutions can apply newly published sanctions, politically exposed person, adverse media and enforcement intelligence through an API within minutes of publication by LSEG analysts.
  • The screening workflow can be configured around an institution's own risk appetite, policies and payment data rather than applying one uniform screening rule across every transaction.

Faster intelligence only matters if it reaches the payment decision before funds move. The integration shortens the gap between a new risk signal and transaction screening while keeping policy configuration with the financial institution. That makes data freshness, alert quality and audit evidence key measures of whether AI and financial crime compliance actually improve in production.

S&P Global Ratings Puts Vault Risk Data Onchain

October 28, 2026, United States and Global
  • S&P Global Ratings' Vault Risk Assessment data is now available onchain through Chainlink DataLink, with Base as the first supported blockchain.
  • The assessments cover credit quality, liquidity mismatch, curator risk, blockchain risk, protocol risk, security and governance. They are risk opinions, not credit ratings.
  • Deposits in blockchain lending vaults reached approximately $10 billion in September 2026, up from $1.5 billion two years earlier.

Independent risk analysis is moving into the same environment where onchain capital is allocated. That can make vault selection and governance more comparable for institutions that need third party evidence before deploying funds. The next step is whether protocols and investment committees begin using the assessments as a formal control rather than optional information.

Australian Court Orders The Star to Pay A$260 Million for AML Failures

October 28, 2026, Australia
  • Australia's Federal Court ordered The Star Entertainment Group to pay A$260 million for breaches of anti money laundering and counter terrorism financing laws.
  • The Court found The Star failed to maintain a compliant AML program and failed to monitor customers well enough to identify, mitigate and manage money laundering and terrorism financing risk.
  • The penalty follows earlier state and Commonwealth action, including A$200 million in penalties for conduct that the Court said significantly overlapped with the current proceedings.

A$260 million turns weak AML controls into a board level cost. Financial firms should read the judgment as an operating warning on customer risk assessment, monitoring and program evidence. The penalty also raises the price of waiting until supervisory concerns become enforcement.

Further Embeds ADGM Compliance Rules Into Tokenized Assets

October 27, 2026, Abu Dhabi
  • Further Asset Management adopted Chainlink Automated Compliance Engine inside Anubis, its machine readable compliance platform for tokenized assets.
  • The initial ADGM deployment can apply configured controls covering issuance, KYC, AML, ownership, trading, custody and sanctions before a transaction executes.
  • ADGM is home to more than 340 financial institutions, giving the deployment a regulated market where tokenized asset rules can be translated directly into transaction controls.

Tokenized assets become easier to scale when compliance rules can travel with the transaction instead of being checked in a separate manual process. Further is testing that model inside a regulated financial center. The critical proof point is whether institutions adopt the controls in live issuance and trading workflows.

SME Finance And Business Banking

Lendistry Opens OrigenLink Lending as a Service to Banks

October 29, 2026, United States
  • Lendistry announced OrigenLink, a managed lending as a service platform designed to let banks offer additional small business credit options inside their own customer experience.
  • The model removes the need to send borrowers who do not fit a bank's existing products to a separate Lendistry application, allowing participating banks to retain the relationship while adding Lendistry products.
  • Lendistry says it has deployed more than US$11 billion to small businesses since 2015 and uses AI and automation across the lending lifecycle. The US$11 billion figure is company reported.

OrigenLink changes the handoff between a bank and an alternative lender. Instead of losing a customer when the bank cannot make the loan, the institution can keep the relationship and add another credit path behind its own brand. That gives banks a way to expand SME lending without building every underwriting and servicing capability internally.

Billd and Cross River Take Flex Line Nationwide

October 27, 2026, United States
  • Billd launched Flex Line nationally with Cross River Bank originating the revolving credit product for qualified commercial subcontractors.
  • The working capital line is not tied to an individual construction project and replenishes as balances are repaid, giving subcontractors another source of liquidity alongside traditional bank credit.
  • Billd positions the product around the cash flow mismatch created when subcontractors must pay labour and materials before receiving payment from contractors or project owners.

Construction finance exposes the working capital problem in unusually clear terms: businesses often have confirmed work but still need liquidity before invoices are paid. Flex Line adds another embedded credit option for that gap and extends the broader shift toward small business working capital and lending being delivered closer to the operating workflow.

Weekly Close

Canada's proposed stablecoin rules would require 100% daily reserve backing, redemption within three business days and a maximum 1% redemption fee, with implementation targeted for fall 2027. Meanwhile, Ripple secured final OCC trust bank approval, BNY opened institutional custody for XRP and RLUSD, and Robinhood brought RLUSD into its trading infrastructure, reaching a platform with 28.6 million funded customers. Companies that control custody, distribution and settlement stand to gain.

Canada's challenge is to turn its regulatory framework into commercially viable infrastructure before global networks capture the market.

NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech news and insights, industry research, or launch into emerging financial innovation opportunities.


NCFA Canada logoThe National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

Binance $6.3B Hack and Polymarket Breach Expose Weaknesses

October 30, 2026 | NCFA Story Intelligence | Digital Assets Blockchain And Tokenization, Cybersecurity And Fraud, Competition And Market Structure

AI illustration of Binance $6.3B hack and Polymarket breach illustrated with unauthorized withdrawals, frozen assets, trading halt, vendor breach and customer protection controls.

How two separate security failures exposed weak points in authorization, recovery and digital finance infrastructure

On October 29, 2026, Binance suffered unauthorized withdrawals with an estimated US$6.3 billion impact, while Polymarket suffered a separate third party breach that forced its international prediction market to halt trading. Binance says the attack may have started with a compromised DevOps engineer’s laptop. Polymarket says one of its third party providers was compromised. The Binance hack and Polymarket breach aren’t known to be connected, but both exposed a similar weakness. Neither required the underlying blockchain to fail.

At Binance, the attacker reached systems capable of submitting withdrawal transactions. The exchange says it has found “no evidence of any wallet private key leak.” About US$3 billion has been frozen onchain, and Binance says customers won’t absorb the loss. Deposits are operating normally. Withdrawals remain paused while the exchange rebuilds parts of the withdrawal service.

Polymarket faced a different failure. Its international exchange entered cancel only mode at 2:05 p.m. ET, identified the compromised provider at 2:37 p.m., prepared to resume trading at 2:55 p.m. and marked the incident resolved at 3:05 p.m. Polymarket says “Anyone who has been impacted will be made whole.” The platform is operating again, but full reimbursement of every affected user hadn’t been independently confirmed at the latest verification cutoff.

Binance shows what can happen when attackers reach the systems that authorize money movement. Polymarket shows how hostile code can reach customers through software sitting between them and the market. In both cases, the financial rails could keep processing instructions after the instructions themselves had been compromised.

The Binance Hack Starts Before the Money Moves October 28 to 29

The theft looks almost instant in a headline. It wasn’t. TRM Labs says activity tied to the Binance operation began at least 36 hours before the main withdrawals. Its reconstruction found funding, testing and preparation before most of the money left in roughly 20 minutes starting around 20:05 UTC on October 29.1

TRM attributes the Binance hack with high confidence to North Korea’s TraderTraitor operation. Binance hasn’t made that attribution, and no public law enforcement finding had confirmed responsibility for this attack at the latest verification cutoff.

The money moved in minutes. The operation appears to have been prepared much earlier.

What the North Korea Attribution Actually Means

TRM says its assessment draws on onchain and offchain intelligence and similarities with earlier TraderTraitor operations. The firm points to advance preparation and transaction behaviour that it says match previous North Korea linked attacks.

There is history behind that assessment. In February 2025, the FBI formally attributed the US$1.5 billion Bybit theft to North Korea and identified the activity as TraderTraitor.2

That earlier attribution doesn’t prove who attacked Binance. Binance hasn’t identified the perpetrator. Until law enforcement reaches its own conclusion, North Korea remains an attributed assessment rather than a confirmed finding.

TRM estimates approximately US$6.36 billion moved from Binance wallets across ten blockchains. Elliptic independently calculates about US$6.43 billion.

Binance’s official estimate remains approximately US$6.3 billion. Different pricing times produce small differences, but all three calculations land around the same extraordinary number.

US$6.3 Billion Spreads Across Ten Blockchains October 29

Elliptic estimates roughly US$3.80 billion left through Ethereum based assets alone. Another 18,270 BTC worth about US$1.48 billion moved, together with hundreds of millions of dollars across Tron and other networks.3

This wasn’t one token leaving one wallet. Assets moved across different networks and different forms of money before Binance stopped withdrawals.

The recovery options split immediately. Stablecoin issuers could freeze supported tokens. Bitcoin and ether could be watched moving across public ledgers, but no issuer could switch them off.

The asset the attacker held started determining what Binance could get back.

Where Most of the US$6.3 Billion Went

Elliptic calculates US$3.80 billion on Ethereum, including about US$1.9 billion of USDT and US$823 million of USDC. It also identified 18,270 BTC worth about US$1.48 billion and roughly US$612.7 million of USDT on Tron.

Most of the stolen value therefore sat in a small number of large positions, but those positions didn’t carry the same recovery rights. Tether and Circle could intervene in their tokens. No company could impose the same freeze on native bitcoin.

Token prices can change the dollar value. The control rights don’t change with the price.

Binance Says the Private Keys Didn’t Leak October 29 to 30

Binance’s most surprising technical finding so far is what the attacker apparently didn’t steal. The exchange says it has found no evidence that wallet private keys leaked. Its initial investigation points instead to a compromised DevOps engineer’s laptop that may have opened access to a service container used to submit unauthorized withdrawals.

The investigation has since widened beyond one computer. Binance says the incident involved multiple factors and that its security team is tracing the complete attack path through the withdrawal system.4

Independent investigators go further. TRM believes Binance’s signing infrastructure was compromised. Elliptic reached a similar conclusion after examining signed withdrawals across several chains and prepared authorizations on Ethereum.

Binance has promised a full technical postmortem once the investigation is complete.

If the forensic reconstruction holds, the attacker didn’t need the keys. Reaching the machinery deciding what those keys should sign was enough.

NCFA saw a striking variation of the same problem only weeks earlier. How 4,000 BTC Left Liquid Network Without A Stolen Key showed how nearly an entire reported Bitcoin reserve could leave through an apparently valid process even when the obvious authorization key remained intact.

A compromised employee device can sit several steps away from a private key and still reach systems that decide which transactions get signed.

For an exchange, authorization controls become part of custody whether the private key leaks or not.

The Race to Freeze Billions Begins Minutes After the Theft

Once the withdrawals landed, the attacker started changing the asset mix. Stablecoins such as USDT and USDC can be frozen by their issuers under certain conditions. Bitcoin and ether can’t.

Elliptic estimates roughly US$786 million of stablecoins was converted before freezes took effect. Some swaps were completed at prices well below prevailing market value. Getting out appeared to matter more than getting a good price.

TRM separately traced large USDT conversions into ETH. It also found an attacker wallet using USDT as collateral in Aave to borrow ETH before controls tightened.

The attacker was willing to lose money to hold assets that were harder to stop.

The First Hour Became a Stablecoin Freeze Race

Elliptic says the attacker’s main Ethereum wallet received stolen USDT at 20:24 UTC. Tether froze about US$1.18 billion of USDT 37 minutes later and then followed funds into additional attacker addresses.

Circle froze about US$823 million of USDC in the same main wallet soon afterward. Ripple, World Liberty Financial, Paxos, First Digital and other ecosystem participants also acted on supported assets.

By 08:00 UTC on October 30, Elliptic had independently verified about US$2.84 billion frozen. Binance later put the verified total at roughly US$3 billion. Attack speed and issuer response were competing in real time.

Tether, Circle and other issuers could immobilize supported balances while stolen assets were still moving.

Bitcoin and ether stayed visible but movable. Tracing the money and controlling the money were two different powers.

Frozen Crypto Isn’t Recovered Crypto October 30

The US$3 billion frozen figure sounds like half the money came back. It didn’t.

A frozen stablecoin balance may no longer be movable, but Binance doesn’t automatically possess it again. Returning the asset can still depend on issuer action, legal process and cooperation across companies and jurisdictions.

Investigators can also know exactly where bitcoin or ether sits without controlling it. Binance can separately replace assets from its own balance sheet even while stolen funds remain frozen or under attacker control.

Frozen, recovered and reimbursed are three different numbers.

Binance Recovery Snapshot
Estimated impact
US$6.3B
Frozen onchain
~US$3B
Company resources allocated
US$6.34B+
Final recovery
Not yet known

NCFA visualization. Sources include Binance, Elliptic and TRM Labs. Frozen assets aren’t the same as recovered assets or customer reimbursement.

Binance Puts US$6.34 Billion Behind Customer Losses October 30

Binance then changes the financial story.

The exchange says it has allocated more than US$6.34 billion of company resources to cover the incident. About US$5 billion is already held in affected token assets. Binance says it is buying the remaining assets through market and over the counter channels so the replacement portfolio matches what was lost.5

Those figures don’t include the roughly US$3 billion already frozen.

Binance is replacing its asset position while the recovery effort continues separately. SAFU alone is far smaller than the incident, so protecting customers depends heavily on broader company resources.

A US$6.3 billion hack is now testing Binance’s liquidity, reserves and ability to absorb a loss without passing it to customers.

What Binance Still Has to Replace and Prove

Estimated impact is about US$6.3 billion.

Company resources allocated exceed US$6.34 billion.

Matching affected tokens already held total about US$5 billion.

Remaining replacement purchases are roughly US$1.34 billion.

Frozen onchain stands at roughly US$3 billion and is separate from the company allocation.

The technical postmortem and updated Proof of Reserves are still pending. Those releases should show what failed, what changed and whether customer liabilities remain fully backed after remediation.

Binance Update October 30

“Withdrawals remain paused while our team completes a security revamp.”

Binance says deposits are operating normally and expects withdrawals to resume within 48 hours. View the official Binance update.

Polymarket Breach Halts Trading for One Hour October 29

Polymarket’s breach followed a different path.

Its international exchange entered cancel only mode at 2:05 p.m. ET. At 2:37 p.m., Polymarket said a third party provider had been compromised and the issue was fixed. Trading was prepared for restart at 2:55 p.m., and the incident was marked resolved at 3:05 p.m.

Reuters identified the provider, through a source familiar with the matter, as DebugBear, a website performance monitoring company. DebugBear separately acknowledged its own security incident and advised customers using its Real User Monitoring product to remove the embedded code.6

Polymarket hasn’t publicly named the provider. Its international platform is now operational.

The exchange came back in an hour. Customer recovery took a different clock.

Polymarket Incident Record
2:05 ET
Trading enters cancel only mode and relayer actions pause.
2:37 ET
Polymarket says a third party provider was compromised and the issue was fixed.
2:55 ET
Trading restart is announced.
3:05 ET
The incident is marked resolved.

View Polymarket’s official incident record

How the Polymarket Breach Reached Logged In Traders

Security researchers recovered malicious JavaScript distributed through infrastructure linked to the compromised monitoring service. The code checked whether a Polymarket visitor was already logged in, then examined balances and prediction market positions.7

Depending on the account setup, the script could try to sell positions, transfer position tokens or move cryptocurrency. Researchers didn’t identify a routine whose central purpose was stealing a password, seed phrase or private key. The code reused authority already available inside the authenticated application.

One outside analysis traced the attack path through 710 deposit wallets and 731 addresses, while stressing that the address count doesn’t equal the number of victims. A customer could authenticate correctly and still encounter hostile software after login.

Polymarket hasn’t confirmed a final loss figure or victim count. Outside estimates range from about US$2.2 million to US$2.7 million.

Polymarket says affected users will be made whole. Full reimbursement hadn’t been independently verified at the latest cutoff.

Polymarket Is Hit Through a Vendor Again June to October 2026

October isn’t Polymarket’s first recent third party compromise.

In June, Polymarket confirmed that a compromised outside vendor allowed malicious code into its website for some users. The company acknowledged that funds were stolen and said victims would be refunded in full. Outside researchers estimated losses around US$3 million.8

Four months later, another outside service sits inside another loss event.

The company has also been moving deeper into regulated financial markets. Polymarket Earns Approval to Relaunch in the U.S. followed its return path after acquiring a regulated derivatives exchange and rebuilding access to the American market.

The business is becoming more institutional while its customer experience still depends on monitoring tools, browser code, authentication services and outside software.

Polymarket can decentralize parts of the market without decentralizing every dependency needed to reach it.

The Weak Point Moves Outside the Blockchain 2025 to 2026

The Binance hack and Polymarket breach are separate, but both cut through the old idea that crypto security is mainly about protecting a private key.

In February 2025, attackers stole roughly US$1.5 billion from Bybit. The FBI later attributed the theft to TraderTraitor. Investigators said the attack manipulated the approval process around a legitimate transaction rather than breaking Ethereum itself.

Now Binance says its wallet private keys appear intact while investigators examine the systems around transaction approval. Polymarket’s market also kept functioning while malicious web code allegedly reused authority inside logged in customer sessions.

The blockchain can keep doing exactly what it is told after the instruction itself has been compromised.

Founders and institutions building on digital assets can’t treat security as a wallet problem alone. Employee devices, access rights, transaction limits, supplier controls and approval workflows all sit inside the same chain of trust that protects the assets.

What the Binance Hack Means for Canada October 2026

Five days before the Binance and Polymarket incidents, Canada published proposed Stablecoin Regulations for consultation.

The proposed rules require covered issuers to maintain reserves at least equal to outstanding stablecoins at the end of each day, use qualified Canadian custodians and support redemption at par. They also add governance, risk management, data security, incident reporting, recovery and resolution requirements. Consultation closes December 23, 2026, with implementation intended for fall 2027.9

NCFA’s Canada Proposes Stablecoin Market Entry Rules examines the commercial choices created by that framework. The Binance hack makes one of those choices unusually visible. Stablecoin issuers weren’t passive observers after the theft. Their ability to freeze supported assets changed the recovery picture by billions of dollars.

Canada’s proposed rules don’t govern the Binance or Polymarket incidents, and there is no basis to claim they would have prevented either one.

Canadian banks, PSPs, wallets and fintechs still face the same operating questions. Who can authorize the transaction, who can stop it, which suppliers can touch it and who carries the loss when the control chain breaks?

Binance also carries unusual Canadian context. Binance Left Canada but the Fight Reached Supreme Court traced how the exchange’s Canadian exit became a wider fight over regulatory reach and company records. This security incident tests a different side of institutional credibility. Binance now has to show that its own controls can withstand a failure large enough to move billions.

What Binance and Polymarket Still Have to Prove

Binance hasn’t finished proving the recovery works just because deposits are back. Withdrawals still have to resume without reopening the weakness that forced them to stop. The exchange also needs to show that replacement assets fully support customer liabilities after billions moved out. Its promised postmortem needs to explain how unauthorized withdrawals passed internal controls and what changed before the system reopened.

The updated Proof of Reserves will put numbers behind the customer protection promise. Binance says customers won’t absorb the loss. Reserve data can show whether the assets behind customer balances have actually been restored.

Polymarket isn’t finished once trading comes back either. Affected users still need to be fully reimbursed. Two third party compromises in four months also leave a harder question over the business. **How much outside software should be able to touch an authenticated customer session before the market itself becomes exposed?**

The Binance hack showed that a platform can lose billions without evidence that its private keys were stolen. Polymarket showed that a market can remain technically intact while hostile code reaches customers through a supplier. Stablecoin issuers then froze billions of dollars that native bitcoin and ether issuers couldn’t freeze because no such issuer exists. Binance’s own balance sheet became the backstop after those controls ran out.

That is where the competitive line in digital finance is moving.

The strongest platforms won’t be the ones that simply claim secure infrastructure. They’ll be the ones that can **limit what a compromised employee, supplier or software component can do, stop bad instructions before settlement, isolate losses quickly and carry the financial weight when prevention fails**.

Binance and Polymarket are now being measured on exactly that.

The blockchain may settle the transaction. Trust won’t come from the blockchain alone. It will depend on everything that happens before an instruction reaches the chain and everything a company can still do after something goes wrong.

Frequently Asked Questions

Were Binance private keys stolen
Binance says it has found no evidence that wallet private keys leaked. Its investigation points to a compromised employee laptop, service infrastructure and a wider attack path. Independent investigators believe transaction signing infrastructure was compromised, but Binance’s complete technical postmortem is still pending.
Has Binance recovered the US$3 billion
No. Binance says roughly US$3 billion has been frozen onchain. Frozen assets aren’t automatically returned. Actual recovery can still require issuer action, legal process and cooperation across several institutions.
How did the Polymarket breach happen
Polymarket says a third party provider was compromised. Independent researchers found malicious JavaScript that could interact with authenticated user sessions and attempt to sell positions or transfer assets. Polymarket hasn’t yet published a complete technical postmortem.
How much did Polymarket users lose
Polymarket hasn’t published a final loss figure or victim count. Outside estimates currently range from about US$2.2 million to US$2.7 million. Polymarket says anyone affected will be made whole, but full reimbursement hadn’t been independently confirmed at the verification cutoff.

Related NCFA Intelligence

Digital Asset Security

How 4,000 BTC Left Liquid Network Without A Stolen Key

How nearly an entire reported Bitcoin reserve left through an apparently valid process even though the obvious authorization key remained intact.

Binance

Binance Left Canada but the Fight Reached Supreme Court

How Binance’s Canadian exit became a wider test of regulatory reach, company records and access to digital asset markets.

Prediction Markets

Polymarket Earns Approval to Relaunch in the U.S.

How Polymarket moved back toward regulated US market access after acquiring a licensed derivatives exchange.

Stablecoins

Canada Proposes Stablecoin Market Entry Rules

Canada’s proposed rules put reserves, custody, redemption, data security and recovery directly into the stablecoin operating model.


NCFA Canada logoThe National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter


NCFA Weekly Fintech Intelligence Oct 17-Oct 23, 2026

Oct 17, 2026 | Last Updated: Oct 30, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Competition And Market Structure, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Identity And Trust, Embedded Finance, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, Sustainable Finance ESG And Financial Inclusion, Digital Banking And BaaS, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading, Open Banking Open Finance And Data Sharing

Fintech market intelligence visualization

] Image: Freepik

This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-March 13, 2026, March 14-March 20, 2026, March 21-March 27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-June 12, 2026, June 13-June 19, 2026, June 20-June 26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-July 24, 2026, July 25-July 31, 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026, September 5-September 11, 2026, September 12-September 18, 2026, September 19-September 25, 2026, September 26-October 2, 2026, October 3-October 9, 2026, October 10-October 16, 2026).

Weekly Fintech Market Intelligence Oct 17 - Oct 23, 2026

Digital Banking And BaaS

Sezzle Files to Establish a U.S. National Bank

October 22, 2026, United States
  • Sezzle filed an application with the Office of the Comptroller of the Currency to charter Sezzle Bank, N.A. and separately applied to the Federal Deposit Insurance Corporation for deposit insurance.
  • If approved, the bank would offer FDIC insured checking and savings accounts along with credit products. Sezzle says it would focus on digitally native consumers, including people who are new to credit or prefer buy now pay later products over traditional credit cards.
  • A national charter would bring Sezzle Bank under OCC supervision for safety and soundness, consumer compliance, Bank Secrecy Act and anti money laundering controls, and fair lending. Sezzle also plans to become a bank holding company supervised by the Federal Reserve.

Sezzle is trying to move from distributing credit through banking partners toward owning a federally supervised banking platform. If approved, that would give it more control over deposits, credit products, funding and customer economics. The next signals are OCC and FDIC decisions, capital requirements and how much of Sezzle's current partner model eventually moves inside the bank.

NORTHGUARD Buys Wiseday to Build Canadian Mortgage Lender

October 20, 2026, Canada
  • NORTHGUARD Financial launched as a Canadian mortgage lender and servicer and announced its purchase of Wiseday, an established mortgage lender in Quebec. Financial terms weren’t disclosed.
  • The company combines a Canadian built, AI enabled lending and servicing platform with Wiseday’s lending operations. It plans to serve brokers, capital partners and homeowners across prime and alternative mortgages.
  • A national rollout is planned through 2027. The announcement doesn’t establish that every product or market is already live.

Mortgage technology only earns its place when it improves underwriting, servicing and broker economics. NORTHGUARD has acquired an operating base rather than starting with software alone. Founders and capital partners should watch how quickly it expands beyond Quebec, how it funds mortgages and whether faster decisions translate into stronger loan performance.

Ramp Applies for US National Trust Bank Charter

October 19, 2026, United States
  • Ramp publicly announced on October 19 that it submitted an application to the Office of the Comptroller of the Currency (OCC) on October 16 to establish Ramp National Trust Bank.
  • If approved, the proposed national trust bank would provide fiduciary investment management and digital asset custody under federal supervision. It would not accept deposits or make commercial loans.
  • The proposed bank would operate alongside Ramp's existing banking partners. No charter approval or launch date has been announced. Ramp recently raised US$1.85 billion at a US$60 billion valuation.

Ramp is seeking direct control over regulated investment and custody capabilities rather than relying entirely on external providers. Following its recent funding and expansion, the charter application adds another route for the company to broaden its financial services business. The key tests are OCC approval, which capabilities Ramp brings in-house, and how the new entity would work alongside existing bank partners.

SoFi Launches 4.40% Tokenized Consumer Bank Deposit

October 22, 2026, United States
  • SoFi launched SOFIE, an interest-bearing tokenized consumer deposit representing US$1 held at SoFi Bank. The advertised yield at launch is 4.40% APY, with applicable FDIC insurance limits.
  • Members can convert SOFIE at a 1-to-1 rate into SoFiUSD to make blockchain transfers or buy crypto. SOFIE is a bank deposit; SoFiUSD is a separate payment stablecoin.
  • SoFi says customers can access SOFIE through its crypto account. The 4.40% APY is variable, and deposit insurance applies only to qualifying funds within the relevant limits.

SoFi is testing whether customers will keep digital dollar balances at a bank until they need to transact. The split between an insured deposit and a transferable stablecoin is commercially important because the legal protections change at conversion. Banks and fintechs should compare yield, redemption terms and access rather than treating both tokens as the same product.

Finom Opens Permissioned Business Account Data to AI Assistants

October 22, 2026, Netherlands / Europe
  • Finom launched an MCP connection for ChatGPT and Claude that lets business customers ask questions about transactions, invoices, cards and accounting data in natural language.
  • The service is available across Finom plans in Europe to a customer base the company puts at more than 300,000 businesses. Customers authenticate with Finom and can revoke the connection.
  • Access is limited to the user’s existing account permissions. The current connection is read-only; it cannot initiate payments, issue cards or change account settings.

Banks are starting to offer controlled data access where customers already work with AI, rather than forcing every question back into a banking app. Finom’s read-only design keeps the risk boundary relatively clear. The test is whether business owners use it routinely and whether future payment permissions can be added without sacrificing that control.

Artificial Intelligence And Data

Starling Bank Deploys AI Investigator for Financial Crime

October 21, 2026, United Kingdom
  • Starling Bank disclosed that its agentic financial crime investigator has been operating for about three weeks inside the bank’s core banking engine. The disclosure came from its chief customer and banking officer, Bernadette Smith.
  • Smith says the system investigates transaction monitoring alerts, records its audit trail and returns a reasoned decision in less than 17 seconds per alert. She compares that with 15 to 30 minutes of manual review.
  • The system uses Starling’s own data and model, with access to live transaction context. The bank hasn’t published independently tested accuracy rates, false positive results or cost per investigation.

A bank can now test whether AI cuts investigation costs without losing control of the decision trail. Starling’s approach also raises the bar for vendors that sit outside the banking core. But speed isn’t enough. Compliance teams still need to know when a decision should be challenged, who owns an error and whether the economics hold across higher risk cases.

ECB Tells Banks to Submit AI Cyber Risk Action Plans

October 20, 2026, Euro Area
  • The European Central Bank says supervised banks are expected to submit concrete action plans by the end of October showing how they will address cyber risks created by more capable AI systems.
  • The ECB asked banks to reassess cybersecurity measures as well as related IT budgets and staffing. It warns that advanced AI can find and exploit vulnerabilities faster than existing defensive processes may respond.
  • Supervisory concerns extend beyond cyber attacks. The ECB also flags model dependence, bias, poor data quality and concentration risk where banks rely heavily on a small group of cloud providers.

AI risk is moving from broad supervisory concern into bank level remediation work. The practical question is no longer whether banks recognize the threat. It's whether they can show the ECB who owns the risk, what systems need investment and how quickly controls can change as models become more capable. NCFA first tracked the supervisory direction in ESRB Warns Frontier AI Models Could Strain Cyber Resilience. The October action plans turn that warning into an execution deadline.

FCA Publishes AI Practices for Financial Firms

October 19, 2026, United Kingdom
  • The Financial Conduct Authority published examples of good practice and areas for improvement in financial services AI, drawing on supervisory work, AI Live Testing and its Supercharged Sandbox. The examples apply to machine learning, generative AI and agentic AI.
  • The FCA says existing requirements already apply when firms use AI. Its examples cover consumer outcomes, governance, monitoring, senior management accountability, human oversight, operational resilience and third party dependencies. The publication does not create new requirements.
  • Good practices include testing outcomes before deployment, maintaining auditable records, setting clear escalation routes and monitoring live performance. Weak practices include unclear ownership, retrospective governance, poor documentation and reliance on AI vendors without enough testing or exit planning.

The FCA has made current obligations easier to test against real deployment patterns without creating a separate AI rulebook. Firms can compare their controls with concrete supervisory examples before weak ownership, monitoring or vendor dependence becomes an operating problem. NCFA has been tracking the same AI governance and compliance costs as financial institutions move from experiments into live workflows.

Capital Markets Infrastructure And Funding

SEC Registers Cboe Clear U.S. to Clear Binary Securities Options

October 22, 2026, United States
  • The U.S. Securities and Exchange Commission granted Cboe Clear U.S. temporary registration as a securities clearing agency, expanding its authority beyond futures and swaps into securities products.
  • The registration allows Cboe Clear U.S. to provide central counterparty clearing for binary securities options. Cboe says its first use will be clearing binary options tied to specified corporate key performance indicators that are planned for Cboe Options Exchange and Robinhood.
  • The approval creates another registered clearing route for securities options alongside the existing U.S. clearing infrastructure. Cboe Clear U.S. is already registered with the CFTC as a derivatives clearing organization.

This expands the market infrastructure available for event driven securities products before the products themselves reach investors. The commercial test is whether Cboe and Robinhood can turn the new clearing authority into meaningful trading volume while keeping the risk, margin and settlement controls expected of regulated securities markets.

LSEG Agrees to Buy Octus for US$3.535B

October 22, 2026, United Kingdom / United States
  • London Stock Exchange Group agreed to acquire Octus for US$3.535 billion in cash, moving beyond the acquisition talks it confirmed on October 13. Closing is expected in the first half of 2027, subject to regulatory approval.
  • Octus serves 750 customers and more than 40,000 users across private, illiquid and distressed credit. It has more than 900 employees and expects over US$300 million in 2026 revenue with an adjusted EBITDA margin of about 40%.
  • LSEG plans to combine Octus data and workflows with Workspace, LPC, Yield Book, PRS and Tradeweb. Octus also distributes data through an MCP connector and AI workflows, giving LSEG another route into private credit research and decision tools.

Private credit is becoming too large for market data firms to treat as a side business. LSEG is paying for proprietary information, workflow and distribution in a market it estimates at US$3.5 trillion. Investors should watch whether the deal improves pricing and risk visibility in less liquid credit or simply concentrates more valuable data inside one platform. The commercial upside depends on cross selling without weakening the specialist product customers already pay for.

Canada Opens C$1.75B Venture and Growth Capital Programs

October 22, 2026, Canada
  • Canada announced C$1 billion for the Growth VCCI, including C$700 million for funds of funds, C$200 million for life sciences and C$100 million for emerging fund managers. The fund-of-funds application window closes January 21, 2027.
  • A separate C$750 million Early and Growth Stage Investment Strategy allocates C$75 million to pre-seed and seed activity and C$675 million to later-stage growth. Feedback on the latter stream closes November 23, 2026.
  • The government expects the combined plan to attract at least C$3.8 billion in private capital. This is a projection, not money already raised or invested; BDC will administer the C$750 million strategy.

Fund managers have a new capital application window, but founders still need to meet the investment criteria of the funds receiving public commitments. The capital won’t necessarily reach businesses outside the venture model. The immediate tests are which managers apply, how they attract pension and private capital, and whether founders beyond established funding hubs gain access.

Kalshi and BitGo Let Traders Borrow Against Crypto for Margin

October 22, 2026, United States
  • Kalshi Prime launched HODL Margining with BitGo Bank & Trust, allowing eligible customers to fund dollar trading margin using loans secured by BTC, ETH or eligible stablecoins.
  • Kalshi Katalyst supplies the dollar loans, with proceeds deposited into Kalshi Prime accounts. Pledged assets remain at BitGo in qualified custody rather than being sold or transferred to the trading venue.
  • Kalshi Prime is a CFTC-registered futures commission merchant. The Katalyst loans are not regulated by the CFTC or NFA; borrowers face interest costs, liquidation exposure and additional leverage risk.

This separates collateral custody from the funding used on a derivatives platform. Traders can keep crypto exposure while obtaining dollar margin, but the convenience comes with another lender, security interest and liquidation process. Custodians and brokers should watch collateral valuation, loan terms and who can act when markets gap outside banking hours.

SEC and France AMF Open Registration Cooperation for Asset Managers

October 20, 2026, United States / France
  • The US Securities and Exchange Commission and France’s Autorité des Marchés Financiers entered into a supervisory memorandum of understanding covering cross-border investment adviser, investment company and investment service provider oversight.
  • The arrangement establishes consultation and information sharing between the two authorities for regulated firms operating across their markets.
  • The SEC confirmed it will process new and pending registration applications from AMF-supervised asset management companies seeking to operate as US investment advisers. The agreement is not an automatic registration approval.

French managers seeking US advisory access have a clearer supervisory cooperation arrangement behind their applications. The practical question is how registration processing, compliance preparation and ongoing examination responsibilities operate under the memorandum. Asset managers expanding internationally should distinguish the renewed application pathway from permission to begin serving clients without SEC registration.

Malaysia Launches Tokenized Bond and Sukuk Infrastructure

October 20, 2026, Malaysia
  • Bank Negara Malaysia launched SSDS+, a new platform for issuing, depositing and safeguarding tokenized bonds and sukuk across Malaysia's financial market.
  • The system builds on Malaysia's existing Scripless Securities Depository and can support wholesale issuance as well as tokenized government and corporate retail bonds.
  • SSDS+ connects with RENTAS+ for secure payment and settlement around the clock. Securities ownership moves through SSDS+, while the cash leg can settle in central bank money.

Malaysia has moved tokenized fixed income into core market infrastructure rather than leaving it in a pilot. That matters because issuance, ownership records and settlement now sit inside infrastructure controlled by the central bank. NCFA previously tracked the earlier groundwork in Bank Negara Malaysia Onboards Ringgit Stablecoin And Tokenized Deposit Pilots. The next test is issuance volume and whether banks, governments and corporate borrowers start using the new rails regularly.

UK CMA Proposes Fairer iPhone Contactless Access

October 20, 2026, United Kingdom
  • The Competition and Markets Authority opened a consultation on a proposed NFC access conduct requirement for Apple’s mobile platform under the UK digital markets competition regime.
  • The proposal would require access for third-party developers on fair, reasonable, transparent and nondiscriminatory terms, addressing access fees and commercial restrictions.
  • The CMA is considering access through both secure element and host card emulation. Responses close November 17, 2026; no final conduct requirement has been imposed.

Mobile wallet providers and fintechs could gain more control over how contactless services reach iPhone users. Fees, available technical methods and contractual access are the practical questions. Firms considering wallet or account-based payment products should examine the consultation now, rather than planning around terms that have not yet been finalized.

Cross Border Payments And FX

Western Union Picks Noah for Stablecoin Remittances

October 20, 2026, United States / United Kingdom / Global
  • Western Union selected Noah to provide stablecoin payment infrastructure for its planned Receiver Redirect service. Noah says the service is designed for more than 60 currencies across over 200 countries and territories.
  • The design uses USDPT issued by Anchorage Digital Bank on Solana. Noah will support the treasury, conversion and payment infrastructure behind the proposed service.
  • Western Union operates more than 500,000 agent locations. The announced network reach describes the intended service footprint, not completed stablecoin transaction volumes or a fully live rollout.

Western Union already has customer distribution and cash access. The harder work is fitting a stablecoin rail into local payout rules, liquidity and customer support. Noah gains an important infrastructure role, but both firms still need to show where customers can actually use the service and whether fees fall without making redemption harder.

Newline and Visa Open Corporate Card Issuing in 40+ Countries

October 19, 2026, United States / Global
  • Eligible US fintechs can now offer Visa corporate cards for approved business use in more than 40 countries through Newline by Fifth Third and Visa's Multinational Program.
  • Cards are issued for local use in each approved country, so transactions are authorized in local currency and processed more like domestic card payments. Newline says the coverage exceeds that of any other bank issuing through the Visa program.
  • The service is aimed at fintechs including expense platforms, HCM providers and vertical software companies. Availability still depends on client, country, regulatory, sanctions and financial crime requirements.

Cross border card programs become expensive when every new country needs another bank relationship and operating stack. Newline is using Fifth Third's balance sheet and Visa's network to give fintechs one route into more than 40 markets. The opportunity is meaningful for software platforms serving global employers and businesses. The real test is whether local authorization and issuing reduce fees and failed transactions enough to justify the added compliance work.

Fiserv Opens Commerce Hub Globally for Cross Border Payments

October 19, 2026, United States / Global
  • Fiserv made Commerce Hub globally available, giving enterprise merchants one connection to local payment methods, acquiring, settlement, reconciliation, reporting and operational controls across markets.
  • Fiserv reports that Commerce Hub supports several billions in processing volume and is growing more than 100% year over year across multiple industries, payment methods and business models.
  • Dell Technologies is using Commerce Hub to support a more unified commerce model and introduced Pix in Brazil through the platform. Fiserv also combines fraud protection, payment optimization and emerging payment methods within the same operating environment.

Fiserv is selling fewer integrations as a cross border growth advantage. Large merchants can add local payment methods without rebuilding settlement, reporting and operational controls market by market. The commercial test is whether that consolidation lowers total payment costs and speeds expansion enough to outweigh the value of using specialized providers in individual countries.

Three Central Banks Expand BLOOM Digital Money Settlement

October 23, 2026, Singapore / Malaysia / Thailand
  • Bank Negara Malaysia and the Bank of Thailand joined Singapore’s BLOOM initiative as policymaker members to develop cross-border use of tokenized deposits and regulated stablecoins.
  • Participants will work on acceptance and settlement, interoperability, and programmable controls covering identity, sanctions and transaction restrictions.
  • New participants include Airwallex, Mastercard, Maybank, Monee, Nium, Ripple, Visa and the World Bank Group. The announcement establishes a joint development effort, not a live shared settlement network.

Cross-border digital money won’t scale if every bank has to negotiate a different settlement and compliance arrangement in every market. BLOOM puts three central banks at the table with the providers building those connections. Operators should follow the actual commercial agreements, supported assets and settlement rules, not just the growing participant list.

Cybersecurity Fraud And Financial Crime

Mastercard Introduces Stablecoin Payment Risk Intelligence

October 19, 2026, United States / Global
  • Mastercard introduced Stablecoin Security, an API-based risk intelligence offering that combines payment context and blockchain analytics across fiat and stablecoin payment flows.
  • The service assesses transaction origin, sanctions exposure, potential scams and other risks before payment completion, with outputs designed for existing fraud, compliance and case management workflows.
  • Borderless.xyz and Keyrails are initial partners. The product is launching first in North America, with wider commercial availability expected during 2027; Mastercard has not published product-specific transaction volumes.

Stablecoin payments are being fitted into existing institutional fraud and compliance operations rather than treated as a separate risk channel. Banks and payment providers will need to test whether the combined intelligence improves decisions across conversion, transfer and payout stages, and how responsibility is divided between partners when a suspicious transaction is held or rejected.

Skyfire and Forter Test Agent Identity at Checkout

October 19, 2026, United States
  • Forter integrated Skyfire Know Your Agent identity data into its existing checkout fraud decisions, distinguishing authorized buying agents from suspicious automated activity.
  • The partners completed a pilot with online retailer Jomashop, which reported nearly 100% checkout success for tested agentic traffic without an increase in chargebacks.
  • Forter reported a more than fourfold increase in agentic orders across its network since August. The Jomashop result is a customer-specific pilot finding, not a network-wide checkout success rate.

Agent-driven commerce needs a way to recognize authorized software without giving fraudsters a free pass. Identity signals that enter the merchant’s existing risk engine offer one practical approach. The next test is whether checkout performance holds across more merchants, higher transaction volumes and contested payments, where evidence of the human mandate matters as much as recognizing the agent.

Digital Assets Blockchain And Tokenization

Participate Uses Tokenized Deposits for Bank Loan Payment

October 19, 2026, United States
  • Vantage Bank and Rio Bank completed a principal and interest payment on a loan participation using tokenized deposits through Participate and Hazel Network.
  • The payment moved between the two Texas banks in less than three minutes. Loan balances and payment notices updated automatically as the funds moved instead of arriving through separate processes.
  • Participate describes the transaction as a first for loan participation or syndication payments between financial institutions using tokenized deposits. The result proves one transaction flow, not broad production volume across the loan market.

Loan participation payments are still full of reconciliation work after the money arrives. Moving the payment and loan records together attacks that operating cost directly. Banks should care less about the token label than whether the process shortens settlement, reduces exceptions and keeps every participant on the same loan balance. Repeat volume across more institutions would turn this from a useful transaction into infrastructure.

JPMorgan Takes JPM Coin Live on Ethereum

October 19, 2026, United States / Global
  • Kinexys by J.P. Morgan made JPM Coin (JPMD), its US dollar deposit token, available on Ethereum mainnet to J.P. Morgan institutional clients, following its earlier rollout on Base.
  • The token gives eligible institutions a form of bank deposit money for activity involving blockchain-based assets and transactions, rather than requiring a stablecoin issuer outside the bank.
  • The announcement establishes Ethereum network availability; it does not disclose separate JPMD-on-Ethereum transaction volumes or make the token generally available to retail users.

Institutional settlement now has another bank deposit option on a public blockchain where tokenized assets already trade. Treasury and digital asset teams can compare the legal claim, eligible counterparties, network access and liquidity against stablecoin-based settlement. The commercial test is whether institutions use the additional network for regular transactions, not simply as another technical connection.

Revolut Gets Gibraltar DLT Licence for Global Crypto Expansion

October 19, 2026, Gibraltar
  • The Gibraltar Financial Services Commission granted Revolut Global Digital Assets Limited authorization as a Distributed Ledger Technology provider under Gibraltar's Financial Services Act.
  • The permission covers the transmission and execution of virtual asset orders, virtual asset custody and staking services. Gibraltar's government also confirmed that Revolut has resumed onboarding local residents to its payments app.
  • Revolut reports more than 80 million retail customers and over 16 million crypto users. The company plans to use the Gibraltar entity to support international digital asset expansion, but target markets and rollout dates have not yet been announced.

Revolut now has another regulated entity it can use to expand crypto services without relying on one licensing base for every market. The value will come from where the Gibraltar permission actually opens distribution, custody and staking at scale. Investors should watch which markets are added, how quickly customers migrate to the new entity and whether regulatory expansion improves revenue without adding disproportionate compliance cost.

Wealthtech Investing And Trading

FINMA Approves Switzerland's First Retail Bitcoin ETF

October 20, 2026, Switzerland
  • FINMA approved Switzerland's first exchange traded retail fund that invests directly in Bitcoin, opening a regulated fund route that was previously limited to qualified investors.
  • The regulator granted an exception from normal diversification rules because Bitcoin has a longer trading history and higher volume than other cryptocurrencies. The fund remains subject to operational and custody safeguards, clear risk disclosure and Swiss conduct rules.
  • FINMA stressed that Bitcoin remains highly volatile and investors can lose a substantial amount of capital. Other providers have also submitted or announced applications for Bitcoin ETFs.

Switzerland already had deep crypto infrastructure, but retail fund approval changes distribution. Wealth platforms and advisers can now offer Bitcoin through a supervised investment product instead of pushing every customer toward direct ownership. The advantage is easier custody and familiar fund controls. The risk doesn't disappear, and competing providers will still have to win on fees, liquidity and investor trust.

Digital Identity And Trust

TerraPay Verify Joins JPMorgan Liink for Payee Checks

October 22, 2026, United Kingdom / United Arab Emirates / Global
  • TerraPay Verify has integrated with Kinexys by J.P. Morgan's Liink Confirm, giving connected financial institutions and nonbank providers access to bank account and digital wallet verification before sending a payment.
  • The integration checks recipient details before money moves. TerraPay cites research estimating that 10% to 15% of international payments fail because beneficiary information is wrong, creating delays, manual work and fraud exposure.
  • TerraPay says its wider network reaches more than 7.5 billion bank accounts across 156 plus countries and 3.7 billion digital wallets. Those network figures describe TerraPay's reach, not the number of accounts already verified through Liink.

Failed cross border payments are expensive because the bank or fintech still absorbs investigation, repair and customer service costs. Connecting verification across bank accounts and wallets gives institutions a chance to catch bad recipient data before funds leave. The value will show up in lower exception rates and fewer fraud losses. Adoption will depend on how much coverage Liink participants can use without adding another slow step to the payment flow.

European Payments Council Starts EU Wallet Payment Rules

October 19, 2026, European Union
  • The European Payments Council announced SCARLET, an industry rulebook initiative for using EU Digital Identity Wallets to authenticate payments. Its board approved the work on September 24 and publicly announced it on October 19.
  • The proposed framework covers shared technical rules, participation terms and responsibility for failed or disputed authentication. It targets interoperability among an expected 3,000 plus payment providers and more than 27 wallet providers.
  • The EPC plans consultation in summer 2027 and a first rulebook in December 2027. No operating scheme has entered into force.

Payment providers can’t afford a different wallet authentication arrangement for every country or partner. A common set of rules could lower integration costs and clarify liability. The industry now has time to shape those rules, but firms shouldn’t treat a published development plan as a completed authentication standard.

World Opens ID Verification Tools for Banking and Finance

October 18, 2026, United States / Global
  • World launched the World ID for banking and finance suite for financial firms seeking to check human presence, identity attributes and interactions involving AI agents.
  • The offering uses cryptographic proofs including Proof of Human, Proof of Presence and Proof of Attributes for customer-facing and internal experiences.
  • Bain Capital, OpenExchange, Outtake, Pantera Capital and VanEck Funds are named initial design partners using the technology. No bank-wide adoption rates or financial transaction volumes were published.

Financial identity checks are extending beyond onboarding into agent interactions, remote approvals and sensitive communications. Firms considering these tools need to test exactly which facts a proof establishes, what data must be retained and who accepts liability if a verified participant still gives fraudulent instructions. Design-partner use is an early distribution step, not proof of broad institutional adoption.

Embedded Finance

Stripe and Anthropic Put Business Payments Inside Claude Duet

October 21, 2026, United States / Ireland
  • Anthropic integrated Stripe Link's wallet for agents and Stripe MCP into Claude Duet, a new app launching in research preview for small business owners and professionals.
  • Owners can ask Claude Duet to make purchases, send invoices and payment links, manage products and prices, analyze revenue and issue refunds. Each purchase still requires owner review and approval before Claude completes it with a virtual card.
  • Stripe says Link already powers payments for more than 200 personal agents. That figure describes Link's broader agent network, not adoption of Claude Duet, which remains in research preview.

AI assistants are moving from advice into execution inside everyday business software. Stripe gives Claude access to payment and commerce tools while keeping the owner at the approval point. For founders, that can cut routine admin without handing an agent open ended spending authority. The commercial question is whether customers trust the controls enough to move real purchasing and finance work into the interface.

Payments Infrastructure And Money Movement

HSBC Puts a Regulated Stablecoin Into Everyday Payments

October 23, 2026, Hong Kong
  • HSBC launched RedCoin, ticker RCHKD, on PayMe as its first regulated Hong Kong dollar stablecoin. The Hong Kong Monetary Authority licenses and supervises the stablecoin under Hong Kong's Stablecoins Ordinance.
  • More than 3.3 million PayMe users can activate a stablecoin wallet and use RedCoin for payments to friends and merchants. PayMe reaches more than 100,000 merchants.
  • HSBC Digital Assets Custody safeguards RedCoin. HSBC also plans to extend its use into tokenized investment products, adding retail payments to a digital asset stack that already includes digital bonds, tokenized gold and wholesale tokenized deposits.

Stablecoin adoption is moving into a bank's existing retail distribution rather than asking customers to adopt a new crypto wallet. That cuts a major onboarding barrier. The numbers to watch now are wallet activation, payment frequency and merchant usage. If customers use RedCoin for ordinary transactions, regulated stablecoins start competing as payment products rather than mainly trading and settlement tools.

Nuvei Wins Israeli Direct Acquiring Licence

October 21, 2026, Canada / Israel
  • Montreal based Nuvei secured a direct acquiring licence in Israel, extending its direct acquiring network to 53 markets. The licence was granted by the Israel Securities Authority under local payment services legislation.
  • Direct access to domestic card acquiring can reduce dependence on intermediary acquirers and give Nuvei more control over authorization, reconciliation and settlement services.
  • Nuvei says it has operated in Israel for 20 years and employs more than 300 people there. The new licence adds local regulated capacity, but the company hasn’t disclosed volumes processed under it.

Payment margins can depend on who controls the local acquiring relationship. Nuvei can now bring more of that work inside its own network instead of paying intermediaries. Merchants should compare actual approval rates and processing costs after implementation. For Canadian payment firms, the licence shows how regulated local access can strengthen international distribution.

Mastercard Opens Agent Pay for Machines to Developers

October 20, 2026, United States / Global
  • Mastercard opened developer early access to Agent Pay for Machines after completing payment pilots with Cloudflare, Ant International, Base, BVNK, Coinbase and other partners.
  • In a demonstration, one approved agent budget covered nine payments to two independent merchants. The agent purchased research and generated images without separate accounts or invoices for each service.
  • The design uses x402 payment requests and signed vouchers. Providers verify purchases as they occur and redeem vouchers later. Buyer and seller APIs, sandbox access and documentation are now available for testing.

Agents that buy software services need spending limits that survive across multiple suppliers. Mastercard is testing a way to approve a budget once without granting open access to company funds. The commercial question is whether developers and merchants adopt one shared payment method instead of creating another patchwork of wallets, credits and billing accounts.

Euronet Launches OLON Merchant Payments Platform

October 21, 2026, United States / Europe
  • Euronet launched OLON, a modular merchant commerce platform that combines in store and online payment acceptance with business applications, settlement monitoring and customer services.
  • Its first planned full market deployment is Greece, with a stated reach of approximately 225,000 merchants, 300,000 physical points of sale and 7,000 online shops. Full deployment is still ahead.
  • Euronet says its merchant services business already operates in more than 15 European countries. OLON is also taking shape in Germany and other Southern European markets.

Euronet wants a larger share of the merchant relationship than payment processing alone. Connecting checkout, reconciliation and business software can improve retention and open new service revenue. Merchants will judge the platform on integration costs and daily usefulness. Competing payment providers should watch whether the Greece rollout turns Euronet’s distribution into a durable advantage.

Visa, BILL and Billtrust Process Live Agentic Invoice Payments

October 20, 2026, United States
  • Visa, BILL and Billtrust launched a live pilot processing end-to-end invoice payments through authorized AI agents acting between buyer and supplier platforms.
  • The BILL Payment Agent uses Visa Trusted Agent Protocol, Agentic Directory and tokenized credentials to access Billtrust supplier portals and complete previously approved payment instructions.
  • The pilot is processing transactions with participating buyers and suppliers. Buyers still authorize the underlying invoice payments, and suppliers retain portal controls; general production scale has not been announced.

Business payment automation is crossing a practical barrier: recognized agents can finish authorized transactions inside supplier portals without a person manually completing every step. Finance teams will need to define mandate limits, approval evidence and exception handling before using this model more widely. Successful pilot transactions are a useful milestone, but broad interoperability and dispute processes remain to be proven.

PPRO Forms Council for AI Payments on Local Rails

October 21, 2026, United Kingdom / Europe
  • PPRO launched a Local Payments Council for Agentic Commerce with BLIK, EPI, Bancontact Company and DIAS to develop common technical approaches for noncard payment methods used by buying agents.
  • The work covers agent identity, delegated consent, authorization handoffs, refunds, disputes, liability and payment method discovery.
  • The council is an industry standards initiative. No unified payment rulebook or production adoption deadline has been announced.

Card networks are designing agent payment protocols, but local bank account and wallet schemes can’t simply assume those rules fit. The council gives payment providers a place to settle the hard questions around mandates, identity and refunds before agents become another checkout channel. Its value depends on usable technical specifications and adoption by real payment schemes.

Treasury Liquidity And Cash Management

Hong Kong Expands Offshore RMB Liquidity Support

October 23, 2026, Hong Kong
  • The Hong Kong Monetary Authority designated 12 banks as Primary Liquidity Providers for the offshore renminbi market for a new two year term beginning October 27, 2026.
  • The dedicated RMB repo facility for those banks increases from RMB20 billion to RMB22 billion.
  • HKMA selects providers based partly on their ability to supply offshore RMB funding and make markets in RMB instruments. The authority can continue adjusting the number of providers and the size of the facility as market needs change.

More official repo capacity gives market makers another liquidity buffer as Hong Kong builds deeper offshore RMB markets. The increase itself is modest, but the control point is important. Banks competing for RMB flows now have stronger public liquidity support behind market making, while exchanges, payment firms and treasury platforms get a deeper funding base for products built around offshore RMB.

HSBC Connects Tokenized Deposits to a Tokenized Money Market Fund

October 22, 2026, United Kingdom / Singapore / Global
  • HSBC completed its first transaction using tokenized deposits to invest in a tokenized money market fund with Ant International and Franklin Templeton.
  • The transaction connected HSBC's Tokenised Deposit Service with Ant International's WhaleRTP wholesale settlement platform and a Franklin Templeton tokenized money market fund.
  • HSBC says the structure can support more efficient, always on liquidity management. Company staff describe the transaction as a pilot, so one completed subscription should not be treated as general commercial availability or recurring volume.

Corporate treasurers leave cash idle when fund cut off times don't match when money becomes available. This transaction shows how tokenized bank money can connect that cash directly to an investment product without rebuilding the treasury stack around a stablecoin. The opportunity is better use of working cash. The business case will depend on redemption speed, fund access and whether the model scales beyond bespoke transactions.

Stripe Opens Business Treasury Tasks to AI Agents

October 21, 2026, United States / Ireland
  • Stripe Treasury for agents lets businesses use AI agents to check balances, pay invoices, transfer money between accounts and convert currencies from tools including ChatGPT and Claude.
  • The service sits inside Stripe Treasury, where businesses already manage banking alongside payments. Companies keep control over account access and permissions rather than giving an agent unrestricted authority.
  • Stripe says card creation and agent spending limits are coming next. Those capabilities aren't part of the current launch and shouldn't be treated as live today.

The important shift isn't that an AI can read a balance. It can now carry out approved treasury work inside the financial account. Founders gain leverage if routine transfers and invoice payments move out of the admin queue without weakening controls. Banks and fintechs will need equally clear permission models because the competitive question is moving from who has an AI assistant to who safely lets it touch money.

Regulation And Policy

SEC Puts AI, Tokenization and Treasury Clearing on Its 2027 Exam List

October 23, 2026, United States
  • The SEC's Division of Examinations published its fiscal 2027 priorities for more than 34,000 registrants, including investment advisers, funds, broker dealers, clearing agencies, transfer agents and funding portals.
  • Emerging technology is now an explicit examination area, including advanced AI that can affect market operations, compliance, fraud controls and investor protection.
  • The SEC will also examine risks around Treasury clearing reforms, tokenization and changing market infrastructure, alongside cybersecurity, customer information, private credit and anti money laundering controls.

AI and tokenization are no longer sitting outside the routine examination cycle. Firms using either in regulated workflows should expect questions about governance, supervision, records, controls and investor outcomes. For infrastructure providers, the combination of Treasury clearing and tokenization also puts implementation risk closer to the examiner's desk, not just the product roadmap.

Canada Sets New Federal Rules for Regulatory Competitiveness and Red Tape Reduction

October 21, 2026, Canada
  • Canada published a new Cabinet Directive on Regulatory Competitiveness and Red Tape Reduction, effective December 31, 2026. It replaces the 2018 directive and applies to specified federal regulations made by or approved by Cabinet, Treasury Board or federal ministers.
  • Regulators must assess and communicate the competitiveness impacts of proposed measures, offset $2 for every $1 increase in business regulatory burden over three years, and consider recognized standards for regulatory alignment across jurisdictions.
  • Significant impact regulations must be reviewed within five years, with other regulations reviewed at least every 10 years. The directive also calls for proportionate regulation, reduced overlap and clearer information on how businesses can introduce innovative products and services.

Regulatory competitiveness now has explicit federal policy requirements, but better outcomes aren't automatic. Fintechs and investors should watch whether impact assessments, burden offsets and regulatory reviews actually reduce entry costs and approval friction. The same questions around OSFI's approach to growth and competition extend across federal regulation: will the new requirements make it easier for credible entrants to launch, scale and compete?

OCC Finalizes US Stablecoin Rules and Leaves Rewards Case by Case

October 21, 2026, United States
  • The Office of the Comptroller of the Currency issued its final GENIUS Act rule for payment stablecoin issuers and certain custody activities under its supervision. The rule takes effect January 18, 2027.
  • The rule covers reserve assets, redemption, risk management, audits, custody, capital and supervision. Issuers still cannot pay interest or yield solely because a customer holds, uses or retains a payment stablecoin.
  • The OCC dropped proposed presumptions that could have treated some third party reward arrangements as prohibited. Existing programs get no automatic safe harbour; the OCC says it will judge arrangements on their facts. Applications haven't opened yet, and anti money laundering and sanctions rules remain subject to separate rulemaking.

The final rule gives stablecoin issuers a clearer operating framework, but rewards remain a competitive fault line between banks and crypto platforms. Exchanges may still have room to pay customers when the reward isn't simply interest for holding a stablecoin, yet there is no blanket approval. Issuers and partners now need structures they can defend under OCC review. For banks, the deposit competition debate isn't settled just because the rule is final.

FCA Clarifies Crypto Licensing Exclusions and Application Relief

October 21, 2026, United Kingdom
  • The Financial Conduct Authority opened consultation CP26/36 on proposed guidance for exclusions from the UK's incoming cryptoasset regulatory perimeter. The exclusions address certain stablecoin payment and settlement arrangements, proprietary trading, market making and technical services.
  • The new cryptoasset regime takes effect October 25, 2027. The consultation closes November 18, 2026, with final guidance targeted for January 2027.
  • The FCA will allow limited application forbearance where uncertainty over the technical services exclusion materially affects a firm's ability to complete its arranging permission application. Existing UK crypto businesses seeking authorization under the new regime must apply between September 30, 2026 and February 28, 2027 to benefit from the savings provision.

Crypto firms need to establish which activities require authorization and which qualify for exclusions before committing to licensing and operating structures. The distinction is particularly important for stablecoin payments, decentralized protocol interfaces and technical service providers. Firms affected by uncertainty over arranging permissions should engage with the FCA during the application window rather than assume that forbearance extends the application deadline.

Canada Proposes Wider Bank and Insurer Investment Powers for Fintech

October 17, 2026, Canada
  • The Department of Finance published four proposed regulations covering more than 400 federally regulated financial institutions, including banks, credit unions, insurers and trust companies. The proposals would activate broader technology and investment powers enacted in 2018 but not yet brought into force.
  • Institutions could undertake a wider range of technology activities without prior ministerial approval and acquire substantial or controlling interests in businesses combining financial and nonfinancial activities. Eligible businesses must generate at least 60% of revenue, operating expenses or assets from financial activities.
  • Large institutions with equity above C$12 billion would face limits of 10% of annual revenue and regulatory capital for covered nonfinancial activities. Smaller institutions could use up to 15% of revenue, with the same 10% capital limit. Large institutions would also face transaction and annual reporting requirements. The changes remain proposed, not effective.

Canada's existing restrictions can complicate fintech investments when a business combines financial services with other commercial activities. The proposed fintech investment reforms would give banks and insurers more room to invest, acquire and build technology businesses while retaining limits on their exposure. Fintech founders could gain access to strategic capital and established distribution networks. The commercial test is whether institutions use that flexibility to expand products and partnerships, rather than simply absorb promising competitors.

UK Proposes Cutting Senior Manager Approval Burden

October 22, 2026, United Kingdom
  • The Prudential Regulation Authority proposed removing prior regulatory approval for almost half of its current Senior Manager Functions, replacing those applications with notifications while keeping firm responsibility for fitness and propriety.
  • The proposal would remove recurring certification requirements for approximately 7,700 individuals and extend temporary senior manager cover from 12 to 18 weeks.
  • Comments close January 22, 2027. Implementation is contemplated in the second half of 2027, subject to legislation and final rules; these changes are not in force.

Hiring senior leaders can take months when every role requires an external approval. The UK is proposing to put more of that decision back on regulated firms without removing accountability. Boards and compliance teams should compare the proposed savings with the additional burden of documenting their own assessments before changing staffing or control plans.

Risk Compliance And Regtech

Singapore MAS Sets Anti-Scam Guidance for Retail Brokers

October 20, 2026, Singapore
  • The Monetary Authority of Singapore published Guidelines on Anti-Scam Measures for Brokers covering retail brokerage firms.
  • The guidelines have a confirmed effective date of June 30, 2027, giving firms a defined implementation period.
  • MAS also issued accompanying FAQs and strongly encourages retail brokers to implement the measures as early as practicable.

Retail brokers now have a dated supervisory benchmark for scam controls rather than a general warning about fraud exposure. Firms should review the full guidelines and FAQs against their customer protection, escalation and operational processes, identify changes requiring development or vendor support, and budget the work ahead of June 2027.

Ireland Penalizes Coinbase Over Customer Money Safeguards

October 22, 2026, Ireland
  • The Central Bank of Ireland reached a settlement with Coinbase Ireland over breaches of customer money safeguarding and outsourcing requirements between November 2020 and August 2025.
  • The regulator set a €4.65 million penalty, reduced to €3.25 million under its settlement discount. Coinbase Ireland accepted the findings, but the sanction requires High Court confirmation before taking effect.
  • The findings cite prolonged shortfalls in a safeguarding account, insufficient local oversight of outsourced functions and inadequate escalation and controls over material changes.

A global crypto brand still needs effective controls inside its locally regulated payments entity. Reliance on a parent company doesn’t transfer accountability for safeguarding customer funds. Payment firms expanding into Europe should verify daily reconciliations, board visibility and the resources available to challenge a group service provider when problems appear.

FCA Proposes Financial Crime Controls for AI and Crypto Risks

October 23, 2026, United Kingdom
  • The Financial Conduct Authority opened consultation CP26/38 on updates to its Financial Crime Guide. Proposed revisions cover fraud, sanctions, proliferation financing, data security and financial crime systems.
  • The draft would address emerging risks involving AI and cryptoassets, including the new UK cryptoasset regime expected from October 2027.
  • Responses close December 24, 2026. The consultation is guidance development, not an immediately binding new financial crime rule.

Financial crime controls built around yesterday’s payment and customer patterns can miss risks introduced by agents, crypto products and new vendors. Firms should test whether their transaction evidence, staff escalation and sanctions processes still work across those channels. The consultation offers a chance to challenge unclear expectations before the final guide is issued.

Sustainable Finance ESG And Financial Inclusion

Canada Publishes Final Green and Transition Finance Methodology

October 20, 2026, Canada
  • Canada’s Taxonomy and Transition Planning Council released its final Sustainable Finance Taxonomy Methodology Report, setting out definitions and a process for identifying green and transition economic activities.
  • The methodology considers Canadian economic conditions and Indigenous rights while drawing on international sustainable finance approaches.
  • Sector-specific technical screening criteria and guardrails are still being developed, beginning with electricity, buildings and transportation. The methodology is not a binding rule or a completed list of eligible investments.

A shared classification method could give issuers and capital providers a more consistent basis for assessing transition-finance claims. But the real allocation decisions will turn on sector thresholds, supporting evidence and independent review. Investors and borrowers should not treat today’s methodology as a certification of individual projects or assume that unsettled greenwashing and disclosure risks have disappeared.

Open Banking Open Finance And Data Sharing

Brazil Tightens Open Finance Data Partner Rules

October 22, 2026, Brazil
  • Joint Resolution 21 amends Brazil’s Open Finance rules for institutions sharing customer information or derived, identifiable data with commercial partners, including credit scores.
  • Institutions must strengthen partner contracts, security oversight, governance and reporting. Boards and senior executives receive explicit responsibilities for Open Finance performance and control.
  • Existing partner arrangements must be reported to the central bank by December 1, 2026. The regulator can restrict sharing or order a partnership suspended or terminated where specified risks or breaches arise.

Financial data partnerships now carry clearer accountability beyond the initial customer consent. Banks and fintech aggregators need to map every downstream recipient, inspect contract rights and test whether their oversight works when data are reused. Access to the rail is valuable, but it won’t excuse weak controls at the next company in the chain.

Weekly Close

Canada put C$1.75 billion in venture and growth capital on the table and introduced new rules to make federal regulation more competitive. Internationally, banks and fintechs advanced tokenized deposits, cross-border settlement and AI-controlled financial transactions. These are becoming practical business decisions about who controls customer access, payment infrastructure and compliance costs. The opportunity for Canadian fintechs is to compete on execution, building products customers trust, securing distribution and turning regulatory change into commercial advantage.

NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech news and insights, industry research, or launch into emerging financial innovation opportunities.


NCFA Canada logoThe National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

Why Investors Still Fall for Charismatic Founders

October 20, 2026 | NCFA Story Intelligence | Capital Markets And Funding, Leadership And Governance, Artificial Intelligence And Data
AI illustration for NCFA story on why investors still fall for charismatic founders, showing a startup founder pitching investors as hype, valuation and media attention outpace evidence and due diligence

Theranos, Investor Psychology and the Power of Founder Storytelling

On October 16, 2026, You Can See Everything opened in Canadian theatres. Four days later, the documentary about Elizabeth Holmes is still one of the biggest stories at the North American box office. It opened with about US$15 million from only 855 screens. That's an extraordinary result for a documentary about a founder whose company collapsed years ago and is now serving a federal prison sentence.1

Holmes didn't raise money because investors wanted to lose it. She sold a future that sounded possible, surrounded herself with people whose reputations made belief easier, and built a company whose story moved faster than outsiders could verify the technology. By the time the evidence caught up, investors had committed hundreds of millions of dollars.

What follows is a story of how founder trust becomes part of an investment case and how evidence can lose ground to momentum. The same human problem returns whenever investors finance an uncertain future.

A Founder Learns to Sell the Future 2003 to 2010

Elizabeth Holmes leaves Stanford and starts Theranos with a promise that is easy to understand and hard to ignore. Blood testing should require less blood, hurt less and become easier to access. The mission sounds personal and the market is enormous. Investors aren't being asked to finance another laboratory. They are being asked to back a founder who says healthcare can work differently. That's where trust first enters the deal.

The idea is bigger than the product. Theranos tells investors that its technology can run a broad range of tests from tiny amounts of blood. The company is private, the technology is closely guarded and outsiders have limited access to what happens inside the machines. That secrecy can sound like competitive protection when the founder is believed.

Conviction becomes part of the product. Holmes presents Theranos as a mission driven company that can transform healthcare. Investors hear a founder who appears certain about the future and willing to devote herself to it. That confidence is valuable in a startup because the product, market and operating model are all unfinished. It also makes the founder unusually important to the investment case.

Powerful Names Make Belief Easier 2011 to 2014

Then other people start lending Holmes their credibility. George Shultz joins the board after what was supposed to be a short meeting turns into a conversation lasting more than two hours. Henry Kissinger, William Perry, Sam Nunn, James Mattis and other prominent figures follow. Major investors arrive too. Each new name makes the company easier for the next person to believe. Theranos is no longer only asking whether investors trust Holmes. It's asking whether they trust everyone who already does.

How Theranos Built Borrowed Trust

By 2014, Theranos had assembled a board that looked more like a national security council than a medical technology startup. Former secretaries of state, defence leaders, senators, military commanders and senior business figures gave the company extraordinary status. Fortune later noted how little directly relevant laboratory expertise sat on the board compared with its political and business stature.2

That reputation travelled into fundraising. Court records later listed US$125 million from Rupert Murdoch and nearly US$100 million from RDV Corporation, the investment office associated with the DeVos family, among the losses considered for restitution.3

The names didn't prove the technology worked. They changed the social setting around the investment. A founder sitting alone across the table has to establish credibility. A founder surrounded by respected directors, major retailers, wealthy families and national media arrives with credibility already in the room.

The same pull shows up outside venture capital. The Finfluencer Effect on Canadian Retail Investors reported an OSC experiment with a striking result. 38% of participants exposed to promotional investment content bought the promoted asset, compared with 8% in the control group. The context changes how people act, even when they believe they are making their own decision.

The board looks formidable. Fortune described Theranos in 2014 as having one of the most illustrious boards in American business. George Shultz, Henry Kissinger, William Perry, Sam Nunn, James Mattis and other prominent figures gave Holmes access to experience, networks and public credibility that most young founders could never assemble.4

The board can't substitute for technical oversight. A famous director can open doors and challenge strategy. That doesn't automatically give a board the scientific depth to test a diagnostic platform. Prestige can make a young company look safer while leaving the hardest operating question untouched.

The Story Spirals Beyond the Evidence 2013 to 2015

By now Theranos has a founder people recognize, a board people respect, national retail partners and a story the media wants to tell. The company is valued at about US$9 billion. Every new endorsement makes the earlier endorsements look smarter. Inside that momentum, the distance between the public story and the operating evidence keeps growing. Investors are no longer judging a lonely startup. They are judging a success story that appears to be happening in front of them.

What Theranos Investors Were Told

The SEC later alleged that Theranos raised more than US$700 million through false or exaggerated statements about its technology, business relationships and financial performance. Broader accounts put total lifetime funding above US$900 million, but the SEC figure is the amount tied to the fraud case it brought.5

The financial claims were dramatic. Investor materials projected more than US$100 million in 2014 revenue and about US$1 billion in 2015. Actual 2014 operating revenue was only a little over US$100,000.6

Investors were also told the technology had been used by the US military in Afghanistan and on medevac helicopters. The SEC said it had not. They were told the proprietary analyzer could perform comprehensive testing from a few drops of blood. The SEC said it could perform only a small number of tests, while most patient testing relied on modified commercial machines made by other companies.

The gap wasn't one bad forecast or one late product milestone. Technology claims, revenue expectations, commercial relationships and outside validation all helped support the same investment story.

The numbers make the story feel real. A multibillion dollar valuation, hundreds of millions raised and national retail partnerships give investors familiar business signals. Those signals usually matter. They become dangerous when investors start treating them as evidence about the one thing the company still has to prove.

The media helps close the loop. Holmes becomes a symbol of Silicon Valley ambition. WIRED has now revisited its own 2014 coverage and acknowledged how media enthusiasm helped amplify the founder story before the science received enough scrutiny.7 The founder earns attention because investors believe. Investors see attention and find another reason to believe.

Diligence Still Doesn't Break the Spell 2010 to 2015

The easy story about gullible investors falls apart here. Walgreens visits Theranos, reviews patents, discusses regulation and brings in outside medical expertise. Safeway says it spends more than 100 hours on diligence. These aren't people writing cheques after one inspiring pitch. They are trying to verify the company. Yet the founder still controls much of what they are allowed to see, and some of the evidence they receive later proves unreliable.

How Sophisticated Diligence Still Failed

Walgreens did many of the things investors say they want to see. It visited headquarters, reviewed patents, discussed regulatory strategy and engaged outside experts. A later court record says Holmes sent Walgreens reports bearing logos from Pfizer, GlaxoSmithKline and Schering Plough and described them as independent technical validation. Representatives from those companies later testified that they had not independently validated the technology and had not authorized the use of their logos on those reports.8

Safeway also kept looking. Former CEO Steven Burd testified that the company spent at least 100 hours on diligence. The relationship eventually cost Safeway more than US$360 million before it was abandoned. During testing at Safeway headquarters, Burd said the device could make noise and still fail to deliver the expected result.9

Diligence only works when it reaches the evidence that can kill the deal. A founder controlled demonstration isn't the same as an independent production test. A customer logo isn't the same as a reference call. A report carrying a respected company's name isn't the same as confirmation from that company.

Good diligence can still ask the wrong question. Investors may spend weeks testing market size, legal structure, partnerships and founder references while the core product remains difficult to inspect. A deal room can contain thousands of pages and still miss the fact that matters most.

The founder can become the gateway to the evidence. That creates a dangerous loop. Investors trust the founder enough to accept the materials, then use those materials to decide whether they should trust the founder. Independent verification has to break that loop.

The Evidence Breaks Through 2015 to 2023

Eventually the story meets people who won't accept the controlled version of the evidence. Employees raise concerns. Whistleblowers push information outside the company. John Carreyrou begins reporting for The Wall Street Journal. Regulators and prosecutors follow. The change isn't that Holmes suddenly becomes less persuasive. The change is that outsiders finally have enough independent evidence to judge the claims without relying on her.

The criminal case narrows the facts. In January 2022, a federal jury convicts Holmes of conspiracy to defraud investors and three counts of wire fraud tied to transfers totalling more than US$140 million. The jury acquits her on patient related conspiracy and several patient fraud counts, while other investor counts end without a unanimous verdict.10

The sentence makes the cost tangible. In November 2022, Holmes receives 135 months in federal prison. She begins serving the sentence in 2023. The SEC had put the investor principle plainly years earlier when it said investors are entitled to “complete truth and candor” from companies and executives.11

The Company Dies but the Founder Story Survives 2023 to 2026

Theranos disappears. Holmes goes to prison. Yet the founder story keeps finding an audience. Books, podcasts, television dramas and documentaries revisit the same rise and collapse. Now You Can See Everything turns her final month of freedom into a theatrical event. More than 70% of the opening weekend audience is reportedly under 35. Many of those viewers were children when Theranos was at its peak. The company is dead, but the story is recruiting a new audience.12

Why Founder Stories Change Investment Decisions

Entrepreneurs need stories because early companies contain more uncertainty than evidence. Investors have to imagine the market, the product and the team several years ahead. Research published in 2024 found that investors can become mentally absorbed in a founder's pitch. When that happens, they are more likely to reshape the opportunity positively and commit resources.13

Another large study summarized by Harvard Business Review looked at founders from more than 4,000 US companies. Actual expertise was the strongest predictor of a successful exit, while signals of expertise were more strongly associated with getting funded. The ability to look investable can help win the cheque before the qualities that create long term value have been proven.14

Charisma isn't fraud. Storytelling isn't deception. Investors need founders who can make an uncertain future understandable enough for employees, customers and capital providers to join them. Trouble starts when the story becomes the evidence.

The audience knows how the story ends. That makes the continuing fascination more revealing. People aren't buying tickets because the verdict is unknown. They are watching because confidence, ambition, deception and failure are still compelling human material.

Persuasion still moves money. Canadian investors see the same mechanism in a different setting. How AI Is Changing Canadian Investors’ Decisions found that 84% of surveyed self directed investors used AI, financial creators or both. Technology changes the channel. It doesn't remove the human desire to find someone or something that makes uncertainty feel easier.

AI Brings the Question Back 2026

The next founder asking investors to believe before all the evidence exists probably won't be selling blood tests. Today, capital is rushing toward artificial intelligence, where products, business models and infrastructure costs can change between financing rounds. Carta says more than 60% of venture dollars on its platform went to AI companies in the first quarter of 2026. Investors are again deciding how much future they are willing to finance before the operating record is complete.15

What AI Investors Should Verify Before Believing the Demo

AI makes founder trust unusually important because a compelling demonstration can move faster than production evidence. A model may look remarkable in a controlled setting while customer retention, gross margins, compute costs, data rights and reliability remain unsettled.

Start with customers. Speak to them directly. Find out what is live in production, what is still a pilot and what would disappear if the startup stopped subsidizing usage. Then follow the money. Revenue quality matters more than a large contract headline if the deal depends on heavy discounts, strategic credits or one customer that can leave.

Then test the product outside the founder's preferred demonstration. Ask who chose the prompts, data, workflow and success criteria. Compare performance with realistic alternatives. If the company depends on another model provider, cloud vendor or data source, price that dependency into the investment case.

The current market makes that discipline harder, not less important. The Financial Times reported in September that a new group of AI companies raised roughly US$24 billion in six months, sometimes before they had meaningful products or revenue. Founder pedigree itself was helping unlock capital.16

Elon Musk belongs in a very different category from Holmes. Tesla and SpaceX built real products, customers and operating businesses. Yet Musk also shows how closely a founder's words can become tied to investor expectations. In 2018, the SEC settlement over his “funding secured” tweets required governance changes at Tesla and US$40 million in combined penalties. Musk isn't a Theranos analogue. The episode still shows why markets need controls when one person's credibility can move billions of dollars.17

Investors can use AI Investing Tools to accelerate research. The judgment still belongs to the investor.

Founder conviction still has value. Early stage investors are paid to finance businesses before every answer exists. A founder who can't make others believe in an uncertain future may never recruit the team, customers or capital needed to build it.

Conviction needs independent evidence beside it. Customer calls, production data, technical review, board oversight and financial reconciliation give investors something that doesn't depend on the founder's version of events. The earlier the company, the more important it becomes to know which assumptions are still beliefs.

The Next Founder Won’t Look Like Elizabeth Holmes

Holmes is in prison, Theranos is gone and investors now know how the story ended. That makes the mistakes look obvious in hindsight. They were much harder to see when the company was raising money, signing national partners, attracting famous directors and appearing on magazine covers.

The next founder who lets belief outrun the evidence will probably look nothing like Holmes. The company may be building AI, financial infrastructure, robotics, biotech or something investors have not learned how to value yet. The founder may have respected backers, impressive customers and a demonstration that makes the future feel close enough to touch.

Early founders often have to sell conviction before the product, revenue or market fully exists. That's part of building a venture, not evidence of deception. Investors are financing a future that has not happened yet, so imagination belongs in the deal.

The line gets crossed when aspiration is presented as fact, a controlled demonstration is presented as independent proof, or hoped for traction is sold as something already verified. A founder can sell why the future might happen. The investor still has to know what is already true.

Questions for the Next Deal

  • Will AI investors demand more independent product and customer verification as valuations rise?
  • Can startup boards challenge charismatic founders without removing the conviction that helped build the company?
  • Will venture investors change diligence when founder reputation becomes part of the valuation?
  • Can founders prove ambitious claims without slowing the speed that makes startups competitive?

Related NCFA Intelligence

STORY INTELLIGENCE

How OpenAI And Anthropic Reached Public Markets

OpenAI and Anthropic show what happens when founder vision, strategic backers, governance choices and enormous private capital converge before public market scrutiny arrives.

FOUNDER BUILD

Inside a Licensed Profession: What Ownright’s Build Teaches Fintech Founders

Ownright offers a current founder case where credibility comes from operating evidence, regulatory fit, customer execution and a system that has processed more than $2 billion of transactions.

MARKET ACTIVITY

FNZ Turnaround Tests La Caisse and Canadian Pension Capital

Repeated capital raises and management changes at FNZ show what investor conviction looks like after the cheque is written, when ownership starts turning into active governance.

NCFA INSIGHT

Canada’s Early Stage Startup Funding Funnel Narrows

A tighter Canadian funding market raises the stakes for founders trying to earn attention and for investors deciding which stories deserve scarce early stage capital.


NCFA Canada logoThe National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter


NCFA Weekly Fintech Intelligence Oct 10-Oct 16, 2026

Oct 10, 2026 | Last Updated: Oct 28, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Payments Infrastructure And Money Movement, Regulation And Policy, Wealthtech Investing And Trading, Risk Compliance And Regtech, Sustainable Finance ESG And Financial Inclusion

Fintech market intelligence visualization

Image: Freepik

This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-March 13, 2026, March 14-March 20, 2026, March 21-March 27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-June 19, 2026, June 20-June 26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-July 24, 2026, July 25-July 31, 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026, September 5-September 11, 2026, September 12-September 18, 2026, September 19-September 25, 2026, September 26-October 2, 2026, October 3-October 9, 2026).

Weekly Fintech Market Intelligence Oct 10 - Oct 16, 2026

Artificial Intelligence And Data

Anthropic Secures Nova Scotia Data Centre as EverWind Plans C$10B Investment

October 16, 2026, Canada
  • Anthropic signed a long-term lease for data centre capacity at EverWind's planned Point Tupper campus in Nova Scotia, marking its first Canadian data centre agreement. EverWind confirmed the tenant commitment without naming Anthropic; Reuters independently identified the company.
  • EverWind plans more than C$10 billion in private investment, including over C$8 billion for the data centre campus and C$2 billion for four Nova Scotia wind projects. The development is projected to support approximately 2,000 construction jobs and 215 permanent positions.
  • The initial 95 MW phase targets late 2027, with a further 325 MW planned for 2028, bringing potential capacity to 420 MW. The expansion remains subject to commercial, technical and regulatory conditions, including electricity system studies and approvals. No computing capacity is operating under this agreement yet.

Anthropic's lease gives EverWind a committed customer for its first development phase, strengthening the commercial case for a major Canadian infrastructure investment. But financing AI compute infrastructure depends on more than tenant demand. Power availability, construction costs and grid approvals determine when that demand becomes revenue. For investors, the distinction is between securing a customer today and delivering profitable computing capacity on schedule.

HKMA Issues Responsible AI Guidance for Hong Kong Banks

October 15, 2026, Hong Kong
  • The Hong Kong Monetary Authority (HKMA) issued Supervisory Guidance for Responsible Adoption of Artificial Intelligence for authorized institutions and introduced its Accountability, Resilience and Trust (ART) framework.
  • The framework includes plans for a training data sharing platform with Cyberport and the University of Hong Kong. More than 60% of use cases in the second generative AI sandbox cohort explored agentic AI.
  • The HKMA will continue agentic AI trials and publish a discussion paper on governance. Proposals for an agent registry and intervention controls are not yet finalized requirements.

Hong Kong banks now have updated supervisory guidance for deploying AI, while future rules for autonomous agents remain under discussion. Banks investing in these systems need clear ownership of decisions, reliable input data and controls that allow staff to intervene. Canadian financial institutions face many of the same questions as they expand AI into lending, compliance and customer service. The operating advantage will depend on speed and cost savings that hold up under supervisory review.

TD Expands Agentic AI Into Mortgage Funding and Discharge

October 13, 2026, Canada
  • TD Bank Group introduced two agentic AI capabilities for mortgage funding and discharge, expanding its use of AI beyond mortgage pre-adjudication.
  • The capabilities coordinate document checks, connect information across systems and flag potential discrepancies. Employees review generated information and retain responsibility for decisions.
  • TD reports that the funding tool can reduce the initial review time by up to half. Its earlier mortgage pre-adjudication process reduced average processing time from 15 hours to less than three minutes.

TD is using AI to clear document checks at more stages of the mortgage process, freeing staff to handle exceptions and borrower decisions. The reported time savings are substantial, but lenders still need to measure end-to-end completion times, error rates and rework. The investment pays off when faster reviews translate into funded mortgages without weaker controls.

Capital Markets Infrastructure And Funding

ESMA Finalizes T+1 Settlement Messaging Rules Ahead of December Deadline

October 16, 2026, European Union
  • ESMA confirmed that the regulatory requirements for the EU’s transition to one business day settlement on October 11, 2027 are complete.
  • From December 7, 2026, investment firms and their professional clients must meet new requirements for trade allocations and confirmations, including standardized electronic communication and machine readable messaging, subject to exceptions for temporary technical disruption.
  • The revised guidelines accompany amended settlement discipline technical standards. ESMA is asking participants across the trading and settlement chain to begin coordinated testing.

The first deadline arrives well before the settlement switch. Brokers, custodians and asset managers now need to reconcile message formats, client instructions and exception handling across counterparties. Canadian firms trading European securities face the same operational handoffs. A short settlement cycle leaves less room to repair missing allocations overnight.

BBVA and Santander Run €150M Syndicated Loan Entirely on Blockchain

October 15, 2026, Spain
  • BBVA and Santander arranged €150 million in syndicated financing for Iberdrola through a distributed ledger platform developed with ioBuilders.
  • The live facility uses the platform for execution and disbursement, interest management, waivers, repayments, loan assignments and maturity.
  • The banks describe it as the first live syndicated financing administered on blockchain throughout the loan lifecycle, rather than only at origination.

Loan syndication involves years of servicing, amendments and lender coordination after the initial funding. Handling those events on a shared record could reduce duplicate reconciliations and disputes over loan status. The same operating question sits behind shared bank blockchain infrastructure: can participants keep one reliable record without adding new integration costs? Lenders will want evidence of repeat transactions before committing more capital.

EU Clarifies When Crowdfunding Platforms Can Charge Membership Fees

October 16, 2026, European Union
  • The European Securities and Markets Authority (ESMA) confirmed that crowdfunding platforms can charge registration, membership or access fees without automatically breaching EU requirements for publicly accessible investment platforms.
  • Before charging, platforms must provide enough free information for prospective investors to understand available opportunities, fees and investment risks. ESMA expects investor categorization, knowledge tests and loss capacity assessments to be completed before retail investors pay for access.
  • ESMA also warns about conflicts involving finfluencers and paid referrals. Platforms must disclose commercial incentives and can't use membership fees to bypass investor protections. The October 16 guidance interprets existing EU crowdfunding rules rather than creating a new licensing regime.

Paid investor communities can create recurring revenue for crowdfunding platforms, but the fee can't become a barrier to understanding what investors are buying. Operators need to show enough deal information before collecting membership payments and explain exactly what those fees purchase. The bigger commercial issue is trust. Platforms that sell access before demonstrating investment value risk higher acquisition costs, complaints and regulatory scrutiny. A subscription model can work, but it still has to earn investors' money.

CIRO Proposes Volatility Controls for Extended Trading Hours

October 13, 2026, Canada
  • CIRO opened a consultation on marketplace thresholds and single stock circuit breakers for trading outside 9:30 a.m. to 4:00 p.m. ET.
  • The proposed guidance addresses how volatility controls should operate during extended sessions, including periods of limited trading activity.
  • Comments close November 12, 2026. The proposed guidance is not yet in force.

Longer trading hours change the conditions under which orders meet available liquidity. Marketplaces and brokers need controls that work when fewer orders are on the book and prices can travel farther on small trades. The consultation gives Canadian trading firms a chance to address threshold design before extended hours become a larger operational commitment.

BNY and Citadel Settle Tokenized Treasury for Triparty Repo

October 13, 2026, United States
  • BNY and Citadel Securities completed an overnight triparty repo using a tokenized two-year U.S. Treasury note as collateral.
  • Citadel Securities purchased the Treasury through Tradeweb. BNY recorded its tokenized representation on a private ledger, settled it within minutes and accepted it as repo collateral.
  • BNY calls this the first tokenized asset used on a major triparty repo platform. Longer settlement hours and digital cash capabilities are planned, not part of the completed transaction.

BNY has demonstrated that tokenized market infrastructure can support real overnight financing, not just digital settlement. For dealers, the advantage could be faster access to collateral and lower funding friction. The economics depend on custody fees, connections to other counterparties and how often the process can be repeated at scale. One completed repo proves the workflow; regular volume would prove the business case.

Federated Hermes and Prometheum Plan Funds for Brokerage Accounts

October 13, 2026, United States
  • Federated Hermes and Prometheum agreed to develop tokenized securities funds for distribution through regulated U.S. brokerage infrastructure. Federated Hermes reported US$911.6 billion in assets under management at June 30, 2026.
  • Prometheum's registered brokerage businesses plan to handle custody, clearing and settlement. Its correspondent clearing service would give introducing brokers a route to distribute the products.
  • The partners target the first fund in Q1 2027. No fund has launched under this arrangement.

The partnership tackles a central obstacle for tokenized funds: reaching investors through regulated broker dealer workflows they already use. Federated Hermes brings investment products; Prometheum would provide custody, clearing and brokerage connections. Managers and intermediaries will judge the offer by distribution costs, settlement performance and investor demand, not the use of tokens alone. The first fund remains planned for 2027.

Origin Bancorp Transfers NYSE Listing to Texas Stock Exchange

October 13, 2026, United States
  • Origin Bancorp arranged to transfer the primary listing of its common shares from the New York Stock Exchange to the Texas Stock Exchange (TXSE), retaining the ticker OBK.
  • Its SEC filing states that NYSE trading was expected to end after October 12, with TXSE trading scheduled to begin at the October 13 market open.
  • TXSE issued trading alert TXSE-2026-056 covering the new listing, providing an operational notice to market participants.

Origin gives TXSE a publicly traded bank issuer and a practical chance to compete for U.S. listings. But a listing win is only the beginning. Brokers and investors will judge the exchange by trading depth, spreads, execution quality and reliable access to market data. Those measures will determine whether other issuers see a commercial reason to follow.

Evernorth Begins Nasdaq Listing With 473 Million XRP Treasury

October 12, 2026, United States
  • Nasdaq set October 12 as the marketplace effective date for Evernorth Holdings' Class A shares and warrants under the symbols XRPN and XRPNW, following completion of its business combination with Armada Acquisition Corp. II on October 9.
  • Evernorth entered the public markets holding approximately 473 million XRP and reported approximately US$300 million in gross cash proceeds from the transaction.
  • The company's strategy combines public equity financing with an XRP treasury and planned institutional investment activities. The listing provides investors with publicly traded exposure to a company whose financial position is substantially tied to XRP.

Evernorth offers stock market investors exposure to a company holding a large XRP treasury without requiring them to buy XRP directly. Its shares may trade at a premium or discount to the underlying assets. Investors should weigh treasury management, operating costs and future capital decisions against the simpler alternative of owning the asset itself.

Ripple Prime Opens 24 Hour Institutional RWA Swap Trading

October 15, 2026, United States / Global
  • Ripple Prime opened round the clock trading and settlement for perpetual swaps linked to more than 100 markets, including equities, indices, ETFs, commodities and foreign exchange.
  • Institutional clients including Virtu are already trading. Ripple Prime acts as principal, with contracts referencing futures listed by Trade.xyz on Hyperliquid.
  • Clients can cross margin positions with other supported assets and use Ripple USD (RLUSD) as collateral where eligible. The service is available through Ripple Prime's British Virgin Islands licensed entity; wider regional access is planned.

Institutions can now manage traditional market exposure through a crypto trading venue when stock and futures exchanges are closed. That's a meaningful opening for firms that trade across time zones, but 24 hour access doesn't guarantee deep liquidity or better prices. Prime brokers and market makers will compare margin efficiency, weekend spreads and counterparty risk with established derivatives markets before moving significant volumes.

Cross Border Payments And FX

Payoneer Canada Registers Under Retail Payment Activities Act

October 13, 2026, Canada
  • Payoneer announced that Payoneer Canada Limited registered with the Bank of Canada as a payment service provider under the Retail Payment Activities Act (RPAA).
  • The registration supports continued Canadian operations, including local-currency collection and cross-border services for businesses, together with locally adapted onboarding and compliance.
  • Payoneer says it supports customers across more than 190 countries and territories through nearly 100 banking and payment service provider partnerships.

RPAA registration gives payment providers a defined route to serve Canadian businesses, along with continuing safeguarding and reporting duties. Payoneer can use that standing in discussions with customers and banking partners. For competing providers, the relevant costs extend beyond registration to the controls needed to maintain it.

RBI Tightens Rupee Derivatives and Introduces 20% FX Risk Reserve

October 10, 2026, India
  • The Reserve Bank of India issued two foreign exchange circulars restricting the rebooking of cancelled rupee derivative contracts and reducing the threshold for certain transactions without establishing underlying exposure from US$100 million to US$5 million.
  • Authorized dealers must obtain and retain customer undertakings confirming that the same underlying exposure has not been hedged with another dealer. The restrictions cover specified over the counter and exchange traded rupee derivatives.
  • The RBI introduced a 20% cash Foreign Exchange Risk Reserve for specified INR derivative contracts exceeding US$2 million. It applies to transactions hedging current account exposures where customers purchase foreign currency against rupees, rather than all foreign exchange derivatives.

The restrictions change how banks price rupee hedges and how companies manage currency exposure. Dealers face cash reserve costs and tighter checks on the transactions they can accept. Corporate treasury teams may need to reassess hedging across multiple banks, especially when a cancelled contract can no longer be rebooked. The immediate commercial impact is on liquidity and flexibility, not just compliance paperwork.

Cybersecurity Fraud And Financial Crime

Hong Kong Sets Cyber Rules for Critical Retail Payment Infrastructure

October 15, 2026, Hong Kong
  • The Hong Kong Monetary Authority issued a Code of Practice for retail payment system infrastructure operators designated as critical infrastructure operators under Hong Kong's Protection of Critical Infrastructures law.
  • The code gives designated payment operators practical requirements for complying with category 1 and category 2 obligations under the legislation. These cover governance, incident response, security management and reporting duties tied to critical computer systems.
  • The code took effect on October 15, 2026. The HKMA can update the requirements as technology, cyber threats and industry practices change.

Payment infrastructure is now being treated as critical digital infrastructure with direct cyber obligations attached. For operators, this moves resilience from good practice into a formal compliance responsibility. Boards and technology teams need to know which systems are designated, who owns incident decisions and whether reporting can happen fast enough when a critical payment service fails.

New Zealand Regulators Set Frontier AI Cyber Expectations

October 15, 2026, New Zealand
  • The Reserve Bank of New Zealand and Financial Markets Authority jointly outlined supervisory expectations for financial institutions managing cybersecurity risks associated with frontier AI, following an industry roundtable with national cybersecurity and government officials.
  • The expectations address three areas: AI-enabled cyber threats, governance and management accountability, and third party concentration risk. Institutions are expected to reassess material changes in their risk exposure and maintain controls appropriate to their business.
  • Regulated firms should maintain incident response and recovery plans, test severe but plausible scenarios and understand their exposure to critical technology suppliers. The expectations build on existing prudential, conduct and operational resilience obligations rather than creating a separate AI rulebook.

Frontier AI is raising the standard of evidence supervisors expect when reviewing financial institutions' cyber resilience. Boards need visibility into where AI changes their threat exposure, which vendors create concentrated dependencies and whether recovery plans still work against faster attacks. The immediate operating priorities are vulnerability management, supplier assurance, incident testing and clear accountability before failures expose gaps.

FIS Opens AI Money Laundering Investigations Tool to US Banks

October 15, 2026, United States
  • FIS made its AML Investigations Agent commercially available to U.S. banks, including institutions that do not use FIS core systems. It developed the tool with support from Anthropic.
  • The agent assembles case evidence and generates recommendations with links to source records. Analysts must explicitly confirm case closures, and each bank retains control of its risk rules and thresholds.
  • Deployment is underway at Amalgamated Bank. Based on its workflow analysis, the bank projects more than 90% less time for initial alert reviews and approximately 98% less time for deeper investigations. These are projections, not realized results.

FIS is taking an AI investigation tool from development into commercial banking operations. The potential savings are substantial because analysts spend considerable time gathering records before judging an alert. But banks still own the compliance decisions. Buyers should examine audit trails, false positives and completed case volumes before relying on projected productivity gains. For Canadian providers, the competitive pressure is on evidence quality and operating cost, not merely the number of alerts an AI system can review.

Incode Launches Cross Institution Network for Repeat and Agentic Fraud

October 14, 2026, United States / Global
  • Incode launched TrustGraph, a privacy preserving network that lets banks, fintechs and other participants detect repeat and agentic fraud using signals from other institutions without pooling or exposing their customer records.
  • Incode reports that institutions in its early access program detected up to 53% more fraud with TrustGraph than with their existing models alone. The network is available now as part of Incode's identity platform.
  • TrustGraph uses secure multiparty computation to compare fraud and trust signals while customer data remains with the institution that collected it. Participants receive explainable signals that can support approval, denial, escalation or additional verification.

Fraud intelligence is becoming shared infrastructure rather than a control each institution builds alone. TrustGraph takes a different technical route from Canada's CSAFE fraud exchange, using cryptographic matching instead of pooling customer records. The commercial advantage grows with participation: more institutions create more opportunities to identify repeat attacks before fraud reaches another account.

EnStream Launches CSAFE Fraud Data Exchange for Canadian Banks

October 14, 2026, Canada
  • EnStream launched the Cross-Sector Anti-Fraud Exchange (CSAFE) to share confirmed fraud intelligence across Canadian banks and telecom providers.
  • Participants include Bell, Rogers, TELUS, BMO, CIBC, Desjardins, National Bank, RBC and Scotiabank. The platform follows an earlier CIBC and Rogers pilot.
  • CSAFE standardizes information submitted by participants. Each institution decides how to use the intelligence in authentication, account opening and transaction screening.

Fraud often crosses the boundary between a mobile account and a bank account. CSAFE gives participating firms confirmed intelligence from both sides, helping them recognize repeat attacks sooner. The financial value will come from fewer losses and investigations without blocking legitimate customers. That depends on timely, accurate contributions and disciplined privacy controls.

Bank of America Faces US$1.21B in AML and Sanctions Actions

October 13, 2026, United States
  • FinCEN assessed US$1.2 billion against Bank of America over failures in anti-money laundering controls, correspondent banking due diligence and suspicious activity reporting.
  • The OCC also imposed a US$750 million Bank Secrecy Act penalty. That amount is credited toward FinCEN's assessment and must not be added again.
  • OFAC separately settled 475 apparent sanctions violations for approximately US$11.6 million. The combined financial resolutions total about US$1.212 billion.

The penalties show how failures in alert handling, correspondent banking controls and sanctions screening can become major financial liabilities. For banking executives, the response requires more than a larger compliance budget: investigations must be timely, findings must reach decision makers and remediation must work across business lines. Investors should track the cost and effectiveness of those repairs.

Digital Assets Blockchain And Tokenization

EU Banking Authority Classifies USDC as First Significant E-Money Token

October 14, 2026, European Union
  • The European Banking Authority (EBA) classified Circle Internet Financial Europe SAS's USDC as the EU's first significant electronic money token under the Markets in Crypto Assets Regulation (MiCA). The EBA reports 45 notified electronic money tokens in the EU.
  • From November 12, 2026, the EBA will directly supervise specified requirements covering own funds, asset reserves, liquidity and recovery and redemption plans.
  • France's ACPR will continue to supervise other areas, including governance, ownership suitability, outsourcing and conflicts of interest. The classification changes supervisory responsibilities; it is not a new USDC launch or authorization.

USDC's designation brings a major stablecoin under closer EU oversight of capital, reserves and redemption. Circle must now manage a split supervisory relationship, while banks and payment providers gain a clearer view of which authority oversees critical financial safeguards. For Canadian stablecoin operators, the decision shows how growing scale can change supervisory obligations even after a token enters the regulated market. Compliance costs and the confidence of institutional counterparties will matter together.

Qivalis Gets Dutch EMI Approval for Bank Backed Euro Stablecoin

October 14, 2026, Netherlands
  • Qivalis announced that De Nederlandsche Bank authorized it as an electronic money institution, a regulatory prerequisite for its proposed euro stablecoin.
  • The 37-bank consortium across 15 European countries plans to serve payment providers, exchanges and financial institutions with a euro settlement asset.
  • The stablecoin has not launched. Issuance still depends on applicable MiCA requirements, including a published white paper.

Authorization gives the bank consortium an important legal foundation for issuing a euro stablecoin. It does not yet provide a token that customers can use. Banks, exchanges and payment providers will evaluate redemption certainty, liquidity and integration costs once issuance begins. Broad institutional backing could support distribution, but demand still has to be earned.

Flowdesk Adds PSD2 Payment Authorization for Stablecoin Services

October 13, 2026, France / European Union
  • France's Prudential Supervision and Resolution Authority authorized Flowdesk Europe as a Payment Institution under PSD2, adding regulated payment permissions to its European digital asset business.
  • The authorization allows Flowdesk Europe to provide custody and transfer services for fiat referenced e money token stablecoins to clients across the European Union.
  • Flowdesk already received its MiCA Crypto Asset Service Provider authorization from France's AMF in June 2026. The two permissions give the company regulated coverage across both crypto asset services and specified stablecoin payment activities.

Stablecoin operators increasingly need both digital asset and payment permissions when products cross from trading into money movement. Flowdesk can now combine MiCA services with PSD2 payment capabilities inside one European regulatory structure. For firms comparing international models with Canada's stablecoin framework, the operating question is how quickly multiple regulatory permissions can translate into custody, transfers and institutional volume.

Standard Chartered Opens Institutional Custody for Ripple RLUSD

October 12, 2026, Singapore / United Arab Emirates
  • Standard Chartered launched institutional custody for Ripple USD (RLUSD) issued on the XRP Ledger. The live service is available to eligible clients through its Dubai International Financial Centre branch, regulated by the Dubai Financial Services Authority.
  • The bank is working with Ripple and LMAX Group to make RLUSD eligible collateral for agreed trading and collateral management products using Standard Chartered's collateral mirroring model.
  • The planned model would allow eligible RLUSD to remain in bank custody while its value is represented to LMAX for trading purposes. Collateral integration is not yet live and remains subject to documentation, testing, regulatory requirements and internal approvals.

Institutional stablecoin use depends on custody, transfer permissions and access to trading venues. Standard Chartered now offers a regulated custody option for RLUSD. Its proposed LMAX integration could let clients use collateral without moving it to an exchange. The commercial benefit will depend on funding efficiency, safeguards and the costs of operating across several counterparties.

Episode Six Adds Live Backing Checks for Bank Issued Tokens

October 15, 2026, United States / Global
  • Episode Six launched Verified Backing within its E6 Token Control Ledger to check bank issued stablecoins and tokenized deposits when they're created and redeemed.
  • The bank side system confirms that a token has recorded backing before issuance, then checks that it's genuine and still outstanding before cash is released on redemption. The checks apply to tokens issued through the E6 ledger.
  • Verified Backing is available now to Episode Six customers in supported markets. It doesn't hold reserves or replace an issuer's audits, attestations or regulatory duties. Episode Six operates in more than 50 countries.

A bank issuing digital money needs to know which tokens are still valid before paying holders back. Episode Six puts that check inside the bank's ledger at the point of redemption, where an error could turn into a direct loss. The commercial question is whether this control reduces reconciliation work and fraud without slowing payment flows. Banks still have to prove the reserves exist; software checks aren't a substitute for that obligation.

Digital Banking And BaaS

Kraken Parent Payward Signs Agreement to Acquire Saldo Bank

October 14, 2026, Europe
  • Kraken parent Payward signed a definitive agreement to acquire Saldo Finance Oy, whose subsidiary Saldo Bank UAB holds a specialized banking licence in Lithuania.
  • Saldo offers deposits and lending in several European markets, including services for fintech partners. Payward intends to combine those capabilities with its existing payments and investment products.
  • Closing is expected in 2027, subject to regulatory approval and other conditions. Payward does not yet own Saldo Bank.

Buying Saldo could give Payward direct control over more European deposit and lending services instead of relying on bank partners for every product. The agreement is not ownership yet, and regulated banking brings capital and supervision costs. Once the deal closes, investors should watch customer uptake, funding costs and whether the combined businesses improve margins.

Crédit Agricole Signs Deal to Acquire Germany’s IKB Bank

October 12, 2026, France / Germany
  • Crédit Agricole agreed to buy 100% of IKB Deutsche Industriebank, giving the French banking group a larger direct position in German SME and midmarket lending if the deal closes.
  • IKB reported about €14.3 billion in assets and an €8.2 billion loan portfolio for 2025.
  • The transaction requires regulatory and competition approvals. Closing is expected by the end of Q2 2027.

IKB would give Crédit Agricole an established German business lending franchise and relationships it would otherwise have to build customer by customer. That creates opportunities to offer existing borrowers more services and fund loans through a larger banking group. Returns will depend on credit quality, customer retention and integration expenses after closing.

Hong Kong Opens Cross Border Banking Data Verification With Chongqing

October 14, 2026, Hong Kong / China
  • The Hong Kong Monetary Authority and Chongqing authorities launched a cross border data validation platform for banking services including account opening and loan applications.
  • The platform uses blockchain records and cryptographic hashes to check customer information without transferring or storing the original documents across the border. Banks are developing uses for data moving in both directions.
  • A related Shenzhen and Hong Kong platform has completed more than 40,000 validations for over 10 banks. Those are results from the earlier system, not transaction volumes from the new Chongqing platform.

Banks need reliable customer records to lend and open accounts across borders, but moving those records creates cost and privacy concerns. This platform lets participating institutions verify information without receiving the underlying files. That could shorten onboarding and credit checks for businesses operating in both markets. The next test is how many banks integrate it, what it costs per verification and whether customers see faster decisions.

Payments Infrastructure And Money Movement

South Africa Sets 2027 Timeline for Direct Nonbank Payment Access

October 16, 2026, South Africa
  • The South African Reserve Bank (SARB) plans to let fintechs, telecom companies and retailers access national payment clearing and settlement infrastructure directly, reducing their reliance on banks as intermediaries.
  • SARB expects to publish payment activity and exemption rules by November 2026. The first licensed nonbank participants could begin operating around March 2027, with broader access targeted for mid-2027. These are planned milestones, not approvals already granted.
  • The reform forms part of SARB's Payments Ecosystem Modernisation programme, which includes a national payments utility built around PayInc, faster digital payments and infrastructure shared across banks and nonbank providers.

Direct payment access could change the economics of launching a fintech in South Africa. Providers would have a route to clearing and settlement without depending on a sponsoring bank for every transaction. That could reduce intermediary costs and give new entrants more control over their services. The commercial opportunity now depends on licensing requirements, connection fees and how quickly the new infrastructure can support real transaction volume.

Visa Direct Puts USDC Cross Border Prefunding Into Production

October 15, 2026, United States / Global
  • Visa Direct moved stablecoin enabled prefunding into commercial production, with payments infrastructure provider Inyo Global as the first enabler for eligible Visa Direct customers and partners.
  • Inyo integrated the service into its existing APIs. Eligible businesses can use USDC to prefund cross border payouts in near real time, rather than relying exclusively on conventional funding windows.
  • Visa says Inyo's platform supports domestic and international payouts across more than 180 countries. Eligibility and geographic availability vary; the announcement does not provide live transaction volumes.

Stablecoin funding can help payment companies keep less idle cash in multiple accounts while supporting payouts outside traditional banking hours. Visa and Inyo now have a production service, but the financial gain depends on conversion costs, liquidity and the actual timing of settlement. Banks and payment fintechs should compare those economics with their existing prefunding arrangements before assuming round the clock access will improve margins.

UK Proposes One Access Rulebook for Payment Systems

October 15, 2026, United Kingdom
  • The UK's Payment Systems Regulator (PSR) opened consultation CP26/3 on replacing overlapping payment system access requirements with one regulatory framework. The proposal forms part of plans to transfer the PSR's responsibilities to the Financial Conduct Authority (FCA).
  • The package includes a revised General Direction 2, consolidated access guidance and an updated compliance reporting template. It covers payment system operators and providers seeking direct or indirect access. Existing access protections would largely remain in place.
  • The changes depend on the planned repeal of overlapping requirements under the Payment Services Regulations 2017. Responses close December 10, 2026. The consultation doesn't change access rights or grant firms new permissions today.

Payment fintechs spend time and money negotiating access to the systems that move customer funds. A simpler rulebook could reduce duplicated compliance work and make access terms easier to challenge when incumbents impose costly conditions. But consolidation alone won't guarantee better access. Founders need to examine connection charges, technical requirements and the rights available when an operator refuses entry. Those details will determine whether the reform lowers the cost of competing or mainly reduces paperwork.

Mastercard and BVNK Launch Stablecoin and Fiat Money Platform

October 15, 2026, United States / United Kingdom
  • Mastercard and BVNK launched Global Money Platform, available through BVNK, combining fiat accounts, stablecoin capabilities and conversion services through a single API.
  • Banks, fintechs and businesses can use modular capabilities for account management, stablecoin linked cards, treasury operations and local bank payouts through Mastercard Move.
  • Nuvei, Marqeta, Ontop, Beem and Almond FinTech are among the first announced integrators. Broader coverage of more than 40 currencies across over 200 countries and territories is planned for 2027, not available in full today.

Mastercard is turning its BVNK acquisition into a distribution channel for businesses that need to hold, convert and pay in both bank money and stablecoins. A single integration may lower development and reconciliation costs for fintechs. But buyers will still compare pricing, available corridors and responsibility for funds across the service. The competitive question is whether bundled infrastructure delivers better working capital management than separate providers.

Nuvei Gains South African Authorization for Local Merchant Payments

October 14, 2026, Canada / South Africa
  • Canada founded payments company Nuvei obtained authorization from the Payments Association of South Africa to offer local merchant payment services.
  • The authorization extends Nuvei’s domestic acceptance and acquiring infrastructure to 52 markets.
  • Nuvei plans to serve local businesses and international merchants through its existing global platform, with local payment routing and operational controls.

Local acceptance capacity gives merchants more than another foreign payment option. It can improve authorization routing and reconciliation where domestic rules differ. Nuvei already connects payment acceptance with enterprise invoice workflows; South African access extends the territory where that infrastructure can be sold. Merchant uptake and transaction performance will decide the return.

Polygon Completes Coinme Deal to Add US Regulated Payment Capacity

October 14, 2026, United States
  • Polygon Labs completed its acquisition of Coinme, adding regulated US money movement capabilities to its Open Money Stack.
  • The combined platform connects conventional payment entry and exit options with transactions recorded on blockchain networks.
  • Tazapay, Mesh, Toku and Kira are named among the first customers adopting the platform. Polygon distinguishes the completed acquisition from capabilities it intends to expand.

Owning licensed payment capacity changes Polygon’s role from infrastructure supplier toward a provider that can connect digital asset transfers to conventional money. It also adds a regulated distribution component to the stablecoin payment infrastructure opportunity. Customers will judge the combined platform by supported payment routes, settlement reliability and total cost, rather than token throughput alone.

Visa Receives Preliminary Approval for Domestic Clearing in China

October 13, 2026, China
  • The People’s Bank of China approved Visa’s Application to Prepare for a domestic bankcard clearing institution.
  • The decision permits Visa to begin formal preparations for a local clearing business; it is not authorization to process domestic card transactions.
  • Visa must complete the remaining regulatory steps before it can commence domestic bankcard clearing operations in China.

Visa has gained a formal route toward operating in China’s domestic card market, but it cannot clear local transactions yet. The next milestones are the remaining approvals and connections with issuing banks, acquirers and merchants. Market share will depend on those relationships and the cost and quality of competing with established networks.

Regulation And Policy

MAS Proposes Independent Dispute Resolution for Payment Firms

October 16, 2026, Singapore
  • The Monetary Authority of Singapore proposed requiring Major Payment Institutions and Standard Payment Institutions to join the Financial Industry Disputes Resolution Centre (FIDReC).
  • The proposal would also cover MAS regulated stablecoin issuers once Singapore’s stablecoin regime takes effect.
  • The consultation opened October 16 and closes November 30, 2026. Membership requirements are proposed, not yet mandatory under this consultation.

Payment providers could face an independent route for customer complaints, beyond their internal case handling. If adopted, membership would add costs for records, escalation and disputed transactions. Canada’s proposed open banking complaint requirements address related responsibilities for participants, although they are a separate regime. Firms selling payment and stablecoin services across borders need to cost customer redress into their operating model.

ESMA Expands Grounds to Delay Inside Information Disclosure

October 16, 2026, European Union
  • ESMA finalized revised Market Abuse Regulation guidelines on when listed issuers may delay public disclosure of inside information.
  • The revisions add five legitimate interests for delay, including requests from public authorities, incomplete information needed for market assessment and risks to sensitive commercial opportunities.
  • The guidelines become applicable when published in the EU’s 24 official languages. ESMA also removed provisions linked to prolonged processes already addressed by June 2026 rule changes.

Listed companies need decisions about delayed disclosure to withstand scrutiny after information becomes public. The revised grounds offer more clarity, but they do not remove the obligation to assess confidentiality and investor impact in each case. Boards and legal teams should update decision records and approval procedures rather than treating the five additions as blanket exemptions.

CSA Finalizes IFRS 18 Changes to Canadian Issuer Disclosure

October 15, 2026, Canada
  • The Canadian Securities Administrators published final amendments to National Instrument 52-112 covering non-GAAP and other financial measures disclosed outside financial statements.
  • The amendments address the new IFRS 18 rules for management defined performance measures and permit certain information to be incorporated by reference to the financial statement notes.
  • Subject to required approvals, the amendments take effect December 29, 2026. IFRS 18 applies to annual periods beginning on or after January 1, 2027.

Public companies must align earnings presentations, investor materials and financial statement notes before the reporting change. The CSA amendments apply to issuer disclosures, while separate IFRS 18 reporting changes affect federally regulated insurers. Finance teams should reconcile definitions across published measures and underlying accounts before disclosures reach investors.

ASIC Consults on Custody and Settlement Rules for Digital Assets

October 15, 2026, Australia
  • ASIC released Consultation Paper 392 to implement the Corporations Amendment (Digital Assets Framework) Act 2026, which is scheduled to commence April 8, 2027.
  • The package proposes operating guidance for digital asset platforms and tokenized custody platforms, together with requirements for holding customer assets, trading, settlement and financial resources.
  • Consultation closes November 27, 2026. Draft instruments may change before adoption.

The consultation puts detailed custody, settlement and capital proposals behind ASIC’s earlier digital asset licensing roadmap. Platform operators can now compare existing controls against draft requirements and price the cost of entering Australia. Firms must distinguish their responsibility for holding customer assets from their role in executing and settling trades.

FSB Proposes Eight Principles to Modernize Financial Regulation

October 14, 2026, Global
  • The Financial Stability Board opened a consultation on eight principles for modernizing financial regulation and supervision, aimed at improving effectiveness, efficiency, risk focus and responsiveness to emerging technologies and market changes.
  • The proposed principles would guide authorities as they review existing requirements while maintaining financial stability safeguards and implementing internationally agreed standards. They are proposals, not new obligations for financial firms.
  • Comments close January 8, 2027, with the final report expected in the first half of 2027. A related FSB implementation review identifies national circumstances and policy design as contributors to uneven adoption of international standards.

Regulatory modernization could affect how quickly new financial products reach customers and how much compliance costs smaller entrants. The consultation gives fintechs and industry associations a chance to identify rules that impose costs without improving outcomes. The real test will be whether future supervisory reforms shorten approval timelines, reduce duplication and preserve financial safeguards.

OCC Identifies Debanking Policies at Nine Major US Banks

October 14, 2026, United States / Canada
  • The US Office of the Comptroller of the Currency reviewed nine large national banks, including TD Bank and BMO Bank, for policies that could restrict services based on lawful activities or customers’ beliefs.
  • The OCC found that all nine had relevant policies during 2020 through September 2025. Its report reflects supervisory findings rather than a newly imposed industry rule.
  • The review followed a US executive order on fair access to banking and examined bank policies, account restrictions and related governance.

Customer screening is now subject to closer scrutiny over why banks accept or decline legitimate businesses. Institutions need documented distinctions between lawful customer activity, financial crime risk and reputational judgments. For Canadian banks with US operations, policy review and audit evidence are practical priorities. Access decisions that cannot be defended consistently can carry supervisory and commercial costs.

MAS Finalizes Consumer Safeguards for Financial Product Marketing

October 12, 2026, Singapore
  • The Monetary Authority of Singapore finalized enhanced safeguards governing how financial institutions and their representatives market financial products through public prospecting activities, including roadshows.
  • Institutions will be expected to limit prospecting to designated areas at commercial premises, appoint qualified supervisors and obtain consumer consent before proceeding with financial product marketing. Street canvassing and door to door prospecting remain prohibited.
  • MAS plans to issue updated marketing and distribution conduct guidelines in 2027, followed by a nine-month transition period for financial institutions to implement the enhanced safeguards.

The new safeguards require financial product distributors to prepare for tighter supervision of public sales activity. Firms should update staff training, customer consent records and controls over where representatives approach people. The transition period creates time to make those changes before MAS applies the revised guidelines.

Wealthtech Investing And Trading

India Tightens Controls on Algorithmic Trading in GIFT IFSC

October 16, 2026, India
  • India's International Financial Services Centres Authority issued new rules for algorithmic trading across GIFT IFSC stock exchanges, broker dealers and remote trading participants. The circular took effect immediately.
  • Trading algorithms require prior exchange approval and conformance testing. Firms must maintain real time risk controls, price and quantity checks, audit trails, tested kill switches and annual system audits.
  • Where AI, machine learning or self learning models influence a trading algorithm, the market participant remains responsible for explaining how the technology affects its decisions. Existing systems must complete required conformance testing within three months.

GIFT IFSC is putting a clear accountability line around automated trading. A firm can use more advanced models, but it can't outsource responsibility to the software or its vendor. Brokers, trading firms and technology providers now have a concrete checklist for approval, testing, surveillance and shutdown controls before they scale automated strategies.

ASIC Proposes Ten-Year Extension of Retail CFD Trading Protections

October 12, 2026, Australia
  • The Australian Securities and Investments Commission opened Consultation CS 64, proposing to extend its contracts for difference product intervention order for another 10 years and amend specific requirements affecting retail trading products.
  • ASIC reports that 68% of retail CFD traders lost money during 2023–24, with aggregate net losses exceeding A$458 million, including A$73 million in fees. The existing order limits leverage and includes protections against excessive retail losses.
  • The consultation proposes targeted amendments addressing industry practices and product developments identified since the order took effect. Comments close November 9, 2026. The proposed extension and amendments are not yet final.

ASIC’s loss figures put pressure on brokers that rely on frequent, highly leveraged retail trading. The proposal could affect product terms, customer acquisition and dealing revenue if adopted. Platforms should assess those consequences now, while regulators consider whether the existing protections still address the products offered to retail investors.

Sustainable Finance ESG And Financial Inclusion

ESMA Clarifies Impact and Climate Transition Claims

October 12, 2026, European Union
  • The European Securities and Markets Authority published two thematic notes on sustainability impact and climate transition claims used in investment funds, bonds and benchmarks. The notes provide examples of clearer and potentially misleading communications based on existing regulatory requirements.
  • For positive impact claims, ESMA distinguishes intentionality, additionality and measurability. Investment managers should explain how their strategies contribute to environmental or social outcomes, including the difference between a company's positive impact and the contribution attributable to investors.
  • Climate transition claims should explain targets, baseline years, implementation plans, progress measures and material assumptions. Firms should distinguish measurable commitments from future ambitions and explain relevant uncertainties. The notes do not create new regulatory requirements.

European asset managers need to distinguish between holding companies with strong environmental credentials and demonstrating how investor capital contributes to measurable improvements. The supervisory examples also clarify how future transition promises should be explained and monitored. Canada's recent green taxonomy and investor trust debate addresses the complementary question of which activities qualify for sustainable financing in the first place.

Risk Compliance And Regtech

FSB Finalizes 12 AI Risk Practices for Financial Institutions

October 15, 2026, Global
  • The Financial Stability Board finalized 12 sound practices for responsible AI adoption by financial institutions, following its June consultation and review of approximately 160 responses.
  • The practices cover board accountability, AI risk assessment, model selection, data governance, explainability, performance monitoring and human oversight throughout the AI lifecycle.
  • Financial institutions are also encouraged to manage AI cybersecurity risks and third party dependencies, including concentration and business continuity risks. The practices are voluntary and do not introduce binding requirements.

The FSB has given financial institutions a common reference for assessing AI controls across business lines and technology providers. Banks and fintechs can compare their existing governance, vendor contracts, model inventories and monitoring against the final practices. The commercial challenge is keeping controls proportionate as AI adoption expands without making every deployment slower or more expensive.

FCA Finds Market Abuse Surveillance Gaps at Seven Retail Brokers

October 14, 2026, United Kingdom
  • The UK Financial Conduct Authority published Market Watch 86 after supervisory visits to seven retail brokerage firms.
  • The review examined surveillance systems, escalation and governance for suspected insider dealing and market manipulation in retail equity trading.
  • The FCA identified weaknesses in how firms manage alerts, review potential suspicious trading and demonstrate effective oversight. These are supervisory findings, not newly enacted trading rules.

Retail brokers cannot treat surveillance as a technology purchase and assume compliance is handled. Alert thresholds, investigation judgments and management review determine whether suspicious trading is escalated. NCFA’s market abuse risk research also covers more complex automated trading behavior. Brokers need case files and decision trails that stand up to supervisory examination.

Weekly Close

This week brought production stablecoin payment services, a live €150 million blockchain loan and new rules for securities settlement and financial disclosures. Canadian firms also gained overseas payment access while domestic regulators advanced trading controls and reporting requirements. For founders, the opportunity lies in replacing costly operational steps with services customers will use repeatedly. Investors should look beyond launches to actual volumes, integration costs and the obligations that follow when a product becomes financial infrastructure.

NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.


NCFA Canada logoThe National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter