






Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 4, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Digital Assets, Embedded Finance
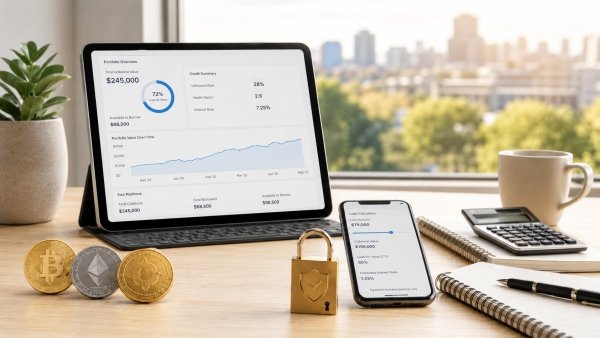
On September 3, 2026, Toronto-based APX Lending launched a five-year crypto-backed line of credit that lets eligible borrowers pledge Bitcoin, Ethereum or both, draw funds, repay them and borrow again. APX says the facility supports borrowing up to 60% loan to value, with annual rates from 10.49% to 11.99% depending on the outstanding balance.
Interest applies only to money actually borrowed, with no charge on unused capacity. APX also says there are no origination, prepayment or liquidation fees. The biggest change from APX's existing fixed-term loans is that borrowers can use the credit line more than once. They can keep approved collateral in place, draw funds when needed, repay them and borrow again.
APX gives the example of C$200,000 of Bitcoin and C$100,000 of Ethereum supporting up to C$180,000 of borrowing at the maximum 60% LTV. Available credit changes with the value of the collateral, so a falling crypto market can reduce borrowing capacity quickly.
The basic idea will be familiar to anyone who has used a securities-backed line or borrowed against property. The difference is the collateral. Bitcoin and Ethereum trade around the clock and can fall sharply in a short period, which makes ongoing collateral management a much bigger part of the borrower experience.
For long-term crypto holders, the attraction is access to cash without selling the underlying asset. That can help with business funding, debt repayment or other liquidity needs, although borrowing costs above 10% mean APX still has to compete with conventional secured credit where borrowers have access to it.
APX begins warnings when a loan reaches 80% LTV. At 90%, collateral is partially sold until the loan returns to 85% LTV. APX introduced the 90/85 liquidation model in August and says there is no liquidation fee.
A borrower can still lose Bitcoin or Ethereum when prices fall. APX's approach changes how much gets sold once the threshold is reached rather than removing liquidation risk altogether.
Custody is part of the product design as well. The OSC decision granting APX exemptive relief says collateral held under the lending arrangement is not rehypothecated (not reused or lent out to other parties). APX says assets are held in segregated BitGo Trust cold-storage wallets. Client accounts are not protected by CDIC or the Canadian Investor Protection Fund.
The revolving line follows APX's July launch of embedded crypto lending with Netcoins. Eligible Netcoins users can access APX loans through the platform while APX supplies the capital, underwriting, collateral management, compliance and servicing.
APX therefore doesn't have to rely entirely on finding borrowers through its own brand. Exchanges and wealth platforms can potentially add crypto-backed credit without building the lending operation themselves. The new revolving facility has not been announced as a Netcoins product, so the partner channel and the new line should be treated separately for now.
Ontario's securities regulator granted APX time-limited exemptive relief for its crypto-backed lending model, with the decision extending to participating jurisdictions through Canada's passport system. The order covers Bitcoin and Ether collateral and sets conditions around custody, disclosure and account suitability. It is tailored to APX and expressly says the decision should not be treated as precedent for other applicants.
APX is entering a market where other Canadian platforms are experimenting with similar products. Shakepay's Bitcoin-backed credit line, launched in August, gives eligible Canadians another way to borrow against digital assets. Cayman-based Ledn also continues to offer Bitcoin-backed Dollar Loans in most Canadian provinces, although Quebec, New Brunswick, Nova Scotia and Saskatchewan are excluded. APX differs by supporting both Bitcoin and Ethereum and by offering a five-year revolving facility rather than Ledn's standard 12-month Bitcoin-backed loan.
One platform can own more of the lending relationship itself; another can plug into a specialist lender such as APX. For exchanges and wealth platforms, embedded credit creates a way to earn more from customers who already hold digital assets without forcing those customers to sell them.
Will crypto holders use Bitcoin-backed credit often enough to make it a mainstream secured lending product?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Sep 3, 2026
Anyone who has onboarded a client at a fintech startup knows the bottleneck. The product works, the API integration is done, and then someone emails a photo of a passport taken at an angle in bad light, with half the machine-readable zone cut off. Multiply that by fifty applicants a week and your compliance queue turns into a photo-editing job.
Small lenders, brokerages and crypto exchanges all hit the same wall. Identity verification and record-keeping are document-heavy by law, and the documents arrive in whatever format the customer's phone produced.
That is the gap a mobile scanner fills. OKEN, listed on the Play Store under the longer name OKEN - camscanner, pdf scanner and published under the name CAMBYTE Pte. Ltd., is a Productivity app that turns a phone camera into a document scanner with edge detection, OCR text recognition, and export to PDF, JPG, Word or TXT. It also reads QR codes, which matters more than it sounds in a payments context.
The core loop is straightforward. Point the camera at a page, let the app find the borders, and it flattens the perspective into something that looks like it came off a flatbed scanner rather than a kitchen table.
OCR is where the finance use case gets interesting. A scanned invoice or ID page that carries a searchable text layer can be indexed, queried and pulled up during an audit without anyone flipping through image files. A scan without OCR is just a picture of information.
The format range is the practical part for anyone assembling a client file:
The store listing pitches it at students and small business people, accountants, realtors and managers. That is a fair description of who benefits most: teams too small to own scanning hardware but still accountable for the same paper trail as the big institutions.
Phone scanning is fine for capture. It stops being fine at the point where you have thirty scanned pages sitting on a handset and a Windows machine holding your CRM, your case management system, and the shared drive your auditor actually looks at.
That handoff moment is usually why people start looking at OKEN scanner for PC rather than sticking with the phone alone. On a desktop, the app runs inside an Android emulator, and the exported PDFs land somewhere your other software can reach.
Most emulator advice is generic. For a scanner app, only a couple of things really change the experience.
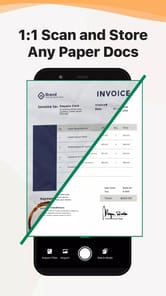
Batch OCR is noticeably more comfortable on a large monitor. Correcting a misread account number in a recognized text layer is tedious on a 6-inch screen and fast with a keyboard.
Treat the app as capture and formatting, not as verification. OKEN produces a clean, readable, searchable document. It does not authenticate an identity document, check it against a sanctions list, or satisfy any regulator on its own.
For internal paperwork, supplier invoices, signed agreements and expense records, that distinction barely matters. For customer identity files it matters a great deal, and the scanner should sit in front of a proper verification provider rather than in place of one.
One caveat worth carrying away: scanned identity documents are among the most sensitive files a small firm will ever hold. If you run the app on a shared office desktop through an emulator, the exported PDFs live in a Windows folder that anyone with access to that machine can open. Decide who that is before the first scan, not after.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
On September 3, 2026, Canada's July trade report put two stories beside each other. Exports to the United States fell 6.6%, while exports to countries outside the U.S. rose 7.4% to a record C$25.6 billion. Canada's merchandise trade surplus with the world narrowed from C$4.2 billion in June to C$769 million. Its surplus with the United States fell from C$10.3 billion to C$5.9 billion.
Those numbers now sit inside a much rougher political relationship. On August 22, the United States imposed a 50% tariff on roughly US$20 billion of Canadian exports, while the Government of Canada values the affected goods at C$27.6 billion. Canada has rejected the terms on offer and announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
Canada is still deeply tied to the U.S. economy, but the reaction is no longer confined to government. Buy Canadian sentiment has returned. Companies are reviewing suppliers and customers. Travel choices have changed. More Canadian businesses are looking beyond the U.S. at the same time that Ottawa is asking them to absorb the cost of doing it.
The question running through this story is whether the tariff fight is merely disrupting Canada U.S. trade or helping create commercial relationships that remain different even after the politics cool.
The evolving trade war began with a border argument. Washington said Canada was not doing enough on fentanyl and border security. Ottawa said the scale of the problem did not justify an economy wide tariff and answered with retaliation rather than concession.
Ottawa disputed the premise while tightening the border anyway. Canada argued that the U.S. was imposing an economic penalty far larger than the border problem it cited. At the same time, Ottawa strengthened enforcement, giving the fight an early contradiction that never really disappeared.
North America already has a trade agreement designed to make cross border commerce predictable. The surprise is not that Canada and the U.S. disagree. It is that the disagreement can still produce sweeping tariffs while CUSMA remains in force.
CUSMA then became the shield Canadian companies hoped it would be. A large share of continental trade kept moving under the agreement, offering businesses a degree of protection from the broad tariff threat.
The most politically sensitive sectors did not get the same protection. Steel, aluminum and autos became proof that a trade agreement could survive while the industries most tied to jobs, factories and regional politics still took direct hits.
CUSMA remains in place, but businesses now know that compliance with the agreement does not eliminate every tariff risk. A company can remain inside the North American trade framework and still be exposed to a separate sector fight.
Canada entered the 2026 CUSMA review looking for certainty and left without it. Ottawa wanted companies to know the North American rules would hold for another generation of investment. The review did not deliver that reassurance.
The United States did not give Canada the long runway it wanted. The agreement stayed alive, but companies making plant, supplier and capital decisions measured in years were left with a shorter political horizon.
The agreement remains in force. But the failed long term extension means companies can no longer assume the relationship will simply return to the old operating model after one review.
Then the tariff ceiling moved again. After bilateral talks failed, Washington raised the pressure to levels that made another Canadian response almost unavoidable. The dispute was no longer about whether tariffs would remain. It was about how much economic pain each side was willing to absorb.
Canada chose retaliation over the deal on the table. Ottawa said the U.S. terms would leave Canadian workers and businesses worse off. Canada announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
This is where the fight stops looking like a temporary tariff negotiation and starts looking like a choice about economic autonomy. Canada is accepting the risk of another round of costs rather than take terms Ottawa says would leave important industries worse off.
Trump then turned Lake Ontario into part of the dispute. The Lake America order gave Canadians something more visceral than a tariff table to react to. A fight over market access suddenly had a symbol that touched geography, identity and sovereignty.
The symbolism hit a country already primed to push back. The tariff fight had been accompanied by statehood rhetoric and repeated claims that Canada depended too heavily on the United States. The lake renaming made the argument feel less like a dispute over customs schedules and more like a challenge to Canadian identity.
A tariff can feel remote until it affects a price, a contract or a job. Renaming a shared Canadian lake for U.S. federal purposes created a cultural symbol that was easier to understand and harder to separate from the wider sovereignty argument.
Canadian resistance is showing up in everyday choices. Buy Canadian sentiment has strengthened as consumers reconsider groceries, travel, technology, vehicles and other purchases. Businesses are also reviewing where they source products and whether U.S. dependence still looks commercially sensible.
American opinion is much less supportive of the escalation. A Reuters Ipsos poll found 57% of Americans opposed the latest tariffs on Canada and only 20% supported them. The same poll found 63% opposed Lake America and 14% supported it.
Canadian patriotism has many sources, so the tariffs should not be treated as the sole cause. But the observable response to repeated tariff threats, statehood rhetoric and Lake America includes stronger Buy Canadian behaviour, support for retaliation and a more explicit case for economic self reliance.
Some companies are acting on the anger instead of waiting it out. Reuters reported that Chapman's Ice Cream plans to cut U.S. imports by 70% by mid 2027. Other firms are reviewing suppliers, sourcing more at home and looking for customers outside the United States.
Once a supplier is replaced, politics may not put the old relationship back together. New contracts, certifications, logistics routes and internal processes create switching costs. A future agreement could remove a tariff quickly while leaving behind commercial relationships built during the dispute.
This is where a patriotic reaction can become structural economic change. The first purchase may be emotional. The lasting effect depends on whether Canadian and non U.S. alternatives become good enough to keep the customer or supplier relationship after the anger fades.
The July numbers show Canada really is looking elsewhere. Exports outside the United States rose 7.4% to a record C$25.6 billion. Non U.S. destinations accounted for roughly one third of Canadian merchandise exports in July.
America is still too large to replace quickly. Canada's trade surplus with the U.S. fell to C$5.9 billion in July, while Canada ran a C$5.1 billion deficit with countries outside the U.S. More trade elsewhere reduces concentration before it replaces the commercial value of the American market.
The record non U.S. export figure shows diversification was already underway before the August 22 escalation. It does not prove the newest tariffs caused the change. It does show Canada was already finding more business outside the U.S., even while the American market remained too large to replace quickly.
Every new route creates another bill before it creates resilience. New buyers can require longer shipping, different payment terms, more foreign exchange and more working capital. New suppliers can require deposits, inventory changes and fresh credit checks. The cost arrives before the exporter knows whether the new relationship can match the economics of the old one.
Canada can become less exposed to one market while making individual companies more complicated to finance. Diversification works only if firms have enough liquidity to survive the period between leaving an old relationship and making a new one profitable.
Lenders now have to see tariff risk before the financial statements do. U.S. customer concentration, tariff sensitive inputs, margin exposure and the time needed to replace a buyer can change a borrower's risk within weeks. Historical revenue can therefore look healthy while the economics underneath it are already deteriorating.
Payments, foreign exchange and treasury providers face the opposite problem. More destinations create more currencies, settlement routes, counterparties and cash timing issues. The same diversification that reduces geographic concentration can increase demand for cross border payments, hedging, trade finance, receivables tools and working capital.
Trade policy becomes financial services work once companies start changing customers and suppliers. Credit has to recognize new exposure sooner. Payments have to reach more markets. Treasury teams have to manage more currencies. Working capital has to cover the period before new trade relationships mature.
Markets still assume some of this confrontation eventually fades. Currency forecasts are already looking past the current hostility and pricing a calmer relationship later. Businesses have less freedom to wait for that version of the future.
Businesses cannot wait for that forecast to come true. Carney said on September 1 that the United States must start being serious before talks can resume. At that point no new bilateral negotiations were scheduled. A company choosing a supplier, market or plant location has to make the decision under today's rules.
That is the deeper consequence of the dispute. Governments can reverse tariffs quickly. Companies that have spent months replacing suppliers, winning customers and building payment routes may have less reason to go back. The tariff war could therefore leave a commercial footprint that lasts longer than the tariffs themselves.
Talking Point
Trump's tariff campaign has done more than raise the cost of Canada U.S. trade. It has turned economic dependence into a Canadian political issue, revived Buy Canadian behaviour and pushed companies to look harder for customers and suppliers elsewhere. The unresolved question is whether that response leaves Canada with stronger companies and more durable trade relationships or simply a more expensive way to do business.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 2, 2026
India is increasingly relevant to fintech companies for more than market access. It is also a significant source of technology, product, finance, risk, data, and operational talent that global scaleups can integrate into international teams.
India's wider startup ecosystem had more than 2.23 lakh government-recognised startups by March 31, 2026, while the country's digital financial infrastructure continues to expand rapidly. UPI alone processed more than 24,000 crore transactions during FY26, illustrating the scale at which digital financial services now operate in the country.
For a Canadian or international fintech, however, deciding to recruit in India creates a strategic question:
Should the company establish an Indian entity before building a team, or can it begin hiring first and make the larger corporate investment later?
For many scaleups, these decisions do not need to happen simultaneously.
A phased talent strategy can allow a fintech to test access to Indian talent, build an initial team, understand operating costs, and validate its long-term requirements before committing to a full local entity.
India combines a large technology workforce with an established ecosystem across financial services, digital payments, software development, data, and startup innovation.
This creates hiring opportunities across functions that fintech companies frequently need as they scale, including:
India's digital payments ecosystem also gives fintech professionals exposure to financial products operating at substantial scale. UPI accounted for 85.5% of India's digital payment transaction volume in the second half of 2025, according to RBI data reported by IBEF.
But the business case for building a team should not begin with the question, "How many people can we hire?"
It should begin with:
Which capabilities should the company own internally, and which of those capabilities can be built effectively in India?
That changes hiring from a cost exercise into a talent strategy.
A fintech talent strategy defines which capabilities a company needs, where those capabilities should be located, and how employees will be hired, managed, and integrated into the organisation.
For an India expansion, a useful talent strategy should address five areas:
This is particularly important for fintech companies because many roles interact with sensitive financial data, regulated products, security systems, or customer operations.
Hiring should therefore be considered together with data access, information security, governance, internal controls, and business continuity.
The first India hires should solve clearly defined business problems rather than simply expand headcount.
A practical approach is to prioritise functions where the company already understands the workflows and can manage outcomes remotely.
| Function | Why a Fintech May Build It in India |
| Engineering | Product development, integrations, platform infrastructure |
| Data | Analytics, reporting, data engineering and modelling |
| QA | Product testing, automation and release support |
| Cybersecurity | Security operations and technical monitoring |
| Finance operations | Reporting, reconciliation and operational support |
| Customer operations | User support and service delivery |
| Risk operations | Process-driven risk and verification support |
| Product operations | Coordination between technology, product and commercial teams |
Leadership should also identify whether the function is supporting the global business or conducting activity directly in the Indian market.
That distinction can affect entity, regulatory, tax, and Permanent Establishment considerations later.
Yes, depending on the type of relationship and business activity.
A foreign fintech typically has several potential models available.
Contractors may be appropriate for genuinely independent, project-based work.
For example, a fintech might engage a specialist for:
Contractors should not simply be used as substitutes for employees where the actual working arrangement functions like regular employment.
A fintech can outsource a complete function or defined process to another company.
In this model, the external provider typically manages its own employees and delivers an agreed service or outcome.
That is different from building a dedicated internal team.
Where a fintech wants dedicated employees in India but does not yet have a local employing entity, an Employer of Record India model can provide another option.
The EOR becomes the legal employer in India, while the fintech continues to manage employees' daily responsibilities, goals, projects, and performance.
A fintech can establish its own Indian company and employ staff directly.
This generally provides greater long-term control but also introduces ongoing corporate, accounting, payroll, HR, tax, and administrative responsibilities.
The best structure depends on the company's stage and objectives.
| Factor | Contractor | Outsourcing | EOR | Own Entity |
| Dedicated employee relationship | No | Usually no | Yes | Yes |
| Local entity required | No | No | No for EOR employment | Yes |
| Client controls daily work | Limited by independent relationship | Usually outcome-focused | Yes | Yes |
| Local payroll | Not employee payroll | Provider handles employees | EOR handles | Company handles |
| Initial setup burden | Low | Low | Lower than entity | Highest |
| Suitable for testing India | Yes, for genuine projects | Yes | Yes | Possible but larger commitment |
| Long-term large workforce | Limited | Depends on model | Depends on scale | Strongest fit |
For a fintech building an internal product or operations team, the main comparison is often between EOR employment now and direct employment through an entity later.
Entity establishment is a strategic corporate decision.
Hiring can be an operational decision.
Those decisions may move at different speeds.
Suppose a Canadian fintech has funding to build a six-person engineering and data team in India. It already knows the roles it needs, but management is not yet certain whether India will eventually support 10 employees, 50 employees, or a much larger operation.
Immediately building a company around an uncertain headcount assumption can create unnecessary fixed infrastructure.
A staged approach allows the fintech to answer questions such as:
The business can then make its entity decision using operating evidence rather than projections alone.
Salary is only one component of India workforce costs.
Finance teams should compare the total cost of different structures.
Relevant categories can include:
An EOR may involve a per-employee service fee, while an owned entity introduces more fixed organisational costs.
The economics can therefore change as the team becomes larger.
Companies comparing these structures can also review State of India EOR 2026 when assessing employment costs, entity considerations, compliance responsibilities, and potential tax exposure.
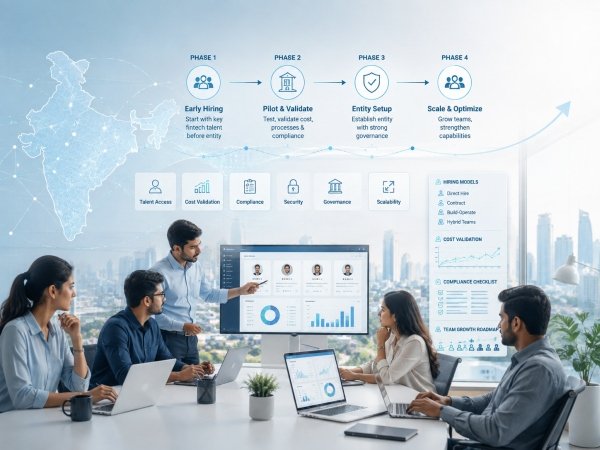
Fintech teams often work within more sensitive operating environments than ordinary remote teams.
The question is not simply whether a developer or analyst can work remotely.
Companies may also need controls around:
Employees may interact with customer data, financial information, transaction records, or internal risk systems.
Access should be based on role requirements.
Devices, authentication, credentials, source code, and internal platforms require appropriate security controls regardless of where employees are located.
Certain finance or payment workflows may require multiple layers of approval rather than giving one employee end-to-end control.
Teams should understand who owns decisions, where approvals are recorded, and how processes are audited.
Hiring someone in India does not itself determine whether the fintech is permitted to offer regulated financial services in India.
Employment structure and financial-services licensing are separate questions.
A company building an India team to support overseas operations should therefore distinguish workforce expansion from market entry.
India's four consolidated Labour Codes came into effect on November 21, 2025, covering wages, industrial relations, social security, and occupational safety and working conditions.
Companies employing workers directly need processes covering relevant employment requirements, including areas such as:
Under an EOR structure, many agreed employer-side administrative responsibilities are handled by the EOR.
However, using an EOR does not remove the fintech's responsibility for how employees access systems, handle information, perform regulated activities, or represent the business.
Potentially, depending on what the employees do.
An EOR or contractor arrangement does not automatically eliminate Permanent Establishment or wider business-connection considerations.
India's Income Tax Department states that business income of a non-resident can be taxable in India where the enterprise has a Permanent Establishment or business connection, subject to applicable tax treaties.
Indian tax rules also identify activities such as habitually concluding contracts or playing a principal role leading to the conclusion of contracts as potentially relevant to business-connection analysis.
A fintech should therefore obtain appropriate tax advice where India-based personnel:
A developer supporting a global product and a senior commercial executive entering contracts on behalf of the foreign company may present very different risk profiles.
An entity can become increasingly attractive as India moves from an experimental talent location to a strategic operating hub.
Common indicators include:
There is no universal employee number at which every fintech should incorporate.
The decision should consider scale, cost, tax, regulation, employment requirements, business activity, and long-term strategy together.
A practical expansion sequence can look like this:
Identify the roles that India can support and the business problem each role solves.
Recruit a small number of clearly defined roles using an appropriate employment structure.
Implement security, communication, management, documentation, payroll, and performance systems.
Compare productivity and total employment costs against the original business case.
Estimate whether the India operation is likely to remain a small global team or grow into a major operating centre.
Once the scale and commercial requirements are clearer, evaluate establishing a local entity.
This approach allows a fintech to treat entity setup as a consequence of proven scale rather than a prerequisite for exploring Indian talent.
For fintech companies that want employees in India before establishing their own entity, Asanify provides an India-focused Employer of Record model.
Asanify operates through its own Indian entity and can act as the legal employer while the client fintech retains control over employees' daily work, responsibilities, and performance.
Its EOR support can include:
This structure can be useful for scaleups testing the Indian talent market or building an initial team while their long-term entity strategy remains under evaluation.
Tax, regulatory, financial-services licensing, PE, data, and other business-specific risks should still be assessed separately.
For fintech scaleups, India expansion should start with the capabilities the business needs, not with entity setup.
Companies can first define the right roles, choose a suitable employment model, and validate costs, compliance, and team performance. This gives leadership a clearer view of how India fits into the wider operating strategy.
As the team grows, the business can then decide whether a larger local infrastructure or entity is justified. A phased approach helps keep early expansion flexible while supporting more informed long-term decisions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 30, 2026
In today's busy market, new founders have to stand out from all the noise. They need to look for new ways to get non-dilutive help and support from ventures. A lot of times, things like repeating income or how much money a company brings in can take a long time to show up. Because of this, people who back these companies now try to find other ways to see if the market wants what the company offers. Many likes, comments, and shares online can be strong signs that people are interested in the brand, even before its first product comes out.
To grow, companies have to use smart ways that grab attention fast. The right platforms and smart marketing help reach more people, make others share, and raise the brand’s name in the market. This can turn someone scrolling on social media into a true fan or bring in the first real support. When you use new tools like Blastup Instagram likes, new businesses can get noticed by backers who can help them take off.
Digital finance asks people to trust what they read and see online. On sites like Kickstarter, Wefunder, or Republic, people do not just look at ideas and promises. They read what others say about the project. They also check if people are talking about it and see how many people are taking part in these talks online.
A high interest means there is less risk in the market for people who may support it.
Social media sites pay more attention to posts that get many likes and shares very fast. When a startup gets many people to talk or react to a post, more people see it. This helps the page reach even more people. A bigger reach lets more users find crowdfunding pages. It brings in extra visitors and can help more people give money.
Social numbers are not only about how things look. They are real tools for marketing. They can help people think about a brand in a good way from the start. This can also help get money faster at the beginning.
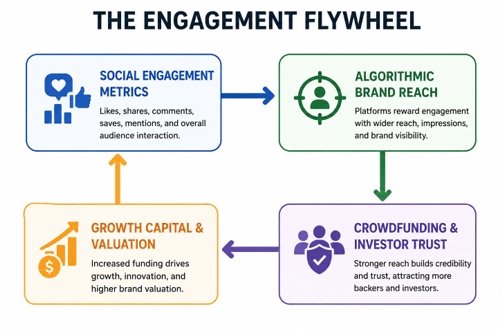
| Metric | Core Focus | Direct Impact on Funding |
| Engagement Velocity | Speed of likes, comments, and shares on new posts | Accelerates algorithmic placement and press interest |
| Audience Depth | Frequency of long-form comments and discussions | Signal of high customer retention and brand loyalty |
| Conversion Velocity | Ratio of social followers to email subscribers | Demonstrates commercial intent to institutional VCs |
When founders use clear stories with good ways to get people interested, they make a way to work that old-style outbound marketing cannot match.
To bring together both social proof and getting digital money in a good way, startups should use a clear three-step plan.
Digital finance is changing how people put their money in projects. In this, social proof is one of the main things for crowdfunding to work well. If founders know how to get people’s attention, they can turn talks on social media into real ways to get money that lasts. When you use the right steps to grow Instagram likes and reach more people in the community, your company can build trust and social proof. This can help you pull in investors, go over your crowdfunding goals, and let your business grow with time.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 26, 2026 | NCFA Community Announcement | Fintech And Innovation, Artificial Intelligence And Data, Capital Markets And Funding
Elevate is less than a month away! Checkout the latest Elevate 2026 agenda giving founders, investors and technology operators a closer look at the conversations coming to Toronto from September 22–24.
For Canada's fintech community, the mix is worth watching. Elevate's 2026 programming spans fintech, artificial intelligence, capital, commercialization and other technologies competing for investment, customers and talent. NCFA is a Community Partner for this year's festival at Meridian Hall.
Canadian fintech has a direct place in the program.
Eva Wong, Co-Founder and Chief Product Officer of Borrowell, is among the announced speakers, bringing experience from one of Canada's established consumer fintech companies to discussions about product, fintech and the development of Canada's digital finance market.
The latest agenda announcement also highlights Mati Staniszewski, Co-Founder and CEO of ElevenLabs; Adam Collins, Chief Communications Officer at Reddit; and Jessica Chalk, Founder and CEO of myStoria.
Those adjacent technology perspectives are relevant to financial innovators. AI is entering customer service, fraud detection, compliance, product development and internal operations, while fintech companies still have to turn technical capability into products customers trust and businesses can scale.
For founders, the useful question isn't simply which technology attracts the most attention. It's where new capabilities can solve a real financial problem, reach customers and support a viable company.
Elevate is also expanding direct access between founders and investors.
Its Meeting Exchange program is doubling capacity for 2026, with more than 750 curated one-to-one meetings for investment-ready startups.
That adds a practical capital component to a festival expected to bring together approximately 10,000 technology professionals, entrepreneurs, founders, executives and investors.
For early and growth-stage companies, concentrated access to investors, potential customers, partners and other founders can make the trip more useful than a schedule built around stage content alone.
NCFA community members can receive 20% off General Pass tickets for Elevate Festival 2026.
Use promo code: NCFAELEVATE20
📅 September 22–24, 2026
📍 Meridian Hall, Toronto
More speakers and sessions are being added ahead of September.
For fintech founders, investors and operators, the value is in the overlap. Finance is colliding with AI, new infrastructure, changing customer expectations and tighter competition for capital. Elevate offers three days to test ideas with people building, funding and buying technology across those markets.
#ElevateFest2026
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 25, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Competition And Market Structure, Open Banking Open Finance And Data Sharing
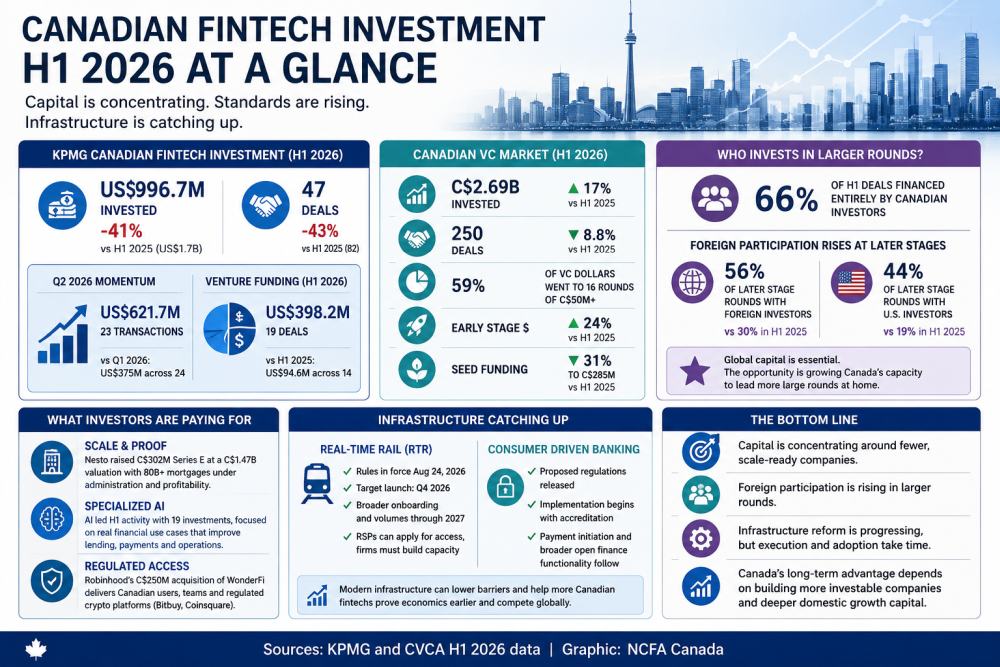
On August 25, 2026, KPMG reported KPMG H1 fintech data showing US$996.7 million across 47 Canadian fintech deals in the first half of 2026. Its current comparison puts that against about US$1.7 billion across 82 deals a year earlier, leaving both investment and deal activity down more than 40%.
Q2 was much stronger than Q1 without producing more deals. Investment climbed to US$621.7 million across 23 transactions from US$375 million across 24. Venture funding reached US$398.2 million across 19 deals from US$94.6 million across 14. Almost the same number of transactions attracted substantially more capital.
Canada's broader venture capital market tells a different story. Canada H1 venture data show C$2.69 billion invested across 250 deals, with dollars up 17% and deal count down 8.8%. Sixteen rounds of C$50 million or more absorbed 59% of all venture capital.
Look at the funding source of those larger cheques. Rounds financed entirely by Canadian investors represented 66% of H1 venture transactions, but foreign investors participated in 56% of later stage rounds, up from 30% a year earlier. U.S. investors participated in 44%, up from 19%.
Global capital is valuable to Canadian companies and should remain part of the funding mix. However, the opportunity is to build more domestic capacity to lead large rounds as companies scale, allowing Canada to retain more ownership, investment influence and financial upside while still attracting international investors.
KPMG and CVCA measure different markets. KPMG includes venture capital, private equity and M&A, while the CVCA figures above cover venture capital. Together, they show a funding market where larger commitments are going to a relatively small group of companies.
KPMG says investors are favouring scale, specialized AI capabilities, competitive positioning and demonstrable economics. For Canadian fintechs, the funding bar is getting clearer and harder to clear.
The largest Canadian fintech financing in KPMG's H1 data was Nesto's C$302M Series E in June at a C$1.47 billion valuation. The Montréal mortgage technology company entered the round with more than C$80 billion of mortgages under administration, more than C$37 billion of 2026 originations and a profitable business.
Nesto also owns lending technology and established mortgage businesses while building Nesto Cloud and Maestro AI for financial institutions. Investors were backing technology connected to customers, lending operations, distribution and a large existing financial market.
Regulated access can carry similar strategic value. Robinhood's WonderFi acquisition gave it Canadian customers, local teams and regulated crypto platforms through Bitbuy and Coinsquare instead of building that position from scratch.
AI attracted the most activity in KPMG's H1 data with 19 investments, compared with eight digital asset deals and four payments deals. KPMG says investors are favouring specialized applications that make lending, deposit taking and payment processing faster or more efficient.
That is already visible in Canadian financing. Float raised C$85 million to expand its AI business finance platform across payments, cash management and finance workflows. Nesto is applying AI to mortgage operations and lending technology. AI becomes easier to finance when it can lower costs, improve risk decisions, speed up work or increase revenue inside a financial product customers already use.
The early stage pipeline below those larger companies needs attention. CVCA says early stage investment dollars rose 24% on a flat deal count, while seed funding fell 31% to C$285 million. KPMG recorded 12 early stage fintech deals and eight seed rounds. Future Canadian scale companies depend on enough younger fintechs getting the capital and customers required to reach that level.
KPMG expects Consumer Driven Banking and the Real-Time Rail to improve fintech economics by opening access to financial data and payment infrastructure. Both are finally entering implementation after years of delay.
Canada's RTR access rules came into force on August 24. Payments Canada is targeting a Q4 2026 launch with initial direct participants, followed by additional onboarding and transaction growth through 2027. Registered payment service providers can pursue membership and RTR access, but firms still need the technology, settlement arrangements, fraud controls and operating capacity to participate.
Consumer Driven Banking is also getting closer to operation. Proposed regulations cover data access, accreditation, liability, security and technical standards. Implementation is expected to begin with accreditation after final regulations are published, while payment initiation and wider open finance capabilities come later.
These infrastructure reforms can reduce barriers that have favoured larger institutions, but firms still need the resources to integrate, comply and compete. Smaller challengers benefit when access becomes practical and affordable enough to improve their products and economics.
Canada's delay also affects how much experience fintechs build before competing internationally. In 2025, the Bank of Canada described payments modernization delays compared with the UK, Australia and EU. Fintechs in those markets have had more years to develop products around faster payments, financial data access and modern infrastructure.
Canadian firms are only now gaining some of the same tools. Infrastructure delays do not explain the success or failure of any individual company, but they can leave Canadian fintechs with less experience using capabilities that competitors elsewhere already know well. That can make winning customers and market share outside Canada harder.
Scale, licences, customer access and specialized technology are easier to finance once companies have had time to build them. If modern infrastructure helps Canadian fintechs prove their economics earlier, more firms could become credible candidates for larger rounds.
Canada's fintech funding concentration was already visible in 2025. H1 2026 makes the domestic question more pressing. Strong companies are still attracting large cheques, but fewer fintechs are reaching investors.
More selective investment can reward stronger companies, but Canada still needs enough firms coming behind today's winners. Better payment and data infrastructure can lower operating barriers. Applied AI can improve real financial workflows. Deeper domestic growth capital can help Canadian investors lead more large rounds.
The goal is not to make investors less selective. It is to produce more Canadian fintechs strong enough to earn their capital and compete globally.
Canadian fintech investors are backing scale, specialized AI, regulated access and proven economics, while international capital becomes more important in larger rounds. Can Real-Time Rail and Consumer Driven Banking help more Canadian fintechs build those advantages earlier while Canada develops more capacity to finance their growth at home?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
