





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


March 5, 2026 | NCFA Feature | Capital Markets And Policy And Regulation
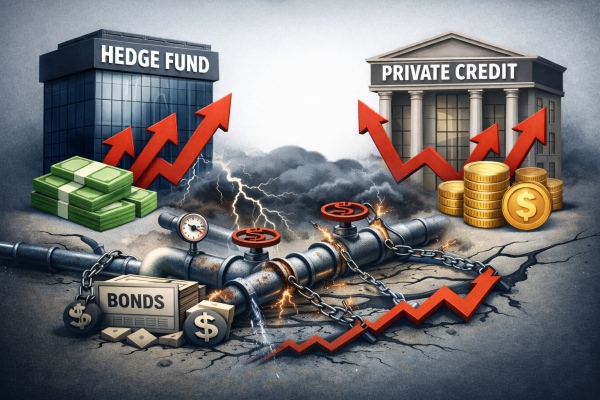
On March 4 2026, Bank of Canada Governor Tiff Macklem discussed how non bank finance can amplify stress in debt markets during remarks at the Global Risk Institute in Toronto. He pointed at two pressure points that matter for Canada right now:
Macklem puts a clear number on hedge fund demand in Canada:
"In Canada, they purchase up to 50% of Government of Canada bonds sold at auction and account for a big portion of secondary market trading.”
Hedge funds aren't just active in Canada. Similar patterns show up across many major economies. Hedge funds now hold a significant share of government debt outside central banks and large institutions. When government bond markets become unstable, the effects spread quickly. Mortgage rates, business loans, and corporate borrowing costs all move with government bond yields, so shifts in that market ripple through the entire economy.
The Bank highlights the repo market because repo borrowing funds many leveraged bond trades. A repo (repurchase agreement), works like a very short term loan. An investor borrows cash and posts government bonds as collateral, then agrees to buy those bonds back a day or a few days later.
Macklem says many hedge fund bond positions rely on this type of borrowing and are often highly leveraged. The structure makes markets sensitive to sudden changes in funding conditions.
He explains that “globally, about half have an overnight maturity. And haircuts are low zero or negative more than 80% of the time.” If lenders raise collateral requirements or reduce lending, investors may need to sell bonds quickly to reduce leverage.
When several large investors unwind positions at the same time, liquidity can vanish and prices can fall sharply. Macklem points to past episodes where this dynamic played out, including the global dash for cash at the start of the pandemic, the United Kingdom gilt crisis in 2022, and stress in the United States Treasury market in 2023.
Macklem also focuses on private credit because transparency is more difficult than in public markets:
“The opacity of private credit means investors may not have enough information about the quality of loans held in their funds.”
If defaults rise and investors rush for exits, he warns that the strain can spill into public credit markets. Canada connects to this risk because Canadian institutions invest in private credit globally, and funding links can pull stress back into the regulated system through liquidity needs and cross border channels.
The Bank of Canada is also changing how it plans to conduct its repo transactions. In a market notice, the Bank says it will join the Canadian Collateral Management Service tri party platform for its domestic repo operations by early 2027. CCMS is a market utility launched by TMX Group and Clearstream that helps participants move collateral, manage substitutions, and automate settlement for repo trades.
The Bank also says it intends to clear its repo operations through the Canadian Derivatives Clearing Corporation once TMX completes upgrades to expand central clearing services. CDCC acts as a central counterparty that guarantees settlement if one side of a trade fails.
The goal is to support stronger collateral management, reduce counterparty risk, and encourage broader use of modern repo infrastructure in Canada.
More lending and market activity now happens via non-bank firms who often use short term funding that can tighten quickly, not just traditional banks. When that happens, pressure in debt markets can build fast. Canadian institutions need better visibility into funding conditions, leverage, and collateral movement across markets. Fintech companies that help banks monitor liquidity, collateral, and repo exposures in near real time can fill an important gap.
At the same time, stronger market infrastructure matters for Canada’s competitiveness. Investors and dealers gravitate to markets that settle trades smoothly and manage collateral efficiently, especially during periods of stress.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply