






Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Aug 29, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Competition And Market Structure, Regulation And Policy, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Cross Border Payments And FX, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Payments Infrastructure And Money Movement

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026).
This is a material step beyond the group's 2025 exploration phase. TD and Scotiabank are now participating in a global bank-led issuance venture while Canada's own stablecoin framework is still moving through implementation. The Canadian question is whether major banks build meaningful CAD-denominated digital-money capacity alongside domestic initiatives or gain scale first through shared global USD infrastructure.
Coinbase supplies the regulated trading and custody stack while Webull keeps the investor interface and brokerage relationship. That reduces the infrastructure brokers need to build themselves and gives specialist providers another route into Canadian retail distribution. It also intensifies Canadian crypto competition over who owns the customer and who supplies the regulated back end.
LSEG is extending tokenization from private markets and settlement infrastructure toward public equities. The harder test is whether tokenized shares can preserve legal ownership rights, corporate actions, price integrity and regulated settlement while gaining wallet portability and longer trading access. If that model works, public-market infrastructure begins competing directly with blockchain-native distribution without abandoning the protections of an exchange-listed security.
Coinbase is bringing regulated crypto derivatives distribution into Canada without routing the products through Coinbase Canada itself. The important boundary is eligibility as it expands access for sophisticated investors while keeping the offering outside ordinary retail availability. It also gives regulated venues a stronger alternative to offshore derivatives platforms for Canadian capital, hedging and price discovery.
The important development is bank ownership of shared tokenized deposit infrastructure, not the financing round. Cari is moving toward production with banks helping govern, fund and use the network while retaining the customer relationship. Alongside other shared bank blockchain infrastructure, the test is whether common digital money networks can achieve enough participation and interoperability to compete with institution specific systems.
Forty-three state licences give OpenPayd something infrastructure providers can't create through software alone: regulated geographic reach. The company can now connect its payment stack to a much larger U.S. operating footprint while combining fiat and digital asset permissions across the United States, United Kingdom and Europe. The test is how quickly that regulatory coverage converts into client activity and payment volume.
Final approvals put the transactions into execution. National Bank is positioned to absorb Laurentian's retail and SME relationships while Fairstone combines its commercial lending operations with Laurentian's commercial specialization. Customer migration, product continuity and retention now determine how much of the approved transaction value survives the transfer.
Singapore is converting stablecoin policy into the legal requirements issuers will operate under. The consultation advances the status tracked in NCFA's stablecoin regulatory intelligence from a finalized framework awaiting legislation toward implementation. Reserve, redemption, capital and cross-border requirements can now be tested against issuer economics before the rules are finalized.
The case makes privileged information a concrete event contract surveillance problem. Exchanges and brokers need controls that can connect unusual positions with access to confidential information, investigate suspicious activity and enforce trading restrictions. NCFA's regulated event contract infrastructure brief tracks this market integrity gap as distribution expands.
Section 311 can reach beyond a targeted foreign bank because U.S. institutions must also identify transactions routed indirectly through other correspondent relationships. Banks and payment firms therefore need enough counterparty visibility to detect the institution behind a payment chain, not only the correspondent presenting the transaction.
The investigation puts transaction monitoring and global compliance governance under direct supervisory scrutiny at a major cross-border payment provider. The operating test is whether controls identify known laundering typologies across high-risk channels and whether global decisions support local obligations. The eventual findings could provide useful evidence for how regulators assess AML controls across international payment networks.
Australia's AML expansion has reached the point where AUSTRAC is testing whether newly covered firms have entered the regulatory system at all. Service classification, enrollment and working AML controls can no longer remain implementation projects. Regtech providers also gain a much larger addressable compliance market, but buyers will need products matched to obligations regulators are actively checking.
Conditional approval advances Revolut from U.S. fintech distribution toward direct regulated banking capacity. Its U.S. business still relies on a partner bank, while NCFA's Revolut company intelligence had tracked the national bank application as pending. A completed charter would give Revolut more control over deposits, credit and payment connectivity, but the remaining federal approvals and preopening requirements still determine whether that capacity reaches customers in 2027.
OpenReserve is trying to combine conventional banking, tokenized deposits, digital asset custody and stablecoin infrastructure inside one national bank structure. Preliminary approval brings that model closer to regulated operating capacity, but the remaining test is execution: capital, controls, final authorization and separate approval for the planned stablecoin subsidiary still stand between the proposed structure and live customer activity.
TabaPay is trying to internalize regulated banking capacity rather than relying exclusively on sponsor bank relationships. Owning an OCC chartered bank could give the payments fintech more control over settlement, sponsorship, redundancy and difficult client use cases while retaining outside bank partners. The acquisition still requires regulatory approval, making the next test whether supervisors accept that vertical integration and its governance model.
A successful Swedish licence would turn Allica's international expansion from a funding plan into regulated market access. The bank now has to prove that its UK SME model can satisfy a new supervisor and compete in a concentrated, highly digital banking market. Approval would also give Allica a potential base for wider European expansion rather than requiring each new market to begin from the UK.
The US$3 billion target gives scale to the real time receivable funding model introduced in the United States this week. VersaBank is betting that faster access to bank balance sheet funding can take business from conventional securitization and warehouse structures. Fiscal 2027 will test whether partner demand converts into several billion dollars of new assets without weakening credit quality or funding economics.
The licence adds another authorized BNPL provider while reinforcing regulatory permission as a condition of market access in Saudi consumer finance. New entrants have to compete inside that perimeter, putting more weight on underwriting, merchant distribution, pricing and compliance execution once authorization is secured.
QR Ph is extending domestic interoperability into cross-border acceptance without requiring merchants to install another payment system. That reduces one of the practical barriers to international wallet acceptance, especially for smaller merchants. The competitive question is whether national QR networks increasingly become gateways through which global payment aggregators reach local commerce.
Agorá has crossed the real-money test identified in earlier Project Agorá testing. The harder questions now concern legal finality across jurisdictions, liquidity, interoperability and whether a shared multicurrency platform can reduce correspondent-payment friction at institutional scale without weakening central-bank control or commercial-bank money.
Banks are pushing deeper into stablecoins, tokenized deposits and direct control of payment infrastructure, while fintechs are trying to own more of the regulated stack themselves. The fight is increasingly over who controls the account, the customer relationship and the transaction flow.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 3, 2026 | NCFA Market Interest | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Wealth Investing And Trading
Kraken parent Payward has reportedly delayed its U.S. IPO again, this time to the second quarter of 2027 at the earliest. The company confidentially filed a draft registration statement in November 2025, then put the listing on hold in March as crypto prices, trading volumes and valuations weakened. Payward hasn't confirmed the new 2027 timing, so it remains a reported window rather than a scheduled IPO date.
The delay comes at an interesting point for the business. Payward reported US$508 million in Q2 adjusted revenue, up 17% year over year. Funded accounts rose 42% to 6.6 million, while assets on the platform were US$40 billion. Adjusted EBITDA was much thinner at US$23 million, and total platform transaction volume fell 18% to US$310 billion as crypto spot trading cooled.
Those numbers give Payward a pretty clear reason to wait. Revenue and customers are growing, but the company is still proving how much earnings it can generate when trading activity softens. Going public now would put that question in front of investors every quarter.
Kraken is still central to Payward, but the parent company now earns money from more than crypto spot trades. Asset based and other revenue accounted for 60% of adjusted revenue in Q2, up from 55% a year earlier. Payward also owns NinjaTrader, has added regulated U.S. derivatives through Bitnomial, and expanded into payments and card issuing through Reap.
Those businesses and revenue lines are important when trading slows. Payward's transaction volume fell 18% year over year, yet adjusted revenue still rose 17%. That doesn't make the company immune to crypto cycles, but it does show that the revenue mix is changing.
The acquisitions have also made Payward more complicated. Investors eventually have to decide whether futures, derivatives, payments, tokenized equities and infrastructure services add up to a stronger financial business or simply a larger collection of products. Staying private gives management more time to answer that with operating results.
Payward's recent transactions have valued its equity at about US$20 billion. The company also says it closed an US$800 million private funding round backed by investors including Citadel Securities, Jane Street, Oppenheimer and Tribe Capital.
The capital gives Payward capital and time, but the valuation also raises expectations for an eventual IPO. Public investors will want to see more than account growth. They will be looking at earnings, cash generation, trading volumes and whether the businesses Payward has bought can produce dependable revenue together.
The current quarter gives them both sides of the argument. A record 6.6 million funded accounts and 17% revenue growth are strong. US$23 million of adjusted EBITDA on US$508 million of adjusted revenue leaves much more room to prove that scale can turn into profit.
Payward's xStocks business is expanding beyond Kraken. xStocks distribution already reaches third party exchanges, wallets and blockchain applications, and Payward now says the products have passed US$40 billion in total volume, including more than US$20 billion settled onchain, across more than 200,000 holders.
The company took another step on September 1 when LSEG and Payward announced plans to explore tokenized UK public equities. Subject to regulatory approval, the London Stock Exchange intends to list xStocks on its planned LSE 24 venue in 2027.
If everything takes, that would put Payward beside a traditional exchange operator at the same time its own IPO waits. It is a good example of how far the company has travelled from being known mainly as a crypto exchange.
The biggest question is earnings. Payward can keep adding accounts and products, but public investors will want to see whether those businesses can produce stronger profits when crypto trading is weak. Q2 showed that revenue can keep growing while transaction volume falls. The next step is showing that more of that revenue reaches the bottom line.
The acquisitions also have to work together. NinjaTrader brings traditional futures clients. Bitnomial adds regulated U.S. derivatives. Reap adds payments and card issuing. xStocks adds tokenized equities. Payward Services sells some of the same technology to banks, fintechs and other platforms. If customers start using several of those products together, the company can earn more from each relationship without depending as heavily on one trading market.
Payward Canada is registered as a restricted dealer, giving Kraken regulated access across Canada. xStocks are still unavailable to Canadian retail clients, so Payward's wider product expansion won't automatically arrive here. Canadian access will depend on what regulators approve and which products the company decides to bring north.
Payward has private capital, growing accounts and several businesses still being integrated. It doesn't have to accept a public valuation today if management believes another year of results can support a better one.
There is risk in waiting too. Crypto markets can weaken further, acquisitions can disappoint and the IPO market may not improve on Payward's schedule. A private US$20 billion valuation is only as strong as the earnings and growth the company can eventually show public investors.
Kraken's IPO delay is therefore more than a calendar change. Payward is using the extra time to prove that it can grow into a larger financial platform, make its acquisitions pay off and earn enough outside crypto spot trading to support the valuation it wants when it finally lists.
Can Payward turn product growth into enough profit to support a US$20 billion public valuation?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 3, 2026
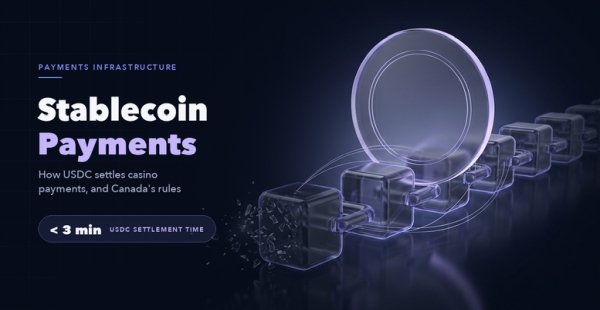
A credit card payment at an online casino costs the operator between 2.5% and 5% in processing fees, takes one to three days to settle, and carries a chargeback risk that averages 0.8% to 1.2% of total transaction volume. A USDC transfer on Solana or Base costs less than $0.01, settles in under three minutes, and cannot be reversed once confirmed on chain. For fintech professionals watching how stablecoin infrastructure performs under real production stress, online casinos have quietly become one of the most revealing test environments in payments.
This is not a story about which casino accepts crypto. It is a story about why the payment rails built under pressure from hostile acquirers are now structurally superior to legacy alternatives, and what that means for broader fintech infrastructure.
Online casinos operate under merchant category code 7995, one of the most restricted classifications in card network underwriting. Most tier-one payment processors refuse to onboard iGaming merchants entirely. Those that do charge premiums well above standard interchange rates, often landing between 3% and 5% per transaction.
The structural challenges compound from there. Chargeback rates in iGaming regularly exceed the thresholds set by Visa and Mastercard, triggering remediation programs that can end in merchant termination. Players expect withdrawals within minutes, yet ACH settlement runs on T+1 to T+3 timelines, and SWIFT transfers take three to five business days. The gap between player expectations and banking infrastructure creates friction at every point in the payment lifecycle.
These pressures created a forcing function. Operators that wanted to scale needed payment rails capable of high velocity cross-border flows, instant finality, reduced credit risk, and independence from acquirer gatekeeping. Stablecoin rails, particularly USDC, addressed all four requirements simultaneously.
When a player requests a withdrawal at a stablecoin casino, the transaction never touches an acquiring bank, a card network, or a correspondent banking chain. It travels on chain.
The operator's treasury system holds a liquid float in a hot wallet, sized to cover 24 to 48 hours of rolling withdrawal demand. The player's withdrawal request triggers a signed transaction broadcast to the blockchain. On Base or Solana, confirmation arrives in seconds with cryptographic finality. There is no authorization hold, no batch settlement window, and no reversal mechanism.
Chain selection matters at scale. ERC-20 USDC on Ethereum carries gas fees of $0.50 to $2.00 per transaction depending on network congestion. Solana reduces that below $0.001. Base sits below $0.01. For an operator processing 50,000 withdrawals per month, the choice of chain alone becomes a six-figure annual decision.
According to Circle, USDC has settled more than $70 trillion in cumulative on-chain transactions across institutional, B2B, and consumer use cases. This is production-scale infrastructure running across financial services, payments, and iGaming.
A direct comparison makes the economic case clearer than any narrative.
| Payment Rail | Settlement Time | Operator Fee | Volatility Exposure | Chargeback Risk |
| Credit Card | 1 to 3 days | 2.5% to 5%+ (iGaming premium) | None | High (MCC 7995) |
| Bank Wire (SWIFT) | 3 to 5 business days | $25 to $65 flat + FX spread | FX exposure | Low |
| Bitcoin (BTC) | 10 to 60 minutes | $1 to $30 variable | High | None |
| USDC (Base/Solana) | Under 3 minutes | Below $0.01 per transaction | None | None |
For an operator processing $10 million per month on card rails at a blended 3% iGaming rate, shifting to USDC represents roughly $300,000 in annual fee savings before accounting for chargeback losses.
Bitcoin is not a viable substitute at scale. Price volatility means any operator holding BTC in treasury carries mark-to-market risk on the liability side. A 10% price decline on a $1 million player balance creates an immediate $100,000 accounting gap. USDC, pegged 1:1 to USD and redeemable through Circle Mint, carries no equivalent risk. The liability stack stays USD-denominated throughout.
Platforms already running on these rails demonstrate the production reality. A live USDC casino operating at scale today faces none of the acquirer relationship risk, chargeback remediation exposure, or cross-border correspondent banking friction that card-dependent operators manage as ongoing cost centers.
In Canada, FINTRAC requires operators handling virtual assets, including stablecoins, to register as virtual asset service providers. This registration carries obligations for Travel Rule compliance at the transaction level and ongoing AML monitoring programs.
The regulatory trajectory is converging across jurisdictions. Canada's VASP framework, the EU's MiCA regulation, and emerging US stablecoin legislation all emphasize disclosure, reserve attestation, and Travel Rule compliance. USDC's monthly reserve attestation model, published by an independent accounting firm, already satisfies the transparency requirements taking shape in all three regulatory environments.
Operators building on Circle's infrastructure can inherit compliance controls directly. Circle's Payments Network includes built-in OFAC screening, Travel Rule messaging support, and AML monitoring capabilities. This reduces the compliance engineering burden materially compared to building a custom integration from scratch.
For Canadian fintech professionals, the key milestone to watch is FINTRAC's expected expansion of VASP reporting thresholds to cover stablecoin-specific transaction patterns. Operators and payment processors building on USDC rails now will have a compliance architecture head start when those requirements arrive.
On-chain settlement introduces a transparency layer that legacy payment infrastructure cannot replicate. Every deposit, withdrawal, and balance change is recorded on an immutable public ledger, creating a continuous audit trail without reliance on third-party attestation.
In iGaming, this connects directly to the concept of provable fairness. Understanding what is RTP in slots has traditionally required trust in third-party testing labs that certify return-to-player percentages. On-chain settlement opens the door to cryptographically verifiable RTP calculations, where players and regulators can independently confirm that game outcomes match published odds. This shift from trust-based to verification-based fairness represents a meaningful evolution for both player protection and regulatory oversight.
Programmability adds further capabilities that card rails cannot match. Smart contract-based bonus logic, automated affiliate settlement, and on-chain provable fairness are native to blockchain infrastructure. None require a third-party processor, a settlement delay, or a revenue-share arrangement with a payments intermediary.
The shift away from card rails in iGaming is structural, not cyclical. Card networks retain the unilateral right to remove a merchant category from acquirer eligibility without notice. That existential counterparty risk has no analog in stablecoin settlement, where the protocol itself has no commercial relationship with the merchant.
The cross-border advantage is equally concrete. USDC is natively issued across 37 blockchains and available in over 185 countries. Sending USD from Canada to a licensed offshore operator through a correspondent banking chain costs $30 to $60 per transfer and takes three to five business days. A USDC transfer costs less than a cent and settles in under a minute.
The onboarding friction for USDC is real: players still need a non-custodial wallet or an account on a centralized exchange. That friction is the primary reason card rails coexist in hybrid operator stacks. But for operators targeting experienced crypto users, the economics are unambiguous. And as wallet infrastructure improves, that friction is shrinking quarter by quarter.
A stablecoin casino is an online casino that accepts and settles player balances in USD-pegged stablecoins like USDC or USDT rather than fiat currencies or volatile cryptocurrencies. Operators use stablecoin rails to achieve near-instant withdrawals, eliminate chargeback exposure, and reduce payment processing fees to fractions of a cent per transaction.
On low-fee chains like Base or Solana, on-chain confirmation occurs in seconds with cryptographic finality. This compares to bank wire settlement of three to five business days and card processing of one to three days. The speed is structural, built into the protocol's confirmation mechanics, rather than dependent on processor batch windows or banking hours.
Licensed online gambling operates under provincial regulatory frameworks in Canada. Platforms handling virtual assets, including stablecoins, must comply with FINTRAC's VASP registration requirements, implement Travel Rule compliance, and maintain AML monitoring programs. Players should verify that their chosen platform holds valid licensing and is registered under the applicable VASP framework.
USDC is redeemable 1:1 for USD through Circle Mint at all times. Operator treasuries holding USDC carry no BTC or ETH price risk. The entire liability stack is USD-denominated, which means accounting, regulatory capital calculations, and player balance reconciliation all operate in the same fiat reference currency. This is a fundamental structural difference from Bitcoin or Ethereum reserves, where a price move creates an immediate liability gap.
Both are USD-pegged stablecoins, but they differ on compliance transparency and regulatory alignment. USDC, issued by Circle, publishes monthly reserve attestations from an independent accounting firm and is natively issued on 37 blockchains. USDT, issued by Tether, carries higher consumer adoption but provides fewer issuer-level compliance disclosures. For operators building compliance-forward stacks, USDC's attestation model aligns more directly with the disclosure requirements emerging under MiCA, FINTRAC, and US stablecoin legislation.
Online casinos did not adopt stablecoin rails out of ideological alignment with decentralized finance. They adopted them because card acquirers either refused to underwrite MCC 7995 or charged rates that made the business model unworkable.
The infrastructure built under that pressure is now the same infrastructure payment professionals are deploying for remittances, B2B settlement, and embedded finance. Near-zero fees, instant finality, zero chargeback exposure, and a USD-denominated treasury that requires no foreign exchange management: these properties are not specific to gambling. They represent the core value proposition of stablecoin payment rails in any high-volume, cross-border merchant category. The proving ground is already running at scale.
Circle - USDC Overview: https://www.circle.com/usdc
FINTRAC - Crypto Asset Guidance: https://www.fintrac-canafe.gc.ca/re-ed/crypto-eng
Wild.io USDC Casino: https://wild.io/casino/usdc-casino
Wild.io RTP Guide: https://wild.io/academy/articles/what-is-rtp
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 1, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, SME Finance And Business Banking, Digital Banking And BaaS
On September 1, 2026, London, Ontario based VersaBank announced the first U.S. Real-Time SRP implementation with ECN Capital. The system can fund eligible point of sale loans within hours. VersaBank says conventional funding can leave lenders waiting five to 30 days or longer while enough receivables accumulate.
ECN isn't a new customer. It implemented VersaBank's original U.S. Structured Receivable Program in 2025, and another ECN subsidiary joined the program in July with at least US$300 million in expected annual fundings. ECN Capital's Chris Johnson said the original SRP helped the company “grow our business faster” while improving profitability. The September implementation adds the newer real time capability, although VersaBank hasn't disclosed how much volume is flowing through it yet.
The scale is already substantial. VersaBank's total Structured Receivable Program portfolio exceeded C$4.4 billion as of January 31, 2026 after growing at a 33% compound annual rate over five years. U.S. SRP credit assets reached US$604.9 million by the end of the bank's second fiscal quarter of 2026, and VersaBank was targeting at least US$1 billion in additional U.S. SRP fundings during fiscal 2026.
What changes with ECN is speed. A funding model VersaBank has used in Canada for more than 15 years, and recently accelerated with Financeit, is now running in the U.S. with an established finance company.
Point of sale lenders need capital to keep making loans. A lender financing home renovations, HVAC systems, equipment or other large purchases may hold new receivables on its own balance sheet or borrow against them through a warehouse facility until the loans can be sold, refinanced or packaged into a securitization. That interval ties up capital and carries a financing cost.
VersaBank's Structured Receivable Program purchases qualifying receivables from finance companies. Real-Time SRP brings that funding closer to the original loan by evaluating and financing eligible individual receivables within hours rather than waiting for a larger pool to accumulate.
The model was first tested through an April Financeit pilot. The pilot finished ahead of schedule, and Financeit became the first partner to use Real-Time SRP at large scale when VersaBank formally launched the program in June. Financeit was approaching C$2 billion in annual loan originations, giving VersaBank a sizeable Canadian lending operation on which to prove the process before taking it into the U.S.
VersaBank describes the system as AI enabled, but its public disclosure supports a more targeted description. The bank says its internal AI technology helps evaluate individual loans underlying SRP receivables. It has not disclosed enough detail to determine exactly how eligibility, credit scoring, fraud checks or other decisions are divided between automation and human oversight.
Financeit completed a C$201 million ABS in June while also using VersaBank's real time funding. Those sources of capital can serve different stages of the same lending business. VersaBank can provide funding closer to origination, while securitization can provide longer term institutional capital after loans have accumulated into a larger pool.
Forward flow provides another option. Propel Holdings secured a US$60 million forward flow from Mesirow managed funds for Freshline loans, allowing institutional capital to purchase eligible production as it is originated. Warehouse lenders, forward flow investors, banks, private credit funds and ABS buyers are all competing to fund the period between a lender making a loan and receiving longer term capital.
VersaBank is trying to compress that period. The economic benefit depends on whether the cost of its funding, integration requirements and credit rules are attractive enough to save lenders money or free enough capital to justify adding another funding relationship.
VersaBank has operated versions of its Structured Receivable Program in Canada for more than 15 years. It entered the U.S. point of sale finance market after acquiring a U.S. bank in 2024, giving VersaBank an OCC chartered national banking platform in Minnesota.
VersaBank is doing more than licensing software to ECN. It's using deposits and its own balance sheet to buy qualifying U.S. receivables through a funding model developed in Canada. That lets the bank grow through lending partners without having to build a large consumer lending operation itself.
ECN is now using the faster version in the U.S. VersaBank already had hundreds of millions of dollars in U.S. SRP assets, and the wider ECN relationship includes at least US$300 million in expected annual fundings. The real time version gets eligible receivables onto VersaBank's balance sheet sooner.
Faster funding can help lenders keep more cash available for new loans, but only if VersaBank's price and credit rules beat the alternatives. Lenders already have warehouse lines, forward flow buyers, banks and securitization markets competing for their business, so speed alone won't win the account.
For VersaBank, more U.S. receivables mean more loans and leases earning interest on the bank's balance sheet without VersaBank having to find the borrowers itself. The economics work only if what the bank earns on those assets stays comfortably above its funding costs and credit losses.
Growth can also concentrate risk. A few large partners, weaker loan quality or rising deposit costs could turn faster asset growth into lower returns. ECN is the first U.S. user of the real time version, so the more telling evidence will be whether other lenders adopt it and whether those portfolios perform well as volumes rise.
Private credit adds another source of competition for finance companies seeking capital. Canadian institutions already have roughly C$500 billion of private credit exposure, much of it outside Canada, while U.S. private credit funds have become major lenders to businesses and specialty finance companies. VersaBank is entering that competition with a regulated bank balance sheet, a deposit base and a funding system designed to work much closer to loan origination.
Can VersaBank turn a Canadian funding model into a scalable U.S. lending business?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 2, 2026
Image: Magnific/Rawpixel.com
American retail currency traders navigate one of the most strictly supervised financial environments on earth. A company holding a proper Forex license within the United States offers top-tier security for customer capital and operates under full regulatory transparency. Mandates from the Commodity Futures Trading Commission (CFTC) and National Futures Association (NFA) enforce stringent balance sheet requirements on these platforms. Consequently, only a small, dedicated group of brokerage firms actively accept US residents in 2026.
Federal laws require every retail foreign exchange dealer to maintain at least $20 million in adjusted net capital. This massive financial requirement prevents undercapitalized entities from taking on retail accounts. Additionally, rules designed to safeguard individual deposits impose strict limits on daily trading operations.
Brokers must follow several mandatory execution rules across all trading accounts:
These stringent operating conditions eliminate high-leverage gambles and build a transparent trading environment. Traders who prioritize fund safety often view these regulatory guidelines as a protective buffer rather than a hindrance.
Active traders must research operational histories and compliance records before opening an account. Because foreign unregulated brokers frequently try to attract American traders with promises of extreme leverage, market participants must verify every regulatory claim through official government databases.
On the operational side, financial entities entering this market rely on experienced legal advisors to manage these complex international standards. SBSB Fintech Lawyers brings more than 13 years of experience in fintech, crypto, gambling, and investment consulting. Their team assists international firms with regulatory compliance, structural planning, and licensing solutions across global markets.
Before opening a live account, retail clients should evaluate specific features:
Smart traders check these details carefully before transferring capital. Verification of these factors keeps funds safe from unauthorized offshore entities operating without proper oversight.
Accounts opened within the US regulatory framework offer distinct financial benefits. Tax treatment represents a significant advantage for active market participants. While spot forex trades default to ordinary income rates under Section 988 of the Internal Revenue Code, traders can opt into a more favorable treatment. Under Section 1256, qualifying forex transactions receive a 60/40 tax split. Sixty percent of gains receive long-term capital gains tax rates, while forty percent fall under short-term rates, regardless of position duration.
Traders should consider several practical account management strategies:
Proper record-keeping combined with strategic account management helps market participants keep more of their earnings. American trading regulations impose tight boundaries, yet the enhanced security and favorable tax rules offer tremendous value to serious traders.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 2, 2026
Image: Pexels
Ontario has turned a small product detail into a serious design question. A deposit limit once looked like a setting near the edge of an account page. In 2026, the Ontario Lottery and Gaming Corporation moved it closer to the centre of the experience when it introduced a measure requiring some online players under 25 to set deposit limits as engagement rises through its safer gambling approach. That decision gives fintech designers a live case study in timing and restraint.
The point reaches beyond gaming. Banking apps, trading platforms and payment products all ask people to make money decisions on small screens. Speed helps when someone pays a bill and it can harm judgment when a screen nudges faster spending. Ontario’s model shows how a digital product can add friction at the right place without turning every action into a lecture.
OLG’s under-25 measure focuses on a group that research often links with higher gambling harm. The rule does not ban play. It asks certain users to set a cap as their activity grows. A cap can be daily or longer term. In financial design, the same idea can apply to stock trading deposits or crypto purchases. Earlier boundaries can reduce decisions made under pressure.
Ontario also gives designers a mature market to study. iGaming Ontario says its regulated market produced $82.7 billion in wagers during 2024 to 2025, with $2.9 billion in gaming revenue across more than 2.6 million active accounts in its annual report. A market of that size creates real design evidence. The best lessons come from how controls appear during ordinary use.
Spending controls work best before stress arrives. A daily limit has more force when someone sets it during account setup. A reminder has more value when it appears before a pattern becomes hard to interrupt. Product teams often want the shortest route to a completed transaction. Ontario’s approach suggests a better question for finance apps: at which point does speed stop helping the customer?
Investing apps already face a version of this test. A user may understand a company but misunderstand leverage. Another may know the price of a fund but overlook currency exposure. A good interface does not need to scold either person. It should show the cost, the limit and the consequence before confirmation. Ontario’s spending controls offer a model for that kind of intervention.
Casino comparison sites entered this landscape because choice became too large for casual browsing. Readers now compare payment methods, transaction times and withdrawal rules before opening an account. They also check licences, customer support and responsible-gambling tools before making a first deposit, a research habit that increasingly resembles fintech comparison. Someone choosing a trading app, for example, wants fees and account conditions visible before funding begins.
A regional review page can serve the same purpose by showing how product design differs across approved platforms. Someone looking at options selected by Casino.ca in Ontario can compare licensed casinos across practical criteria such as payment methods, withdrawal speeds, games and overall experience. The review format becomes more useful when it goes beyond a simple ranking and helps readers understand why platforms differ, including differences in security, banking options and customer support.
That structure also shows fintech teams how third-party guides can add value by making fees, risks, account controls and other important product information easy to inspect and compare. In both casino and fintech contexts, the strongest comparison experience helps users evaluate the product before they commit funds, rather than leaving important conditions until after registration.
Behaviour signals can help a product notice risk before a user asks for help. A sudden limit increase has meaning in one context and less in another. Several deposits in a short period can show excitement, confusion or distress. The product cannot read motive. It can slow the next step and offer support without pretending to know the full story.
The Alcohol and Gaming Commission of Ontario tells operators to use automated and manual monitoring so they can identify signs of harm and respond at a pace that matches changing behaviour in its operator guidance. Automated checks can catch patterns at volume. Staff review can add judgment where a rule may overreach. Fintech products need that same balance when they flag risky payments or rapid trading.
Crypto products face a harder version because transfers move fast and reversal options can be limited. A wallet app can show network fees and destination checks before a transfer leaves. A trading product can display volatility ranges before a purchase. Those steps protect choice by adding context. They work best when the words sound like service language rather than legal fog.
A control that users cannot find has little practical value. iGaming Ontario reported player awareness of responsible gambling tools at 71.5% in 2024 to 2025 through its 2026 to 2029 business plan. That figure gives product teams a hard target to think about. Of course, awareness doesn't arrive by placing a link in a footer. The interface has to bring the tool into normal view.
Fintech apps often place limits in account settings. Many users visit that area only when something breaks. Better design brings controls into the flow. A deposit screen can show the current cap. A payment app can show a monthly spending marker. A trading platform can let customers set cooling-off periods before volatile orders. The user still decides, but the decision gains context.
Language decides whether people use the feature. “Set a deposit limit” works better than “configure responsible-use parameters.” “Take a break” works better than a policy label. The same rule applies in banking. “Pause card spending” tells the user what will happen. “Manage transaction governance” sends them elsewhere. Good fintech design respects attention.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 31, 2026
Betting has been one of our favourite activities for centuries, with people eager to wager on what they predict will happen when dice are thrown, wheels are spun, and so on. For most of human history, it was an extremely low-tech activity that relied on everyone being in the same room. While those games still exist in much the same form, it’s become far easier to engage with them, thanks to the following key innovations.
A vastly wider range of games represents the biggest change in casinos since they went online. While casinos were always limited due to their physical space in the past, the switch to online sites allowed operators to greatly increase their collection of games. This began with the introduction of more classic games, such as roulette and blackjack, which were usually very similar to the traditional versions.
However, leading game developers have taken our favourites in new directions since then. The Sportaza online casino contains a huge variety of slots, such as Royal Coins by ELA Games, Chicken Road 2.0 by InOut, and 3 Million BC by Betsoft. These games take the tried and trusted slots mechanism from the past and add new themes. Features such as jackpots and bonus rounds have been added to create more varied gameplay too.
In terms of table games, the biggest change has been implemented through livestreaming technology, which allows casinos to host online games with live presentation. A group of 4K cameras is typically used to provide different camera angles that the player can choose from, giving a smooth, uninterrupted view of the action at all times. In some cases, augmented reality is added, meaning that the cards and chips on the screen move between digital and real life. The Google AR & VR page explains how these technologies fit together.
This has led to classic table games being reimagined with new features, such as multipliers and side bets. It’s also given us game shows including Candy Wheel, Football Thrill, and Robin the Fair. These games introduce giant wheels, slots rounds, and other types of props to let players place varied wagers in a live setting.
The integration of different types of betting on the same site has been another huge change in the way we gamble. Sports betting has always been about wagers placed before the action begins, which are then settled once the final result is known. When online sports betting began, it followed this same process. However, the work carried out to integrate live scores and updates onto the same sites as casinos has allowed sportsbooks to now provide live betting.
This means that fans can bet on games and events as they take place, predicting what happens next based on what they see happening at the time. This has fundamentally changed the way we place sports wagers.
It works through advanced APIs that integrate live event data. Automated risk engines look at the data and adjust the odds instantly to take into account the flow of the action. The other major change has come with the way that users can choose whether to cash out early. This can be done in those cases where a cashout price is shown during the game, so that users can decide whether it makes sense to accept that price or wait for the event to end.
Modern players don’t want to wait days or weeks for transfers to go through, which was one of the issues that held back the early online betting industry. Therefore, casinos now put their cashier experience as one of the most important parts of the overall site performance. This can be done thanks to the fact that several fintech innovations have helped make it a lot easier to move funds back and forth.
Digital wallets were among the earliest of the changes that were introduced to this sector, with the likes of Skrill and Neteller proving popular in North America. Canadians have also benefited from the introduction of Interac, which allows almost instant transfers to and from bank accounts. Interac is a decentralized interbank clearing network. In other countries, open banking allows users to easily move funds when they want to gamble.
The different types of innovation that have led to these changes have made it far easier for people to enjoy online gambling. As the industry carries on growing, we can expect to see more new technology and ideas being used. If you just want to spin some slots or put some chips on the blackjack table, the good news is that innovations in fintech and beyond make this super easy to do from your own home.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
