Global fintech and funding innovation ecosystem

Open Finance SME Capital Access

NCFA Opportunity Brief - Open Finance SME Capital Access
Innovation Map → Open Banking And Open Finance → SME Finance → Opportunity
Last Updated Jun 24, 2026
FINANCIAL INNOVATION OPPORTUNITY BRIEF This page tracks evidence, risks, validation signals and venture opportunities emerging as open finance connects permissioned business data to AI assisted SME capital decisions.
Innovation OpportunityOpen Finance, SME Finance And AI Decisioning

Open Finance SME Capital Access

Open finance can move SME capital access beyond static applications and backward looking credit files. The opportunity is to use permissioned business, financial, invoice, payment, accounting and treasury data to support better working capital, credit, invoice finance and treasury decisions.

20 Evidence5 Questions4 Related Opps8 Resources

Opportunity Intelligence

Market Potential

SME lendingEarly open finance priority
Embedded capitalWorkflow distribution
HighGrowth signals
4Source count

Market sizing should not rely on one broad fintech TAM figure. The more reliable assessment is that several adjacent markets are converging: SME lending, embedded finance, invoice finance, working capital, open finance infrastructure and AI assisted credit decisioning.

View market and policy sources

Top Opportunity

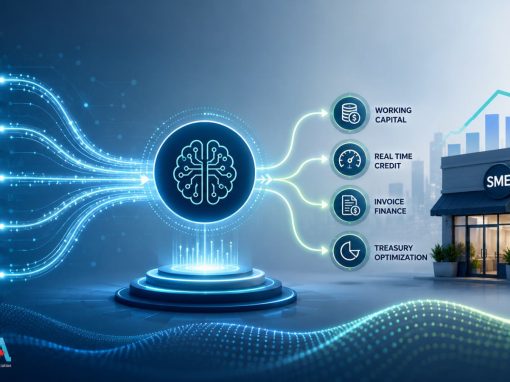
The strongest opening is not simple cash flow underwriting. It is the decision and action layer that turns permissioned SME data into capital access: embedded working capital, real time credit, invoice finance automation and treasury optimization.

Top Risks

  • Open finance standards may develop unevenly across jurisdictions, limiting cross market product repeatability.
  • Connected data may improve decisions but still fail to create buyer trust without clear governance, liability, consent and model oversight.
  • Large platforms, lenders and accounting software providers may absorb the best distribution points before specialists scale.
  • Products that only repackage mature cash flow underwriting or revenue based finance may not qualify as true innovation opportunities.

What To Watch

UK open finance experiments, CFIT SME prototypes, Canada Consumer Driven Banking implementation, Competition Bureau SME financing findings, embedded finance distribution, AI credit decision controls, invoice data standards, and early evidence that SME treasury optimization becomes a purchasable product rather than only a dashboard feature.

Product Opportunities

Lead path: Embedded Working Capital

Evidence currently supports four venture scale paths. Connected SME data, cash flow underwriting and AI decisioning are enabling layers. They should not be treated as standalone product paths unless evidence later shows a distinct purchasable product category.

1. Embedded Working Capital

Capital inside SME workflows and platforms

strongest current path
workflow distribution
commercial window open

SMEs often need capital at the point of activity: invoices, payroll, inventory, supplier payments, marketplace sales or software workflows. Embedded working capital uses platform context and permissioned financial data to offer capital where the need appears.

The innovation is not embedding a loan button. It is combining workflow data, financial data, repayment capacity and AI assisted decisioning so capital can be offered with better timing, fit and controls.

What could break the thesis

Platforms may prefer to partner with existing lenders or build lending directly, reducing room for specialist infrastructure providers.

Market WindowOpen
Buyer ClarityHigh
Competitive PressureMedium High
Evidence StrengthHigh
What to validate first

Which embedded workflows create the clearest budget: accounting, PSPs, invoicing, marketplaces, payroll, procurement or vertical software?

2. Real Time SME Credit

Dynamic credit decisions from live business data

growing evidence
AI decisioning
regulatory dependency

Real time SME credit uses fresh cash flow, account, payment, invoice, accounting and business data to support faster approvals, dynamic limits and ongoing reviews. It is different from mature cash flow underwriting when the credit product updates as business conditions change.

Potential buyers include lenders, banks, embedded finance providers, PSPs, accounting platforms and credit infrastructure providers.

What could break the thesis

If real time credit remains only a faster version of existing underwriting, the innovation window may be too narrow.

Market WindowOpening
Buyer ClarityMedium High
Competitive PressureHigh
Evidence StrengthGrowing
What to validate first

Can connected data support dynamic limits, early warnings, covenant style monitoring or instant credit decisions without creating unacceptable bias, privacy or model risk?

3. Invoice Finance Automation

Receivables finance using invoice and payment data

distinct product path
fraud controls
accounting integration

Invoice finance automation uses invoice, accounting, buyer, payment and fraud data to decide whether receivables can be financed. The opportunity is stronger when systems verify invoice validity, buyer reliability, payment timing and repayment risk without manual PDF workflows.

This path may be distinct enough to survive as a child opportunity if evidence grows around invoice intelligence, receivables verification and automated funding decisions.

What could break the thesis

Invoice finance may remain a lender workflow improvement unless automation clearly reduces fraud, friction, cost or access barriers for SMEs.

Market WindowOpening
Buyer ClarityMedium High
Competitive PressureMedium
Evidence StrengthGrowing
What to validate first

Are lenders and platforms using live invoice and accounting connections to automate financing decisions, or only digitizing existing manual workflows?

4. SME Treasury Optimization

Capital allocation and liquidity decisions

emerging path
AI assisted actions
stablecoin adjacency

SME treasury optimization goes beyond monitoring. It uses connected financial data and AI assisted decisioning to help SMEs decide when to borrow, repay debt, hold cash, pay suppliers, finance invoices, invest surplus cash or allocate liquidity across accounts and payment rails.

This is currently earlier than embedded working capital, but it may become the most differentiated open finance path if evidence shows SMEs adopting decision products rather than dashboards.

What could break the thesis

If products remain cash flow dashboards or alerts without trusted action, this should remain an enabling feature rather than a product path.

Market WindowEarly
Buyer ClarityMedium
Competitive PressureMedium
Evidence StrengthEmerging
What to validate first

Will SMEs delegate capital allocation, liquidity and financing actions to AI assisted treasury tools with human oversight?

Evidence Trail

20 verified and early evidence items. Evidence type classifies the signal, not the publisher.

Filter by signal type to review source records, market signals and thought leadership supporting this opportunity. Evidence is sorted newest to oldest.

2026-04-14
Primary
FCA Open Finance Roadmap
SME lending named as early high impact open finance use case
Policy
2026-04-14
Primary
Open Finance Smart Data Future
Roadmap through 2030 for secure financial data sharing
Policy
2026-03-27
Primary
Competition Bureau SME Financing Study
Canada studies competition in SME financing markets
Policy
2026-01-15
Primary
Competition Bureau Data Portability Report
Data portability as competition and innovation driver
Policy
2026-01-15
Analysis
Embedded Finance As SME ISV Growth Engine
SME finance delivered through software workflows
Working Capital
2025-11-06
Primary
Canada Consumer Driven Banking Framework
Framework for individuals and businesses to share financial data
Policy
2025-10-31
Analysis
MNP Submission On SME Financing
Embedded finance examples including platform based SME lending
Working Capital
2025-09-12
Article
Westpac Invoice Financing Automation Signal
Invoice finance moving away from manual PDF lending workflows
Invoice
2025-09-01
Primary
Bank Of Canada Consumer Driven Banking
Bank of Canada administers framework for approved data sharing
Policy
2025-01-01
Primary
Shopify Capital
Platform based working capital for merchants
Working Capital
2025-01-01
Primary
Square Loans Canada
Embedded financing inside merchant payment ecosystem
Working Capital
2025-01-01
Primary
Xero Invoice Financing Context
Accounting software distribution path for invoice finance
Invoice
2025-01-01
Primary
FundThrough Invoice Funding
Canadian invoice funding and receivables finance market evidence
Invoice
2024-04-18
Article
CFIT Moves Open Finance Proofs Toward Prototypes
SME access to finance selected for next stage
Credit
2024-03-04
Article
JPMorgan AI Cashflow Tool
AI assisted cash flow forecasting and treasury workflow evidence
Treasury
2024-02-29
Primary
CFIT Open Finance Blueprint
SME credit data aggregator proof of concept
Credit
2024-02-29
Analysis
Open Finance Association On CFIT Blueprint
Open finance data sets could expand SME access to credit
Credit
2024-02-29
Primary
CFIT Open Finance Programme
Broader financial data sharing to improve SME lending outcomes
Credit
2024-01-01
Primary
JPMorgan Cash Flow Intelligence
Cash flow intelligence applied to treasury and liquidity decisions
Treasury
2024-01-01
Primary
Stripe Treasury
Embedded financial accounts and treasury services for platforms
Treasury

Participate In This Opportunity

Share your perspective, research, case study or video response. You can also express interest in future discussions, collaboration opportunities and innovation activities related to this topic.

Learn how NCFA identifies, validates and tracks innovation opportunities →
Participate

About NCFA Opportunity Intelligence

NCFA Opportunity Intelligence tracks emerging venture opportunities using evidence, market developments and validation signals. Opportunity briefs are updated as new information, evidence and stakeholder perspectives become available. This content is provided for information purposes only and does not constitute legal, investment, financial, tax or professional advice.

Explore the NCFA Financial Innovation Map →


NCFA Jan 2018 resizeThe National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights

NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter


Leave a Reply

Your email address will not be published. Required fields are marked *




