





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 20, 2026 | NCFA Story Intelligence | Regulation And Policy, Capital Markets And Market Infrastructure, Competition And Market Structure
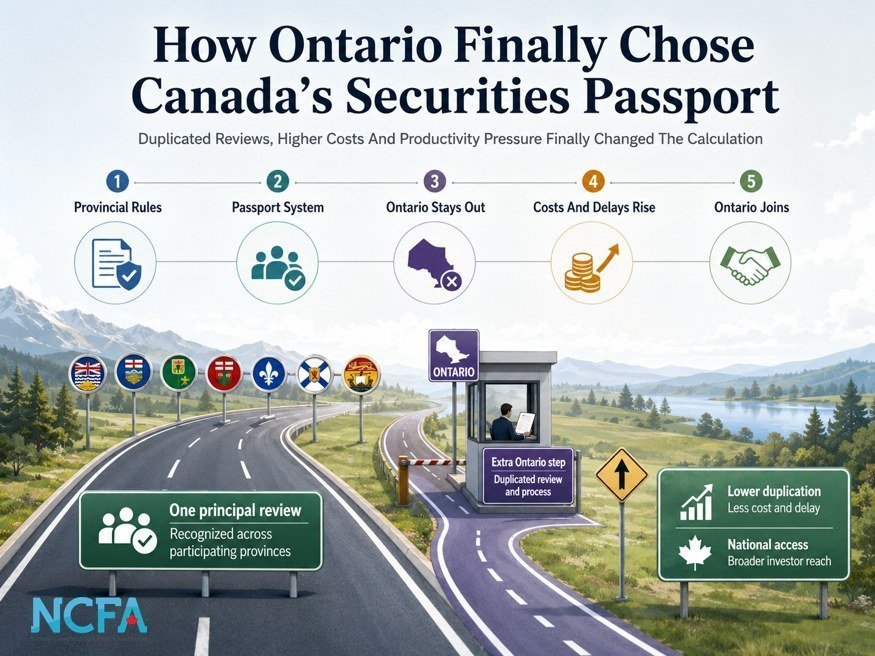
On July 15, 2026, Ontario Finance Minister Peter Bethlenfalvy announced that Ontario had committed to joining Canada’s securities regulatory passport system. The federal Finance Department highlighted the commitment following the federal, provincial and territorial finance ministers’ meeting in Charlottetown, ending almost two decades as the only jurisdiction outside the system.
Finance ministers described the decision as regulatory harmonization, removal of an interprovincial trade barrier and progress toward one Canadian economy. It also resolved a contradiction Ontario had carried for years. The province repeatedly documented duplication, delay and disproportionate compliance costs while continuing to require a separate Ontario decision where most of Canada relied on one principal regulator.
Ontario stayed outside because passport was never the prize it wanted. The province backed a single national regulator, then a cooperative authority with a wider institutional redesign. The first model failed in court. The second survived legally but never opened.
Companies carried the cost of waiting. Equity crowdfunding showed what fragmentation did at company level. A financing model designed to connect issuers and investors online became a provincial compliance exercise that excluded supporters, consumed employee time and made some smaller raises uneconomical.
The story isn’t that Ontario suddenly discovered regulatory friction in 2026. Every alternative gradually weakened while the economic cost of maintaining a separate process became harder to defend.
Canada has one capital market but several securities authorities. Each province and territory retains its legislation, regulator and enforcement powers. The Canadian Securities Administrators develops common instruments, policies and filing systems so companies don’t face entirely different frameworks in every jurisdiction.
Coordination reduces differences without eliminating repeated work. A filing, interpretation, fee or local review may appear reasonable on its own. A company raising capital or operating nationally experiences the accumulated cost through the same legal budget, employees and management time needed to build the business.
Most jurisdictions accept mutual reliance. The principal regulator can develop familiarity with the company, conduct the main review and issue a decision recognized elsewhere. The market gains a national operating mechanism without requiring provinces to surrender jurisdiction.
Ontario remains outside the compromise. An interface arrangement connects it to passport jurisdictions, but companies can still require a separate Ontario decision to access Canada’s largest capital market. The additional step remains while Ontario pursues a more ambitious institution.
The federal proposal reaches far beyond passport. The Canadian Securities Act would place registration, prospectuses, disclosure, derivatives, civil remedies and market offences within one federal regime. Ontario supports a structure that could replace the provincial coordination model rather than simply improve it.
The constitutional loss leaves Ontario without its preferred destination. In 2011, the Supreme Court rejected the proposed Act because Parliament couldn’t assume ordinary provincial securities regulation through its general trade and commerce power. Ontario loses the national model but still doesn’t join passport.
The cooperative model fixes the constitutional problem. Participating provinces would enact uniform laws administered by a common authority, while complementary federal legislation would address systemic risk and national criminal matters. Each legislature remains free to join, amend or leave.
Legal approval cannot assemble the institution. The Supreme Court approved the design in 2018, but major provinces remain outside and implementation dates recede. The first model fails because it takes too much provincial authority. The second preserves authority so carefully that no common regulator opens.
Several provincial rule books confront one digital market. Jurisdictions adopt different offering limits, investor caps, portal obligations, disclosures and filings. NCFA’s archive includes NCFA Canada Response to the Proposed Multilateral Instrument 45-108 Crowdfunding and Start-Up Prospectus Exemption.
The losses appear outside ordinary regulatory statistics. No portal initially registers under MI 45-108. More than 100 startups reportedly lose economical access to Ontario supporters, while one small firm assigns two employees for months to historical compliance work. The underlying record is available in March 1, 2019: NCFA Submission to the Ontario Securities Commission on Regulatory Burden. NI 45-110 harmonizes the market in 2021, but it cannot recover the financing, participation and productive work already lost.
The OSC confirms a pattern rather than a few difficult files. It receives 199 suggestions and identifies 34 underlying concerns, including repeated filings, difficult regulatory navigation, unclear service expectations, outdated technology and requirements that fall more heavily on smaller firms.
The response reveals the jurisdictional limit. The OSC announces 107 initiatives to improve service and remove avoidable work. Related NCFA coverage: OSC Makes Doing Business Easier for Ontario Market Participants. Ontario can improve its own processes, but it cannot eliminate national duplication while continuing to require a separate Ontario decision.
The Taskforce reaches beyond procedural burden. Its recommendations cover governance, competition, capital formation, disclosure, innovation, enforcement and investor protection. NCFA’s formal response is NCFA Response to the Modernizing Ontario’s Capital Markets Consultation Taskforce.
Ontario divides authority inside the OSC while preserving duplication outside it. Capital formation and competition enter the mandate, the Chair and CEO roles are separated and adjudication is placed within a distinct tribunal. The proposed Capital Markets Act does not replace the existing statutes, and no public tracker supports a claim that the complete 74 recommendation program was implemented.
The cooperative transition project winds down without transferring authority. Existing commissions remain responsible, the CSA continues coordinating national policy and passport keeps serving the jurisdictions that joined it. The practical system survives while the ambitious replacement recedes.
Ontario’s holdout loses its destination. The province is no longer choosing between passport and an approaching national regulator. It is choosing between passport and continued duplication with no replacement institution in sight. The original reason for waiting has disappeared, but companies still face the additional process.
The Bank of Canada turns weak productivity into an emergency. In March 2024, Senior Deputy Governor Carolyn Rogers says it is time to break the glass. Weak investment, limited competition and lengthy or unpredictable approvals discourage companies from committing capital.
Ontario’s separate review becomes part of the economic diagnosis. Every repeated filing, legal opinion and approval cycle uses the same employees, financing and management attention needed for technology, customers and expansion. Related NCFA coverage: How Competition Powers Canada’s Economic Growth. Passport doesn’t remove scrutiny. It prevents several regulators from consuming company resources to deliver substantially the same protection.
The cost of duplication is no longer only regulatory. It is productive work that doesn’t happen.
Ontario gives up duplication rather than jurisdiction. One principal regulator can conduct the main review while Ontario retains its legislation, commission, enforcement capability and voice in national policy. The province no longer has to choose between complete institutional control and surrendering its capital market.
The political commitment now faces an operating test. Industry advocates said passport can create a “single regulator experience through a principal regulator,” but harmonization in policy must also deliver harmonization in practice across legislation, policy and regulatory operations. Investment Executive reports the implementation direction and industry response. The strongest evidence of success will be fewer repeated reviews, lower compliance costs and faster interprovincial access while maintaining investor protection.
Ontario’s decision closes a long loop in Canadian capital markets policy.
The province rejected passport because it wanted a more ambitious national regulator. The first version failed constitutionally. The cooperative version survived in court but never became operational. Ontario then documented extensive burden inside its own market, implemented selected modernization reforms and continued requiring a separate provincial process after the national alternative receded.
Equity crowdfunding showed what the delay meant for companies. The market was divided before it could mature nationally. Legal work, platform controls and continuing obligations consumed a large share of modest financings. Investors were excluded by geography. Employees were assigned to compliance work instead of customers and growth.
The productivity emergency raised the stakes. Canada cannot describe weak investment, limited competition and poor productivity as urgent while treating avoidable duplication as institutionally harmless. The same capital and employee time cannot be used twice.
Passport is not a single national regulator, and it does not eliminate provincial authority. Its value is practical. One qualified regulator does the principal work while the others rely on the result.
Ontario didn’t suddenly discover regulatory friction in 2026. It gradually accepted that preserving every layer of control carried an economic cost that internal reform and an unfinished national project had not removed.
Ontario should publish an implementation schedule, identify the decisions covered by passport and report whether review periods, professional costs and duplicate regulatory interactions decline. Results for smaller firms should be reported separately because they carry fixed compliance costs most heavily.
Investor protection remains central. Reliance should remove repetition, not scrutiny. Principal regulators need the information, expertise and authority required to make decisions every participating jurisdiction can trust.
The larger question extends beyond securities regulation. Canada often pursues national economic outcomes through provincial institutions. Governments may continue debating the ideal architecture, but companies shouldn’t be required to finance avoidable friction while they wait.
When governments measure regulatory burden, should they count only compliance expenses that appear on company records, or also the financings, investment and productive work that never occur because the combined process makes them uneconomical?
Share this story → Explore related intelligence → Subscribe
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply