






Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Aug 29, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Competition And Market Structure, Regulation And Policy, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Cross Border Payments And FX, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Payments Infrastructure And Money Movement

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026).
This is a material step beyond the group's 2025 exploration phase. TD and Scotiabank are now participating in a global bank-led issuance venture while Canada's own stablecoin framework is still moving through implementation. The Canadian question is whether major banks build meaningful CAD-denominated digital-money capacity alongside domestic initiatives or gain scale first through shared global USD infrastructure.
Coinbase supplies the regulated trading and custody stack while Webull keeps the investor interface and brokerage relationship. That reduces the infrastructure brokers need to build themselves and gives specialist providers another route into Canadian retail distribution. It also intensifies Canadian crypto competition over who owns the customer and who supplies the regulated back end.
LSEG is extending tokenization from private markets and settlement infrastructure toward public equities. The harder test is whether tokenized shares can preserve legal ownership rights, corporate actions, price integrity and regulated settlement while gaining wallet portability and longer trading access. If that model works, public-market infrastructure begins competing directly with blockchain-native distribution without abandoning the protections of an exchange-listed security.
Coinbase is bringing regulated crypto derivatives distribution into Canada without routing the products through Coinbase Canada itself. The important boundary is eligibility as it expands access for sophisticated investors while keeping the offering outside ordinary retail availability. It also gives regulated venues a stronger alternative to offshore derivatives platforms for Canadian capital, hedging and price discovery.
The important development is bank ownership of shared tokenized deposit infrastructure, not the financing round. Cari is moving toward production with banks helping govern, fund and use the network while retaining the customer relationship. Alongside other shared bank blockchain infrastructure, the test is whether common digital money networks can achieve enough participation and interoperability to compete with institution specific systems.
Forty-three state licences give OpenPayd something infrastructure providers can't create through software alone: regulated geographic reach. The company can now connect its payment stack to a much larger U.S. operating footprint while combining fiat and digital asset permissions across the United States, United Kingdom and Europe. The test is how quickly that regulatory coverage converts into client activity and payment volume.
Final approvals put the transactions into execution. National Bank is positioned to absorb Laurentian's retail and SME relationships while Fairstone combines its commercial lending operations with Laurentian's commercial specialization. Customer migration, product continuity and retention now determine how much of the approved transaction value survives the transfer.
Singapore is converting stablecoin policy into the legal requirements issuers will operate under. The consultation advances the status tracked in NCFA's stablecoin regulatory intelligence from a finalized framework awaiting legislation toward implementation. Reserve, redemption, capital and cross-border requirements can now be tested against issuer economics before the rules are finalized.
The case makes privileged information a concrete event contract surveillance problem. Exchanges and brokers need controls that can connect unusual positions with access to confidential information, investigate suspicious activity and enforce trading restrictions. NCFA's regulated event contract infrastructure brief tracks this market integrity gap as distribution expands.
Section 311 can reach beyond a targeted foreign bank because U.S. institutions must also identify transactions routed indirectly through other correspondent relationships. Banks and payment firms therefore need enough counterparty visibility to detect the institution behind a payment chain, not only the correspondent presenting the transaction.
The investigation puts transaction monitoring and global compliance governance under direct supervisory scrutiny at a major cross-border payment provider. The operating test is whether controls identify known laundering typologies across high-risk channels and whether global decisions support local obligations. The eventual findings could provide useful evidence for how regulators assess AML controls across international payment networks.
Australia's AML expansion has reached the point where AUSTRAC is testing whether newly covered firms have entered the regulatory system at all. Service classification, enrollment and working AML controls can no longer remain implementation projects. Regtech providers also gain a much larger addressable compliance market, but buyers will need products matched to obligations regulators are actively checking.
Conditional approval advances Revolut from U.S. fintech distribution toward direct regulated banking capacity. Its U.S. business still relies on a partner bank, while NCFA's Revolut company intelligence had tracked the national bank application as pending. A completed charter would give Revolut more control over deposits, credit and payment connectivity, but the remaining federal approvals and preopening requirements still determine whether that capacity reaches customers in 2027.
OpenReserve is trying to combine conventional banking, tokenized deposits, digital asset custody and stablecoin infrastructure inside one national bank structure. Preliminary approval brings that model closer to regulated operating capacity, but the remaining test is execution: capital, controls, final authorization and separate approval for the planned stablecoin subsidiary still stand between the proposed structure and live customer activity.
TabaPay is trying to internalize regulated banking capacity rather than relying exclusively on sponsor bank relationships. Owning an OCC chartered bank could give the payments fintech more control over settlement, sponsorship, redundancy and difficult client use cases while retaining outside bank partners. The acquisition still requires regulatory approval, making the next test whether supervisors accept that vertical integration and its governance model.
A successful Swedish licence would turn Allica's international expansion from a funding plan into regulated market access. The bank now has to prove that its UK SME model can satisfy a new supervisor and compete in a concentrated, highly digital banking market. Approval would also give Allica a potential base for wider European expansion rather than requiring each new market to begin from the UK.
The US$3 billion target gives scale to the real time receivable funding model introduced in the United States this week. VersaBank is betting that faster access to bank balance sheet funding can take business from conventional securitization and warehouse structures. Fiscal 2027 will test whether partner demand converts into several billion dollars of new assets without weakening credit quality or funding economics.
The licence adds another authorized BNPL provider while reinforcing regulatory permission as a condition of market access in Saudi consumer finance. New entrants have to compete inside that perimeter, putting more weight on underwriting, merchant distribution, pricing and compliance execution once authorization is secured.
QR Ph is extending domestic interoperability into cross-border acceptance without requiring merchants to install another payment system. That reduces one of the practical barriers to international wallet acceptance, especially for smaller merchants. The competitive question is whether national QR networks increasingly become gateways through which global payment aggregators reach local commerce.
Agorá has crossed the real-money test identified in earlier Project Agorá testing. The harder questions now concern legal finality across jurisdictions, liquidity, interoperability and whether a shared multicurrency platform can reduce correspondent-payment friction at institutional scale without weakening central-bank control or commercial-bank money.
Banks are pushing deeper into stablecoins, tokenized deposits and direct control of payment infrastructure, while fintechs are trying to own more of the regulated stack themselves. The fight is increasingly over who controls the account, the customer relationship and the transaction flow.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Sep 3, 2026
Some buy now, pay later activity reaches Canadian credit files. Most routine instalment plans currently do not.
That is the short answer, and the qualifications matter more than the answer does. Whether a buy now, pay later arrangement appears on a credit file in Canada depends on the provider, on which credit bureau is involved, on whether a payment was missed, and on the month in which the question is asked. Payments made on time and payments missed follow different routes. Two people financing identical purchases through different providers may find entirely different records.
What follows sets out what is reported, by whom, to which bureau, and with what effect on a score, then explains why the answer is this unsatisfying. The position described reflects Canadian reporting as of September 2026, and it is moving.
The Financial Consumer Agency of Canada describes buy now, pay later plans as arrangements that finance a purchase with credit. Its research characterises the category as covering a wide range of credit arrangements and as generally a type of consumer credit, comparable to instalment lending. That framing is the reason the credit-file question arises at all. The obligation is credit, not merely a payment method.
The agency identifies several distinct payment models sold under the same label: pre-authorized debits, pre-authorized credit card charges, an instalment option applied to an existing credit card, retail credit cards, and financing arranged through a financial institution. The entity behind each model differs. FCAC lists the financial service providers active in this market as including banks, credit unions and caisses populaires, financing companies, and money services businesses such as financial technology firms.
That mix determines oversight. FCAC directs consumers with complaints to different regulators depending on who provided the financing: federally regulated financial institutions must maintain their own complaint-handling processes, while other arrangements fall to provincial and territorial regulators. Oversight therefore follows the provider rather than the product category.
Credit reporting is furnisher-driven. A bureau can hold only what a provider chooses to send it, and furnishing is voluntary. In the United States, four senators on the Senate Banking Committee wrote to the major credit reporting companies in May 2026, reporting that several American providers had told them they were not sharing this data with credit bureaus.
The Canadian position is documented more thinly. The Canadian Lenders Association, an industry body, described the position in late 2025 as one in which inclusion of this data in credit files is voluntary, variably reported, and inconsistently used in underwriting. The same commentary reported that Equifax in Canada had begun incorporating this data, with TransUnion not far behind. Beginning is the accurate word, and it should not be read as complete.
Missed payments follow a different route from payments made on time. An account referred to a collection agency can reach a credit file through that channel even where the on-time payment record never appeared. FCAC states that once a creditor sends a debt to a collection agency, the credit score will go down. An arrangement invisible while it was being paid can become visible once it is not.
Because the position varies by provider and bureau, the only reliable confirmation is an individual file. You can check your credit score and see what each bureau holds in your name.
Three independent variables produce the inconsistency, and naming them is more durable than listing providers whose practices change.
The first is whether the provider furnishes at all. This is voluntary, and it varies both between providers and by product.
The second is what the receiving bureau does with it. In a 2022 post it has since archived, the United States Consumer Financial Protection Bureau noted diverging approaches: one credit reporting company implemented a business industry code while letting furnishers supply data in their preferred format, and others planned to hold it in specialty files kept apart from the core files behind traditional reports. That account is American and several years old. Canadian bureau practice is not documented publicly in comparable detail. That gap is part of the answer.
The third is whether the scoring model uses the data. TransUnion Canada stated in a 2024 paper that it was analysing alternative data, including buy now, pay later, without initially affecting its scores. Data can sit on a file while remaining absent from the decision. Presence on a record and effect on a score are separate things, a distinction that governs which financial activity does and does not build a credit file.
The foundational federal research on buy now, pay later in Canada is a pilot study, and the agency says so itself.
FCAC surveyed 1,034 Canadians aged 18 and over. The sub-sample of actual users was 66 people, of whom 20 took part in follow-up interviews. The agency states that most findings are drawn from that sub-sample, that these early findings should not be generalised to Canadians at large, and that unweighted percentages are used throughout. Those are appropriate disclosures on a pilot. The difficulty lies with how often it is cited as settled evidence.
Two details matter. The survey reference period ran from September 2019 to March 2021; the report was published in November 2021. And 44 percent of the users surveyed found the potential effect on their credit score difficult to understand: the confusion this article addresses was documented at the outset. Interview participants described using these plans to bridge a timing gap, wanting to purchase immediately while knowing funds would arrive later.
FCAC identified risks of over-borrowing and over-indebtedness but stopped short of recommending regulation, committing instead to monitor the market, conduct follow-up research, coordinate with provincial and territorial authorities, and provide consumer education. As of September 2026, the agency's published research index lists no further study.
Where these obligations are not furnished, or are furnished into files that scoring models do not read, they are absent from any assessment built on bureau data. A household carrying several concurrent instalment plans can present on a credit file as a household carrying none.
The omission runs in both directions. A consumer reviewing their own file may conclude they carry less than they do. And every party that assesses affordability from bureau data, from banks and credit unions to licensed Canadian lenders, works from a record that omits a category of live obligation. TransUnion Canada listed this as a market concern in 2024, noting that limited reporting constrains the ability of other lenders to conduct credit checks and assess affordability.
This is neither new nor specific to one product. Rent, utilities and telecommunications payments are largely unreported in Canada as well. Buy now, pay later is a recent addition to a longer list of obligations that credit files do not capture. The observation concerns what the record contains, not what any party ought to do about it.
On 23 June 2025, FICO announced two scoring models, FICO Score 10 BNPL and FICO Score 10 T BNPL, built to incorporate buy now, pay later data. The announcement was framed explicitly around the United States credit ecosystem, and FICO stated the models would initially be offered alongside its existing scores rather than replacing them, leaving adoption to individual lenders. No equivalent Canadian scoring model has been announced.
The Canadian Lenders Association, an industry body representing lenders, has argued that the sector needs a consistent framework so that this data supports credit inclusion rather than working against it. The position is reasonable and worth reporting. It is not a neutral one.
The effect of fuller reporting would run in two directions. For a consumer with a thin file, a furnished record of payments made on time would constitute history where none existed. For a consumer carrying several concurrent plans, the same reporting would make visible an obligation load that had gone unobserved. Which effect applies is a matter of individual circumstance.
The question a reader arrives with is whether buy now, pay later touches their credit file. The accurate answer is that it depends on the provider, on the bureau, on whether a payment was missed, and on the month in which the question is asked.
That is unsatisfying, and it is not a hedge. Furnishing is voluntary and partial. Bureau treatment differs and is not documented publicly in Canada at the level of detail the question deserves. Scoring treatment is a separate matter again. The Canadian federal evidence base remains a pilot study of 66 users describing behaviour from a period that ended in March 2021.
Each of those conditions can change without announcement. This article describes the position as of September 2026. A reader returning to the question in a year should expect a different answer.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 22, 2026 | NCFA Fintech Whisperer | Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Payments Infrastructure And Money Movement, Cybersecurity Fraud And Financial Crime, Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Treasury Liquidity And Cash Management, Sustainable Finance ESG And Financial Inclusion, Digital Banking And BaaS, Wealthtech Investing And Trading, Regulation And Policy, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026).
BankChain Alliance adds an association led ownership model to existing bank tokenized deposit networks. Its published plan gives community and regional banks a proposed role in governing shared infrastructure, although the technology provider and participating bank commitments remain unresolved.
RQD combines the financing announcement with disclosed operating volume from its proprietary clearing platform. The expansion plan covers digital-asset custody and tokenization alongside equities and options infrastructure. NCFA’s Alpaca platform analysis examines another provider combining brokerage distribution with regulated clearing and custody.
The pilot tested the digital asset and payment legs within the same institutional transaction. NCFA’s tokenized market infrastructure analysis explains why tokenized securities require a compatible settlement asset. CIMB identifies coupon distribution, secondary transfers and redemption as potential future applications. Commercial production availability has not been announced.
The completed transaction extends Canton's institutional custody and collateral infrastructure into a full repo cycle. Repeat volume, additional counterparties and accepted legal, accounting and capital treatment will determine whether the structure advances beyond a single transaction.
The H1 numbers extend the concentration documented in KPMG's 2025 fintech investment review. Canadian founders now face a market where capital favours scale, regulated access, specialized technology and measurable economics. Infrastructure reform could improve the position of companies that can convert lower data and payment friction into customer adoption.
This is a material follow-on to the June financing behind EDGE's prediction market banking infrastructure. ProphetX provides named distribution and active account funding use for EDGE Connect. Higher limits, dedicated insured accounts and continuous FedNow access give the rail an operating profile that routine partnership announcements lack.
Apex could give Gemini a distribution route through brokerage platforms that already serve tens of millions of investors, while Gemini supplies the regulated venue, execution and clearing. That directly expands the commercial case for event contract distribution infrastructure around brokerage connectivity, compliance and access. The parties still need a definitive agreement, so the LOI establishes the proposed structure rather than a completed rollout.
The March dialogue announcement established the bilateral payments file. The completed August meeting adds an agreement to explore UPI distribution and cross-border payment partnerships, while commercial implementation remains unresolved.
This is a material follow-on to Visa and Nium's earlier stablecoin settlement work. BLOOM adds central bank led governance, multicurrency scope and an explicit interoperability mandate. Together with Nium's recent U.S. card issuance expansion, the pilot gives Nium a larger role across both payment distribution and institutional settlement.
Fasset is putting new capital into the banking, liquidity and settlement connections behind its existing transaction volume. Stablecoins already support settlement across parts of Own Network, placing the company inside the infrastructure opportunity around programmable stablecoin payments rather than relying on token issuance alone. Its 100-plus banking corridors give Fasset a base for competing on routing cost, settlement reach and access across markets where payment infrastructure remains fragmented.
RBC is consolidating ownership of the corporate cash cycle, from payment execution and foreign exchange to liquidity and trade finance. Multinational clients gain a coordinated entry point across Canada and the U.S., raising the integration benchmark for fintechs selling treasury software, cross border payments or working capital tools into the same accounts. The structure continues the transaction banking competition already pushing large banks to invest in digital business payment capabilities.
This is a defined core replacement with a named platform, systems integrator, investment budget and migration sequence. Deutsche Bank says the old and new systems will operate in parallel during the transition to support operational resilience and continuity of service. Testing remains planned for year-end, and no migrated products have yet been reported.
The design gives community banks and credit unions a way to offer AI assistance inside authenticated banking while maintaining institution-level data and transaction controls. iTHINK gives the launch a concrete customer and near-term operating timeline.
The transaction verifies that the connection can process an international card at an approved Syrian merchant. The announcement does not disclose how many merchants are enabled, which issuing markets can participate or when international card acceptance will become widely available.
Banks, payment firms and vendors must revise ISO 20022 delivery schedules without treating the delay as cancellation. Release dependencies, vendor contracts and address-data remediation still need clear ownership while the industry waits for a replacement timeline.
The launch extends USD1's institutional settlement use cases from a planned fund-services pilot to native availability on Canton. Named counterparties and recurring atomic settlement volumes are still needed to prove adoption.
PaidIt combines identity resolution, recipient communication and payment delivery for cases that often depend on manual tracing. CBA’s internal use gives the product operating evidence ahead of its planned institutional client rollout.
August 24 gives prospective RTR participants a live legal framework, while operational access still depends on membership, settlement arrangements, technical integration, fraud controls, testing and certification. The RTR rules and access requirements show why eligibility alone does not put a PSP into production. Firms that can clear the remaining technical and operating requirements will be better positioned to build instant payment, pay by bank, treasury and embedded payment products when the system launches.
Owning Altruist gives Vanguard direct infrastructure across RIA custody and advisor workflows, not only fund distribution. Advisors and competing platforms should watch closing conditions, pricing, product access and whether standalone governance preserves Altruist's independence.
Putting regulated multibank data inside an agent interface connects advisory automation to a structured financial source layer. For wealth firms evaluating governed AI agent workflows, the integration supports portfolio analysis and adviser preparation inside an environment they may already use.
Nasdaq says Q6 data will appear as high-risk alerts inside the existing Verafin investigation workflow, covering check fraud, payment-card fraud and account takeover. The proof-of-concept average demonstrates potential lead time, but it does not establish that every alert will arrive before a fraudulent transaction.
Fraud and compliance teams can now buy agentic case operations within a large identity platform rather than assembling a separate agent layer. Regulated customers still need evidence for each automated decision, clear escalation rules and accountable human owners when an agent closes or changes a case.
The task force turns quantum readiness for fintech into a coordinated financial-sector program. Institutions and vendors should inventory cryptography, rank critical systems and document external dependencies before sector guidance becomes a delivery deadline.
This puts post-quantum preparation into an institutional transaction environment where banks and regulators can test the same cryptographic architecture before migration becomes an operating requirement. That is the implementation work behind financial sector quantum readiness: testing wallet controls, signing standards, governance and cross-border interoperability while existing cryptography still works. A shared reference architecture could also reduce the cost and uncertainty of each institution designing its own migration approach.
India is making technology resilience more measurable while standardizing how cyber incidents enter regulatory reporting. Exchanges, clearing corporations and depositories now face a more structured test of whether critical systems remain reliable and recoverable, while common incident data should make weaknesses easier to compare across institutions and over time.
The task force turns federal quantum policy into a financial sector implementation program. Firms now have a coordinated forum focused on cryptographic inventories, vendor dependencies, digital assets and migration execution. It extends the operating case in quantum readiness analysis: the immediate challenge is finding vulnerable cryptography and planning replacements before migration becomes an operational deadline.
The cohort gives regulators a supervised setting to examine how autonomous financial systems are authorized, monitored and escalated. The useful proof will come from controls that preserve human accountability when an agent completes a task or supervises another agent.
Rowan takes delegated AI access to financial accounts from recommendations into execution. Permission limits, action logs, reversibility and responsibility for losses become core product controls when a conversation can trigger a financial action.
Google is packaging domain methods, licensed data access, workflow execution and governance as one financial AI stack. Banks evaluating the preview will need to examine the quality of its research outputs, permission controls, audit records and integration with existing systems. The same control requirement is already visible in AI agent spending infrastructure, where authorization and observability determine whether automated execution can enter production.
Starling has moved agentic AI inside the authenticated business banking workflow and given it authority to execute a defined financial action, rather than limiting it to analysis or customer support. That brings the consent and liability questions around AI initiated payments into a live bank product: who authorizes the action, what limits apply, how the instruction is recorded and what happens when an automated decision is wrong. For business banking, the commercial opportunity is also concrete. The bank can automate tax, invoicing, fraud checks and cash management inside the account instead of leaving those workflows to separate software providers.
The national improvement does not describe every borrower or every region. Ontario homeowners are carrying persistent mortgage stress while severe non-mortgage delinquency has eased slightly across Canada, giving lenders a more uneven credit picture than the headline rate suggests. That divergence affects underwriting, limit management and collections across consumer lending, including products now becoming more visible in Canadian credit files. Geographic exposure and housing obligations are becoming more important when lenders assess where household credit risk is actually accumulating.
For banks, insurers and investors, the liability perimeter has narrowed. Statutory emissions duties remain, while private climate claims can no longer use this route through tort law. Underwriting, due diligence and climate-risk analysis should reflect the distinction.
Frontier AI preparedness is moving from awareness into evidence of execution. Financial firms need tested escalation authority, recovery plans, dependency mapping and governance that still works when incident timelines compress. The supervisory question is increasingly whether organizations can prove those controls operate under pressure, not whether boards have discussed AI risk.
The mandate changes how payment innovation enters supervisory decision making at the central bank. Stablecoin and payment infrastructure proposals will still have to satisfy financial stability requirements, but innovation becomes an explicit secondary consideration rather than an external policy goal. The practical test is how that mandate affects approvals, infrastructure design and competition as new payment models reach systemic scale.
The notice separates sports and entertainment products from the limited event contracts already available through Canadian investment dealers. NCFA’s event contract infrastructure brief tracks the dealer controls, surveillance, settlement and product-classification requirements connected to permitted contracts.
The final rule directs supervisory attention toward material financial risk and compliance with banking law. It also requires the agencies to tailor unsafe-or-unsound findings and MRA treatment to institution-specific risk factors. The rule does not apply to institutions outside OCC or FDIC supervision.
Payment firms and stablecoin providers will gain a formal innovation consideration within Bank of England supervision, but no automatic approval or lighter standard. Product teams will still need to prove that new payment models protect stability, resilience and users.
The proposed consent judgment gives algorithm design liability a concrete control framework built around age assurance, usage restrictions and parental permissions. Fintech teams offering youth accounts, gamified investing or automated recommendations can compare their controls with these requirements while the court reviews the agreement.
Thailand is working on both sides of institutional crypto access at once: the investment product investors can buy and the custody arrangements funds can use behind it. That puts product approval, offshore asset safeguarding and institutional distribution inside the same regulatory design problem rather than treating crypto ETFs as a listing question alone.
Control of the rails, data, distribution and risk is becoming more valuable. Capital is concentrating around firms that can prove scale and economics, while banks and infrastructure providers invest directly in tokenized settlement, real-time funding, AI and fraud controls. The opportunity remains large, but owning a critical part of how money moves is becoming more valuable than adding another product.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 25, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Competition And Market Structure, Open Banking Open Finance And Data Sharing
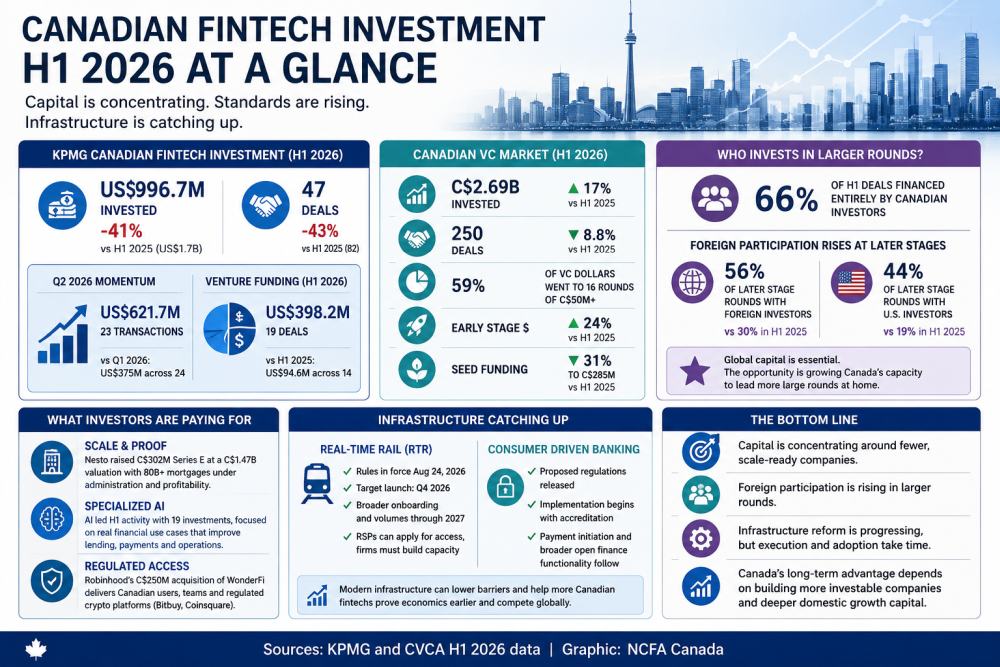
On August 25, 2026, KPMG reported KPMG H1 fintech data showing US$996.7 million across 47 Canadian fintech deals in the first half of 2026. Its current comparison puts that against about US$1.7 billion across 82 deals a year earlier, leaving both investment and deal activity down more than 40%.
Q2 was much stronger than Q1 without producing more deals. Investment climbed to US$621.7 million across 23 transactions from US$375 million across 24. Venture funding reached US$398.2 million across 19 deals from US$94.6 million across 14. Almost the same number of transactions attracted substantially more capital.
Canada's broader venture capital market tells a different story. Canada H1 venture data show C$2.69 billion invested across 250 deals, with dollars up 17% and deal count down 8.8%. Sixteen rounds of C$50 million or more absorbed 59% of all venture capital.
Look at the funding source of those larger cheques. Rounds financed entirely by Canadian investors represented 66% of H1 venture transactions, but foreign investors participated in 56% of later stage rounds, up from 30% a year earlier. U.S. investors participated in 44%, up from 19%.
Global capital is valuable to Canadian companies and should remain part of the funding mix. However, the opportunity is to build more domestic capacity to lead large rounds as companies scale, allowing Canada to retain more ownership, investment influence and financial upside while still attracting international investors.
KPMG and CVCA measure different markets. KPMG includes venture capital, private equity and M&A, while the CVCA figures above cover venture capital. Together, they show a funding market where larger commitments are going to a relatively small group of companies.
KPMG says investors are favouring scale, specialized AI capabilities, competitive positioning and demonstrable economics. For Canadian fintechs, the funding bar is getting clearer and harder to clear.
The largest Canadian fintech financing in KPMG's H1 data was Nesto's C$302M Series E in June at a C$1.47 billion valuation. The Montréal mortgage technology company entered the round with more than C$80 billion of mortgages under administration, more than C$37 billion of 2026 originations and a profitable business.
Nesto also owns lending technology and established mortgage businesses while building Nesto Cloud and Maestro AI for financial institutions. Investors were backing technology connected to customers, lending operations, distribution and a large existing financial market.
Regulated access can carry similar strategic value. Robinhood's WonderFi acquisition gave it Canadian customers, local teams and regulated crypto platforms through Bitbuy and Coinsquare instead of building that position from scratch.
AI attracted the most activity in KPMG's H1 data with 19 investments, compared with eight digital asset deals and four payments deals. KPMG says investors are favouring specialized applications that make lending, deposit taking and payment processing faster or more efficient.
That is already visible in Canadian financing. Float raised C$85 million to expand its AI business finance platform across payments, cash management and finance workflows. Nesto is applying AI to mortgage operations and lending technology. AI becomes easier to finance when it can lower costs, improve risk decisions, speed up work or increase revenue inside a financial product customers already use.
The early stage pipeline below those larger companies needs attention. CVCA says early stage investment dollars rose 24% on a flat deal count, while seed funding fell 31% to C$285 million. KPMG recorded 12 early stage fintech deals and eight seed rounds. Future Canadian scale companies depend on enough younger fintechs getting the capital and customers required to reach that level.
KPMG expects Consumer Driven Banking and the Real-Time Rail to improve fintech economics by opening access to financial data and payment infrastructure. Both are finally entering implementation after years of delay.
Canada's RTR access rules came into force on August 24. Payments Canada is targeting a Q4 2026 launch with initial direct participants, followed by additional onboarding and transaction growth through 2027. Registered payment service providers can pursue membership and RTR access, but firms still need the technology, settlement arrangements, fraud controls and operating capacity to participate.
Consumer Driven Banking is also getting closer to operation. Proposed regulations cover data access, accreditation, liability, security and technical standards. Implementation is expected to begin with accreditation after final regulations are published, while payment initiation and wider open finance capabilities come later.
These infrastructure reforms can reduce barriers that have favoured larger institutions, but firms still need the resources to integrate, comply and compete. Smaller challengers benefit when access becomes practical and affordable enough to improve their products and economics.
Canada's delay also affects how much experience fintechs build before competing internationally. In 2025, the Bank of Canada described payments modernization delays compared with the UK, Australia and EU. Fintechs in those markets have had more years to develop products around faster payments, financial data access and modern infrastructure.
Canadian firms are only now gaining some of the same tools. Infrastructure delays do not explain the success or failure of any individual company, but they can leave Canadian fintechs with less experience using capabilities that competitors elsewhere already know well. That can make winning customers and market share outside Canada harder.
Scale, licences, customer access and specialized technology are easier to finance once companies have had time to build them. If modern infrastructure helps Canadian fintechs prove their economics earlier, more firms could become credible candidates for larger rounds.
Canada's fintech funding concentration was already visible in 2025. H1 2026 makes the domestic question more pressing. Strong companies are still attracting large cheques, but fewer fintechs are reaching investors.
More selective investment can reward stronger companies, but Canada still needs enough firms coming behind today's winners. Better payment and data infrastructure can lower operating barriers. Applied AI can improve real financial workflows. Deeper domestic growth capital can help Canadian investors lead more large rounds.
The goal is not to make investors less selective. It is to produce more Canadian fintechs strong enough to earn their capital and compete globally.
Canadian fintech investors are backing scale, specialized AI, regulated access and proven economics, while international capital becomes more important in larger rounds. Can Real-Time Rail and Consumer Driven Banking help more Canadian fintechs build those advantages earlier while Canada develops more capacity to finance their growth at home?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 15, 2026 | NCFA Fintech Whisperer | Cybersecurity Fraud And Financial Crime, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Digital Assets Blockchain And Tokenization, Cross Border Payments And FX, Regulation And Policy, Insurance And Insurtech, Treasury Liquidity And Cash Management, Artificial Intelligence And Data, SME Finance And Business Banking, Risk Compliance And Regtech
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026).
The numbers show digital assets becoming part of bank formation rather than remaining mainly an activity added to established institutions. More than half of the OCC's recent charter applications include digital asset activity, extending the same infrastructure-ownership question behind Ripple's U.S. bank charter application across a much larger applicant pool. These are applications, not approved banks, but the pipeline shows how many digital asset firms are trying to bring licensing, custody, payments and stablecoin activity inside regulated banking structures.
Singapore is combining tax policy, institutional capital and immigration settings to compete for asset managers and investment talent. The package goes beyond licensing or regulatory simplification by addressing where firms locate teams, where experienced professionals work and whether managers can build enough local scale to anchor investment activity in Singapore. That makes asset-management competitiveness an industrial-policy question as well as a financial-services one.
The report provides unusually concrete evidence on both sides of Canada's securities-policy agenda. Regulators are lowering friction in parts of the capital-raising system while expanding technology-enabled fraud disruption and examining new digital market structures. The C$4 billion raised under the expanded exemption strengthens the question of who gets capital as funding channels multiply because it gives regulators measurable evidence that changing financing limits can alter how Canadian public companies access capital.
As NCFA's review of the RPAA notices explains, a zero-dollar penalty still creates a durable public compliance record. Registration checks now belong in partner onboarding, procurement, investor diligence and market-access planning for payment firms serving Canada.
The SEC is moving from defining how securities law applies to crypto toward creating specific capital-raising pathways for the sector. Its March crypto market structure interpretation established a classification and lifecycle framework; Regulation Crypto Assets would add tailored exemptions that qualifying issuers could use to raise capital within it. If adopted, the rules could materially change how early stage crypto ventures fund development, what they must disclose and how token-based fundraising competes with established private-market exemptions.
The proposal turns the GENIUS Act from legislation into an operating framework for stablecoin issuers and the platforms that distribute their tokens. The definitions of where issuance occurs, which issuers need a licence and when a stablecoin is being offered into the U.S. market will determine how domestic and foreign providers structure access. For exchanges, wallets and payment platforms, compliance will increasingly depend on the regulatory status of the stablecoins they make available, not only on their own licences.
Helcim is using a 22,000 merchant distribution base to extend beyond payment acceptance into more of the financial workflow around small businesses. Vendor payments and business finance could increase revenue per merchant while putting Helcim into closer competition with processors, banks and software platforms that already bundle payments with operating tools. Nearly C$10 billion in expected annual volume gives that expansion enough scale to watch.
Direct participation removes an intermediary from Modulr’s CHAPS settlement process and gives it more control over payment routing and liquidity. The development offers a useful comparison with Canada’s expanding non-bank rail access, where membership and system participation determine how much infrastructure control payment providers can obtain.
The integration gives AlphaPay more Canadian merchant distribution while connecting domestic payment acceptance with Payment Asia's international payment capabilities. The strategic value will depend on whether the combined business can convert that larger merchant footprint into meaningful transaction volume and cross-border activity. The regulatory point also requires precision: Canadian MSBs are registered with FINTRAC, so the company's use of the term "MSB licence" should not be read as a separate banking or payment licence.
Domestic U.S. issuance gives Nium another local component inside a payment network already built for international use. Businesses operating across regions can reduce the number of separate issuing integrations they maintain while combining card programmes with cross-border payouts. That matters most in sectors such as travel and supplier payments, where one transaction can require several payment methods across multiple countries.
New Zealand is still considering the architecture and governance of infrastructure that Canada has placed into approved rules through its Real-Time Rail framework. Payment providers have an early opportunity to address access, fraud responsibilities, interoperability and the role of nonbanks before New Zealand selects its modernization approach.
Offline capability makes hardware compatibility, mobile operator participation and secure deployment part of payment infrastructure design. The consultation gives payment providers and technology companies a direct route into the standards discussion before the pilot begins.
Stripe is reducing the separation between payment acceptance and treasury operations for businesses already using its platform. Revenue can become available for supplier and contractor payments without first being transferred through a separate external banking workflow, while currency conversion stays inside the same system. Treasury for Platforms would extend that model further by letting software platforms distribute account functionality directly to their customers.
Giving an AI agent access to capital requires controls over identity, authority, spending limits, compliance and settlement before the transaction happens. Anchorage is putting those controls inside regulated banking infrastructure, extending the issues already emerging around AI payment consent and liability into institutional treasury and digital asset workflows. Banks, payment firms and fintech platforms now have a clearer benchmark for what controlled agent access to money can look like.
Agent OS puts AI applications closer to financial actions rather than limiting them to analysis or recommendations. The important control boundary is between what an external agent decides and what Binance permits it to execute. That connects directly to the growing AI governance and compliance burden around authorization, audit trails, transaction limits and accountability when agents can act on financial infrastructure.
Financial AI is extending beyond conversational tools into models designed specifically for numerical sequences such as liquidity, transaction flows and other time-dependent financial data. Adoption by global banks gives the model more significance than a research release alone because forecasting accuracy can affect treasury, risk and operating decisions. That also raises the AI compliance burden around model validation, data quality, oversight and evidence when specialist models influence financial decisions.
The useful evidence is adoption inside a real advisory workflow rather than another AI pilot announcement. More than 11,000 client conversations and measurable administrative time savings show where AI governance for Canadian financial advisors is becoming operational: meeting records, follow-up communications and internal information retrieval. As these tools become routine, firms need controls that keep advisor responsibility intact while still capturing the productivity benefit.
Stripe is extending beyond the financial transaction layer into the infrastructure that determines which AI model handles a request and at what cost. That builds on Stripe's expanding infrastructure stack across payments, billing and financial operations. OpenRouter gives Stripe a position in both revenue collection and one of the largest variable costs facing AI companies: model and compute usage.
Giving an AI agent permission to transact creates a different control problem from giving it permission to retrieve information or call software tools. AgentCore places deterministic spending limits and transaction records around an otherwise non-deterministic agent, separating the agent's decision process from the infrastructure that authorizes payment. That control layer is becoming central to whether autonomous financial activity can be deployed at production scale.
Kraken is extending a crypto distribution platform into conventional brokerage while keeping tokenized equities available beside traditional shares. That gives customers two different ownership and market-access structures inside one interface and puts more competitive pressure on brokers that still separate securities, crypto and tokenized products across different accounts.
The proposal addresses how much trading functionality regulators should require when a swap does not have to trade through a prescribed execution method in the first place. Removing the order-book requirement could lower operating complexity for SEFs and give participants more choice in how less standardized or less liquid transactions are executed. The regulatory tradeoff is whether greater flexibility improves market efficiency without weakening transparency or competitive access.
Natural says payment infrastructure at scale requires capital because funds can be advanced before cash settles. The Upper90 facility adds dedicated financing capacity to the software and payment products Natural is building for AI agents. It complements AI agent spending controls emerging elsewhere in the stack, where transaction limits, authorization records and auditability govern automated payments.
Compute is starting to behave like a financial input rather than only a technology expense. Secondary markets are already emerging around scarce AI capacity, with market participants looking for better price discovery, liquidity and ways to manage infrastructure cost risk. Derivatives would take that development further by allowing firms to hedge future compute costs and availability, bringing market structure, manipulation and customer-protection questions directly into AI infrastructure.
The consultation exposes a tension inside post trade regulation: supervisors want better visibility into EU dependence on non-EU clearing infrastructure, but much of the relevant transaction information is already reported elsewhere. ESMA's design work therefore centres on identifying genuine data gaps rather than creating another parallel reporting system. The final technical standards will determine how much additional operational burden clearing firms face for that added visibility.
A regulated leasing route would let AI operators finance compute capacity over time while giving GIFT IFSC a position in the capital layer beneath AI deployment. The proposal addresses the AI infrastructure costs that are becoming a material constraint on production use.
Prediction markets are moving closer to the brokerage infrastructure already used to distribute financial products through fintech apps. That strengthens the innovation opportunity in regulated event contract infrastructure, where distribution, compliance, market integrity and settlement become as important as the contracts themselves. Alpaca's next proof point is whether partners actually embed the product once regulated operations begin.
The significance is regulated market access rather than a full crypto licence. Nigeria is using supervised incubation to bring international digital asset firms inside its regulatory perimeter while retaining control over permitted activities and operating conditions. For Blockchain.com, that creates a formal route into a large African digital finance market without treating sandbox admission as unrestricted authorization.
Adding more operating banks widens the distribution infrastructure behind the e-CNY without proving that customer adoption or transaction volumes have increased. The expansion builds on China's earlier digital yuan bank expansion and shows the operating network continuing to grow through established financial institutions rather than remaining concentrated among the original participants.
RoamQR connects international users to Pix without requiring Brazilian merchants to install new hardware or replace the QR infrastructure they already use. Participating wallets also avoid building separate bilateral integrations for each market. That is the interoperability problem highlighted in the cross border payments benchmark: strong domestic rails create more value when networks can connect them across borders without rebuilding the customer and merchant experience.
The partnership joins several financial layers that are often handled separately: consumer payment settlement, corporate liquidity, foreign exchange, tokenized treasury infrastructure and SME cross-border banking. It also fits Hong Kong's wider push toward tokenized financial infrastructure, where banks are combining regulated balance-sheet access with digital settlement and asset infrastructure rather than treating tokenization as a standalone product experiment.
Cross-border payment platforms can simplify the customer-facing experience, but settlement still depends heavily on regulated banking infrastructure, currency access and correspondent relationships underneath the API. Those dependencies are a central reason faster cross-border payments remain operationally difficult. Deutsche Bank gives TerraPay another institutional layer for moving and settling funds across currencies and jurisdictions, where corridor coverage, liquidity and local network access still determine performance.
Cross border payment competition is increasingly about how much complexity a platform can remove for the business initiating the payment. A single integration into global payout infrastructure can reduce the need to manage separate banking, wallet and local payment connections market by market. Fiserv now gives Thunes a much larger distribution channel into platforms and marketplaces that already manage business payment flows.
The Aug. 17 trigger is the public disclosure of the operating relationship, not the date the partnership became effective. The substance sits underneath Afriex's payment API: sponsor banking, settlement access and regulatory coverage determine how reliably the platform can connect local payment rails with international money movement. For cross-border fintechs, those banking relationships remain core infrastructure even when customers experience the service through a single API.
The acquisition puts insurance capacity, underwriting data and active cyber defence inside the same operating structure. At-Bay already monitors insured risk throughout the policy lifecycle, giving Munich Re a platform that can influence both loss prevention and pricing rather than relying only on claims experience after an incident. That integration could become more important as cyber insurers compete on the quality of the security controls wrapped around coverage.
Boost is putting banking, merchant payments and credit inside one operating interface for small businesses rather than distributing them as separate products. Same-day settlement can feed directly into cash management while transaction history can sit closer to financing decisions. For SMEs, the value depends on whether that integration reduces the time between making a sale, receiving usable funds and obtaining working capital when it is needed.
Canada's move toward faster payments compresses the time available to detect scams before money leaves an account. The survey shows that consumers already put security ahead of speed and convenience, while confidence in fraud protection remains uneven. As Real Time Rail testing and access advance, banks and payment providers will need fraud controls that work across identity, accounts and transaction channels rather than relying mainly on intervention after a suspicious payment has been completed.
The circular connects Faster Payment System deposits directly to trading-account and virtual-asset controls. Efficient funding depends on whether firms can verify ownership, stop suspicious instructions and manage the liability attached to simplified authorization.
The investigation shows why mortgage fraud controls cannot rely only on what one lender can see inside its own book. Repeated brokers, accountants, law firms, documents and funding patterns became more visible when information from multiple banks was analysed together. For lenders, that strengthens the case for shared intelligence and earlier detection before questionable loans are approved and funds become harder to recover.
Hardware wallet security now extends beyond protecting private keys. Order records can identify where crypto holders live and what they purchased, creating targeted phishing, impersonation and physical-security risks even when the wallet itself remains secure. That adds a customer-data layer to the self custody security risks already exposed by device and firmware failures.
APRA’s earlier focus on AI risk governance now extends to shared technology dependencies and stored-value infrastructure. Banks, fintech vendors and wallet providers should expect closer scrutiny of resilience, provider concentration and accountability across outsourced systems.
Like the several past months, this week’s Whisperer shows financial infrastructure becoming more integrated, more programmable and more regulated at the same time. The edge is going to firms that can combine distribution, trusted controls and ownership of the infrastructure underneath payments, AI, digital assets and capital markets without adding friction faster than they add capability.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 20, 2026 | NCFA Resource | Payments And Money Movement, Banking And Credit, Financial Inclusion
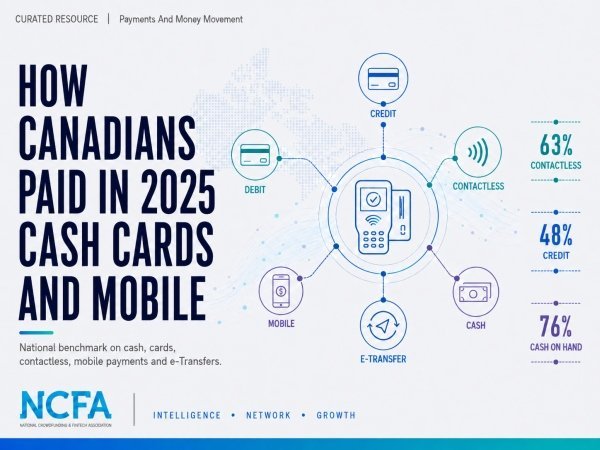
On August 20, 2026, the Bank of Canada published its 2025 Methods-of-Payment Survey, based on responses from 4,964 Canadians and payment diary data from 2,185 participants. The report measures cash holdings, card use, mobile payments, Interac e-Transfer, payment costs, merchant acceptance and how consumers rate different ways to pay.
For payments firms, banks, fintechs and policy teams, the survey provides a current national benchmark for consumer behaviour. Credit cards remain the dominant payment method, contactless now accounts for most in-person purchases, mobile devices are taking a larger share of card taps, and cash remains widely held even though its transaction share fell in 2025.
Credit cards accounted for 48% of purchase volume and 58% of purchase value in 2025. Debit represented 25% of volume and 24% of value, while cash accounted for 18% of point of sale transaction volume and 10% of value. Cash had represented 21% of volume and 11% of value in 2024, so the latest survey records a decline after several years of relative stability.
Contactless payments now dominate in person. In 2025, 63% of in-person payments were contactless, representing 61% of in-person purchase value. Most taps still used physical cards, but mobile devices accounted for one quarter of contactless credit transactions and 15% of contactless debit transactions.
The mobile figures are more useful than in previous surveys because the Bank changed its 2025 payment diary. Respondents who reported tapping a card were asked whether they used the physical card or a version stored on a mobile device. That difference helps separate adoption of mobile wallets from adoption of the underlying payment rail. A credit card stored in a phone remains a credit card transaction, but the interface through which the customer pays has changed.
The revised survey also suggests previous estimates understated mobile use. Over the previous year, 41% of Canadians reported using mobile payments, while just over half used Interac e-Transfer. About one quarter used a digital wallet app and 19% used a bank account app. Those adoption figures should not be read as transaction shares. Interac e-Transfer, for example, appears less often in the three day purchase diary because consumers frequently use it for expenses such as rent and home services that the diary does not capture.
The findings provide a useful consumer benchmark beside Canada’s financial infrastructure changes. Expanded Payments Canada membership, the Real-Time Rail, payment service provider oversight and consumer-driven banking are changing how firms can access and build on payment infrastructure. The Bank’s survey shows the payment habits those services will encounter as they reach consumers.
Cash presents a more mixed picture. About 76% of Canadians had cash on hand when surveyed, with an average of $141 and a median of $70 among people carrying it. Four out of five Canadians said they had no plans to stop using cash, while only 12% described themselves as cashless. At the same time, cash transaction share and average cash holdings both fell in 2025.
The Bank does not treat one year of weaker cash use as proof of a lasting decline. More observations are needed to separate a durable change from normal survey variation or a temporary result. Access also remains relevant: 68% of Canadians described access to an ABM as easy or very easy, compared with 61% for a bank branch.
Payment providers and fintech product teams can use the survey to test assumptions about where Canadian payment behaviour is concentrated. Credit and debit cards still account for most everyday purchases, contactless has become the normal in-person card experience, and mobile wallets are becoming a more important way of presenting those same card credentials.
Banks and financial institutions can use the findings to compare physical and digital access. Consumers are using mobile payment tools more often, but most still keep cash and report that access to ABMs and branches remains important. That combination is relevant when firms make decisions about digital channels, cash services, card products and customer support.
Investors and market researchers get a national reference point for assessing product adoption claims. The report separates annual use, recent use and actual transaction diary data, which helps distinguish a service that many people have tried from one that captures a large share of purchases.
Policy teams can read the findings alongside Canada’s consumer-driven banking rules. The survey does not measure open banking use, but it establishes how Canadians currently pay before regulated data sharing and future payment initiation services reach wider adoption.
For financial inclusion work, the cash findings are especially useful. Digital adoption does not mean all consumers have stopped using physical money. Most Canadians still keep cash, most do not plan to abandon it, and access to withdrawal infrastructure continues to affect how practical cash remains.
The survey combines two useful forms of evidence. The questionnaire captures payment ownership, cash holdings, recent use, costs and consumer perceptions, while the three day diary records purchases and withdrawals closer to when they occur. In 2025, 4,964 people completed the questionnaire and 2,185 submitted at least one day of diary data.
Its history also adds value. The Bank began the Methods-of-Payment survey in 2009 and has run annual surveys since 2021, giving readers a basis for comparing the latest results with earlier payment behaviour. That longer record is why the 2025 decline in cash should be watched rather than immediately treated as a permanent change.
The methodology has limits. The questionnaire uses quota sampling by age, gender and region, then calibrates the samples to Canadian demographic characteristics. The diary covers only three days, and not every questionnaire respondent completes it, so less frequent payments can appear more clearly in recall questions than in the transaction diary.
The new mobile measurement also affects comparisons with earlier years. Separating physical card taps from cards stored on mobile devices improves the 2025 data, but some earlier mobile figures were measured differently and should not be compared mechanically.
NCFA’s Canadian payments market coverage puts the Bank’s consumer survey beside a much larger benchmark. Payments Canada recorded 22.5 billion retail payment transactions worth $12.2 trillion in 2024. The two datasets answer different questions. The Bank of Canada focuses on how consumers hold, choose and use payment methods, while Payments Canada measures transaction volumes, values and market activity across the payment system.
2025 Methods-of-Payment Survey PDF (62 page report, tables, charts and methodology)
Methods-of-Payment Survey (Bank of Canada survey series and historical results)
2024 Methods-of-Payment Survey (previous annual consumer payment benchmark)
Canadian Payment Methods And Trends 2025 (22.5 billion retail transactions worth $12.2 trillion)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
August 19, 2026 | NCFA Resource | Cybersecurity And Fraud, Risk Compliance And Regtech, Capital Markets And Market Infrastructure

In August 2026, the Financial Industry Regulatory Authority published Cybersecurity Effective Practices, a 12-part framework for FINRA member firms reviewing cybersecurity programs, controls and operating procedures. A firm can use the resource as a structured checklist for who owns cybersecurity, which systems and vendors create risk, who can access sensitive data, how threats are detected, and whether the business can recover when systems fail. FINRA designed the practices to scale with firm size, business model, technology complexity and risk profile.
FINRA organizes the resource around 12 areas:
The framework starts with accountability and risk ownership. FINRA recommends a designated cybersecurity lead, regular reporting to senior decision makers, documented policies and periodic reviews, while also making cyber risk part of decisions about new technology, systems and operating changes. From there, firms are expected to identify the information, systems and business functions they depend on, assess threats such as ransomware, insider activity and vendor exposure, test important systems for weaknesses and revisit those risks when technology or operations change.
Third party risk receives detailed treatment. FINRA treats vendors with access to customer information or critical systems as part of the firm’s security perimeter. Firms should know which vendors have access, understand important fourth party relationships and identify which providers support critical operations. Contracts can address audit rights, data handling, breach notification and visibility into subcontractors, while ongoing oversight should include access monitoring and a documented process for removing access and handling customer information when a relationship ends.
That concern extends beyond US broker dealers. Weak access control governance can expose sensitive information when a partner or service provider retains permissions that are unnecessary or poorly monitored. FINRA’s guidance connects vendor governance with the practical question of who can access systems and data, for how long, and under what controls.
Asset management and access control fit naturally together. FINRA recommends keeping a current inventory of hardware, software, cloud services and data flows, assigning owners to important assets and identifying systems that no longer receive security updates. Once firms know what they have, they can control who gets access through unique credentials, role based permissions, multifactor authentication, periodic entitlement reviews, segregation of duties and least privilege. Access should also be changed or removed promptly when employees change roles or leave.
Data protection, training and patching cover another part of the operating picture. Firms are encouraged to classify sensitive data, encrypt it at rest and in transit where feasible, control retention and protect backups, including with immutable or air gapped storage. FINRA also recommends ongoing employee training, role specific instruction for staff with sensitive access and phishing simulations backed by records of participation. Vulnerability management should include regular scanning, risk based patch priorities and verification that remediation work was completed rather than assumed.
The primary users are FINRA member broker dealers, including compliance teams, cybersecurity leaders, technology teams, operations executives and senior management. Smaller firms can use the 12 areas to identify where basic controls are missing without trying to copy the cybersecurity program of a much larger institution, while larger firms can use the same structure to review whether responsibilities, documentation and technical controls are working together.
Technology providers, managed security firms, consultants and RegTech companies serving broker dealers can also use the resource to understand what clients may expect around access, logging, vendor controls, data handling, patching, incident response and recovery. Boards and senior executives can use it as a governance checklist because FINRA makes cybersecurity ownership, management reporting, resource decisions and documented risk acceptance part of the program rather than leaving cyber risk entirely with the technology team.
The main strength is that FINRA connects governance directly to operating controls. A firm can follow the framework from senior accountability through asset inventories, identity controls, encryption, training, monitoring and recovery testing, which makes the document more useful than a high level cyber policy statement.
Third party risk is also handled with more depth than a basic checklist. Firms are expected to understand vendor dependencies, monitor privileged access, address fourth parties and plan how systems and data will be handled when a provider relationship ends. Security monitoring extends that discipline to unusual access, suspicious data transfers, system changes and privileged accounts, with logs retained long enough to support operations, investigations, forensic work and applicable recordkeeping requirements.
The framework also includes threat intelligence, incident response and recovery. FINRA recommends using relevant threat feeds, updating defenses as attack methods change and participating in trusted information sharing networks. Incident response focuses on how a firm detects, escalates and contains an event, while recovery planning deals with how critical systems and data return to service afterward. Tested backups, tabletop exercises, offline procedures and defined Recovery Point Objectives and Recovery Time Objectives all help firms decide how much data loss and downtime different systems can tolerate.
The main limitation is jurisdiction. FINRA developed the resource for US member firms and connects several practices to US requirements, including SEC Regulations S-P and S-ID, FINRA Rules 3110 and 4370, and Exchange Act recordkeeping rules. The document also doesn't create new legal or regulatory requirements or reinterpret existing ones. For Canadian financial technology and service firms, its best use is as a practical comparison and control review, not as a statement of Canadian regulatory obligations.
FINRA Cybersecurity Effective Practices (12-part cybersecurity control framework)
Cybersecurity Effective Practices PDF (downloadable nine page resource)
Small Firm Cybersecurity Checklist (small firm program checklist last reviewed February 2024)
Core Cybersecurity Threats And Controls (small firm threats and control questions)
FINRA Cybersecurity Resources (cybersecurity tools, guidance and related material)
2026 Cybersecurity And Cyber Enabled Fraud (current threats and effective practices)
Proposed Class Action Targets Equifax Access Controls (access governance and third party permissions)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
