





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 30, 2026 | NCFA Story Intelligence | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure
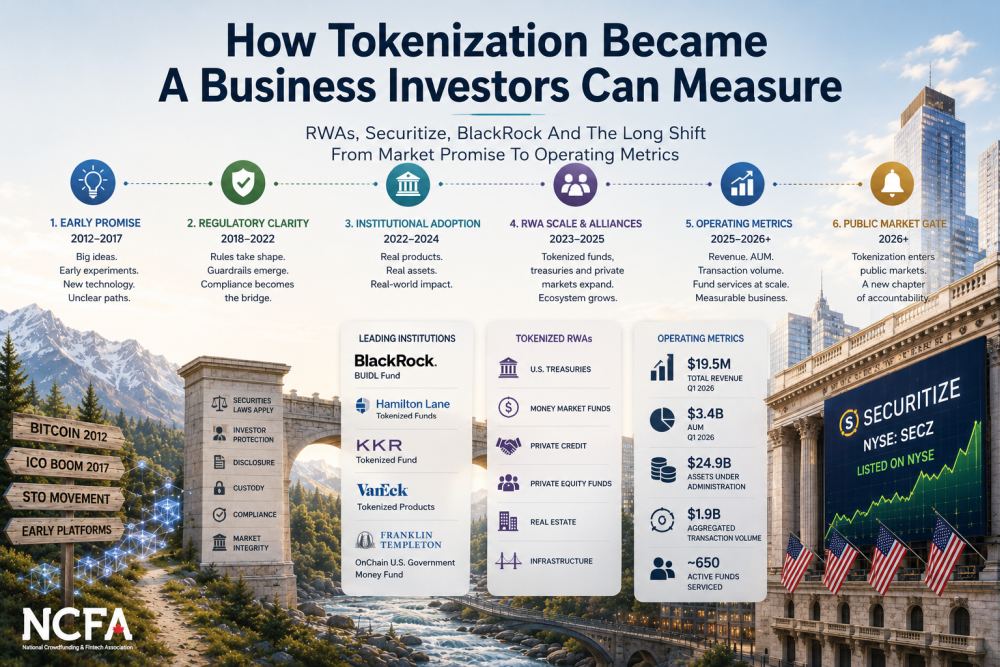
Tokenization promised to change capital markets for more than a decade.
The promise is still attractive. Put ownership on chain. Reduce paperwork. Automate compliance. Improve access. Speed up settlement. Make private assets easier to distribute, manage, and transfer.
But markets don’t run on promises. They run on operating models, regulation, distribution, controls, liquidity, and trust.
That’s why Securitize’s expected NYSE listing is the trigger. The listing isn’t the whole story. It’s the latest chapter in a longer path from tokenization as a market idea to tokenization as a business investors can measure.
The first wave sold a powerful idea. Security tokens, STOs, fractional assets, real estate tokens, private shares, and blockchain based markets promised to bring traditional securities into programmable digital form. The early security token field was framed as a more regulated answer to the ICO boom.
The market didn’t overhaul itself. Early security token projects ran into the same walls: unclear regulation, thin liquidity, limited distribution, custody questions, fragmented platforms, investor eligibility rules, and the simple reality that a tokenized security still has to behave like a security.
The hard work was never only technical. A tokenized fund still needs investor onboarding, KYC, AML, transfer rules, custody, servicing, reporting, distributions, tax records, corporate actions, and permissioned secondary transfers. Those aren’t marketing features. They’re the boring parts that make markets work.
Regulators kept reminding the market that labels don’t change obligations. Hester Peirce’s point that tokenized securities still have to follow securities laws captured the practical boundary. Faster settlement and automation don’t remove investor protection, disclosure, and market integrity requirements.
Real world assets changed the packaging. The market stopped asking whether everything should become tokenized and started asking which assets actually benefit. Treasuries, money market funds, private credit, private equity funds, and alternative assets became more practical test cases than vague claims about digitizing every market.
Private markets gave tokenization a clearer job. Citi, Wellington Management, and WisdomTree tested private market tokenization in 2024, showing how smart contracts could support operating efficiency in traditionally manual private market processes.
Hamilton Lane used tokenization to lower access friction. In 2022, Hamilton Lane and Securitize said qualified US investors would gain access to tokenized feeder funds tied to direct equity, private credit, and secondary transaction strategies.1 Securitize later said one Hamilton Lane fund reduced the minimum investment from about $5 million to $20,000.2
KKR showed that major alternatives managers would test the model. Securitize launched a tokenized fund offering exposure to KKR’s Health Care Strategic Growth Fund II in 2022, framing the product around broader access to alternative investments through digital ownership.3
BlackRock changed the market’s confidence level. BlackRock launched BUIDL, its first tokenized fund, on Ethereum in March 2024. The fund was backed by cash, US Treasury bills, and repurchase agreements, with BNY Mellon enabling interoperability between digital and traditional markets.4
BUIDL became a measurable adoption signal. In March 2025, Securitize said BUIDL surpassed $1 billion in AUM and identified itself as the tokenization provider for the fund.5 BlackRock’s BUIDL launch became one of the clearest institutional signals that tokenization was entering regulated asset management.
Securitize turned the thesis into operating data. In Q1 2026, Securitize reported $19.5 million in total revenue, up 39% year over year, $3.4 billion in AUM at quarter end, $24.9 billion in assets under administration, $1.9 billion in aggregated transaction volume, and roughly 650 active funds serviced through Securitize Fund Services.6
Those numbers change the conversation. Investors can ask normal operating questions: revenue mix, servicing fees, client concentration, transaction volume, fund growth, margins, profitability, operating leverage, customer retention, regulatory execution, and how much tokenization demand converts into durable revenue.
The listing is the trigger. Securitize and Cantor Equity Partners II said the business combination was expected to raise approximately $400 million in gross proceeds, close after shareholder approval and customary conditions, and list on the NYSE under ticker SECZ.7
The listing doesn’t settle the thesis. It exposes the thesis to market discipline. A listed tokenization company has to explain growth, losses, expenses, institutional demand, regulatory risk, competitive pressure, and whether tokenized fund adoption can become a durable public company business.
Canada has a practical watchlist. The opportunity isn’t to copy a US listing. Canadian firms can look across the tokenization value chain: custody, transfer services, fund administration, compliance, exempt market distribution, private market platforms, digital identity, investor onboarding, reporting, and secondary trading.
Regulated product design may decide the next chapter. The OSC’s long term asset fund project pointed to possible retail exposure to traditionally inaccessible assets and raised the opportunity for tokenized long term funds with embedded compliance, transparent records, fractional access, and guardrails.
Tokenization didn’t become measurable overnight. It moved through years of big claims, stalled experiments, regulatory pushback, operating layer buildout, institutional product design, and real world asset packaging before public markets had a company they could evaluate with ordinary business questions.
That may be the clearest test. The first tokenization wave asked investors to believe in a technology. The next wave will ask investors to evaluate execution. Revenue. Margins. Assets. Transactions. Clients. Losses. Retention. Market share. Operating leverage. That is a much harder test, and a much more useful one.
For Canada, the lesson is practical. The next winners may not be the firms issuing the tokens. They may be the firms solving everything around them: custody, compliance, investor onboarding, fund administration, reporting, liquidity, and regulated distribution. That’s where durable businesses are often built, and where Canada’s capital markets innovation map can help identify opportunities that are still taking shape.
What operating metric would convince you that tokenized markets have moved beyond promise?
Share this story → Explore related intelligence → Subscribe
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply