





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Sep 9, 2026
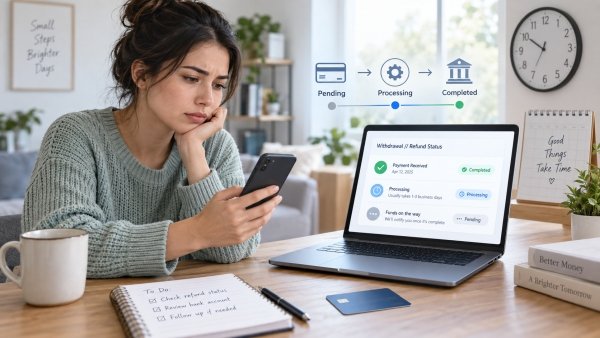
Digital payments often feel immediate. A customer can place an order, fund an account, or purchase a subscription in seconds. When money needs to travel in the opposite direction, however, the process can take considerably longer.
Refunds and withdrawals pass through multiple systems before reaching a customer’s account. The business, payment provider, bank, card network, and fraud prevention team may all play a role. Understanding these stages can help consumers set realistic expectations and identify when a delay requires further action.
A refund reverses all or part of an earlier payment. It might follow a canceled order, returned product, duplicate charge, or service complaint. The money usually returns through the same payment method used for the original transaction.
A withdrawal moves money from an account or platform to an external destination. Examples include transferring funds from an investment app, marketplace, digital wallet, or online casino to a bank account or payment service.
The difference matters because each process follows its own review and settlement procedures. A merchant refund may be approved quickly but remain pending with the card issuer. A withdrawal may require identity checks before the platform releases any funds.
Some services promote instant or same-day withdrawals, but the term usually describes how quickly the platform approves or sends the payment. It does not necessarily guarantee that the money will appear in the recipient’s account immediately.
This distinction is especially relevant in competitive industries. Casino.ca profile Canadian operators with fast payment processes, including instant withdrawal casinos, so readers can compare which platforms are known for efficient payouts. However, the final arrival time may still depend on the withdrawal method, banking hours, identity verification, and the policies of the receiving financial institution.
The same principle applies to retail refunds, freelance platforms, travel companies, and investment services. A business may release funds promptly while another organization within the payment chain takes additional time to process them.
Processing times vary considerably between payment methods.
Digital wallets can be among the fastest options because funds remain within a connected electronic network. Some transfers may arrive within minutes, while others require a short review period.
Bank transfers can take longer, particularly when payments move between different institutions or countries. Weekends, public holidays, currency conversions, and intermediary banks may add further delays.
Card refunds often take several business days to appear. Although a retailer may issue a refund immediately, the card network and issuing bank must still process the reversal. Some banks display pending refunds, while others show the money only after settlement is complete.
Checks are generally slower because they require production, delivery, deposit, and clearance. They may still be offered when an electronic refund cannot be returned to the original payment method.
Platforms that handle financial transactions commonly verify customers before processing withdrawals. This may involve confirming a name, address, payment method, age, or source of funds.
These checks help prevent fraud, identity theft, unauthorized payments, and money laundering. They can also cause delays when documents are missing, expired, unclear, or inconsistent with the account details.
Completing verification early can reduce the risk of disruption. Customers should make sure account information is accurate and submit documents only through secure, official channels.
Businesses should explain their requirements before accepting money rather than introducing unexpected checks when a customer requests a withdrawal.
Processing estimates are usually expressed in business days. A refund issued late on Friday may not begin moving through the banking system until Monday. A public holiday can extend the wait further.
International transactions may be affected by holidays in more than one country. Time zones can also influence whether a request is received before or after a provider’s daily processing cutoff.
For this reason, “three business days” should not be interpreted as 72 hours. Depending on when the request begins, three business days could cover a much longer period on the calendar.
Before contacting support, customers should check the stated processing window, transaction status, payment details, and any verification requests. It is also important to distinguish between the date a payment was approved and the date it was sent.
If the quoted timeframe has passed, request a transaction reference or confirmation number from the business. A bank or payment provider may be able to trace the funds using that information.
Consumers should be cautious if a company repeatedly requests additional deposits, fees, or taxes before releasing a withdrawal. Legitimate charges should be clearly disclosed and should not continually change.
Fast payments can build confidence, but transparency is just as important as speed. Businesses that explain each stage, provide realistic timelines, and communicate delays clearly are more likely to earn lasting customer trust.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply