What Can Traditional Banks Learn From Fintech?

Forbes |

The growing popularity of fintech and the emergence of competitors in different phases of the cycle, from new banks such as Germany’s N26 to partial service providers such as Revolut and others, or niche competitors such as Shine, highlights not just the inability of traditional banking to compete with them, but even to understand the most basic implications of the phenomenon.

The banks’ problem is not competing with these types of companies, or at least, not for now. We talking here about vastly different magnitudes, of scale: a service with strong growth like Revolut, for example, expects to reach three million customers by next month, which is nothing to Santander’s more than 113 million customers in more than ten countries worldwide. The idea that fintech companies represent some kind of threat seems absurd, seen in the context of size.

Obviously, this does not mean that the traditional banks should ignore the phenomenon — and they aren’t. Ignoring change and hoping that size will continue to matter is risky. The big banks are aware that the growth of the fintech phenomenon is mainly due to their own shortcomings, to the strong tendency towards industry isomorphism, and to the need for a replacement highlighted by the fact that fintech attracts younger people. Clearly, if nothing is done, there is a risk that many customers who today resort to competitors from the fintech world for relatively specific needs such as making a transfer or traveling abroad will end up seeing them as a more and more attractive option to the big banks, who are burdened by a specific approach to banking and many years of bad image.

See:  Fintech startup looks to expedite tax-free shopping online for First Nations

So what should the big banks do about fintech? Study how they do things and use them as external innovation laboratories. For a traditional bank, the news is not that a fintech closes a round of successful financing or grows its client base, but that it is able to present itself as a “bank without commissions” when in a reality, their freemium service is very limited, and access to a real range of services requires paying between €7.99 and € 13.99 a month. For a traditional banking executive, the idea that those same customers who protest their operation-by-operation commissions every day may consider paying those amounts because “they are not a commission but an extra service” should be very interesting. If we add seemingly more superficial elements to the equation, such as the new tendency towards heavier metal cards than the usual plastic, supposedly higher status, the question seems obvious: is there a demand for a type of client who not only wants a bank that offers traditional banking services, but also “feels” different in some way. Absurd? Image? A mere fad? The point is that a certain number of people go from protesting about daily commissions from traditional banks to religiously paying a monthly or annual fee for a metal credit card, and the banks need to ask themselves why.

Believe it or not, the new Revolut card’s marketing emphasizes its careful manufacture as if it was some sort of luxury item, while N26’s has no less than an inner tungsten layer. But what they’re really about are services such as cashback systems paid in a cryptocurrency of your choice, special advantages for users of work centers like WeWork, or access to insurance, along with highly customized services for certain customer segments. France’s Shine, for example, is particularly interesting: a specialized approach for freelancers offering services ranging from legal registration to tax payments (a real pain in terms of bureaucracy in France), and with a sign up process pretty similar to a social network’s. For certain groups, a Shine account offers advantages that, whether you’re a Deliveroo runner, somebody offering your services in Upwork or who works directly with your clients, allow you to enter your Shine IBAN on the platform to regularize the entire process, or create a page from which to manage your billing and that allows your customers to pay you with a card.

What do we look for in a bank? Increasingly, services far beyond traditional banking operations, and with much higher tolerance for payment derived from a perception of added value, of simplifying a process. Pay for convenience, not by decree, for what we really value, be it a service or a perception. Where can you expect these kinds of trends to start, where is the right place to see and understand them? Not in a traditional bank that launches them as “another project” by someone who competes for the attention of senior management with a thousand similar projects, but in small fintech companies that treat these services as a matter of identity or even life and death.

More:  U.S. bank regulator allows fintech firms to seek federal charter

How many senior banking executives are curious enough about fintech to have bothered to open an account with a fintech and then to use it to the full to learn from their practices? How many are thinking about what it would take for their organizations to launch similar products or services? How many people in the traditional banks are studying fintech as a source of ideas for innovation at all levels? Or are they too busy with other, supposedly more important things?

Continue to the full article --> here


The National Crowdfunding & Fintech Association of Canada (NCFA Canada) is a cross-Canada non-profit actively engaged with fintech, alternative finance, blockchain, cryptocurrency, crowdfunding and online investing stakeholders globally. NCFA Canada provides education, research, industry stewardship, services, and networking opportunities to thousands of members and subscribers and works closely with industry, government, academia, community and eco-system partners and affiliates to create a strong and vibrant crowdfunding and fintech industry. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: ncfacanada.org
NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights

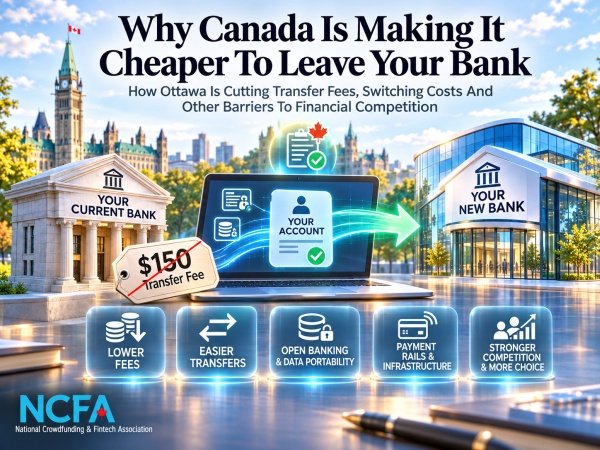
November 11, 2026 | NCFA Story Intelligence | Competition And Market Structure, Wealthtech Investing And Trading, Regulation And Policy Canada is cutting bank fees and switching barriers after years of weak competition, high concentration and poor productivity. On November 7, 2026, the federal government proposed something Canadian investors have complained about for years. Banks would no longer be allowed to charge most investment account transfer fees, which typically cost about $150 per account. Ottawa also wants clearer transfer information and tighter timelines for moving investments to another financial institution. The fee matters because leaving can already be slow and frustrating. Receiving firms often reimburse the outgoing charge to win the account. That means a fee collected by the institution losing the customer can become part of the acquisition cost for the institution trying to win that customer. Canada's six largest banks hold roughly 93% of banking assets. The Competition Bureau was warning about barriers facing fintech competitors in 2017. Ottawa began reviewing open banking in 2018. A federal advisory committee later recommended an operating system by January 2023 and warned that government should not delay. January 2023 came and went. Real Time Rail also slipped years beyond its first expected ...
Digital illustration of Canada bank transfer fee reform showing easier investment account switching, lower fees, open banking, payment infrastructure and stronger financial competition
November 10, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Regulation And Policy Funds, Collateral And Settlement Lead Canada’s Near Term Tokenization Opportunity On November 10, 2026, the Canadian Securities Administrators published its Project Tokenization Phase 1 findings, setting out where Canadian market participants see the strongest commercial opportunities for tokenization and what regulators plan to test next. The report draws on 233 organizations, 21 bilateral meetings and 80 survey responses, along with workshops attended by 281 people in Calgary and 491 in Toronto. Participants put investment funds, private assets, collateral, treasury and settlement infrastructure ahead of public stocks as the strongest near term opportunities. The report also cuts through one of tokenization’s biggest sales pitches. Blockchain can change how an asset is recorded, transferred or settled, but it doesn't automatically create liquidity, investor demand, broader eligibility or stronger ownership rights. Those outcomes still depend on the product, market, legal structure and infrastructure around it. The CSA now plans to take specific projects into Phase 2 through a 120 day public call for proposals. Firms may be able to use existing regulatory processes, tailored regulatory treatment or bounded testing in a ...
Digital illustration of tokenized financial assets, blockchain settlement and legal infrastructure, representing Canada's investment funds and collateral markets.
Nov 11, 2026 A positive work environment is key for any team that wants to succeed. Team morale is crucial for productivity, motivation, and job satisfaction. Engaging in activities that lift spirits and strengthen connections can lead to great results. Creating a positive team environment requires creativity, engagement, and some fun. Each activity can strengthen connections, boost motivation, and improve workplace dynamics. When teams focus on strategies to boost morale, they work toward shared success. These activities can lead to lasting memories and help build a stronger team culture. Here are some fun strategies to help improve your team's morale and make the workplace livelier. Fun at the Arcade Visiting an arcade spot is a great way to enjoy time together and build teamwork. Imagine your team facing challenges with various games. Whether it's racing or playing team games, the arcade encourages friendly competition and bonding. These fun experiences can help reduce stress and improve relationships among coworkers. Arcades offer many options to suit diverse interests and skill levels. The lively atmosphere invites everyone to relax and take a break from their daily tasks. Shared laughter and enjoyment can lead to better communication and teamwork when you return to the ...
Digital illustration of team building activities boosting workplace morale with coworkers playing games and laughing in a bright modern office
November 10, 2026 | Market Activity | Fundraising, Investing, Trading, Leadership, Competition, Human Capital, Health A Brokerage Race Beyond $0 Commissions On November 10, 2026, Webull Canada added Nasdaq Basic Canada, giving clients free real time Level 1 quote and trade data across Canadian listed equities. The feed provides best bid, best offer and last sale information for stocks listed on the TSX, TSX Venture, CSE and Cboe Canada. Nasdaq says its consolidated feed can reduce Level 1 market data costs by more than 60% compared with traditional Canadian data packages. Webull isn't first to give Canadian investors free real time information. The more interesting story is how quickly another paid feature is becoming part of the basic brokerage account. Wealthsimple helped normalize $0 trading in 2019, Questrade followed in 2025 and Webull dropped its own commissions in April 2026. With the headline trading fee largely gone, brokers now need other reasons for investors to move money and keep it on the platform. Who Led Canada’s Race To $0 Trading And Free Market Data Wealthsimple Trade launched nationally on March 13, 2019 with $0 commissions on Canadian and U.S. stocks and ETFs. Questrade removed commissions on listed stocks and ETFs ...
AI illustration of Canadian online brokerage competition with racing cars promoting $0 commissions, free real time market data and transfer match bonuses
November 10, 2026 | Market Activity | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding A Toronto Fintech Riskfuel Analytics Brings AI Pricing Into BBVA’s Global Markets Workflow On November 10, 2026, BBVA deployed Riskfuel Analytics' neural pricing technology inside the pre-trade structuring workflow for autocallable products on its ePricer platform. Riskfuel is a Toronto fintech founded in 2019 that builds AI models for derivatives pricing. BBVA is a global bank with a large corporate and investment banking business. The deployment puts Canadian built AI directly into the calculations used to design complex structured products at a major global bank. Riskfuel's model is trained on BBVA's own pricing engine and uses more than 4,000 market and product inputs. The company says the surrogate was tested against more than 100,000 trades and can evaluate thousands of candidate structures in under a minute. BBVA had already added AI generated investment ideas to ePricer in September. Riskfuel goes further into the workflow by speeding up the numerical pricing work while BBVA's own model remains the reference. How Riskfuel Speeds Up BBVA's Autocallable Pricing Autocallables can depend on volatility, interest rates, dividends, maturity, coupon levels and several barrier conditions. Autocallables are structured investments ...
AI illustration of AI powered derivatives pricing shown on a financial trading screen, illustrating Riskfuel technology used in BBVA structured product workflows
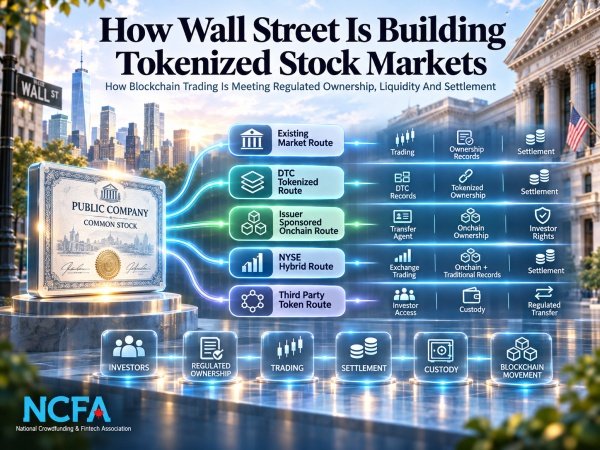
November 9, 2026 | Story Intelligence | Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization How Blockchain Trading Is Meeting Regulated Ownership, Liquidity And Settlement On November 9, 2026, Ava Labs announced Avalanche as the core clearing ledger for NYSE's planned tokenized securities venue. NYSE isn't putting its stock exchange on Avalanche. NYSE Pillar remains the planned trading engine. Regulated transfer agents will connect digital shares with shareholder records. Avalanche will sit inside the clearing process after a trade is matched. Stablecoin funding is part of the design. Blockchain companies have spent years building ways to issue, trade and settle assets directly on digital networks. Wall Street already has a system that performs those jobs at enormous scale. Now the two have to connect. Blockchain can make securities programmable and allow the asset and cash to settle together. Public markets depend on deep liquidity, clear ownership records, custody, corporate actions and regulated firms that remain accountable when something goes wrong. The question isn't whether stocks can be tokenized anymore. It's whether tokenized stocks can gain the speed and flexibility of blockchain without splitting ownership, liquidity and investor protection across too many systems. Canada put a real security through ...
AI illustration of Wall Street tokenized stock markets showing regulated trading, ownership, settlement, DTC tokenization, issuer sponsored shares and blockchain routes
Nov 10, 2026 Paying with your phone has become second nature for most Canadians, whether you're grabbing a double-double or splitting a dinner bill. So it makes sense that more players want to fund their casino accounts the same way. If you've been browsing Google Pay Casinos Canada, you've probably noticed that not every site handles this wallet equally well. Some make deposits feel effortless, while others bury Google Pay behind extra steps or fees. Here's how we'd go about picking a good one. What to Look For in a Google Pay Casino Before you sign up anywhere, it helps to know what separates a smooth Google Pay experience from a frustrating one. We look at a few key areas every time we test a site. A Valid Licence Comes First No payment method can make an unsafe casino safe. Check the footer of the site for a licence from a recognized regulator. If you're in Ontario, look for iGaming Ontario and AGCO approval. Elsewhere in Canada, many players use offshore sites licensed in places like Malta or Curaçao. Whatever the licence, you should be able to click through and confirm it's real. If the casino hides this information, we'd ...
AI illustration of a smartphone digital wallet, online casino interface, and checklist covering licensing, payment options, fees, payout speed, and account security.
November 9, 2026 | Market Activity | Wealthtech, Investing And Trading, Fundraising And Capital Markets Competing for Canada’s $98.6 Billion RESP Market On November 6, 2026, National Bank of Canada agreed to acquire Embark Student Corp. for an estimated $226 million, adding more than $6 billion in RESP assets under management and approximately 436,000 beneficiaries. The deal gives National Bank immediate scale in Canada’s $98.6 billion RESP market and strengthens its digital competition with Wealthsimple, Questrade and other investment platforms. The transaction is expected to close by mid fiscal 2027, subject to court, regulatory and other customary approvals. National Bank already competes in Registered Education Savings Plan (RESP) accounts. It offers advisor supported RESPs and its direct brokerage lets customers manage RESP investments themselves. Embark brings a national digital business focused specifically on managed education savings, grant administration and RESP servicing. The acquisition gives National Bank a third way to compete for families without building that specialist operation one customer at a time. What National Bank Gets That It Doesn't Already Have Embark is one of Canada's largest direct to consumer RESP providers and operates as a Scholarship Plan Dealer across Canada. Its platform handles account administration, investment management, government ...
AI illustration of a graduation cap on stacked books beside a piggy bank and savings jar, illustrating education savings and competition in Canada’s RESP market
November 9, 2026 | NCFA Story Intelligence | Risk Compliance And Regtech, Cross Border Payments And FX, Digital Assets Blockchain And Tokenization When Canadian MSB Registration Meets Sanctions, Crypto and Financial Crime On November 6, 2026, eight Canadian money services businesses appeared on a U.S. sanctions list. Every one of them had a Canadian MSB registration number. That number meant the business had entered Canada's federal registration system. It didn't mean FINTRAC had approved the firm, cleared its customers or vouched for every transaction passing through it. Until November 6, that distinction could sound technical. Then the U.S. Treasury allegations arrived. Treasury says several of the eight firms converted cash or conventional currency into digital assets that reached sanctioned Iranian exchanges, addresses associated with the Islamic Revolutionary Guard Corps and, in some cases, wallets tied by U.S. authorities to Canadian drug trafficker Ryan Wedding. The firms had Canadian addresses, Canadian corporations and Canadian registration numbers. Now they also had OFAC designations. The same day, FINTRAC coordination with OFAC and FinCEN became public. Then Canada's financial intelligence agency disclosed what had been happening inside its own MSB regime during 2026: 161 registrations revoked, more than $198 million in penalties against nine ...
AI illustration of Eight Canadian MSBs linked to U.S. Iran sanctions with FINTRAC, crypto transactions and cross border enforcement imagery
Nov 9, 2026 Work can be stressful, especially in our busy world. Many people feel pressured to meet deadlines and juggle multiple tasks, which can leave them feeling overwhelmed. Work stress and fatigue can hurt both your job performance and your personal life. Recognize these feelings and look for ways to reduce them for better overall well-being. Many believe that working long hours is unavoidable. However, you can find simple ways to manage stress and boost your energy for a more balanced and satisfying work life. Here are some strategies to help you reduce work stress and fatigue. Set Healthy Boundaries Setting boundaries is the first step in managing stress. In a world that expects you to always be available, define your work hours. Let your colleagues know when you are available, and stick to that schedule. When you decide when to stop working, make sure you follow through. This may mean turning off notifications or avoiding emails after work hours. Taking breaks throughout the day is also crucial. Short breaks can increase your productivity and clear your mind. Use these moments to move away from your desk, go for a walk, or take deep breaths. These small pauses can ...
AI illustration of a professional woman taking a relaxing stretch break at her desk to reduce work stress and fatigue in a bright office.


Leave a Reply

Your email address will not be published. Required fields are marked *