





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Aug 31, 2026
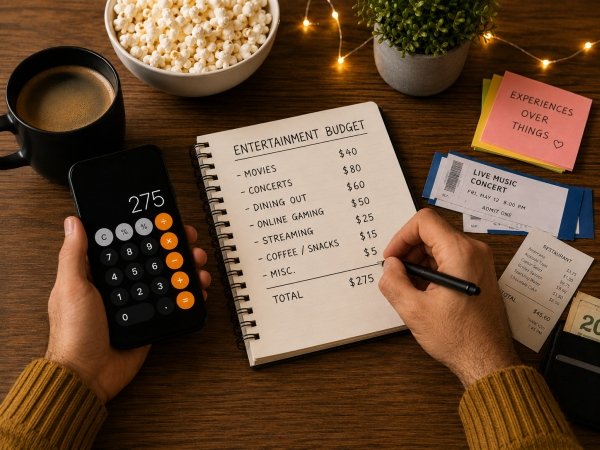
Money's been on my mind recently. Not in that anxiety-spiral way where you check your bank account at 2am, but this quiet realization that maybe I should know where my paycheck actually goes.
Last month I tracked every dollar I spent on fun stuff for 30 days. Movies, streaming subscriptions, nights out, concert tickets, all of it. The final number: $387.42. When I looked at that spreadsheet, I couldn't remember what half those charges were for. What's the point of spending money on entertainment if it vanishes from memory within two weeks?
I started approaching entertainment differently. Not cutting everything fun out, but actually thinking about what I was doing with my money instead of letting it evaporate.
I didn't create some elaborate system. After obsessing over my spending patterns, I noticed something. The weeks where I felt genuinely good about how I'd spent my time and money? Pretty much always came out between $50 and $65. Not $100, not $20, just that range where I'd actually done something worth remembering without that guilty feeling.
Usually broke down like this: one planned thing with friends costing $25 to $30, small daily stuff like grabbing coffee or buying a book adding up to $15 or $20, plus one spontaneous decision for another $10 to $15.
This magic number doesn't work for everyone. Your sweet spot might be $30 or $100 depending on where you live, what you earn, and what brings you joy. But having an actual number instead of vibes-based spending helps you make better choices in the moment.
I started investing 10 minutes researching before spending money on something. When I was considering trying a new platform (like when I checked out Rex Bet after my friend wouldn't shut up about it), I actually looked at what they offered instead of just creating an account and hoping for the best. New restaurant? I'd glance at menu prices first.
Doing that research didn't kill spontaneity like I thought it would. It made spontaneous decisions better because when I did something on impulse, I was way more likely to genuinely enjoy it instead of feeling like I'd wasted money.
Anything over $75 gets a two-day waiting period. That's it.
I wait 48 hours before buying it, and you'd be shocked how many times something I absolutely needed to have right that second completely disappeared from my brain after two days. Still thinking about that $89 blender I almost bought at 11pm on a Tuesday that I've never thought about since.
The stuff I still wanted after waiting? Those purchases turned out to be worth it almost every time. I noticed they were usually experiences instead of things, which bring way more lasting happiness anyway.
I'm not spending dramatically less money now. Some months I actually spend more than my old average. But the difference is I can tell you exactly where that money went and why. I remember the comedy show I saw three weeks ago because I actively chose it instead of defaulting to whatever required the least thought.
My whole relationship with my entertainment budget changed. Stopped being about restricting myself or feeling guilty, started being about actually being present for the experiences I was paying for instead of mindlessly swiping my card and wondering where my paycheck vanished to.
Pretty small shift when you think about it. Made a massive difference though.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
August 24, 2026 | NCFA Insight | SME Finance And Business Banking, Cross Border Payments And FX, Competition And Market Structure, Public Sector Policy And Industrial Strategy
On August 24, 2026, Canada-U.S. trade negotiations had collapsed with new 50% U.S. tariffs on certain Canadian products already in force from August 22. President Donald Trump then threatened to raise new additional 50% tariffs on all Canadian cars, trucks and auto parts beginning January 1, 2027. Canada plans retaliatory tariffs on some U.S. goods beginning September 8.
The breakdown adds fresh urgency to Canada’s push to build more trade outside the U.S. The federal government is already tilting export support in that direction. CanExport SMEs has approximately $31 million available for 2026 and 2027, with about $27.9 million available for non-U.S. market activities and $3.1 million for U.S. projects. The program says the allocation supports Canada’s objective of doubling non-U.S. exports over the next decade.
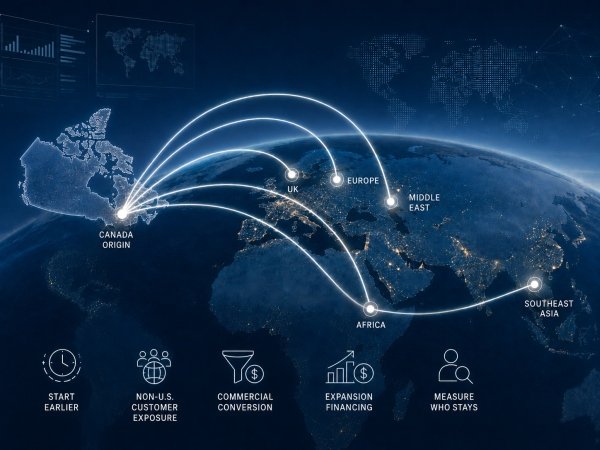
For fintech, software and other digital firms, the problem is how quickly Canadian companies can turn access to a foreign market into customers and recurring revenue. Europe, the UK, Singapore, Southeast Asia, Latin America, Africa and the Middle East already have local firms and international competitors with licences, integrations, distribution, customer relationships and years of operating experience.
Statistics Canada reported $70.3 billion of digitally delivered commercial services exports in 2023. Large firms increased those exports by 20.1%, while small and medium sized firms recorded a 7.6% decline. Canadian multinationals increased commercial services exports outside the U.S. by 21%, compared with 6.6% growth to the U.S. They also accounted for 75% of the increase in Canadian commercial services exports to non-U.S. markets.
NCFA's earlier digital export comparison shows Singapore ahead of Canada despite operating from a far smaller domestic economy. Singapore ranked 11th globally in the underlying 2023 data at US$153 billion, compared with Canada in 16th place at US$118 billion.
Canada doesn't just need another list of markets to enter. It needs more startups and SMEs able to win non-U.S. customers faster and build businesses that can keep competing once they get there.
Canada already has substantial export infrastructure. The Trade Commissioner Service connects companies with customers, partners and investors. Canadian Technology Accelerators provide business development support, strategic guidance and local introductions. CanExport reduces part of the cost of entering new markets, while Export Development Canada's Trade Impact Program provides financing, working capital, guarantees and credit insurance to companies dealing with trade uncertainty.
The Canadian Technology Accelerator also produces measurable results. A Global Affairs study found participating firms had 27% higher revenue one year after completing the program than otherwise similar companies. The positive differences in revenue, assets and payroll became larger over the following years.
But Global Affairs could not determine how much the firms actually became more international because the available data were insufficient. That leaves the commercial outcome Canada now needs to understand. How many firms supported expansion into London, Singapore or another non-U.S. market are still generating recurring revenue there two, three or five years later?
Canadian fintech history shows why market entry alone is a weak measure. Wealthsimple built a UK business for almost five years and reached about 16,000 customers before selling the operation and concentrating on Canada. Clearco expanded into several overseas markets before transferring its international business to Outfund as ecommerce growth slowed and financing conditions deteriorated.
Neither case proves Canadian fintechs cannot compete abroad. They show how demanding a foreign operation becomes when a company has to fund customer acquisition, staff, compliance, banking relationships, treasury, tax and product adaptation while continuing to compete at home.
VoPay is using another model. The Vancouver founded payments infrastructure company established a global headquarters in Doha in January 2026 while keeping its Canadian operations active. Qatar is being built as a major hub for expansion across the Middle East, Africa and Southeast Asia, with more than 400 planned hires across engineering, technology, security, compliance, data and platform operations. The company didn't abandon Canada, but a meaningful part of its next stage of international capability is being built outside the country.
For Canada, it's not a simple win or loss. VoPay remains rooted in Canada while using Qatar as a launch point into several non-U.S. regions. Using a regional hub can also reduce expansion risk by putting management and operating capability closer to target markets while the Canadian core continues to run. The policy question is where the next layer of technical talent, management, partnerships and enterprise value accumulates as Canadian companies expand internationally.
The U.S. capital pull starts much earlier. NCFA's productive participation analysis examined the Canadian founder drain into the U.S. technology ecosystem. Barn Ventures describes a founder conveyor in which U.S. investors and programs recruit Canadian talent from high school and university through company formation and later scale.
Barn's analysis of the Dominion List found 517 U.S. based companies with a Canadian founder had raised about US$414 billion. It found 73% headquartered in California and 56% in San Francisco. Barn also found the number of listed companies founded each year rose sharply after 2022, while acknowledging that the Dominion List is a curated catalogue rather than a census.
Large U.S. capital markets and Silicon Valley's technology ecosystem will always attract ambitious Canadian founders. Those organizations are doing what successful capital markets do. The Canadian problem becomes more serious when founders also conclude they need to leave to get the capital, customers, infrastructure or operating environment required to build a major company. Canada can then lose value at both ends. Some promising founders build in the U.S. before substantial enterprise value accumulates here.
Also, Canada's main export programs generally engage firms after they have built meaningful operating capacity or market traction. By then, their products, sales models and management experience may already have been shaped largely around Canada and the U.S., while competitors in non-U.S. markets have spent years building customers and local experience. That is why promising firms should encounter non-U.S. customers, regulators and market requirements earlier, before they reach the stage where most formal export support begins.
Financial infrastructure can add to that timing gap. NCFA's financial infrastructure history shows Canadian fintechs developing while Real-Time Rail, wider payments access and regulated consumer driven banking arrived multiple years later than comparable infrastructure in several major fintech markets.
That does not explain Wealthsimple's UK exit, Clearco's retrenchment or any other individual company decision. It also affects what Canadian firms learn at home. Years of working with real time payments, portable financial data, modern APIs and digital onboarding build practical experience that can help when companies expand into other markets.
If Canadian firms gain important financial capabilities later, they also have less time to turn them into competitive advantages before entering non-U.S. markets.
The quickest response to Canada's urgent need to diversify beyond the U.S. is not more export information. Canada already has market intelligence, trade commissioners, financing programs and buyer introductions. The priority is to shorten the time between choosing a non-U.S. market and winning recurring revenue there. Canada can do many things differently to help achieve this.
1. Start earlier. Promising fintech and digital companies should encounter non-U.S. customers, regulators and financial institutions while their products are still developing. This doesn't mean sending every startup overseas. It means finding companies with strong technology and real differentiation early enough that requirements in several jurisdictions can influence what they build.
A company that learns to work across several payment systems, data rules, onboarding requirements and regulatory environments before reaching scale develops a different skill set from one encountering that complexity for the first time after years focused on Canada and the U.S.
2. Push buyer introductions toward commercial conversion. Canada already connects companies with qualified contacts, potential customers and partners. But they need to track and measure how consistently those introductions turn into technical evaluations, paid pilots, contracts and recurring revenue. Trade Commissioners in priority non-U.S. markets are well placed to identify concrete buyer needs and concentrate Canadian firms with relevant products against those opportunities.
That also creates better intelligence. If Canadian fintechs repeatedly lose the same types of opportunities in London, Singapore or São Paulo, Canada can determine whether the problem is product fit, pricing, licensing, procurement, financing or a capability competitors already possess.
3. Finance the period between market entry and recurring revenue. CanExport can provide up to $50,000 toward eligible international business development costs. EDC's Trade Impact Program has up to $5 billion of additional capacity over two years and supports working capital, guarantees, credit insurance and other financing tools. Those tools become more useful when they are organized around the economics of a specific foreign operation. Customer acquisition, regulatory work, FX, payments, local staff and management time can absorb capital before a new market supports itself.
For regulated fintechs, entering another country is like building a second company while the first keeps operating. Management needs to know what the foreign operation costs, what milestones justify further investment and when the economics no longer support continued expansion. That discipline protects the Canadian core while giving a promising foreign business enough runway to prove itself.
4. Measure whether companies win and stay. Canada should track the time from choosing a non-U.S. market to the first paying customer, how many assisted firms develop recurring revenue and how many are still operating there after two, three and five years.
The same scorecard can track local licences, staff and operating entities alongside the value that remains anchored in Canada. That includes Canadian employment, management functions, intellectual property, investment and capital recycled into the next generation of companies.
Those results would expose the bottlenecks quickly. A firm that receives many introductions but cannot win customers has a different problem from one that wins customers but cannot finance its expansion. A company delayed by licensing, payments or compliance needs a different response again.
Canada's non-U.S. diversification push became urgent much faster than companies can build international experience. The fastest response is therefore partly to start earlier.
Then judge success by whether Canadian companies are winning customers outside the U.S., staying in those markets and keeping enough of the resulting value anchored in Canada.
Canada now needs to diversify beyond the U.S. faster than many of its technology companies have historically expanded internationally. Can it help promising fintechs build non-U.S. customers and operating experience early enough to win against established competitors while keeping more of the resulting enterprise value anchored in Canada?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 13, 2026 | NCFA Insight | Artificial Intelligence And Data, Competition And Market Structure, Public Sector Policy And Industrial Strategy

On August 10, 2026, Meta published The Future Is For Everyone, Mark Zuckerberg's wide sweeping proposal for how superintelligence should fit into society.
The central idea is personal empowerment. Zuckerberg argues that advanced AI should give individuals more ability to create, learn, build businesses, improve their health and pursue their own goals rather than placing most of that intelligence under the control of governments, large institutions or a handful of AI companies.
Meta's vision imagines personal agents working continuously on a user's behalf, small teams building companies that once required much larger organizations, personalized tutors, faster scientific discovery and powerful creative tools available to billions of people.
Meta wants AI capability spread widely, while the compute, models, release decisions and government relationships needed to provide it remain concentrated among a handful of organizations.
Mark Zuckerberg, Founder and CEO, Meta:
“The defining questions of our age are who will have access to superintelligence and what will we direct it towards.”
One of Zuckerberg's strongest economic arguments is that AI's biggest contribution could come from helping people invent things rather than simply automating today's jobs.
Meta expects individuals to become capable of doing work that currently requires larger teams, more capital or specialized expertise. Zuckerberg predicts more small businesses, more experimentation and potentially more employment as people use AI to create products, services and jobs that don't exist today.
That is a different vision from a future where AI mainly replaces knowledge work. Meta argues that if personal agents increase people's capabilities quickly enough, workers can adapt and new demand can grow alongside automation.
For founders, that could change the economics of starting a company. Product development, research, design, marketing and operations could require fewer people and less initial capital. Small firms could reach meaningful scale much earlier.
Financial services will feel the same pressure. Meta already has AI that can plan work, connect with email and calendars and continue tasks after the user leaves. As agents gain access to financial information and connected services, permissions and accountability become part of the operating model, especially when an agent can act rather than simply advise.
The more unusual part of Zuckerberg's argument is about safety.
He rejects the idea that one centrally controlled superintelligence can be aligned to a single set of values that works for everyone. People disagree about politics, economics, culture and what makes a good life.
Meta's answer is to distribute powerful AI widely enough that people, businesses, governments and competing AI systems check one another.
It is essentially a balance of power argument. One person with vastly better legal, financial or cybersecurity intelligence could gain an enormous advantage. If many people have access to comparable capabilities, Meta argues that power becomes harder to monopolize. (There’s some irony here. Zuckerberg built his fortune by controlling access to data, distribution and network effects that others couldn’t easily replicate.)
That philosophy also influences Meta's approach to alignment. Personal agents should primarily help users pursue their own goals within legal and safety boundaries rather than enforce one company's view of what those goals should be.
Meta says it plans to build a private mode where even Meta can't access a user's information, and it intends to resume releasing some open models. It is also giving its independent board authority to approve safety criteria for model releases rather than leaving those decisions entirely with Zuckerberg or management.
Meta's existing algorithmic products are already under legal scrutiny, including a federal trial involving 29 U.S. states over alleged harm to children. Meta denies the allegations. A company asking people to trust far more capable personal agents will have to show that user empowerment, privacy and safety work in practice. Algorithmic accountability is already moving into the courts as AI and automated systems take on a larger role in people's lives.
Zuckerberg's decentralization argument has limits.
He wants individuals to have broad access to powerful AI, but he also argues that the United States and its allies should retain leadership in advanced models, silicon and infrastructure. Meta supports continued restrictions on exports of leading chips to geopolitical rivals and wants U.S. policy to make it easier to build data centres and energy capacity.
He also proposes closer cooperation between frontier AI labs and government. Rather than waiting until an advanced model is finished, Meta wants labs to share intermediate model checkpoints and technical staff so governments can identify cybersecurity and other security risks earlier.
The result still leaves considerable power with governments, frontier labs and the companies that control advanced compute. Individuals would gain far more capability. Governments would receive earlier access for security purposes. Independent boards would get more authority over release standards. Frontier labs would still control development of the most capable models.
Meta's vision is therefore decentralized at the user level while retaining substantial institutional coordination at the frontier.
Meta expects capital spending of US$130 billion to US$145 billion in 2026 and spent US$31.08 billion in the second quarter alone. It is investing in models, data centres, energy, networking, its own chips and outside accelerators while trying to deliver AI across products already used by billions of people.
If personal superintelligence is going to be free or affordable at global scale, someone still has to pay for the compute..
Meta wants superintelligence broadly distributed, but scarce compute still has to be allocated. Its answer is a dynamic auction for additional capacity, which means the vision of AI for everyone could still produce tiers of access based partly on what users can afford. (conflict?)
The business model hasn't been proven. Meta's second quarter free cash flow fell to US$784 million as infrastructure spending accelerated, even while its core advertising business remained highly profitable.
Meta is making these commitments under real pressure. Its infrastructure spending has climbed rapidly, the company is still building the compute capacity and custom chips needed to compete at the frontier, and its existing platforms face growing legal scrutiny.
The scale of the investment also reinforces a central tension in Zuckerberg's vision. Meta wants personal AI to give individuals more power, but only a small number of companies can currently finance the systems needed to provide it.
Meta's vision has clear upside for Canada.
Canadian entrepreneurs, researchers and smaller businesses could gain access to capabilities they would never be able to finance themselves. If AI lowers the cost of creating companies, learning new skills and developing new products, a smaller economy can participate without matching U.S. frontier model spending dollar for dollar.
Canada is already debating how to keep more domestic intellectual property, capital and compute capacity while using global AI platforms. The country's AI sovereignty debate is partly about preserving enough domestic capability to avoid becoming only a customer of technology developed and controlled elsewhere.
A recent pro-human AI initiative backed by researchers, business and labour groups also argues for human agency, limits on concentrated power and accountability for AI companies. Zuckerberg reaches some similar principles from a very different starting point.
Canada needs enough choice, competition, data control and domestic capability for its companies and citizens to use increasingly powerful AI on their own terms.
Zuckerberg's bet is that superintelligence can give individuals more power to learn, invent, work and build. Meta has the reach and financial capacity to put that idea in front of billions of people. The cost of doing so is already putting heavy pressure on cash flow.Whether users ultimately gain more control will depend on who controls the models, data, compute and rules behind their personal AI.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 20, 2026 | NCFA Resource | Risk Compliance And Regtech, Artificial Intelligence And Data

On June 18, 2026, IOSCO published a Supervisory Tech (SupTech) report called 'Mapping the Use of Technology in Financial Supervision', a global survey of 49 authorities on how regulators are using technology to improve financial supervision. The report maps where SupTech is already being used, what is driving adoption, and which barriers are slowing progress.
SupTech is becoming part of regular ongoing supervision, and is no longer an experiment. Regulators are using technology to improve efficiency, receive and analyze information faster, and strengthen oversight across investor protection, market conduct, capital markets, and emerging areas such as digital assets.
The report gives regulators, fintech firms, and regtech providers a global benchmark for how supervisory technology is being adopted. It covers strategy, budgets, leadership, data, cloud infrastructure, AI, cybersecurity, digital assets, cooperation, and workforce planning.
IOSCO found that efficiency is the main driver of SupTech adoption, followed by faster access to information and stronger supervisory capabilities. AI applications, improved data access, and cloud infrastructure are the leading technology enablers.
Consumer and investor protection and capital markets supervision are the most developed use cases. Digital assets are less mature today, but interest is rising. That gap matters because market activity is moving faster than many supervisory tools.
The report also shows why implementation is hard. Cyber risk, third party dependencies, operational risk, funding gaps, and skills shortages remain major constraints. Many authorities have strategies under way, but full implementation is still uneven.
This resource is useful for securities regulators, policy teams, regtech firms, fintech compliance teams, financial institutions, digital asset platforms, market surveillance teams, and researchers tracking regulatory modernization.
It is especially useful for organizations building or assessing tools for market monitoring, fraud detection, complaints analysis, digital asset oversight, supervisory analytics, data collection, and AI enabled supervision.
The strength of this resource is its global scope. The survey covers authorities across all IOSCO regions and gives readers a baseline for comparing SupTech maturity, priorities, and constraints.
It is also useful because it avoids hype. The report shows that many regulators are still using mid level technologies and practical tools. Advanced analytics and machine learning are important ambitions, but funding and implementation capacity remain real limits.
The limit is that it's survey based, not a product guide. It doesn't rank vendors, provide implementation playbooks, or prove which tools produce the best supervisory outcomes. Its value is in the benchmark, the use cases, and the policy signals.
IOSCO SupTech Report (primary report)
IOSCO SupTech Media Release (announcement summary)
AI Agents Enter Governed Financial Workflows (AI governance and controls)
MIT AI Risk Repository For Fintech Governance (AI risk taxonomy resource)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 2, 2026 | NCFA Resource | Artificial Intelligence And Data

On June 2, 2026, the Bank of Canada published Canadian firm AI adoption survey data from its December 2025 Business Leaders’ Pulse. The research gives fintechs, investors, financial institutions, regulators, and policy teams a useful benchmark for assessing where Canadian businesses stand on AI use, deployment, capital spending, and employment expectations.
The resource draws on 314 firm responses. It separates personal AI use by business leaders from operational AI use inside firms. Many Canadian leaders already use AI at work, but fewer firms use AI in production, service delivery, or core business workflows.
The research helps readers compare AI awareness with real deployment:
The Bank of Canada also shows where AI use starts. Text generation ranks as the most common current application. Visual content creation and machine learning based data processing follow. Over the next three years, firms expect more use of data processing applications, which may matter more for financial services than basic content generation.
For fintechs and financial institutions, AI awareness no longer creates differentiation on its own. The harder work involves choosing real workflows, testing productivity gains, managing risk, training staff, improving data quality, and deciding where AI deserves capital spending.
Fintech founders can use the paper to test whether customer demand has reached live deployment or is still stuck in pilot mode. That helps product teams avoid building around hype alone.
Investors can use the data to assess where demand may grow for AI governance tools, workflow automation, data infrastructure, compliance technology, customer service systems, and implementation support.
Financial institutions can compare their own AI programs against broader Canadian firm expectations. The paper gives banks, credit unions, insurers, and wealth firms a clearer view of how business leaders think about investment and employment effects over the next year and the next three years.
Regulators and policymakers can use the paper to understand practical adoption barriers. Firms that do not use AI most often cite lack of usefulness for their operations. Other barriers include skills, software compatibility, ethics, cost, regulatory obstacles, and data quality.
The strength of this resource is its Canadian evidence base. It also separates personal AI use from business deployment, which makes the adoption picture more useful.
The paper also connects AI adoption with capital spending and employment expectations. Firms expect AI to have a more positive effect on capital expenditures over three years than over the next 12 months. Employment expectations look more cautious. Over three years, 18% of firms expect to hire fewer staff because of AI, while 9% expect to hire more.
The limit is survey design. The Business Leaders’ Pulse helps assess aggregate economic conditions relevant to Canadian GDP. It doesn't produce population representative estimates of firm behaviour. Readers should treat the results as useful directional evidence, not a full census of Canadian AI adoption.
Bank of Canada AI adoption survey (primary staff analytical paper on firm AI adoption, capital spending, and employment expectations)
Bank of Canada central banking AI resource (resource on AI adoption inside central banking and controlled deployment)
Canada AI productivity analysis (analysis on AI adoption, productivity, capital, and execution)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 22, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization, Regulation And Policy, Capital Formation And Venture Markets

Image: Hester Peirce (aka Crypto Mom)
On May 21, 2026, reports confirmed that SEC Commissioner Hester Peirce will leave the U.S. Securities and Exchange Commission later this year to join Regent University School of Law, closing one of the most closely watched regulatory tenures in digital asset policy.
Peirce became affectionately known globally as “Crypto Mom” because she consistently argued that regulators should give digital asset markets workable rules instead of leaving companies to operate inside uncertainty. Her positions moved from controversial to increasingly mainstream as spot bitcoin ETFs launched, tokenization expanded, and major financial institutions entered digital asset infrastructure.
Her departure doesn't mean pro crypto or pro innovation momentum suddenly disappears from Washington. Digital assets no longer depend on a single regulator defending the sector. Bitcoin ETFs now trade in regulated markets. Large banks are building tokenization infrastructure. Stablecoin legislation continues advancing across major jurisdictions. Institutional adoption no longer sits at the fringe.
Still, Peirce leaves behind a clear regulatory record.
For years, she pushed back against regulation through enforcement. She argued that uncertainty weakens both innovation and investor protection because companies struggle to build compliant products when the rules remain unclear.
Many of the issues she raised directly affected fintech competition, startup capital formation, tokenization, crowdfunding, and investor participation. Her speeches consistently returned to the same core themes, such as open markets, proportional regulation, investor choice, and transparent rulemaking.
Peirce’s bluntest critique came during the long debate over regulation through enforcement, where she warned that private meetings with crypto firms cannot replace open rulemaking:
“It’s just not a good way of regulating.”
Her frustration with the SEC’s long delay on spot bitcoin funds became even clearer when spot bitcoin ETFs finally won approval after years of rejected applications:
“We squandered a decade of opportunities to do our job.”
Peirce’s Token Safe Harbor proposal became one of the most discussed crypto policy frameworks because it tried to give blockchain networks time to decentralize before full securities obligations applied.
Her public rulemaking philosophy also stood out in her University of Central Florida FinTech Summit remarks, where she urged regulators to approach innovation with both skepticism and openness instead of reflexive resistance. She later warned that poor engagement damages the relationship between regulators and innovators:
“We are scaring people off from coming in and having a conversation with us.”
Even when she defended innovation, Peirce did not argue for eliminating rules. In her statement on tokenized securities, she welcomed the promise of blockchain while drawing a hard compliance line:
“Tokenization may facilitate capital formation and enhance investors’ ability to use their assets as collateral.”
She also added the part many crypto promoters prefer to skip:
“Tokenized securities are still securities.”
That balance partly explains why Peirce maintained credibility across crypto markets and traditional finance circles. She supported innovation, but she also believed markets work best when participants understand the rules.
Her influence reached beyond crypto. Peirce consistently supported broader access to capital markets, regulatory transparency, and competition for smaller firms. Those priorities aligned closely with long standing NCFA positions on equity crowdfunding and capital markets modernization, fintech competitiveness, and proportional regulation for emerging companies.
Very few SEC commissioners become recognizable public figures outside securities law circles. Peirce did because she represented a different philosophy of regulation during one of the most contested periods in financial technology policy.
Her departure closes an important chapter at the SEC. But the larger debates around tokenization, digital asset infrastructure, market access, and programmable finance are now deeply embedded across global financial systems. Those discussions continue with or without Crypto Mom inside the building.
Peirce also engaged directly with the broader fintech and innovation community over the years, including participating in NCFA’s FFCON21: Breaking Barriers program.
On behalf of everyone at NCFA, we thank Hester Peirce for consistently contributing to open debate around innovation, competition, investor choice, and access to capital during one of the most important periods in modern financial market development. We wish her continued success in this next chapter.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 21, 2026 | NCFA Insight | Capital Markets And Funding

On December 4, 2025, the European Commission published its market infrastructure reform package, including proposed changes to the DLT Pilot Regime. On March 19, 2026, the European Digital Finance Association (EDFA) sent a formal letter to the European Commission about the DLT Pilot Regime and MiCAR. It is addressed to Commissioner Maria Luís Albuquerque and DG FISMA Director-General John Berrigan.
EDFA writes on behalf of its members and the undersigned companies. The core point is that the pilot works for testing, but it does not work for scale. Firms are already trying to build tokenized issuance, trading, registry, custody, and settlement in Europe. The problem is that the current DLT Pilot rules keep those activities small, separate, and hard to repeat.
The issue is structural. The DLT Pilot allows firms to test tokenized issuance, trading, and settlement in controlled conditions. But it doesn't allow those activities to operate at scale. Issuance happens, but it stays small. Trading exists, but liquidity doesn't build. Infrastructure is in place, but it doesn't connect cleanly to the rest of the market. Until those limits are addressed, tokenized securities remain confined to pilot activity instead of forming a market where deals can regularly happen at meaningful scale.
If Brussels makes these changes, firms can issue larger deals and do it more than once. Tokenized platforms can connect to exchanges, custodians, and settlement systems instead of running separately. Companies already licensed at the national level can keep operating instead of being pushed out. And with clear settlement rules, those deals can actually trade and attract real liquidity.
If Brussels does not act, the likely outcome is also clear. Europe will keep producing tokenized deals as part of the DLT pilot, but the market will remain shallow and less commercially important. Operators will keep building, but they will be outwardly looking at jurisdictions that allow larger, cleaner, and more continuous activity.
The DLT Pilot was designed for controlled testing, and has done that. The question now is whether the framework evolves to support real market activity. If it doesn’t, tokenized securities will stay limited to small, controlled use cases. If it does, they can develop into a market with real issuance, trading, and liquidity.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
