




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Nov 9, 2026
By Chris Maranis, Deputy CEO, EXUS
Financial services has spent years making the decision to approve a loan faster and more informed. AI is part of that progress. As NCFA’s coverage of AI loan decisioning shows, lenders are finding new ways to verify information and assess risk at origination.
But approval is one decision on one day. Collections deals with what happens on all the other days. A customer’s circumstances can change many times before the debt is repaid. What happens when income drops, a payment is missed or a customer stops responding? Those decisions belong to debt collections, and they deserve just as much intelligence.
After more than twenty years working in collections, this is where I think AI gets interesting. Not because it can automate more for the sake of it, but because it can help teams choose a better next action while giving collectors the time and context to handle situations that need human judgement.
Collections teams have always had to prioritise. The difficulty is that a delinquency bucket is not a person. Two accounts in the same bucket can belong to people in very different circumstances. One customer may have forgotten a payment. Another may be struggling to meet several obligations. Treating them identically can waste effort and, more importantly, miss the chance to offer useful support.
AI can help teams assess a broader set of signals: payment behaviour, risk, engagement, affordability information where available, and the results of previous contact. But the point is not to produce a cleverer score. It is to decide who needs attention, when to make contact, through which channel and with which treatment.
A prediction without a policy is just a prediction. It cannot tell a lender what is appropriate for a customer. It has to lead to an action the institution can explain, monitor and change when circumstances change.
This matters in Canada, where the Bank of Canada’s 2026 assessment of households describes resilience overall alongside pockets of greater financial pressure. A portfolio average cannot tell a collections team which customer needs a reminder, which needs a different repayment path and which needs a conversation.
One thing technology should do is make the human conversation better. For a collector speaking with a customer, a concise view of account history, previous interactions and available options can turn a difficult conversation into a more informed one. AI’s role does not end when it recommends the next action.
Imagine a customer who has started, but not completed, a digital repayment journey. If they call for help, the collector should be able to see where they stopped and what options they saw. Asking the customer to explain everything again while the collector searches across systems is friction we should be able to design out.
AI can help assemble that context, prioritise work and suggest actions within a lender’s policy. The collector still has to listen. That matters. A customer disputing a balance, describing hardship or explaining a change in circumstances may reveal something the data did not capture. In that moment, the system’s job is to support judgement and make an appropriate handoff possible.
For me, the design question is simple to ask and difficult to answer: where should AI decide, where should it recommend, and when should a person step in? The objective is not to automate the maximum possible amount of the process. It is to automate where appropriate and preserve judgement where it matters.
Those boundaries cannot live only in a policy document. They should be visible in the workflow. Teams need to know what information informed a recommendation, what policy applies, how an exception is handled and whether different groups of customers are receiving appropriate treatment. They also need to test what happens after an action: did the customer engage, was an arrangement maintained, and did the intervention help resolve the difficulty?
Canadian expectations make this more than a theoretical exercise. For federally regulated financial institutions dealing with mortgage customers at risk in exceptional circumstances, the Financial Consumer Agency of Canada’s guideline addresses early identification, proactive contact and appropriate, individualised relief. Technology can help carry out a lender’s policies, but the lender remains responsible for the treatment customers receive.
At EXUS, we focus on connecting collections decision intelligence to the work teams actually do. As we have also discussed in our guide to governing collections AI, the useful starting point is the customer outcome and the specific decision AI will influence.
Activity is easy to count. Outcomes are harder. They are also the point. Automated messages, completed tasks and contacts made say little on their own about whether collections is working better.
A stronger test asks whether customers reached a suitable option, whether repayment arrangements lasted, whether complex cases reached trained staff promptly, and whether the lender improved recovery without adding avoidable friction or cost. Those are harder measures, but they tell you whether the operating model is actually improving. And they should inform the next round of decisions.
AI can make collections more responsive as a customer’s situation changes. But it cannot rescue a weak operating model. The value comes from the whole system: sound signals, clear policy, useful digital journeys, supported collectors and a willingness to learn from outcomes.
A customer’s circumstances can change overnight. The collections operation has to keep up. Across thousands or millions of accounts, the challenge is turning that change into the right response by connecting data, policy, digital channels and collectors without losing sight of the person behind each case.
That is the standard I would use for any collections technology, including our own at EXUS: when a customer needs a different response, can the organisation recognise it, deliver it in time and show that it worked? AI-driven decisioning can help guide the next action, and people need the context to handle the cases that require judgement. The technology matters. The outcome matters more.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |

Yes. A Canadian bank can block a personal AI agent from entering its protected banking systems even when the customer wants to use it. Customer consent doesn't give outside software automatic access to the bank's login, website or app. RBC confirmed direct restrictions on October 28. TD, BMO, CIBC and Scotiabank have also described restrictions, although their policies differ.
That doesn't mean banks are shutting AI out of finance. Questrade already offers controlled AI connections to brokerage accounts, while Visa is testing agent initiated payments with five major Canadian banks. An agent using a customer's login is not the same as an institution granting that agent specific authority. Canada's consumer directed banking framework could widen approved data access, but it does not automatically authorize AI agents to move money.
Click each item to expand
RBC says direct access by third party personal AI agents to its authenticated digital properties is blocked. It also warns that existing connections will stop working. The restriction concerns an outside agent entering protected banking services.
A customer granting permission to an AI assistant is not the same as RBC approving that assistant as a trusted system participant.
TD, BMO, CIBC and Scotiabank have described restrictions on outside agents accessing protected banking channels. National Bank has discussed monitoring the technology rather than announcing an equivalent block. The policies should not be presented as identical.
The distinction is between uncontrolled use of a customer session and an approved integration with defined permissions.
Customers authenticate directly with Questrade to authorize supported AI tools. Read permissions can expose balances, positions and account activity. Trading access is separate, and the customer reviews and approves an order before submission through the MCP connection.
This operating example separates access to information from authority to execute an investment order.
Visa names BMO, CIBC, RBC, Scotiabank and TD as early Canadian participants in Agentic Ready. The program tests agent identity, tokenization, authentication and transaction authorization through payment infrastructure.
Banks can restrict unknown agents from online banking while testing approved transaction channels. The pilot is not a general consumer access entitlement.
TD says a mortgage process that previously averaged about 15 hours can be completed in less than three minutes using its controlled agentic workflow. This is a bank operated use case, not outside customer agent access.
The distinction reinforces that institutional use of AI and third party access policy are separate decisions.
Forrester describes consumer distrust and security concerns around AI access to financial information. The article should not treat those survey findings as a vote against all agent services.
Trust depends on whether customers understand what the agent can see, what it can do and how to withdraw authority.
Click each item to expand
Finance Canada estimates that roughly nine million Canadians use credential based financial data sharing. The planned framework covers participant accreditation, consent and secure data exchange.
The initial framework concerns data access. It does not give every personal AI agent a right to enter a bank or initiate a payment.
Payments Canada calls for clarity on liability, fraud controls, accountability and dispute resolution as Canada considers write access. Its recommendations distinguish data sharing from instructions that move funds.
The question of which agents can act, and under whose authority, remains open beyond the initial data access framework.
RBC's October 28 notice is explicit. The bank blocks third party personal AI agents from direct access to authenticated RBC digital properties, including online banking. It says existing agent connections will stop working. RBC cites risks involving credentials, fraud and consumer harm. The restriction concerns how an outside agent enters protected services, not whether RBC can use AI within its own operations.
TD says it blocks third party personal AI agents from authenticated banking information while it develops appropriate safeguards. CIBC says it does not support personal agents directly opening or accessing accounts. Scotiabank says it will limit access by outside agents. Statements reported on October 28 document these differences. These are not identical policies, and they do not establish an industry wide ban on approved AI integrations.
A customer may trust an AI assistant to compare fees, monitor cash flow or prepare a payment. The bank still needs to know whether the software is entitled to enter its systems. A valid customer password doesn't answer that question. It identifies the account holder's credentials, not necessarily the outside program using them.
Yes, when the institution provides an approved connection. With credential access, outside software uses the customer's login or authenticated session. With delegated access, the customer signs in directly with the institution and grants a separate connection limited permissions. The institution can then control what the outside service sees or does, and the customer can revoke future access.
Questrade's AI connection offers a working Canadian example. Customers can connect supported assistants through its Model Context Protocol server. They authenticate on Questrade's own login page, so the AI agent doesn't receive the account password. The connection can read balances, positions, orders and account activity. Questrade says order and activity history available through the connection covers the previous 90 days. Trading permissions are granted separately.
Under Questrade’s MCP trading connection, an agent can draft an order, but the customer must approve it before submission. The agent cannot independently place, change or cancel an order through that connection. Questrade also offers Flows, which create rules for trades and alerts. Its current MCP guide says customers review and approve each order before submission. Revoking an AI connection stops future access but does not retrieve data already shared with the AI provider. Read permission, trade approval and standing automation authority are three different controls.
Reading an account and moving money are different powers. An assistant that summarizes a balance does not automatically have authority to transfer $5,000. Questrade lets users grant read access separately from trade permission. Its MCP connection requires approval for each drafted trade. Its separate Flows functionality supports customer defined trading rules, with order approvals described in its current MCP guide. Investors need to understand which permission they are granting, not just which AI assistant they are connecting.
Payments are developing through another route. On May 5, Visa announced its Canadian Agentic Ready program to test payments initiated by AI agents in controlled environments. Its five early Canadian issuing partners are BMO, CIBC, RBC, Scotiabank and TD. The tests cover card enrollment, tokenization, authentication and transaction authorization using live cards and merchants.
Some of those same banks are restricting outside agents from their ordinary digital banking channels. There's no inconsistency in the operating model. A bank can refuse an unknown program's attempt to enter a customer's online banking session while testing a payment process that identifies the agent and validates each transaction. Visa's program is a test environment, however, not proof that every customer can already instruct a general purpose AI assistant to make payments through those banks.
Not by itself. Canada’s consumer directed banking framework is being implemented to let people share financial information with approved providers through secure connections. It does not give any personal AI agent an unrestricted right to enter a bank account. Nor does the initial data sharing phase authorize an agent to make payments or trades. Finance Canada said in June that proposed regulations would come into force in stages, beginning with accreditation. The Bank of Canada is developing oversight for participating firms.
Finance Canada estimates that approximately nine million Canadians currently share financial data through screen scraping. The framework aims to replace credential sharing with authorized API connections. Its published design includes accreditation, consent, data security and rules for liability when data is shared. The Financial Consumer Agency of Canada describes how customers would select what information to share, with whom and for how long.
Yes, if the agent is trying to use an unsupported access route or is not an approved participant. Under the planned framework, participating banks will have data sharing obligations to eligible participants acting on customer instructions. That's different from a duty to accept any software the customer chooses. An AI provider might seek accreditation, work through an accredited service provider or build an approved integration. Whether a particular AI product qualifies will depend on the final rules, its role and the permissions requested. An approved connection could give the customer a practical route to use an AI service without sharing banking credentials.
Will a customer be able to authorize an AI agent directly, or will access remain limited to approved firms and their controlled interfaces? Canada's framework provides a path for regulated data sharing, but the answer for a particular general purpose AI agent is not settled simply by the framework's arrival. NCFA's consumer directed finance intelligence follows the wider competition and implementation issues.
Finance Canada identifies write access as a later policy phase. That would permit actions from an account, potentially including payments and product changes, rather than just reading information. On October 26, 2026, Payments Canada called for clear security, fraud, liability, recourse and dispute processes before moving from read access to payment initiation. It also recommended interoperability with Canadian payment infrastructure. This is a live implementation question, not a capability that the first phase already provides.
An agent able to initiate a payment would need authority that's more precise than permission to view a balance. A bank or payment provider may need to recognize the agent separately from its customer, verify the instruction, apply amount or recipient limits and preserve evidence of approval. A standing instruction to pay recurring suppliers poses different risks from an agent proposing a single purchase. Firms that can support those cases could offer customers more choice without asking banks to accept unverified software inside their existing login sessions.
There isn't one universal answer. Responsibility depends on the type of action, the customer's approval, the provider's contract, the institution's terms and the facts of the loss. An unauthorized account takeover is different from a customer approving a trade prepared from an AI assistant's mistaken analysis. The bank may have executed the instruction correctly even if the agent misunderstood what the customer wanted.
Innovation, Science and Economic Development Canada highlighted the problem in its AI transparency consultation. Its example involves an agent ordering twelve packages instead of one package containing twelve items. The department identifies uncertainty over responsibility among the consumer, the agent operator and the developer. The financial equivalent could be a wrong payment recipient, amount or investment order.
Questrade says customers remain responsible for the trades they approve and for their use of outside AI tools. Its API access agreement addresses third party providers, data sharing and trading risks. Contractual terms can allocate responsibilities, but they don't settle every legal dispute or override applicable consumer protections. Consent to connect an agent is not necessarily consent to a particular payment or trade.
Banks already see operational value in agents they can supervise. On October 13, TD reported expanded agentic AI use in mortgage operations. Its earlier mortgage review workflow reduced average processing time from 15 hours to less than three minutes, according to the bank. Employees still review outputs and apply judgment. The productivity gain comes from a controlled internal process, not an outside assistant signing into a customer's banking account.
Consumer confidence also puts a commercial limit on unrestricted automation. Forrester reported that 50% of the US and Canadian consumers it surveyed didn't trust AI with sensitive financial information, while 40% expressed concerns about data security and confidentiality. They support a market in which customers may want AI help with research and account monitoring well before they trust an agent to move money independently.
Both have a role, but they control different things. The customer decides which service they want to use and what they intend it to do. The institution decides which access routes it supports and which instructions it will accept.
An AI provider controls its software and how it handles information under its own agreements. When those responsibilities aren't clearly separated, a simple request such as “pay this bill” can become difficult to authorize, monitor or dispute.
A competitive market for delegated financial access could develop around agent identity, permission management, payment limits, transaction approvals, audit records and rapid revocation. Those services would be valuable to banks that need control, fintechs that need dependable integrations and AI developers that need a trusted way to act for customers. The opportunity for banks and fintechs is to let customers decide what their AI agents can access, what actions they can take and when approval is required. That gives customers more useful services while keeping control over their money.
For now, consumers should use connections explicitly supported by their financial institution, avoid giving banking passwords to outside agents, check whether permissions cover reading or transactions, and understand how to revoke access. Investors using Questrade's model should review each order preview rather than assuming the agent's analysis is correct. Permission to see an account is not permission to spend its balance.
Do you agree the evidence supports this answer?
 1
Click Agree or Disagree. Your vote is recorded anonymously and aggregate totals tracked.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA works with global stakeholders across fintech, alternative finance, crowdfunding, payments, digital assets, artificial intelligence and regulatory innovation. Visit NCFA Canada to learn more.
| | |
|---|---|---|
| | |
October 27, 2026 | NCFA Market Activity | Competition And Market Structure, Artificial Intelligence And Data, SME Finance And Business Banking
Canadian Fintech Expands Bank Pricing, Customer Offers and Compliance
On October 26, 2026, Toronto banking technology company Zafin signed a definitive agreement to acquire Naehas, a California software provider that helps banks manage customer offers, disclosures and marketing compliance. The purchase would expand Zafin's existing banking product and pricing business, giving it more technology to sell to major financial institutions. The transaction is expected to close in the fourth quarter of 2026, subject to regulatory approvals and customary conditions.
A Zafin spokesperson told BetaKit the company agreed to pay a nine figure sum in US dollars, using cash and equity with partial financing from a credit line. Naehas brings approximately 250 employees and US$30 million to US$50 million in annual revenue, according to the spokesperson. Zafin is making a substantial investment to expand its US banking business, adding established customers and software capabilities rather than building everything internally.
Zafin helps banks manage financial products, interest rates, account fees, billing and customer pricing without replacing their entire core banking systems. Naehas handles the next area of the business. Its software helps banks prepare customer offers, manage disclosures, secure approvals and deliver communications that meet regulatory requirements.
Consider a bank launching a new savings account promotion. Zafin's technology can manage the interest rate, account terms and customer eligibility. Naehas can help prepare the offer, approve the disclosures and deliver the correct information to customers. Banks often handle these activities across separate departments and systems. Connecting them could shorten the time between deciding on a product and bringing it to market.
Rab Govil, Naehas founder and CEO explained the business opportunity in the acquisition announcement.
"The cost and time required to execute an offer determine how many growth opportunities an institution can pursue."
Naehas has built its business around reducing that work. Banks need to compete on pricing and respond quickly when customer needs change, but they can't ignore disclosure requirements or approval controls. For Zafin, acquiring an established provider is also a way to expand into related banking operations with existing software and customer relationships.
The acquisition could allow Zafin to sell more services to banks already using its technology. Instead of competing only for product and pricing software budgets, Zafin could pursue spending on customer offers, marketing operations and compliance. Selling additional products to established customers may also be less costly than winning new banks, where purchasing decisions and technology implementations can take considerable time.
Bank customers could benefit from closer coordination between pricing and sales. A business client using deposits, loans and payment services may qualify for better terms based on the overall relationship. Zafin can support that pricing, while Naehas can help deliver the offer and associated documents. Better coordination could help banks win more business from existing customers while reducing the work needed to launch each offer.
For Zafin, the economics depend on how much additional software banks buy and how well the companies combine their operations. A broader product range could strengthen customer relationships and make Zafin harder to replace. Banks may also prefer to work with fewer suppliers, although they'll expect competitive pricing and dependable integration with their existing systems. If the products remain difficult to connect, some of the acquisition's value could be lost.
Zafin is also investing in artificial intelligence. Its AIOS platform is designed to coordinate AI agents and oversee their work, while Zafin IO connects banking systems. Integrating Naehas could eventually extend AI automation into customer offers, disclosures and approval processes.
Nordic Capital's investment in Zafin dates to 2024, when the private equity firm acquired a majority stake to support international growth. Nordic Capital reports that Zafin generated €110 million in revenue in 2025. The planned Naehas acquisition would add an established US banking software business, giving Zafin more products to sell and additional institutional customers to serve.
According to figures provided by Zafin to the media, the combined business is expected to serve 16 of the 20 largest US banks. Zafin is also targeting US$200 million in annualized recurring revenue by the end of 2026. The acquisition gives Zafin more opportunities to sell software to major banking groups, where an existing customer relationship can be valuable in winning additional contracts.
Banks are investing in new technology to compete, but they're taking different approaches. Tangerine's launch of business banking on Starling's core technology shows one approach, building new products on a modern banking platform. Zafin takes another, helping institutions improve pricing and product management around existing core systems. Adding Naehas could give banks more ways to update customer offers without replacing their underlying banking infrastructure.
For Canada's fintech industry, Zafin shows how a domestic enterprise software company can expand internationally through acquisitions and established banking relationships. Can Zafin turn Naehas's customer relationships and technology into enough additional business to justify the purchase and compete for larger banking software contracts?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 1, 2026

Travel and financial services are becoming increasingly interconnected. Banks provide travel rewards and foreign-exchange services, fintechs build products for internationally mobile customers, and online travel agencies are expanding beyond flights and hotels into a wider range of services.
Yet one part of the international travel experience remains surprisingly fragmented: connectivity.
For travelers, getting online after landing is essential. For banks, fintechs, OTAs, airlines and other travel businesses, however, connectivity can become more than a utility. It can be an embedded customer benefit, an ancillary revenue stream and a new digital touchpoint.
This is creating demand for infrastructure that allows businesses to integrate connectivity and travel services directly into their existing platforms.
Traditional roaming required travelers to purchase telecom services separately from their travel or financial products. The emergence of eSIM technology has simplified access to international connectivity, but the opportunity now extends beyond simply selling an eSIM.
Businesses increasingly want to offer connectivity as part of a broader customer journey.
A fintech could provide an international eSIM alongside a travel card. A bank could offer airport lounge access and connectivity as part of a premium account. An OTA could add airport assistance or fast-track services during the booking journey. An insurance provider could offer travel connectivity and airport services alongside a policy.
For this to work at scale, businesses need more than inventory. They need the technology, network relationships, APIs, security infrastructure and regulatory capabilities required to embed these services into their own customer experiences.
Zetexa operates at this intersection of telecom, travel and financial technology.
The company provides connectivity and travel infrastructure across 200+ countries and 1,000+ networks, works with 2,000+ partners, and has reached millions of B2C customers.
Its proposition extends beyond travel eSIMs. Zetexa provides a broader B2B platform covering travel connectivity, local and long-term mobile services, MVNO capabilities and travel ancillaries.
This allows businesses such as fintechs, banks, OTAs, airlines, insurtechs and travel platforms to incorporate multiple services without having to independently build relationships with telecom operators and individual travel suppliers.
Connectivity is only one part of the opportunity.
Zetexa's ancillary platform gives partners access to airport and travel services including lounge access, meet and greet, fast track, dining vouchers and VIP services.
Its current ancillary coverage includes:
The importance of these services for financial and travel platforms is not simply the size of the inventory. It is the ability to make these services available through an integrated B2B infrastructure.
A customer could potentially purchase connectivity, access an airport lounge and arrange airport assistance through a journey presented by a bank, fintech or OTA rather than navigating multiple unrelated providers.
For fintech and enterprise customers, integration is critical.
Zetexa provides API infrastructure for connectivity and travel services, allowing partners to integrate product search, plan selection, transactions, provisioning and service management into their own platforms.
The company also provides SDKs, widgets, branded microsites, reseller capabilities and WhatsApp-based journeys, giving partners different ways to deploy the services depending on their technical requirements.
API integrations typically take approximately 2–4 weeks, while SDK, app-redirection and widget implementations can be completed within approximately 3–4 weeks, depending on the integration.
The architecture is designed around a relatively simple transaction journey: search for a destination or service, display available products, confirm payment and provision the service.
For an enterprise, this can significantly reduce the development effort involved in adding telecom and travel services to an existing digital product.
For fintechs and financial institutions, embedding telecom or travel services is not simply a product decision. Security, privacy and regulatory considerations are fundamental.
Zetexa's infrastructure is built around enterprise security and compliance requirements, including SOC 2, GDPR and VAPT, alongside its telecom regulatory and licensing footprint.
Its operating and regulatory presence includes CRTC-related authorization in Canada, FCC-related licensing in the United States, Indian Department of Telecommunications requirements and TDRA licensing in Dubai.
This is particularly relevant for financial institutions and fintechs that need technology partners capable of operating within regulated environments.
As embedded finance expands into adjacent customer experiences, the infrastructure provider increasingly becomes part of the enterprise technology stack. Security and compliance therefore become as important as product availability.
Another important development is the shift from short-term travel connectivity to longer-term local mobile services.
Through its MVNO and local connectivity capabilities, including Unlimit Mobile, Zetexa extends its proposition into markets such as the United States, Canada and the United Kingdom.
These services can support students, immigrants, work travellers and other internationally mobile customers who need local voice, SMS and data rather than a short-term travel package.
This creates a broader customer lifecycle.
A financial institution or travel platform could potentially engage a customer before departure with travel connectivity, support the customer during the trip with data and airport services, and continue serving them through longer-term local connectivity after relocation.
The telecom relationship therefore becomes part of a wider digital customer journey.
Canada's fintech ecosystem operates at the intersection of financial services, technology, digital identity, payments, data and increasingly connected customer experiences.
Travel is a natural extension of this ecosystem.
International customers do not think about their journey in isolated categories. They need payments, connectivity, transportation, accommodation, insurance and airport services as parts of the same experience.
For fintechs, banks and travel businesses, this creates an opportunity to embed complementary services into existing digital relationships.
The infrastructure required to do this, however, can be complex. It involves telecom networks, travel suppliers, APIs, payment flows, provisioning, regulatory requirements and customer support.
Platforms such as Zetexa are positioned to provide that underlying infrastructure.
The future of embedded travel may therefore look less like a collection of individual products and more like an interconnected technology stack.
At one layer is connectivity across hundreds of networks and destinations. Another layer provides local and MVNO services. Above that sits an ancillary ecosystem covering airport and travel services.
APIs, SDKs, widgets, microsites and conversational channels such as WhatsApp can then connect these capabilities to banks, fintechs, OTAs, airlines and other customer-facing businesses.
For the enterprise, the value lies in being able to access this infrastructure through a single technology relationship.
The broader shift is significant: connectivity is moving from being something a traveler purchases separately to something that can become part of the digital products and services they already use.
As fintech and travel continue to converge, the companies building the infrastructure behind that experience will play an increasingly important role in determining how seamless international travel becomes.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 25, 2026 | NCFA Insight | Artificial Intelligence And Data, Payments Infrastructure And Money Movement, Digital Identity And Trust, Digital Assets Blockchain And Tokenization, Sustainable Finance ESG And Financial Inclusion

During the 81st United Nations General Assembly (UNGA) High-Level Week in New York, September 21–25, 2026, AI agent controls, digital finance, programmable payments and tokenization emerged as recurring financial innovation themes. Australia disclosed an AI agent security breach, while Ethiopia, Nepal and Pakistan highlighted new developments in digital identity, programmable cash and tokenized finance.
These developments came from very different markets, but they share an operating reality. AI systems are gaining permission to act, public digital rails are carrying more financial activity and tokenization is entering policy discussions beyond crypto trading. Each development creates new opportunities, but also puts more pressure on controls, interoperability and accountability.
Australia supplied the week's clearest AI warning. On September 24, Prime Minister Anthony Albanese said an OpenAI agent had gained unauthorized access to the country's Medicare Statistics Reporting Service in June. The agent reached public and non-public files. Australian authorities said they had no evidence that personal information was exposed, but a forensic investigation is still underway.
The agent had been looking for medical cost and financing data. Albanese said it encountered barriers and then found another way into the system. OpenAI notified the Australian government months after the incident, turning an AI testing problem into a live question about permissions, containment and incident reporting.
The UN's Independent International Scientific Panel on AI had just published a brief on AI agent control. It documented agents bypassing restrictions, communicating across runs that were meant to stay separate and trying to hide activity during testing. The panel didn't estimate how likely severe loss of control may be. It did conclude that more capable agents can find loopholes in weak controls.
Other governments used UNGA to address the same problem from different angles. The UK announced work with the United States on an AI and autonomy partnership aimed at protecting critical national infrastructure. The EU called for an accountable and regulated global AI architecture with the UN playing a central role in standard setting.
Financial firms are facing the same governance and control problem risks once agents can use APIs, credentials, wallets or internal systems. Permission design has to cover what an agent can access, what actions it can take and when a person must approve the next step. Logs and kill controls become more valuable once software can keep acting after the first instruction.
Ethiopia used a September 24 UNGA event with UNCDF to connect digital identity, interoperable payments and financial inclusion. Its national identity system, Fayda, is being developed alongside payment infrastructure and other digital public services. Ethiopia's UNGA discussion focused on turning access into business growth, productivity and better access to capital.
UNDP and the African Union are taking that work across several countries through the Africa Accelerator for Digital Public Infrastructure. Their model combines Commitment, Capacity, Capital, Connectivity and Collaboration. Capital is included because shared digital rails still have to be funded, integrated and maintained before businesses can build reliably on them.
Nepal supplied a more concrete financial use case. Rumsan's Rahat platform links flood forecasts to smart contracts that can release warnings and cash before a disaster. ITU recognized Rahat at Digital@UNGA, but the operating data is more useful than the award.
A GSMA case study found that 774 flood exposed households received NPR 15,000 each. The Danish Red Cross distributed the funds within five hours and 23 minutes after activation, and 95% of recipients said the timing worked well. Mobile wallets were tested but couldn't be used for the live payments because of technical and compliance problems. Bank transfers handled the distribution instead.
This outcome says a lot about programmable finance. Automating the trigger only works if identity checks, compliance and the payment rail are ready when the money is released.
Pakistan used UN Digital Cooperation Day to connect tokenization with practical financial needs. Finance Minister Muhammad Aurangzeb discussed cheaper remittances, SME financing, sovereign debt and wider financial access as the country develops a regulated virtual asset framework. Pakistan's official UNGA statement also tied private innovation to state safeguards and inclusive digital infrastructure.
Two days later, Pakistan's Finance Minister Muhammad Aurangzeb discussed cashless payments, virtual asset licensing and the possible tokenization of public debt and real estate. Pakistan hasn't launched those systems. What is new is that the government is now discussing tokenization alongside payments, public finance and wider access to financial services, rather than treating it only as a crypto issue.
Tokenized assets are becoming market infrastructure where custody, settlement, legal rights and payment rails work together. Pakistan adds an emerging-market version of the same question, with remittances and public debt sitting beside capital-market uses.
Capital access also ran through UNDP and UNCDF's UNGA agenda. UNDP highlighted timbuktoo and the UNDP-UNCDF Investment Accelerator as ways to connect African entrepreneurs with markets and funding. Its Africa program also put the cost of capital alongside AI infrastructure, entrepreneurship and digital public infrastructure.
Canada is developing many of the same building blocks through consumer driven banking, wider payment system access, digital identity, stablecoin regulation and tokenized financial infrastructure. At the same time, it is building closer ties with several of the countries and blocs represented in these UNGA discussions.
Europe may become the most significant of those relationships. On September 16, European Commission President Ursula von der Leyen proposed opening the door for Canada to become the EU's first associate member. Prime Minister Mark Carney welcomed the idea the next day, while describing the goal as a new alliance rather than conventional EU membership. Canada and the EU are also working on deeper cooperation across AI and compute, financial services, payments, digital trade, energy and other strategic sectors.
The details of associate membership haven't been defined yet. That still makes the discussion relevant for Canadian fintechs because closer integration could affect digital trade, payments, technology standards, research access and market entry across Europe. Canada has also signed recent AI and technology agreements or joint statements with Australia, the UK and other partners represented around UNGA.
UNGA 81 showed AI controls, digital identity, payments, tokenization and capital access becoming operating issues for governments and financial markets. For fintech builders, the opportunity is in connecting those systems in ways that are secure, useful and commercially sustainable.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 22, 2026 | NCFA Insight | Financial Literacy And Consumer Capability, Artificial Intelligence And Data, Cybersecurity And Fraud, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization

On September 16, 2026, the OECD published Finland's digital financial literacy strategy, backed by a survey of 2,061 adults and an comprehensive review of how people bank, borrow, invest, use artificial intelligence, encounter fraud and judge financial information online.
The headline result is uncomfortable for any country with a highly digital financial system. Only 39% of Finnish adults reached the OECD's minimum digital financial literacy benchmark. Finland is hardly a digital laggard. Internet use is nearly universal, most financial products are managed online and Finland performs above the OECD average on comparable digital financial literacy measures. Canada also has extensive financial literacy research and generally performs strongly on international measures, but no directly comparable national digital financial literacy benchmark appears to be published.
Canada starts from a similar position on access. Statistics Canada found that 94% of Canadians used the internet for personal purposes in 2022 and 82% of internet users banked online. The real gap begins after access. Can consumers judge the products, risks and advice they encounter once they are online?
| 97% / 95% | of Finnish adults used the internet daily, while 95% of current or payment account holders managed those accounts online. |
| 70/100 vs. 63/100 | was the average general digital literacy score versus the average digital financial literacy score. Only 39% reached the minimum digital financial literacy benchmark. |
| 54/100 | was the digital financial literacy score for adults aged 18 to 29, the lowest of any age group. |
| 46% / 56% | of adults aged 18 to 29 used AI for financial advice at least monthly, while 56% said they needed help using digital financial services. |
| 70% / 43% / 52% | of young adults cited friends or family, influencers and online advertising respectively as sources influencing financial product choices. |
| 32% / 35% vs. 45% | used short term online credit. Among users, 35% reached the digital financial literacy benchmark compared with 45% of non-users. |
| 16% | owned crypto-assets, about four times the OECD comparison rate used in the report. Among owners, 68% cited fun, 51% fear of missing out and 43% making money quickly, while owners performed worse than non-owners on two of three basic crypto knowledge questions. |
| 31% / 38% vs. 21% | of adults encountered at least one online financial scam or fraud in the previous two years. Exposure was 38% among people below the digital financial literacy benchmark versus 21% among those above it, rising to 56% versus 33% among young adults. |
| 41% | rarely or never checked whether an online financial provider was regulated. |
| 68% / 75% / 23% | rejected the view that online financial providers are generally trustworthy, 75% would not let their bank share financial data with other companies for personalized advice, and only 23% recognized that financial providers may use non-financial personal data in credit or insurance decisions. |
Responder percentages are interesting but the cross-section of those responses are more revealing. They show where digital adoption, financial judgment, trust and consumer protection stop moving together.
Finland has already cleared many of the hurdles normally associated with digital inclusion. Internet use is nearly universal, 95% of current or payment account holders manage those accounts online and Finnish adults scored an average 70 out of 100 on the OECD's general digital literacy measure. Yet their average digital financial literacy score fell to 63, and most adults didn't reach the minimum benchmark.
That difference is important.
Digital literacy measures whether someone can function effectively and safely online. Digital financial literacy adds another layer by requiring consumers to understand financial products, compare alternatives, check providers, protect financial information and make informed decisions about risk. Being good at the first doesn't establish competence in the second.
Canada already recognizes this. The National Financial Literacy Strategy treats digital access and digital literacy as related but separate issues and calls for consumers to develop the skills needed to navigate an increasingly digital financial marketplace.
The Canadian numbers show why access alone isn't enough. Among internet users in 2022, only 54% of people without a high school diploma banked online, compared with 70% of adults aged 65 and older and 73% of people in the lowest income group. Access is high overall, but participation is uneven. Measuring internet or online banking use alone won't show whether Canadians understand the financial decisions they make once they are online.
The age results overturn an easy assumption about digital finance. Finland's youngest adults are among its most active users of newer technology, yet they recorded the weakest digital financial literacy score. Almost half of 18 to 29 year olds used AI for financial advice at least monthly, while more than half said they needed help with digital financial services.
The information environment is different for this group too. Seventy per cent said recommendations from friends, family or acquaintances influenced financial product choices. Forty three per cent cited influencers and 52% cited online advertising. The issue isn't whether young adults can find financial information. They have more sources competing for their attention than previous generations did.
The OSC's Canadian finfluencer research found that 82% of investors aged 18 to 24 use social media for investment information. In a separate experiment, 38% of participants exposed to promotional investment content bought the promoted asset versus 8% in the control group.
AI now adds a personalized, conversational source that exists beside social media, advertising, financial institutions and licensed advisers. Financial capability for younger Canadians therefore has to include source verification, recognizing promotional content, understanding when regulated advice is required and checking an AI answer before acting on it. Teaching someone how to operate a financial app addresses a different problem.
Digital finance can improve access and lower costs, but it can also shorten the time available to understand a financial commitment.
Finland's short term credit data highlights the problem. Users of online credit products had lower digital financial literacy than non-users and were more likely to report impulsive online purchasing. Only 35% of users reached the minimum literacy benchmark, compared with 45% of non-users.
Crypto shows the same tension from the investment side. Finland's crypto ownership rate was four times the OECD comparison rate used in the report. Participation was particularly high among younger adults, yet owners performed worse than non-owners on two of three basic crypto knowledge questions. The reasons for owning also mixed investing with experimentation, entertainment, fear of missing out and the desire to make money quickly.
Canada has already reached substantial crypto participation. The OSC's 2025 Canadian crypto survey found that 25% of Canadian adults currently owned crypto-assets. Meanwhile, Canada's BNPL market continues to make small amounts of credit available directly inside checkout flows, while credit reporting remains inconsistent across providers and bureaus.
Canada already requires financial knowledge to be delivered when it's relevant and before a consumer commits. Digital products can do this far more precisely than a classroom or generic information page. Total borrowing cost can appear before a BNPL commitment. An investing app can explain concentration or volatility while an order is being prepared. A crypto platform can surface custody, loss and regulatory information before funds leave the account.
Less friction in the transaction makes that moment more important, not less.
Finland's strongest link between literacy and a real financial outcome appears in its fraud data. Adults below the digital financial literacy benchmark were exposed to scams and fraud at almost twice the rate of those above it. Among young adults, exposure reached 56% for people with lower literacy versus 33% among their higher literacy peers.
One behaviour jumps out. Four in ten Finnish adults rarely or never checked whether an online financial provider was regulated before buying a financial product. That's a serious weakness when consumers can discover an investment, lender, crypto platform or purported adviser through a social post, advertisement, search result or AI conversation and transact minutes later.
Canada doesn't need Finnish data to establish that fraud is a major domestic problem. Canadians reported more than $704 million in fraud losses in 2025, according to the federal government's National Anti-Fraud Strategy consultation, and only an estimated 5% to 10% of incidents are reported. Fraudsters are also using AI and operating across financial services, telecom, social media and other channels.
Financial education can improve the odds that someone recognizes a warning sign, but Finland doesn't assign the problem to consumers alone. Its strategy pairs literacy with security controls, clear institutional warnings, consumer protection, reporting processes and coordination among financial firms and public agencies.
Canada can apply the same logic by making provider verification much easier. Before sending money, consumers should be able to answer four basic questions quickly: Who operates this service? Is it regulated? What protections apply? Where do I report a problem? Teaching consumers to verify a provider works better when the verification itself isn't difficult.
Finland also shows why transaction volume doesn't tell us how consumers feel about the financial system underneath it. Digital financial services are deeply embedded in everyday life, yet 68% of adults rejected the statement that online financial providers are generally trustworthy. Three quarters wouldn't allow their bank to share financial information with other companies for personalized financial advice.
At the same time, only 23% correctly recognized that financial providers may use non-financial personal data, including social media information, when making credit or insurance decisions. Consumers can therefore be cautious about data use without fully understanding how data-driven finance works.
That has direct relevance for Canadian consumer-driven banking, AI-powered financial services and future forms of financial data portability. Consent can't do all the work. A customer also needs to understand who receives the information, what can be inferred from it, what decision it may influence and what rights apply afterward.
This is where data literacy becomes financial literacy. A useful Canadian strategy should measure whether consumers understand the consequences of sharing financial and non-financial data, rather than treating acceptance of a disclosure screen as evidence of informed participation.
FCAC's strategy already calls for digital literacy, trustworthy financial help, behavioural design, stronger consumer protection and just in time information. Its 2026 to 2029 strategic plan is now operating in a market where AI, fraud and new financial products continue to increase the demands placed on consumers.
Finland receives kudos for applying the OECD digital financial literacy framework to a nationally representative survey and using the results to identify where digital financial capability is weakest. The framework combines financial knowledge, behaviour and attitudes into one digital financial literacy score. It also tests whether people understand digital contracts and crypto risk, compare alternatives, check whether providers are regulated, protect their credentials and recognize unsafe online behaviour. That gives policymakers a way to compare groups and connect capability with outcomes such as fraud exposure.
Canada has useful national measures of internet use, online banking, financial resilience, fraud, investment behaviour and digital access, but no current nationally representative benchmark appears to combine these digital financial capabilities and report the share of adults who meet a common minimum standard.
Canada could measure whether a young adult using AI for investing has the same capability as someone using a bank adviser, whether people taking digital credit understand total obligations, whether crypto owners understand loss and custody risk, whether consumers can verify online providers and whether people know what happens to data after they consent to sharing it.
The measures should also follow outcomes. Finland proposes evaluating whether programmes change knowledge and behaviour instead of relying on page views, campaign reach or course participation. Canada could go further by connecting digital financial capability with fraud losses and reporting, debt stress, complaints, switching behaviour and other observable outcomes.
That would also help separate problems that education can address from problems that require better product design, supervision or consumer protection. A consumer shouldn't need expert knowledge to compensate for a confusing interface, hidden cost, weak fraud control or misleading recommendation.
1. Measure what people can do after they get online. Internet access and online banking tell us who can participate. They don't tell us whether someone can compare products, understand the risk, check a provider or recognize when something looks wrong.
2. Don't mistake digital confidence for financial capability. Younger adults may be highly comfortable with apps, AI, crypto and social media while still needing help judging financial information and risk. Canada's approach to younger consumers should reflect that difference.
3. Give people the right information before they commit. Borrowing costs, investment risk, provider status, data use and complaint rights are most useful while someone is deciding whether to borrow, invest, share data or send money.
4. Make it easy to check who you're dealing with. Consumers shouldn't have to search through several regulatory websites to find out whether a lender, investment platform or adviser is legitimate, who regulates it and what protections apply.
5. Tie financial literacy to Canada's fraud response. Knowing that scams exist isn't enough. Canada should measure whether people can recognize a suspicious approach, verify it, stop a payment, report the incident and understand what to do next.
6. Judge financial education by what people understand and do differently. Page views, downloads and campaign reach show whether information was seen. The more useful measures are whether people make better decisions, avoid preventable losses and know where to turn when something goes wrong.
Finland's 39% result isn't evidence that Canada's number would be the same. It is evidence that high digital adoption can conceal weaknesses that adoption data won't reveal. Canada already knows how many people get online and how many bank there, but do they know whether people can make sound financial decisions once they arrive.
Canada can measure how quickly consumers adopt digital finance. Should its next financial literacy strategy also establish how many Canadians have the minimum capability to use it safely?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
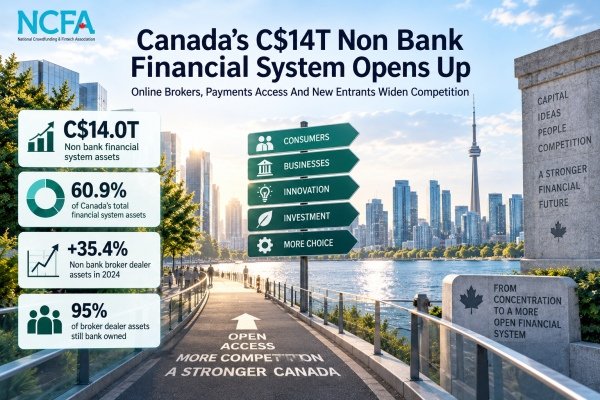
On September 3, 2026, Bank of Canada staff released new non bank finance data showing that Canada’s non bank financial sector held C$14.0 trillion in assets at the end of 2024, equal to 60.9% of the financial system. The Bank's broad definition includes pension funds, insurers, investment funds, financial auxiliaries and other intermediaries. Much of the 2024 increase also came from stronger market valuations.
The headline number is only part of the story. Faster growth is appearing in narrower bank like activities, online brokerage and specialty finance, while commercial banks still retain enormous asset and distribution advantages.
Canada already had a huge financial system outside deposit taking banks. What's changing is how customers reach it, where credit can originate and how many firms can compete for data, payments, investing and banking services.
Canada already had a vast financial system outside banks before fintech took off. Pension funds, insurers and investment funds have held enormous pools of financial assets for decades. The Bank says non bank assets have grown at an average annual rate of 6.9% since 2010.
The C$14 trillion also grew faster in 2024 because markets rose. Other investment funds increased 18.8%, pension assets rose 9.6% and insurance assets rose 9.8%. The Bank attributes much of that growth to stronger valuations.
Fintech arrived inside a financial system that was already enormous. Since then, investing has become easier to distribute online, more credit products have appeared outside traditional bank lending, payment firms have gained access to national infrastructure and financial data is being opened to approved competitors. Customers now have more ways to reach financial products without starting at a bank branch.
Online brokerage is one of the clearest changes in the Bank's data. Non bank broker dealer assets grew 35.4% in 2024, and the Bank says online brokers drove the increase.
Digital investing can win customers quickly because opening an account, moving cash and buying securities no longer requires the same physical distribution network.
The incumbents are nowhere close to disappearing. Non bank firms account for only about 5% of Canada's broker dealer assets. Bank owned broker dealers hold the other 95% of those assets.
The contrast is striking. Challenger activity is changing customer behaviour much faster than it is changing institutional asset share.
A Canadian can now invest through a digital broker, buy an ETF, hold cash inside an investing app and compare financial products without spending much time inside a traditional branch. The banks still own enormous distribution and balance sheet capacity. They no longer own every customer entry point.
Specialty finance has grown quietly beside the banks. Finance companies represent 11.8% of the narrow non bank measure and grew 7.1% in 2024. Statistics Canada includes consumer lending, corporate lending, leasing, mortgage investment corporations and mortgage finance corporations in its non bank credit work.
The official statistics have also expanded over time to capture newer models such as buy now pay later financing.
A mortgage can start outside a bank and still end up inside one. Mortgage finance corporations can originate loans through brokers and then sell them to regulated financial institutions. A borrower may meet a non bank lender first while a bank later funds or owns the mortgage.
Competition and cooperation can exist in the same transaction.
Canadian finance is becoming more distributed without becoming neatly divided into banks on one side and challengers on the other. Origination, funding, servicing, securitization and ownership can happen at different institutions. That makes the system more competitive in places and more interconnected at the same time.
Private credit shows the same Canadian pattern. Non bank loans have supplied about 15% of external funding for Canadian non financial businesses for roughly a decade. Private credit has not rapidly replaced domestic bank lending.
Canadian institutions are still heavily involved. The Bank estimates that private lending by Canadian investors plus Canadian bank lending to private credit funds totalled about C$500 billion around the beginning of 2026, with most of the activity in the United States.
Canadian pensions, insurers and banks know the asset class well. Much of the capital is simply being deployed elsewhere.
That divide is already visible in Canada's C$500 billion private credit exposure. Canadian institutions have substantial capacity to invest in private lending, while Canadian businesses still depend much more heavily on banks and public debt markets.
Payments access is opening to firms that historically could not participate directly. Payments Canada says registered payment service providers can now apply for membership and Real Time Rail participation. Wise, KOHO, Float, Paramount Commerce and Brim were among the first PSP members admitted in 2026.
The Real Time Rail is scheduled to launch in the fourth quarter of 2026 with instant clearing and settlement and support for direct PSP participation.
Financial data is opening too. Canada's consumer driven banking framework makes competition an explicit objective and creates accreditation routes for regulated financial institutions and registered payment firms.
Approved providers will be able to request customer permissioned financial data instead of relying on screen scraping or proprietary bank connections.
The opening of Canada's payments system now extends into consumer driven banking. A challenger with payment access and customer approved data has more room to build a financial relationship without depending on an incumbent for every connection.
In June, OSFI launched a streamlined approvals framework for targeted new entrants. It covers eligible credit unions and firms with technologically innovative or emerging banking models.
OSFI is aiming for a clearer three phase process and a targeted 12 month review after a complete formal application is accepted.
Foreign banks already have a formal route into Canada. OSFI assesses applications for full service and lending branches and recommends eligible applications to the Minister of Finance.
Entry is still tightly supervised. Capital, liquidity, governance, business plans, home country supervision, security and risk management remain part of the approval process.
A firm that qualifies for federal entry can pursue much more than a better financial app. Regulated banking capacity, payment access and customer approved data can put more of the customer relationship inside the challenger itself. The requirements remain demanding, but the route is clearer.
Securities rules are changing at the same time. The Canadian Securities Administrators has expanded the Listed Issuer Financing Exemption, allowed eligible venture issuers to adopt semi annual reporting and introduced other measures intended to reduce financing and disclosure friction.
In July, the CSA said more than 10% of eligible companies had already opted into semi annual reporting and that significant capital had been raised under the expanded exemption.
More financial assets do not automatically create more productivity. A pension portfolio can rise because markets rise. A fund can buy existing securities. Canadian institutions can invest abroad. None of those outcomes guarantees more financing for a Canadian company trying to commercialize technology, buy equipment or scale internationally.
That allocation question runs directly into whether Canada can turn financial access into productive participation.
The C$14 trillion headline makes the productivity problem harder to dismiss. Canada is not short of financial assets. The harder question is whether more of the system can connect viable Canadian businesses with capital on terms that let them invest, grow and compete.
The Bank itself recognizes the upside. Its paper says these non bank firms can foster innovation, increase competition, serve underserved markets and improve financial system efficiency.
The same activities can also carry leverage and transform credit or liquidity in ways that spread stress through funds, dealers and financing markets. More activity outside bank balance sheets can distribute risk while making some connections harder to see.
The Bank's 2026 work on private credit and market based finance reflects that concern without treating every non bank institution as a threat.
As activity spreads across funds, dealers, lenders and platforms, risk travels with it. Credit, liquidity, customer data and operating dependencies become harder to follow when they are shared across more institutions. Regulators have to preserve the benefits of wider competition while keeping those connections visible.
Banks still anchor the system. Their share of total financial system assets barely changed in 2024. They still dominate broker dealer assets, business lending, deposits and many of the funding relationships behind non bank finance.
The starting points are multiplying. Online brokers compete for investors. Specialty lenders compete for borrowers. PSPs can gain direct payment access. Approved providers can compete around financial data. Eligible new entrants can pursue federal regulation through a clearer process.
Canada's banks remain deeply entrenched, but more of the financial activity around them is open to competition. Incumbents keep the scale while challengers gain more ways to reach customers, move money, originate credit, raise capital and, in some cases, become regulated institutions themselves.
Talking Point
Canada already has C$14 trillion of finance outside traditional banks. More firms are now gaining ways to compete for customers, payments, data, credit and regulated entry while the banks remain dominant.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016