





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 17, 2026 | NCFA Market Activity | Payments And Money Movement, Embedded Finance, Competition And Market Structure
On July 15, 2026, Mastercard launched Wallet Services, a development package that helps banks, fintechs and digital businesses add contactless payments to their own iOS and Android apps. Mastercard supplies the software development kits, Secure Element applet and tokenization through Mastercard Digital Enablement Service.
The product reduces work that previously required separate operating system integrations, security approvals and EMVCo certification. Mastercard says its software kits are available wherever Mastercard Digital Enablement Service operates, covering more than 200 countries and territories. Several banks are already building with the product, although Mastercard hasn’t named them or confirmed their launch markets.
A bank can now keep tap to pay inside mobile banking instead of sending customers to Apple Wallet or Google Wallet. Payments can sit beside card controls, rewards, instalments, merchant offers and account data. Mastercard gains another role beneath the customer interface even when the issuer owns the app.
Apple created the opening. With iOS 18.1, approved developers gained access to the iPhone Secure Element and near field communication functions for contactless transactions. Canada joined the first group of supported markets. Developers can also ask users to select another app as the default contactless wallet.
Access still comes with conditions. Developers need an Apple commercial agreement, an entitlement, security approval and payment of associated fees. Apple permits more competition while retaining control over device permissions and the economics of iPhone access.
Mastercard packages that access into a bank ready product. Push provisioning already lets issuers send cards into Apple Wallet or Google Wallet. Wallet Services goes further because the bank or fintech app can become the contactless payment interface.
That fact is at the centre of competition concerns around Apple Wallet. Banks and payment companies could issue cards, but Apple controlled how contactless payments worked on the iPhone. Opening NFC access gives them a way to build their own wallet experience. Mastercard now provides the software and tokenization needed to do it.
Issuer control improves, but independence remains limited. Mastercard still manages the payment token and credential process. Apple still decides which iPhone apps receive access. Consumers must also choose the bank app over wallets they already use for cards, tickets, transit passes and identification.
Wallet Services fits a wider pattern of payment networks opening access while tightening control. Banks receive a new route to the customer, but Mastercard and Apple retain authority over the credential, security standards and device access that make the wallet work.
Mastercard benefits from that split. Banks can own more of the customer experience while Mastercard supplies tokenization, security and cross platform integration. The network can strengthen its position even when its brand isn’t visible at checkout.
Apple Wallet and Google Wallet retain the strongest consumer distribution. Visa can answer with its own tokenization and issuer software. Paze follows a different model. The bank consortium wallet focuses on online checkout, not device level contactless payments, though it reflects the same effort to retain wallet distribution. Independent providers such as Thales also sell branded NFC wallet technology to banks and fintechs.
Mastercard’s advantage comes from combining network credentials with the wallet build. Its weakness comes from the same design. Banks with Visa, Interac and Mastercard cards may not want separate wallet logic for each network. A single network product works more cleanly for a fintech running one Mastercard card program than for a large Canadian bank serving customers across several payment schemes.
Canada offers an immediate test because Apple already permits third party NFC access here. A bank could connect contactless payment with credit card controls, loyalty, fraud alerts and merchant offers inside mobile banking. A fintech could combine a prepaid or credit product with budgeting, expense management or instalment features.
The customer use case is less certain. Apple Wallet and Google Wallet already give users one place for several cards and services. A bank owned wallet needs a clear reason to replace that convenience. Better rewards, stronger controls or a more useful account experience could help. Branding alone won’t.
Coverage will shape adoption as well. Mastercard’s release focuses on Mastercard credentials. Canadian consumers often carry Visa credit cards and Interac debit cards alongside Mastercard products. Banks will need to know whether Wallet Services can exist inside a wider wallet or whether each network requires separate development and commercial terms.
Mastercard hasn’t disclosed pricing, data ownership, merchant data access, fraud liability or support for non Mastercard credentials. It also hasn’t identified the first banks or launch markets. Those omissions limit any claim that the product will change wallet competition quickly.
The technology lowers a real build barrier. Commercial success now depends on whether banks can assemble complete wallets and give customers a reason to use them.
Can banks turn contactless payments inside mobile banking into a better customer experience, or will Apple and Google remain the default because one wallet already serves every card?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 17, 2026 | NCFA Market Activity | Insurance And Insurtech, Embedded Finance, Artificial Intelligence And Data
On July 14, 2026, Cover Genius announced a US$100 million capital raise backed by Vista Credit Partners. The financing transaction values the embedded insurance company at US$1.9 billion and will support new AI tools, deeper platform integrations, international growth and selected acquisitions.
The size of the raise is only part of the story. Cover Genius is taking capital from the credit arm of Vista Equity Partners rather than announcing another conventional venture round. It comes after the company increased revenue by 50% in 2025 and built a large base of recurring platform relationships. That gives Vista a more established enterprise software business to finance, although the interest rate, maturity, covenants and any equity features weren’t disclosed.
Cover Genius now connects more than 200 digital platforms with over 50 insurance carriers. It has issued 240 million policies, protected more than 70 million customers and recorded US$3.2 billion in cumulative gross written sales. Its products are available in more than 60 countries and across all 50 US states.
Cover Genius is no longer simply distributing travel insurance at checkout. It provides the software, carrier connections, product design, pricing, claims handling and payment tools that let another company offer protection inside its own customer experience.
Cover Genius works behind platforms including Klarna, Revolut, Stripe, Booking.com, Agoda, Priceline, Uber, eBay and Turkish Airlines. Its reach now spans travel, ecommerce, retail, ticketing, logistics, mobility and financial services.
A platform can use Cover Genius to add insurance or a warranty without building separate systems for each carrier and country. Cover Genius adapts the product, price and presentation to the customer, transaction and location. It can also manage the policy after purchase and pay approved claims in more than 90 currencies.
That operating model reflects the same infrastructure approach seen across embedded financial services. The customer stays inside the merchant or fintech app while a specialist provider handles regulated work behind the scenes. The platform gains another source of revenue and can make the main purchase easier to protect.
Cover Genius competes with several companies. Bolttech combines insurance exchange technology with a broad carrier and distribution network. Qover builds digital insurance programs for fintech, mobility and other European platforms. Boost Insurance provides the regulated and technical stack behind embedded products in the United States. Tint works with marketplaces and software companies on tailored protection programs. Traditional insurers are also improving their APIs and selling directly through large digital partners.
Cover Genius has a scale advantage in the number of countries, industries and large platforms already connected to its system. That scale creates useful data across product selection, pricing, conversion and claims. It also makes the company harder to replace when a partner relies on it across several markets.
The new capital will fund three defined areas of AI development. Cover Genius plans to(1) improve how protection is selected and presented for each customer, (2) support agent led purchasing, and (3) automate more of the claims process.
1. Personalization could help a platform offer the right protection without adding too many choices at checkout. A travel site may know the destination, fare type, booking value and traveller profile. A retailer may know the product category, delivery route and expected replacement cost. Better use of that information could raise insurance sales while reducing irrelevant offers.
2. Agentic distribution has a less settled business case. As software agents begin booking travel or making purchases for users, they may also compare protection, read exclusions and complete the insurance purchase. Cover Genius wants its products and APIs to be available inside that process rather than waiting for a person to select a box on a checkout page.
3. Claims may deliver the clearer near term return. Cover Genius already operates XCover for policy and claims management, XClaim for approved payments and BrightWrite for pricing and product recommendations. More automation could shorten review times and reduce the support burden for both Cover Genius and its partners.
It also raises an important control question. Automated decisions need reliable evidence, clear reasons and a practical route for customers to challenge an outcome. Insurance claims are more sensitive than product recommendations. Faster processing will only improve the customer experience when the decision is also fair and understandable.
The financing choice suggests Cover Genius believes it has enough operating scale to add debt without giving up another large ownership stake. That can be attractive when revenue is growing and enterprise contracts provide better visibility. It also adds fixed obligations that equity financing doesn’t carry.
The company raised US$80 million in a Series D led by Spark Capital in 2024 after reporting 107% revenue growth for 2023. The latest transaction gives it more capital for product development and expansion, but the company hasn’t disclosed current revenue, profitability, cash flow or the cost of the new financing. A US$1.9 billion valuation alone doesn’t answer whether the credit structure is conservative or aggressive.
There are several ways the investment could work well. Cover Genius may deepen existing partner relationships, enter new industries and use AI to improve conversion and reduce claims costs. Its global carrier network could also make selected acquisitions more valuable because acquired products can be distributed through an existing platform.
Execution could become harder as the company expands. Insurance regulation remains local, partner integrations can be complex and claims quality has a direct effect on trust. Larger insurers and other global insurtech platforms are also investing in the same distribution layer. Cover Genius must grow without making its products harder to understand or its claims process harder to challenge.
Canadian insurers, fintechs, travel companies and ecommerce platforms face the same integration problem. Building protection internally requires carrier relationships, licensing, pricing, compliance and claims operations. A provider such as Cover Genius can shorten that work, although Canadian companies still need to understand who controls the customer data, product terms and claims decision.
The funding structure also offers a useful comparison for Canadian growth companies. Private capital markets are giving mature technology businesses more ways to finance expansion after venture equity. Credit can preserve ownership, but it works best when recurring revenue and cash flow can support repayment through a slower period.
Has Cover Genius become the insurance infrastructure layer for digital platforms, or will global carriers and competing insurtechs make embedded protection a lower margin service?
Angus McDonald and Chris Bayley founded Cover Genius after encountering fragmented insurance distribution while operating an online travel business. RentalCover became the first use case for combining digital distribution, policy administration and claims support.
RentalCoverRental vehicle protection distributed through digital booking platforms
LaunchA focused first product built around a clear travel use case
Founder LedEarly development preceded the company’s later institutional funding rounds
Travel And MobilityRental car bookings across multiple countries
Travel PlatformsOnline travel agencies and rental car booking businesses
Integrated ProtectionInsurance offered inside the booking flow rather than through a separate purchase
The first product mattered because it gave Cover Genius a practical route into a difficult market. The company learned the operating work before expanding the platform.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 15, 2026 | NCFA Market Activity | SME Finance And Business Banking, Embedded Finance, Payments And Money Movement, Competition And Market Structure
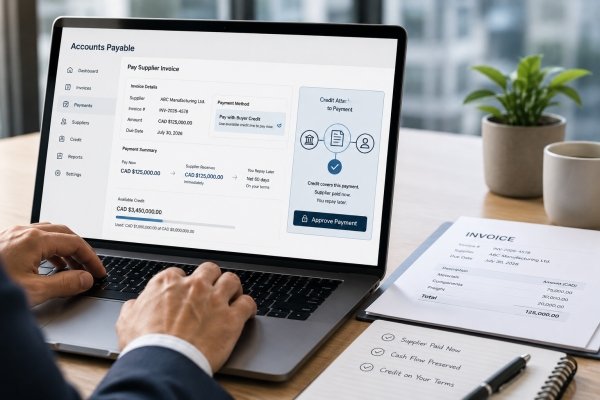
On July 15, 2026, Nasdaq Stockholm listed KEO Capital launched Workeo Canada, bringing a supplier payment and B2B working capital service to the Canadian market. Workeo lets businesses pay suppliers when an invoice is approved while extending their own payment terms to preserve cash flow. The service went live at the end of June with a Toronto team and a revolving senior loan facility of up to C$50 million from an undisclosed Big Six Canadian bank.
The product places credit inside the supplier payment decision. An approved buyer uses a revolving facility to pay an invoice or operating expense through Workeo. The supplier receives payment, while the buyer repays later under its credit terms.
That is more specific than combining payments and lending on one website. Workeo finances the buyer’s payable at the point of payment. The business doesn’t need to draw from a separate bank line, place the payment through another provider and reconcile both transactions afterward.
KEO is entering Canada with funding already attached to the operating model. That gives the company capacity to originate credit from launch rather than waiting to fund Canadian receivables from equity or offshore lending facilities.
Workeo connects buyers and suppliers through one account. Once approved, a business can use its revolving credit line to pay supplier invoices and operating expenses, extend its own payment terms and preserve cash for other needs.
The structure differs from invoice factoring. A factor generally advances money to a supplier against an outstanding receivable. Workeo primarily finances the buyer that owes the invoice. The supplier still receives payment sooner, but the credit relationship is with the purchaser.
It also differs from a standard line of credit. A conventional bank facility gives the company access to capital, but the borrower must manage the draw, supplier payment and repayment as separate steps. Workeo connects the financing to the underlying payment instruction.
The model is also different than corporate cards. Cards can extend payment time and simplify expenses, but they aren’t accepted for every supplier invoice and often require the balance to be repaid over a much shorter period. KEO hasn’t disclosed Canadian credit limits, repayment terms, pricing or underwriting requirements, so the practical advantage will depend on how those terms compare.
KEO says Workeo uses proprietary technology and blockchain infrastructure to support local payment execution. It hasn’t published enough technical information to establish which blockchain is used, how transactions settle or whether customers interact with that infrastructure directly. The payment and credit workflow is therefore more important to the Canadian launch than the blockchain claim.
The company targets midmarket and large corporate buyers in manufacturing, construction, logistics, wholesale distribution, professional services, retail and health care. It says services are available in Ontario, British Columbia, Alberta, Manitoba and Atlantic Canada, subject to provincial requirements. Quebec and Saskatchewan aren’t included at launch.
Canada offers substantial payment volume for a provider that can attach credit to commercial transactions. KEO cites more than C$9 trillion in annual domestic commercial payment value using Payments Canada data. That figure covers the value processed through several ACSS payment categories. It isn’t KEO’s addressable lending market, but it shows the scale of payment activity surrounding Canadian businesses.
The bank facility explains why KEO can launch the credit product and payment workflow together. Its Canadian subsidiary can borrow up to 80% against eligible receivables during an initial one year revolving period, with an automatic one year extension. The facility is priced at the Canadian Overnight Repo Rate Average plus about 300 basis points, or roughly 6.5% when KEO disclosed the agreement.
KEO estimates that the facility could support approximately C$375 million in annual billings. That's not booked volume or expected revenue. Actual performance will depend on customer demand, credit limits, portfolio turnover, defaults and the amount KEO draws.
The parent company guarantees KEO Canada’s obligations and must maintain at least US$60 million in tangible net worth. Those conditions show that the Canadian bank isn’t funding the portfolio without recourse to the listed company. They also make credit performance central to the economics. Losses, slower repayments or ineligible receivables could reduce the amount KEO can recycle through the facility.
KEO brings prior operating evidence. Workeo was developed by KEO World after its 2020 founding. A four year secured facility of up to US$500 million from Hayfin helped finance nearly US$1 billion in company reported credit volume, mainly in Mexico, before KEO repaid the facility in January 2026.
The company’s corporate structure also changed before the launch. Maha Capital completed its acquisition of KEO World in April 2026 and raised US$27 million through directed share issues. It then adopted the KEO Capital name and KEOC ticker in June. The transaction placed KEO World inside a Nasdaq Stockholm listed company with access to public capital and a larger balance sheet.
Canada is therefore part of a connected expansion sequence. Workeo proved credit volume in Latin America, repaid its original institutional facility, joined a listed company and secured a domestic bank line for its next market.
KEO enters an active Canadian market. It isn’t the first company to connect business spending, payments and credit.
Float’s working capital expansion combines business accounts, cards, bill payments and short term credit. Its product begins with company spending and cash management. Workeo begins with the supplier invoice and attaches revolving buyer finance to that payment.
Telpay’s acquisition of Notch connected supplier payments with receivables and cash flow software. Plooto also integrates accounts payable, accounts receivable and reconciliation. Neither publicly presents a revolving buyer credit facility attached to each supplier payment in the same way.
FundThrough’s invoice funding model addresses the opposite side of the transaction by advancing cash against supplier receivables. Banks provide lines of credit and treasury products, but often leave the business to connect financing with accounts payable operations.
KEO’s competitive position combines payment execution with credit for the buyer, funded through an institutional facility rather than customer deposits.
The commercial benefit is the SME operating relationship. Embedded working capital becomes more valuable when credit appears inside invoices, supplier payments and other operating workflows. A provider that finances the invoice can see when businesses pay, which suppliers they use and how quickly obligations are repaid. That data can improve underwriting, increase product use and make the payment account harder to replace.
Execution still needs proof. The C$50 million facility gives Workeo capacity. It doesn’t establish adoption. The next proof will come from originations, repeat use, credit performance and whether Canadian companies treat Workeo as a financing product or part of their daily payment operations.
Will Canadian businesses increasingly access working capital through the supplier payment workflow rather than managing credit and payments as separate services?
KEO entered Canada with domestic bank funding, Toronto operations and Workeo’s buyer financed supplier payment model. The launch tests the model under a different banking and regulatory structure.
Workeo CanadaOntario incorporated subsidiary · FINTRAC registered money services business
ExpansionToronto operations and five initial Canadian regions
Up To C$50MCanadian revolving senior facilityUp to 80% advance rate · CORRA plus about 300 basis points
5 RegionsOntario, British Columbia, Alberta, Manitoba and Atlantic Canada
Midmarket+Canadian corporate and enterprise buyers
Embedded Buyer FinanceCredit enters at the supplier payment instruction
Canada tests whether KEO can transfer an institutionally funded payment and credit workflow into another regulated market. The facility supplies capacity, but customer adoption, credit performance and repeat use will determine whether Workeo becomes part of daily business payments.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 14, 2026 | NCFA Market Activity | Wealth, Investing And Trading, Financial Inclusion, Embedded Finance
On July 14, 2026, Toronto based Islamic fintech Manzil launched self directed halal stock trading across the United States, United Kingdom, United Arab Emirates, Saudi Arabia, Qatar, and Bahrain. The service combines fractional shares, live Sharia screening, Zakat and purification calculators, and accounts that don’t pay interest on uninvested cash.
Investors can start with US$100. Manzil charges US$48 a year plus 0.4% of invested assets, although it waives the annual subscription for accounts holding at least US$100,000.
The launch extends Manzil beyond managed portfolios. Customers now choose individual stocks, while Manzil controls which securities enter the trading universe and monitors whether they remain compliant with its Sharia standards.
That changes the product from a portfolio service into an active investing account. It's also a practical model for international fintech expansion where Manzil owns the customer experience and religious compliance, while regulated partners provide the brokerage functions underneath.
Halal investing requires more than excluding companies involved in alcohol, gambling, tobacco, weapons, or other prohibited activities. A company’s debt, interest income, and other financial ratios can also affect whether its shares meet Sharia requirements.
Manzil screens its available stocks against standards set by the Accounting and Auditing Organization for Islamic Financial Institutions. Customers can’t buy a stock that falls outside the approved universe. If its status changes after purchase, Manzil notifies the investor.
The product removes several steps from the customer’s normal process into a single account. An investor no longer needs to research compliance in one service, trade through another, and calculate Zakat or income purification separately. The customer still controls each investment decision, but the software restricts the available securities and supplies the religious compliance information needed to manage the portfolio.
That's strategically differnt than say a halal exchange traded fund. Wealthsimple’s halal ETF gives Canadian investors access to a screened portfolio, but investors don't get to choose the individual companies held inside it. Manzil Trading offers direct stock selection within an approved universe.
The fee also places pressure on the product to prove its value. Many general brokerages charge little or nothing for basic stock execution. Manzil customers pay for continuous screening, religious calculations, restricted stock access, and specialized support.
That package will appeal only if it saves enough time, reduces uncertainty, and offers a wide enough selection of approved stocks. The overall compliance experience is therefore part of the product, not a marketing feature added after the trade.
Manzil isn’t building every regulated function required to operate the account. Investment advisory services are offered through Manzil Investment Advisors, a U.S. registered investment adviser. Securities are offered through Alpaca Securities, a U.S. broker dealer and self clearing brokerage provider.
The companies started working together in 2025 when Manzil launched managed investment portfolios for American Muslims. The new trading service extends that relationship from managed portfolios into customer directed stock execution.
Alpaca provides the brokerage connections, account system, custody, clearing, and fractional share access. Manzil can focus on Sharia governance, product design, education, customer acquisition, and support.
This division of work and strategic partnership lowers the cost of launching an investment product. Becoming a broker, building clearing operations, and connecting directly to markets would require far more capital, specialist staff, and regulatory approvals.
Customer access still depends on the registrations, exemptions, onboarding rules, and brokerage permissions that apply in each jurisdiction. Manzil says it is gradually expanding towards more than 100 countries, but the service is currently available in six.
The current rollout shows how a vertical fintech can enter several approved markets without recreating the entire brokerage system in each one. Alpaca handles the common transaction functions. Manzil retains control of the customer requirement that distinguishes the product.
Manzil isn’t competing only with other halal investing companies. It is also competing with the customer habit of combining a mainstream brokerage with a separate screening application, or avoiding direct stock investing altogether.
An integrated account can win when the customer requirement affects every transaction. Compliance isn’t occasional for a Muslim investor who follows Sharia rules. It determines which stocks can be bought, how holdings are monitored, and whether part of a return needs to be purified.
That gives Manzil room to build a deeper financial relationship. The company already offers managed investing, funds, home financing, savings products, and Islamic wills across its Canadian and U.S. businesses. Its halal home financing book passed $100 million in 2025, showing that its customer proposition extends beyond investing.
The growth model is commercially attractive because the same trust can support several products. A customer who uses Manzil for home financing may also use it for investing, savings, estate planning, or money management. Each product can lower the cost of acquiring the next relationship.
Its pricing strategy is being tested as it scales. At US$48 a year plus 0.4% of assets, Manzil needs customers to value the integrated experience more than a general brokerage paired with a separate halal screening tool.
For founders, the useful insight isn’t simply to target a niche. The customer requirement must change the workflow in a way that mainstream providers don’t serve well. Manzil’s religious rules affect product selection, account design, data, calculations, and customer support. That creates a stronger commercial position than branding a standard brokerage for a defined community.
Manzil is Canadian, but Canada isn’t among the first markets for its new trading service. The international product relies on U.S. advisory and brokerage entities, while Canadian investment dealers operate under a separate registration, custody, clearing, and self regulatory framework.
Manzil hasn’t said whether regulation, partner availability, economics, or product sequencing explains Canada’s absence. The launch does show that a Canadian fintech can validate a customer need at home, then use regulated foreign partners to distribute a different product across approved markets.
The customer need remains significant at home. Mohammed Sawwaf previously told an industry discussion that the lack of halal financial products excludes many Muslim Canadians from services other consumers take for granted.
Financial inclusion isn’t only about whether someone can open an account. The account must also meet the legal, cultural, or religious requirements that allow the customer to use it.
Manzil is building around that gap. Its international trading launch will show whether a specialized Canadian fintech can retain control of customer trust and product rules while licensed partners carry the regulated transaction work.
Can a vertical fintech build an international investment business by owning the customer rules and experience while regulated partners supply the brokerage system underneath?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 4, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization, Cybersecurity Fraud And Financial Crime, SME Finance And Business Banking, Capital Markets And Market Infrastructure, Policy Regulation And Governance, Risk Compliance And Regtech, Data Privacy And Governance

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026).
AI training data now carries an auditable collection burden across source choice, legal basis, sensitive data and model output controls. Canadian fintechs using European personal data should map what is scraped, why it is needed, who controls the processing and how records can be filtered or removed before consultation language becomes supervisory practice.
Fund innovation depends on regulatory speed as well as product design. Asset managers, exchanges, fintechs, wealth platforms and regulators should watch how dedicated approval pathways and product specific guardrails influence the pace of retail investment innovation without reducing investor protection.
Swift is testing whether tokenized deposits can extend today's banking infrastructure into always available cross border payments without replacing existing settlement systems. The pilot results will provide an early benchmark for bank led tokenized payment networks.
Always on market design is moving beyond crypto. Exchanges, brokers, clearing firms, liquidity providers, risk teams and regulators should watch how 24/7 trading changes oversight, operations, margin, surveillance and market resilience.
Credit infrastructure is consolidating around data depth, identity coverage and alternative underwriting. Lenders, fintechs, credit bureaus, SME finance platforms and regulators should watch how alternative data, fraud controls and AI assisted decisioning affect credit access for thin file borrowers and small businesses.
Hong Kong is replacing a widely used authentication method across online securities and regulated virtual asset trading. Brokers and platforms also need stronger monitoring, client notifications and incident response procedures, while senior management may be held accountable for losses caused by inadequate controls.
The findings connect payment design directly to fraud exposure, customer friction and trust. Lower fraud by transaction count is encouraging, but higher losses by value and rising first-quarter fraud show why scale requires stronger authentication, transaction risk data and coordinated controls. These operating results add important context to the UK’s payment milestone and Canada’s trust framework.
Financial institutions and technology providers will gain a structured environment for testing AI security tools against European requirements. Firms serving the European market should prepare to demonstrate model safety, operational resilience and secure deployment before advanced systems enter critical financial operations.
AI cyber risk is now a financial stability issue. Banks, fintechs, payment firms, infrastructure operators, software vendors and supervisors should watch how AI vulnerability discovery, third party concentration, open source dependencies and cyber resilience planning become part of financial sector oversight.
Circle's trust charter places a major stablecoin issuer inside the U.S. federal banking framework. The pace of implementation, custody adoption and any future expansion into reserve management will show whether trust banks become the preferred operating model for regulated stablecoin infrastructure.
The paired licences let one regulated provider connect crypto conversion, asset transfers, conventional payments and payment accounts. Firms pursuing similar models across Europe will need to determine when MiCA authorization must be combined with payment permissions as their products cross from digital assets into fiat payment execution.
Crypto platforms are moving toward regulated multi-asset investment access. Exchanges, brokers, dealers, crypto platforms, regulators and investors should watch how derivatives, equities and crypto converge inside licensed investment platforms.
MiCA is becoming a market access gate for global digital asset firms. Banks, payment companies, custodians, stablecoin issuers, exchanges and compliance teams should watch how full EU authorizations shape cross-border crypto services, institutional distribution and regulated stablecoin infrastructure.
Eltropy is turning agentic banking into a platform market rather than a closed vendor product. The commercial question is whether shared controls, integrations and distribution can make specialized financial agents easier for smaller institutions to adopt.
Regulated AI adoption needs control infrastructure, not only models. Banks, insurers, telecoms, fintechs and compliance teams should watch how agent oversight, inference monitoring, shared IP and enterprise control planes become part of Canadian AI governance.
AI in retail finance is becoming a competition, consumer protection and fraud issue at the same time. Banks, fintechs, wealth platforms, insurers, lenders and compliance teams should prepare for AI agents, personalization, delegation, identity controls and new forms of consumer harm.
Large fintechs are testing direct charter strategies again. Lenders, BNPL firms, embedded finance platforms, banks, investors and regulators should watch whether major payment and credit firms choose bank partnerships, owned charters or hybrid models for the next stage of regulated growth.
Regulators are increasing both the reach and speed of financial misconduct enforcement. Firms now face faster detection, coordinated action across jurisdictions and far less time to correct weak promotion, reporting and compliance controls.
This week’s intelligence points to a more mature phase of financial innovation. Stablecoins are entering regulated banking structures, tokenized deposits are nearing live payment use, regulators are setting terms for continuous markets, and AI governance is becoming a practical operating requirement. In Canada, the Real Time Rail rules, PSP access model and planned Q4 launch show how domestic payment modernization is entering the same execution stage. Advantage will favour institutions that can combine trust, regulatory readiness and delivery at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 27, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Risk Compliance And Regtech, Wealth And Asset Management
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026).
Cross border payments are getting clearer operating standards for retail and SME use cases. Banks, payment firms, remittance providers, fintechs and SME platforms should watch how fee disclosure, FX transparency, delivery certainty and last-mile processing become competitive requirements.
The connection gives Singapore users direct access to Vietnam’s domestic QR acceptance network without requiring merchants to install separate terminals. Singapore becomes the fourth ASEAN market and sixth jurisdiction connected to NAPAS, with outbound payments from Vietnam to Singapore planned later in 2026.
Agentic payments are moving into live financial infrastructure. Banks, payment networks, merchants, PSPs, AI providers and fraud teams should watch how consent, authentication, agent identity and liability controls evolve for AI-initiated transactions, including the broader question of whether fintechs should design for people or AI agents.
Agentic commerce needs payment controls that work inside the buying flow. Merchants, payment networks, fintechs, issuers, fraud teams and AI platforms should watch how tokenized credentials, spend limits, approved categories, agent identity and audit trails define the next payment interface. NCFA's Financial Innovation Map tracks agent commerce infrastructure as an emerging opportunity.
Canada’s instant payments system now has the legal foundation needed for launch preparation. Banks, payment service providers, fintechs, merchants and compliance teams should track how RTR rules, access, fraud controls, ISO 20022 messaging and 24/7 operations change payment product design and competition.
Wholesale CBDC work is concentrating on settlement infrastructure rather than retail money. Central banks, banks, market infrastructure firms, custodians and payment providers should watch how tokenised settlement, securities delivery and cross border liquidity use cases shape the next phase of central bank money innovation.
Canada's retail payments regime is shifting from registration into active supervision. PSPs, fintechs, payment processors, compliance teams and investors should track how incident reporting, safeguarding information, annual reports and PSP Connect submissions become part of the operating cost of regulated payment activity.
Canada's open banking framework is entering the implementation phase. Banks, fintechs, payment service providers, credit unions and technology providers should prepare for accreditation, technical integration and operational requirements as consumer driven banking moves toward production. See NCFA's Open Banking in Canada opportunity brief for the market gaps, adoption signals and infrastructure questions this framework is meant to address.
Stablecoin payment firms are building through combined cryptoasset and e-money permissions. Fintechs, banks, treasury teams, payment providers and stablecoin issuers should watch how MiCA, EMI licences, IBAN access and euro stablecoin services define regulated market entry in Europe.
Regulated retail crypto platforms are adding on-chain access while changing how custody, disclosure, risk controls and investor responsibility work. Brokers, crypto platforms, wallets, regulators and compliance teams should watch how self-custody DEX trading inside mainstream apps affects token access, suitability controls, tax reporting and Canadian crypto regulation and investor safeguards.
The case combines a licensing exit with a failed liquidity transaction, withdrawal uncertainty and possible insolvency. Regulators and users can assess the effectiveness of the wind down through access to account records, withdrawal processing, financial disclosure and the treatment of unreturned balances. Canada’s registered crypto platforms operate under different rules. The same questions apply to custody, liquidity, capital, governance and orderly customer exits. NCFA’s comparison of MiCA and UK crypto rules explains how demanding authorization standards can favour firms with stronger operating infrastructure.
MiCA is becoming the operating gateway for institutional digital asset firms. Trading firms, custodians, prime brokers, exchanges, asset managers and compliance teams should watch how authorization under a harmonized EU framework expands regulated cross-border crypto services.
Retail investing is extending into onchain financial infrastructure. Brokers, crypto platforms, wallets, custodians, exchanges, wealth platforms and regulators should watch how tokenized equities, Layer 2 networks, onchain lending and AI directed trading reshape product access, market supervision and investor protection.
Stablecoin regulation is starting to look like payment system supervision. Issuers, banks, custodians, payment firms, exchanges and compliance teams should watch how systemic designation, transition planning and cross-regulator supervision affect market access for regulated digital money.
The UK crypto market is getting a clearer operating perimeter. Crypto platforms, custodians, stablecoin issuers, intermediaries and staking firms should prepare for authorisation, capital planning, market conduct controls and compliance standards that bring crypto closer to mainstream financial regulation.
Stablecoin competition is shifting toward scale, governance and distribution. Banks, payment networks, wallets, merchants, fintechs and stablecoin issuers should watch whether shared economics, partner governance and broad platform participation become a stronger model for digital money adoption.
Tokenized securities need regulated payment and custody rails, not only issuance technology. Asset managers, administrators, custodians, stablecoin providers and tokenization platforms should watch how CASP and payment licences shape the full transaction lifecycle from subscription to redemption and payout.
Institutional stablecoin adoption is becoming part of regulated banking infrastructure. Banks, custodians, asset managers, payment firms and stablecoin issuers should watch how custody, minting, redemption and settlement services expand across institutional digital asset workflows.
Stablecoin payments are starting to connect settlement with spending controls. Merchants, payment networks, wallets, stablecoin issuers, compliance teams and fintechs should watch how programmable rules, item level controls and point of sale integration expand programmable stablecoin payments in commerce.
Agentic finance needs controls at the point of action. Banks, fintechs, payment firms, wealth platforms and compliance teams should watch how agent identity, authority, escalation, audit trails and transaction limits become core requirements for AI systems that can act on behalf of users.
Agentic finance is becoming a supervisory design question. Banks, fintechs, payment systems, trading firms, AI vendors and regulators should watch how consent, liability, agent identity, market controls, cyber resilience and accountability standards develop as autonomous systems enter financial workflows.
Market transparency increasingly depends on shared data infrastructure. Exchanges, trading venues, fixed income dealers, market data providers, asset managers and regulators should watch how consolidated bond market data improves price discovery, execution quality and market oversight.
Tokenised capital markets need legal certainty as much as technology. Issuers, investors, custodians, exchanges, fund managers and regulators should watch how bond issuance, record keeping, settlement and transfer rules adapt as fixed income markets move onto distributed ledger infrastructure.
Crypto regulation is expanding beyond market access into enforcement. Cryptoasset firms, trading venues, brokers, compliance teams and market participants should prepare for enforcement policies that increasingly align digital asset markets with established financial market conduct standards.
Crypto regulation can create financial crime pressure during market transition. CASPs, VASPs, banks, payment firms, exchanges and compliance teams should watch how licensing deadlines, customer migration and supervisory coordination affect AML controls across Europe.
Investment regulation increasingly focuses on communication as well as compliance. Asset managers, wealth platforms, advisers, fintechs and product manufacturers should prepare for disclosure requirements that prioritize clarity, comparability and consumer understanding alongside regulatory obligations.
Event contract regulation is moving from listing debates into market surveillance and data reporting. Prediction markets, exchanges, brokers, compliance teams and regulators should watch how reporting rules shape the boundary between derivatives, event markets, gambling and retail speculation.
The strongest fintech companies don't wait for certainty. They recognize patterns early, build where demand is growing and stay ready when regulation catches up. That's the value of watching the evidence, not just the headlines. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 26, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Risk Compliance And Regtech, Payments And Market Infrastructure, Regulation And Policy, Treasury Liquidity And Cash Management
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026, Jun 6-12, 2026, Jun 13-19, 2026).
Credit unions now have a clearer way to test stablecoins, tokenized deposits and digital asset accounts inside member owned financial institutions. Banks, core providers, payments firms, fintechs and regulators should watch whether these early programmes become production deployments for real time settlement, deposit tokens and broader member access to digital assets.
Stablecoin issuer regulation is becoming an AML and identity control issue, not only a reserve or redemption issue. Issuers, banks, custodians, wallets, exchanges and compliance teams should prepare for customer identification, verification, recordkeeping and risk controls as payment stablecoin frameworks mature.
Stablecoin regulation is moving from policy design into operating rules for payment infrastructure. Issuers, banks, custodians, payment firms, exchanges, and fintechs should watch how reserve design, redemption rights, safeguarding, and systemic supervision shape market access for regulated digital money.
Tokenization platforms are entering public capital markets. Asset managers, broker dealers, transfer agents, custodians, exchanges and investors should watch how public company access, regulated ATS infrastructure and cross border digital securities permissions shape the next phase of tokenized fund and real world asset distribution.
Event contract markets are facing a sharper boundary test. Exchanges, brokers, prediction market platforms, sports leagues, tribal gaming authorities and regulators should watch whether Congress narrows the line between federally regulated event contracts and state regulated gambling.
Private market trading infrastructure needs audit rules that firms can apply before transactions scale. Companies, auditors, advisers, venues and investors should watch how PISCES treatment affects independence checks, audit committee planning, transaction readiness and the operating model for periodic private share trading.
Canadian issuer disclosure is becoming more digital by default. Public companies, transfer agents, investor relations teams, legal advisers and compliance staff need to adjust delivery controls, SEDAR+ workflows, investor notices and request handling before the new access model takes effect.
Canadian equity market structure remains tied to US implementation timelines. Trading venues, brokers, market makers, and technology teams need more time to adjust routing logic, fee models, tick increments, compliance controls, and systems that support trading in interlisted securities.
Tokenization is moving closer to regulated market infrastructure. Exchanges, brokers, clearing firms, custodians, digital asset platforms, and regulators should watch how traditional market operators and crypto venues build permissioned pathways for tokenized securities, futures access, custody, execution, and compliance. Similar infrastructure questions are also emerging in event contract markets as new regulated venues, distribution channels, and contract frameworks develop.
Bank AI adoption is moving from pilots to operating metrics. Financial institutions, fintech vendors, compliance teams, investors, and regulators should watch how large banks measure AI value, scale employee access, govern automation agents, and connect AI deployment to fraud control, onboarding, productivity, risk operations, and compute infrastructure markets.
Cross border payments are becoming a regulated corridor strategy. Exporters, payment firms, banks, compliance teams and fintechs should watch how RPAA registration, money services business obligations, local payout capability and bank account connectivity affect competition in Canada India payment flows.
Digital euro policy is becoming payment infrastructure design. The next test is how offline use, privacy controls, holding limits, fees, PSP distribution, and cash protection fit into a system that has to work across public money, private payment providers, and existing rails.
Mortgage distribution is becoming a stronger fraud, licensing, and consumer protection issue. Brokers, lenders, fintech mortgage platforms, compliance teams, and investors should watch how higher penalties, clearer licensing rules, and stronger supervision reshape risk controls in mortgage services.
Financial crime detection no longer depends only on what individual institutions can see. Banks, credit unions, payment service providers, securities dealers, fintechs and other reporting entities can now strengthen risk detection by sharing designated information, creating new opportunities for collaborative fraud controls, network analysis and anti money laundering investigations.
Regulatory enforcement is becoming more incentive driven. Banks, insurers, investment firms, credit unions and compliance teams should review how early investigation strategy, breach assessment, remediation evidence and senior accountability affect enforcement outcomes.
Audit reporting is becoming more focused on useful disclosure, controls evidence and investor readability. Companies, audit committees, auditors, governance advisers and compliance teams should prepare for updated report content, Provision 29 controls statements and revised audit workflows before the December effective date.
Firms need to know where encryption is used, which vendors are exposed, which systems protect high value data, and how long migration will take. Crypto inventory, procurement language, vendor assurance, and roadmap planning should start before compliance dates become delivery pressure.
A regulated operating company is using a tokenized money market fund for its own liquidity rather than presenting it as a future client product. That moves tokenization into daily treasury operations, where continuous access, settlement speed, custody controls and balance-sheet utility can be tested against conventional cash-management infrastructure.
Approval processes are becoming more transparent and predictable for eligible applicants entering or expanding within Canada's federally regulated financial sector. Banks, fintechs, federal credit union applicants and regulated financial institutions should watch how the framework affects application timelines, market entry, organizational changes and future supervisory expectations. For background, see NCFA's earlier coverage of the Streamlined Approvals Framework proposal.
Manitoba has put AI governance and cybersecurity inside the same statutory control structure for the public sector. The next test is implementation. Regulations will determine how far the province goes on human oversight, technical standards, incident reporting and vendor procurement, and whether those requirements become a practical benchmark for other Canadian governments.
Every week brings hundreds of announcements. Only a small number signal meaningful change. This week's developments point to new opportunities across payments, digital assets, AI, capital markets and regulation that could influence where innovation accelerates, investment flows and new business models emerge next.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
