





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


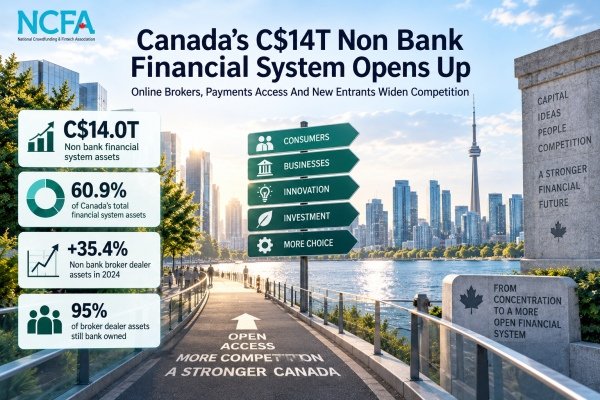
On September 3, 2026, Bank of Canada staff released new non bank finance data showing that Canada’s non bank financial sector held C$14.0 trillion in assets at the end of 2024, equal to 60.9% of the financial system. The Bank's broad definition includes pension funds, insurers, investment funds, financial auxiliaries and other intermediaries. Much of the 2024 increase also came from stronger market valuations.
The headline number is only part of the story. Faster growth is appearing in narrower bank like activities, online brokerage and specialty finance, while commercial banks still retain enormous asset and distribution advantages.
Canada already had a huge financial system outside deposit taking banks. What's changing is how customers reach it, where credit can originate and how many firms can compete for data, payments, investing and banking services.
Canada already had a vast financial system outside banks before fintech took off. Pension funds, insurers and investment funds have held enormous pools of financial assets for decades. The Bank says non bank assets have grown at an average annual rate of 6.9% since 2010.
The C$14 trillion also grew faster in 2024 because markets rose. Other investment funds increased 18.8%, pension assets rose 9.6% and insurance assets rose 9.8%. The Bank attributes much of that growth to stronger valuations.
Fintech arrived inside a financial system that was already enormous. Since then, investing has become easier to distribute online, more credit products have appeared outside traditional bank lending, payment firms have gained access to national infrastructure and financial data is being opened to approved competitors. Customers now have more ways to reach financial products without starting at a bank branch.
Online brokerage is one of the clearest changes in the Bank's data. Non bank broker dealer assets grew 35.4% in 2024, and the Bank says online brokers drove the increase.
Digital investing can win customers quickly because opening an account, moving cash and buying securities no longer requires the same physical distribution network.
The incumbents are nowhere close to disappearing. Non bank firms account for only about 5% of Canada's broker dealer assets. Bank owned broker dealers hold the other 95% of those assets.
The contrast is striking. Challenger activity is changing customer behaviour much faster than it is changing institutional asset share.
A Canadian can now invest through a digital broker, buy an ETF, hold cash inside an investing app and compare financial products without spending much time inside a traditional branch. The banks still own enormous distribution and balance sheet capacity. They no longer own every customer entry point.
Specialty finance has grown quietly beside the banks. Finance companies represent 11.8% of the narrow non bank measure and grew 7.1% in 2024. Statistics Canada includes consumer lending, corporate lending, leasing, mortgage investment corporations and mortgage finance corporations in its non bank credit work.
The official statistics have also expanded over time to capture newer models such as buy now pay later financing.
A mortgage can start outside a bank and still end up inside one. Mortgage finance corporations can originate loans through brokers and then sell them to regulated financial institutions. A borrower may meet a non bank lender first while a bank later funds or owns the mortgage.
Competition and cooperation can exist in the same transaction.
Canadian finance is becoming more distributed without becoming neatly divided into banks on one side and challengers on the other. Origination, funding, servicing, securitization and ownership can happen at different institutions. That makes the system more competitive in places and more interconnected at the same time.
Private credit shows the same Canadian pattern. Non bank loans have supplied about 15% of external funding for Canadian non financial businesses for roughly a decade. Private credit has not rapidly replaced domestic bank lending.
Canadian institutions are still heavily involved. The Bank estimates that private lending by Canadian investors plus Canadian bank lending to private credit funds totalled about C$500 billion around the beginning of 2026, with most of the activity in the United States.
Canadian pensions, insurers and banks know the asset class well. Much of the capital is simply being deployed elsewhere.
That divide is already visible in Canada's C$500 billion private credit exposure. Canadian institutions have substantial capacity to invest in private lending, while Canadian businesses still depend much more heavily on banks and public debt markets.
Payments access is opening to firms that historically could not participate directly. Payments Canada says registered payment service providers can now apply for membership and Real Time Rail participation. Wise, KOHO, Float, Paramount Commerce and Brim were among the first PSP members admitted in 2026.
The Real Time Rail is scheduled to launch in the fourth quarter of 2026 with instant clearing and settlement and support for direct PSP participation.
Financial data is opening too. Canada's consumer driven banking framework makes competition an explicit objective and creates accreditation routes for regulated financial institutions and registered payment firms.
Approved providers will be able to request customer permissioned financial data instead of relying on screen scraping or proprietary bank connections.
The opening of Canada's payments system now extends into consumer driven banking. A challenger with payment access and customer approved data has more room to build a financial relationship without depending on an incumbent for every connection.
In June, OSFI launched a streamlined approvals framework for targeted new entrants. It covers eligible credit unions and firms with technologically innovative or emerging banking models.
OSFI is aiming for a clearer three phase process and a targeted 12 month review after a complete formal application is accepted.
Foreign banks already have a formal route into Canada. OSFI assesses applications for full service and lending branches and recommends eligible applications to the Minister of Finance.
Entry is still tightly supervised. Capital, liquidity, governance, business plans, home country supervision, security and risk management remain part of the approval process.
A firm that qualifies for federal entry can pursue much more than a better financial app. Regulated banking capacity, payment access and customer approved data can put more of the customer relationship inside the challenger itself. The requirements remain demanding, but the route is clearer.
Securities rules are changing at the same time. The Canadian Securities Administrators has expanded the Listed Issuer Financing Exemption, allowed eligible venture issuers to adopt semi annual reporting and introduced other measures intended to reduce financing and disclosure friction.
In July, the CSA said more than 10% of eligible companies had already opted into semi annual reporting and that significant capital had been raised under the expanded exemption.
More financial assets do not automatically create more productivity. A pension portfolio can rise because markets rise. A fund can buy existing securities. Canadian institutions can invest abroad. None of those outcomes guarantees more financing for a Canadian company trying to commercialize technology, buy equipment or scale internationally.
That allocation question runs directly into whether Canada can turn financial access into productive participation.
The C$14 trillion headline makes the productivity problem harder to dismiss. Canada is not short of financial assets. The harder question is whether more of the system can connect viable Canadian businesses with capital on terms that let them invest, grow and compete.
The Bank itself recognizes the upside. Its paper says these non bank firms can foster innovation, increase competition, serve underserved markets and improve financial system efficiency.
The same activities can also carry leverage and transform credit or liquidity in ways that spread stress through funds, dealers and financing markets. More activity outside bank balance sheets can distribute risk while making some connections harder to see.
The Bank's 2026 work on private credit and market based finance reflects that concern without treating every non bank institution as a threat.
As activity spreads across funds, dealers, lenders and platforms, risk travels with it. Credit, liquidity, customer data and operating dependencies become harder to follow when they are shared across more institutions. Regulators have to preserve the benefits of wider competition while keeping those connections visible.
Banks still anchor the system. Their share of total financial system assets barely changed in 2024. They still dominate broker dealer assets, business lending, deposits and many of the funding relationships behind non bank finance.
The starting points are multiplying. Online brokers compete for investors. Specialty lenders compete for borrowers. PSPs can gain direct payment access. Approved providers can compete around financial data. Eligible new entrants can pursue federal regulation through a clearer process.
Canada's banks remain deeply entrenched, but more of the financial activity around them is open to competition. Incumbents keep the scale while challengers gain more ways to reach customers, move money, originate credit, raise capital and, in some cases, become regulated institutions themselves.
Talking Point
Canada already has C$14 trillion of finance outside traditional banks. More firms are now gaining ways to compete for customers, payments, data, credit and regulated entry while the banks remain dominant.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply