





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Fintech Product Launch | June 12, 2025
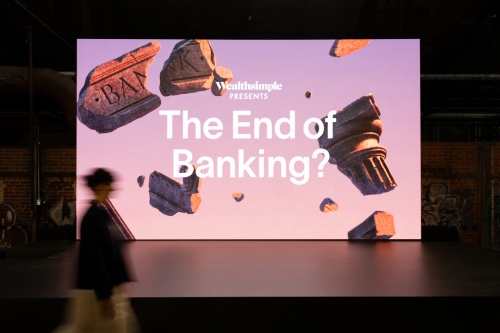
Image: Wealthsimple Presents: The End of Banking (WS Newsroom)
On June 11, 2025, Wealthsimple hosted their first 'Wealthsimple Presents: The End of Banking?" public event in Toronto where they announced the launch of two new financial products that will compete head-on with Canada's largest banks and financial institutions. (1) No fee 2% cashback credit card; and (2) Instant access low rate line of credit starting as low as 4.45%.
These offerings are for anyone who is currently paying banks and credit card companies higher interest rates and fees for the same services, and everything is online and available without having to visit a physical branch. This is healthy competition that will only benefit consumers, and the Canadian government and regulators should take notice.
The company also highlighted a series of upgrades to its hybrid chequing/spending account and teased new cash delivery pilots that could soon offer same day cash drop-offs to users' doorsteps.
Michael Katchen, Co-founder and CEO of Wealthsimple:
“Canadians don’t need another bank. They need something better. We’re removing friction, fees, and outdated experiences.”
The new Wealthsimple credit card is the most requested product in the company’s history. It offers:
Sam Newman-Bremang, Senior Product Director at Wealthsimple:
“This isn’t just another credit card, it’s the one Canadians have been asking for. As the most requested product in our history, it’s clear people want a smarter and more rewarding way to use credit. So that’s what we built: a card that puts humans first, with unlimited cashback, no foreign transaction fees, and no hidden charges.”
Wealthsimple will also roll out a line of credit product by the end of 2025 with rates starting at 4.45%, depending on collateral and client profile. The current Bank of Canada prime rate is 4.95% source, which means Wealthsimple’s offering could undercut many traditional unsecured personal loan products, such as unsecured credit card APRs (20-24%+) or home equity LOC rates (typically 5.5-5.7%).
Unlike typical credit lines, Wealthsimple clients will be able to use their investment or chequing balances at Wealthsimple as collateral, enabling lower risk and faster approval.
Plus, because Wealthsimple is not a federally regulated bank, it partners with 10 Canadian banks to hold deposits and qualify customers for up to $1 million in CDIC protection, which is much more than the standard $100,000 protection one would get by banking at a single institution.
Wealthsimple now offers a type of chequing account that pays 2.75% interest, 1% cashback on debit purchases, no monthly fees, and no ATM or FX fees. Over one million clients or approx 33% of Wealthsimple’s user base has already adopted the spending account.
The company estimates that in 2024, its users saved more than $100 million in fees they would have paid to traditional banks source.
Recent additions include:
Wealthsimple’s growth strategy is grounded in public dissatisfaction with incumbent financial institutions. In a 2025 Angus Reid survey commissioned by Wealthsimple:
Despite this, the Big Six banks still dominate with over 90% of banking assets under management in Canada. But no doubt that Wealthsimple is on a growth pathway that will chip away at the bank's dominant share by competing with seamless design, lower fees, higher yielding accounts and integrated financial tools built for mobile first customers.
Canada's fintech sector continues to face significant barriers to scale, including regulatory delays around open banking and digital ID. Despite that, leading scale-up fintechs like Wealthsimple are demonstrating how digital platforms can expand their value propositions without becoming a formal bank or acquiring a banking license.
Its model has scaled without a banking licence by partnering with regulated banks and embedding services within a single mobile platform. Wealthsimple now has over 3 million clients and manages over $70 billion in assets, up from $18 billion in 2021. If/when opening banking arrives in Canada, platforms that blend investments, borrowing, payments on a single interface will be game-changing for Canada's financial economy.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply